
 Home Remodeling Market | 2026-2036
Home Remodeling Market Size, Share, and Industry Trends Forecast 2026-2036
Home Remodeling Market Outlook
Building information modeling (BIM) software and prefabrication workflows is reshaping how remodeling contractors coordinate trades and reduce on-site waste. The Home Depot leverages its captive supply chain and digital marketplace to dominate pro-customer fulfillment across North America. Lowe's Companies, Inc. competes through localized inventory positioning and contractor loyalty programs in exurban markets. Andersen Corporation specializes in engineered window systems that anchor its premium positioning against commodity alternatives.
Home remodeling encompasses the alteration, restoration, or functional upgrade of existing residential structures through structural modification, system replacement, or finish improvement, typically involving load-bearing assessments, moisture barrier integration, and code-compliant electrical or plumbing rerouting. Its primary purpose is to extend building service life, improve occupant safety, and adapt interior environments to changed household needs. Kitchen and bathroom remodels lead project-type revenue due to concentrated appliance and fixture replacement cycles, while composite materials within material-type segments capture margin pools through moisture resistance and reduced maintenance liability. Real estate investors within end-user segments drive faster project velocity than homeowners, prioritizing cosmetic turnaround over structural depth.
EPA lead-safe certification requirements and OSHA fall-protection standards shape contractor compliance costs and training burdens across the United States. State-level energy codes and the International Energy Conservation Code incrementally tighten envelope performance thresholds, pushing window and insulation specifications upward. Stakeholders must monitor how municipal permit backlogs and inspector capacity constraints affect project timelines and working capital cycles.
Market Dynamics
The home remodeling market is experiencing a fundamental restructuring as building information modeling software and prefabrication workflows compress project timelines and reduce on-site labor dependency. This technological inflection is reshaping contractor economics and competitive positioning across residential renovation segments.
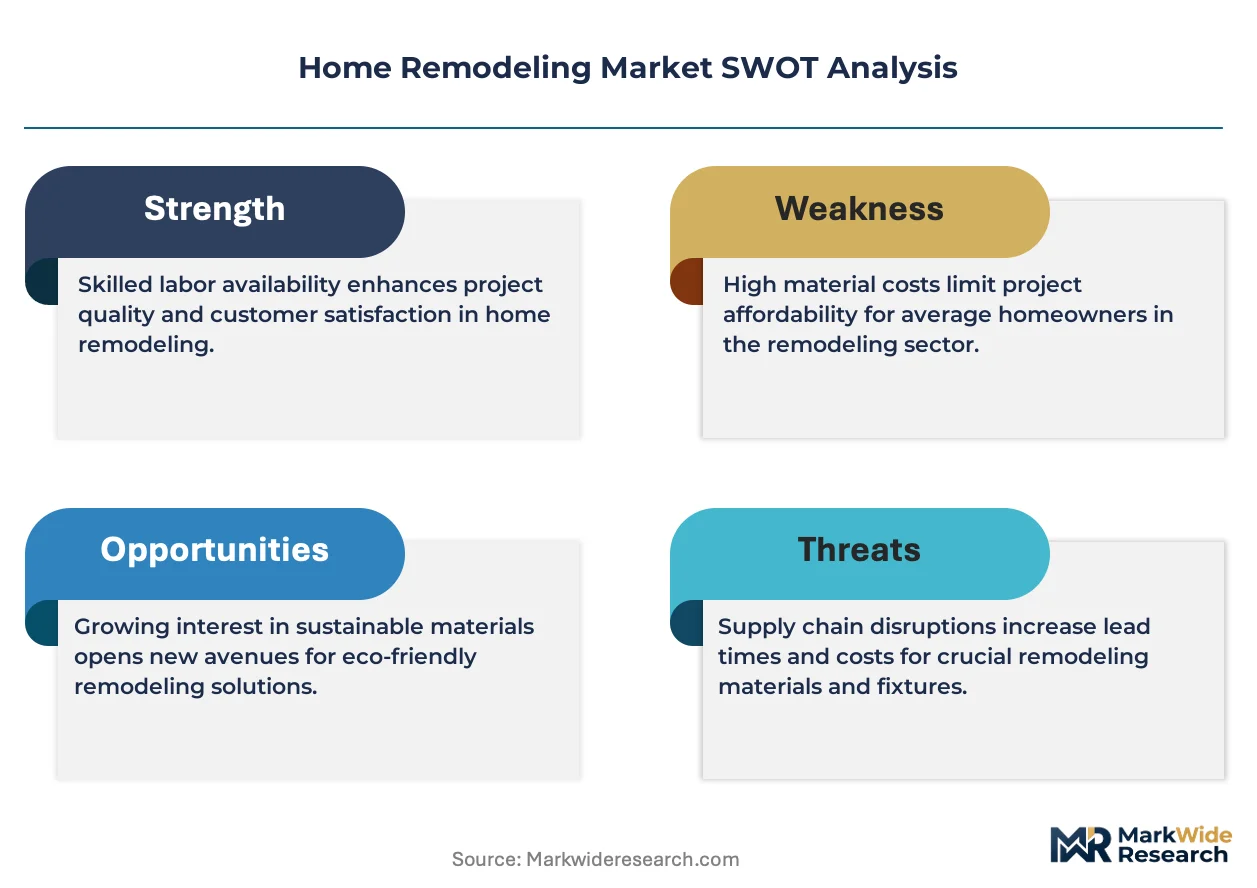
Growth Catalysts
- EPA lead-safe certification mandates:Federal requirements for pre-1978 housing renovations have professionalized contractor training and created recurring compliance revenue streams for certified providers.
- OSHA fall-protection standards:Stricter enforcement of elevated-work safety protocols has accelerated adoption of integrated scaffolding and lift systems that reduce incident liability.
- Sun Belt metro inventory expansion:Climate adaptation needs in Phoenix, Austin, and Tampa are driving concurrent window replacement and HVAC retrofit demand among aging housing stock.
Market Restraints
- Lumber and engineered wood volatility:Input cost swings for structural framing materials compress contractor margins and destabilize fixed-bid project economics.
- Municipal permit backlogs:Inspector capacity constraints in high-growth metros extend working capital cycles and delay revenue recognition for project-based operators.
- Skilled trade labor scarcity:Plumber and electrician pipeline deficits limit project velocity regardless of demand availability.
Strategic Opportunities
- Whole-home electrification retrofits:The Inflation Reduction Act's heat pump and panel upgrade incentives create bundled service opportunities spanning HVAC, electrical, and envelope work.
- Exurban contractor loyalty platforms:Digital procurement tools that consolidate material ordering and financing for dispersed pro customers remain underdeveloped outside major metro cores.
- Moisture-resistant composite materials:Fiber-cement siding and PVC trim boards command premium positioning against traditional wood alternatives in humid climate zones.
Industry Challenges
- EPA RRP certification renewal cycles:Eight-hour refresher requirements every five years create administrative burden and workforce scheduling friction for small contractors.
- Legacy electrical panel integration:Smart home device installation often requires service upgrades that exceed original project scope and customer willingness-to-pay.
- Trade coordination complexity:Multi-specialty projects involving plumbers, electricians, and HVAC technicians suffer from sequencing failures that extend completion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Remodeling Market |
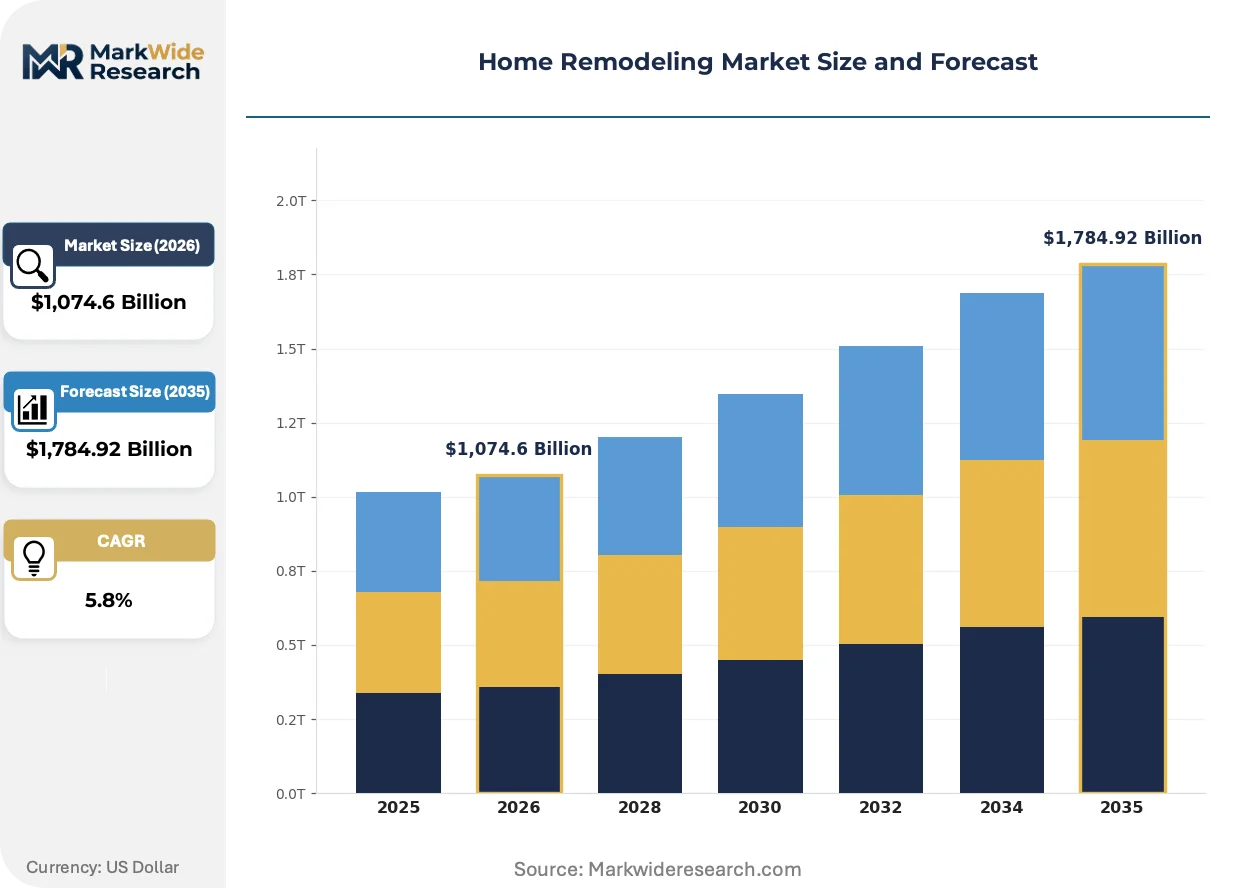
| Market Size in 2026 | $1,074.6 Billion |
| Market Size in 2035 | $1,784.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Kitchen Remodel, Bathroom Remodel, Room Addition, Whole House Remodeling Material Type: Wood, Steel, Composite, Concrete End User: Homeowners, Real Estate Investors, Property Managers, Contractors Service Type: Design Services, Renovation Services, Consulting Services, Project Management |
| Companies Covered | The Home Depot, Lowe's Companies, Inc., Andersen Corporation, ABC Supply Co., Inc., Ferguson Enterprises, Builders FirstSource Inc., BELFOR, Window World, Inc., Menards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Remodeling Market Strategic Shifts
Prefabrication and digital coordination tools are compressing traditional remodeling timelines while elevating quality consistency. Three interconnected developments are restructuring how residential renovation projects are designed, procured, and executed.
Cross-laminated timber and mass timber structural systems are migrating from commercial construction into residential additions and accessory dwelling units. Custom home builders in the Pacific Northwest and Northeast corridors are specifying engineered wood products for their carbon-sequestration credentials and reduced on-site cutting waste. This material transition is compressing framing timelines from weeks to days while requiring new crane logistics and specialized connector hardware.
The International Energy Conservation Code's envelope performance thresholds are tightening window and insulation specifications in state-level adoptions. Contractors in jurisdictions following the 2021 IECC cycle face mandatory blower-door testing and air-sealing verification that add inspection checkpoints. Window replacement projects in Minnesota, Massachusetts, and California now routinely specify triple-pane units that exceed prior code minimums.
Homeowner purchasing for renovation materials has fragmented across showroom, digital marketplace, and direct-to-pro channels. Big-box retailers now compete with specialty distributors for contractor loyalty through dedicated pro desks and volume pricing tiers. This channel diversification is most pronounced in kitchen and bath fixture categories where lead times and customization options vary substantially by sourcing path.
Home Remodeling Market Segmentation
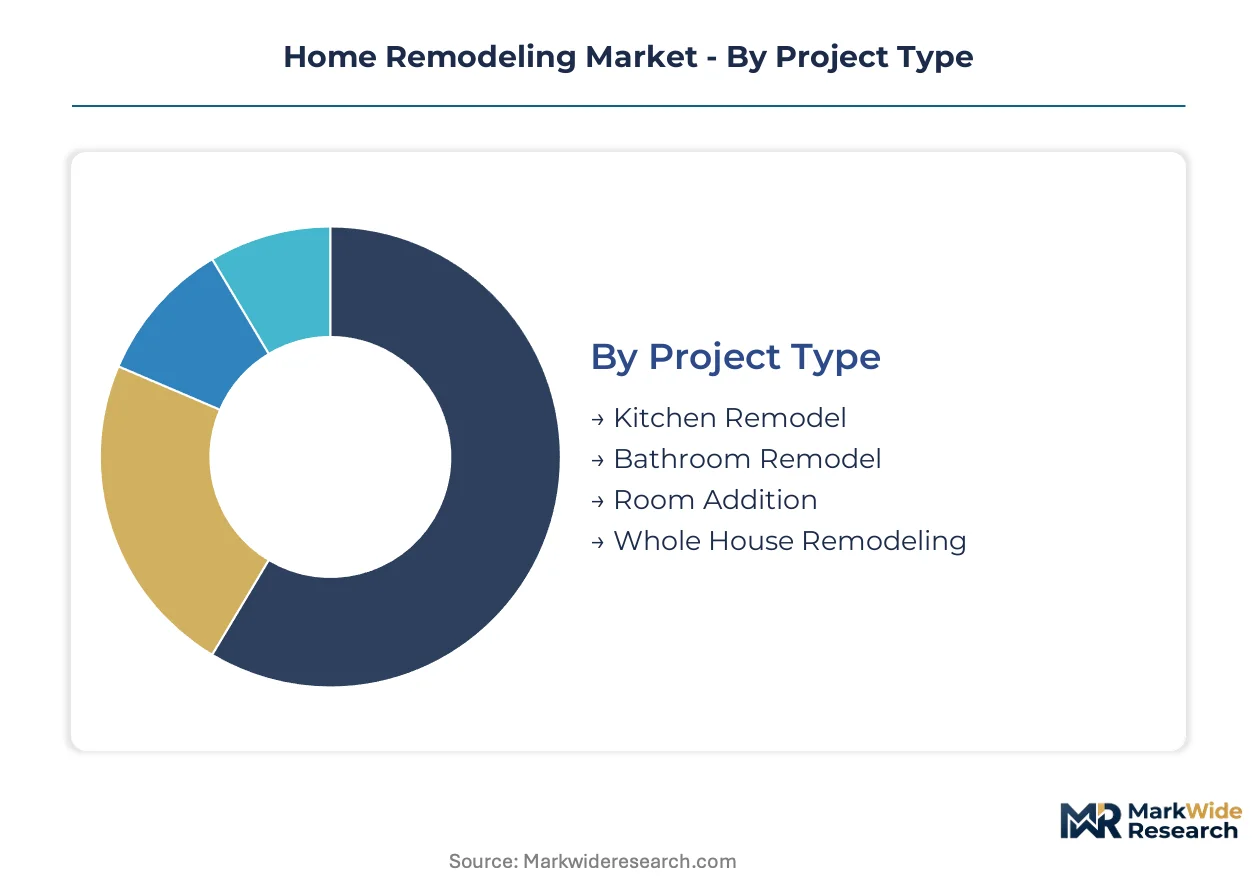
Segmentation reveals how project economics, material specifications, and procurement authority reshape contractor priorities across residential renovation. Distinct customer types and service models create divergent margin profiles that reward specialized positioning.
Project Type:
Cost tier determines fixture density and labor scheduling complexity across renovation scopes.
- Kitchen Remodel:Cabinetry, appliance replacement, and plumbing rerouting concentrate trade coordination demands. Sun Belt metros with aging inventory drive replacement cycles for energy-efficient appliances and moisture-resistant finishes.
- Bathroom Remodel:Tile work, fixture upgrades, and waterproofing dominate material spend. Real estate investors in Phoenix and Tampa prioritize cosmetic turnaround timelines over structural depth for rental property turnover.
- Room Addition:Foundation work and HVAC extension raise permitting burdens. Municipal inspector backlogs in high-growth exurbs extend working capital cycles for project-based operators.
- Whole House Remodeling:Structural assessment and systems integration span multiple trade specialties. EPA lead-safe certification requirements elevate compliance costs for pre-1978 housing stock.
Kitchen remodels hold installed capacity. Whole house remodeling is rotating up the share rankings.
Material Type:
Application environment dictates moisture resistance, thermal performance, and maintenance liability specifications.
- Composite:Fiber-cement siding and PVC trim boards deliver moisture immunity and reduced repaint cycles. Humid climate zones in Florida and coastal Texas show concentrated specification against traditional wood alternatives.
- Wood:Cross-laminated timber and mass timber systems compress framing timelines for residential additions. Pacific Northwest builders specify engineered wood products for carbon-sequestration credentials and crane-assisted assembly.
- Steel:Structural framing for load-bearing modifications and seismic retrofits commands premium positioning. California jurisdictions with stringent seismic codes drive engineered connector hardware demand.
- Concrete:Foundation repair and slab-on-grade work anchor room addition economics. Frost-line depth variations across Minnesota and Massachusetts dictate insulation and drainage specifications.
Composite materials hold installed capacity. Mass timber systems are climbing the fastest in share rankings.
End User:
Customer type shapes project velocity, financing structure, and quality tolerance thresholds.
- Homeowners:Occupant-driven renovations prioritize safety upgrades and lifestyle adaptation. Aging-in-place modifications in suburban communities accelerate bathroom accessibility retrofits and single-floor living conversions.
- Real Estate Investors:Portfolio holders demand compressed timelines for rental readiness and resale velocity. Cosmetic-focused turnaround projects in Austin and Phoenix bypass structural depth to maximize capital rotation.
- Property Managers:Multi-unit maintenance programs standardize fixture specifications across rental portfolios. Volume procurement agreements with big-box retailers reduce per-unit material costs for repetitive unit turns.
- Contractors:Speculative builders and custom home operators integrate remodeling into new construction pipelines. Design-build firms capture margin through bundled architectural and construction services.
Homeowners hold installed capacity. Real estate investors are gaining share fastest in project velocity rankings.
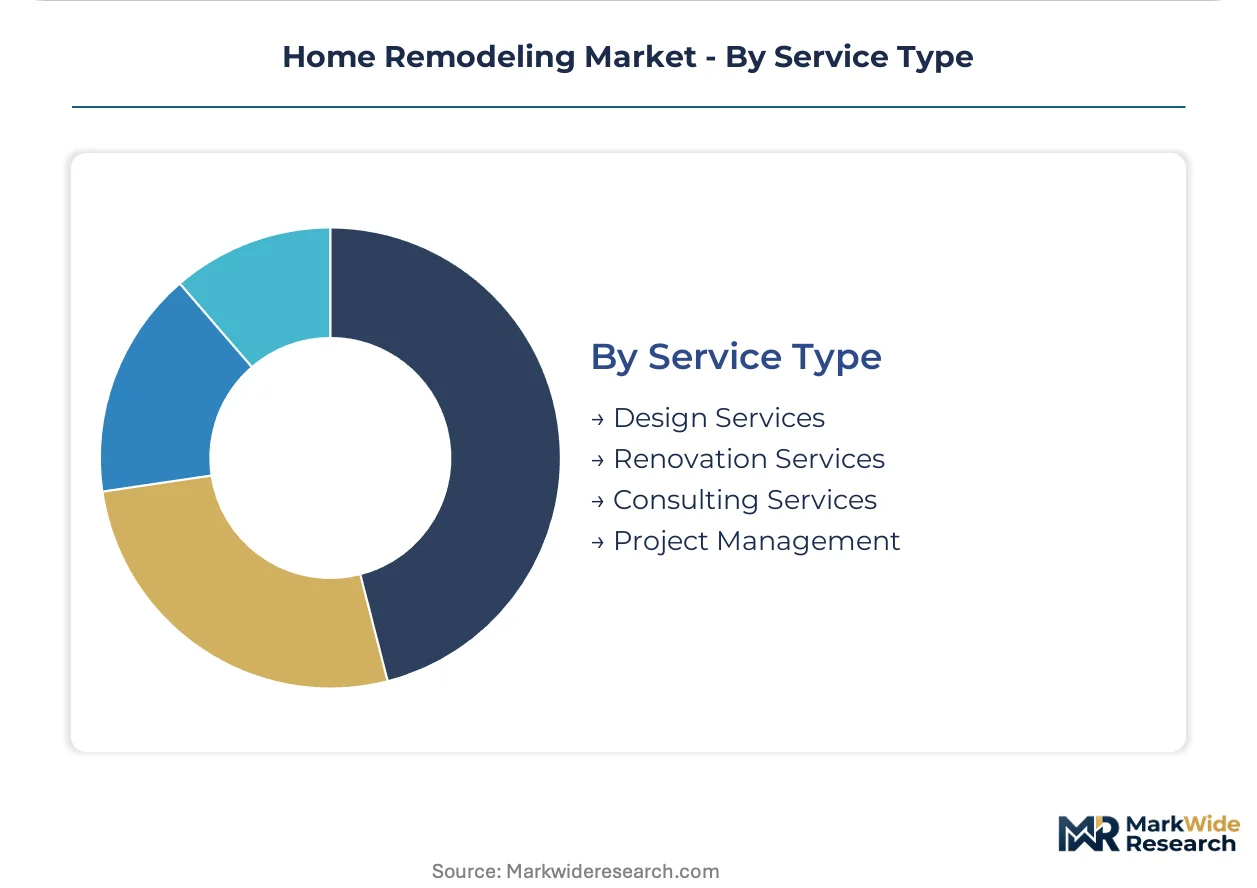
Service Type:
Volume concentration varies by project phase, with front-end design and back-end coordination capturing distinct margin pools.
- Renovation Services:Structural modification, system replacement, and finish installation constitute core revenue. Trade coordination across plumbers, electricians, and HVAC technicians creates sequencing risk that extends completion timelines.
- Design Services:Architectural planning, material specification, and 3D visualization precede construction authorization. Building information modeling software adoption compresses revision cycles and reduces on-site change orders.
- Consulting Services:Code compliance review, energy audit, and permit navigation support owner-driven projects. IECC envelope performance thresholds in Massachusetts and California elevate blower-door testing demand.
- Project Management:Schedule control, subcontractor procurement, and quality inspection coordinate multi-phase work. Digital platforms for material ordering and progress tracking remain underdeveloped outside major metro cores.
Renovation services hold installed capacity. Project management is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Real estate investors and aging homeowners constitute the dominant buyer archetypes, with Sun Belt metros attracting concentrated capital deployment for rental property turnover and suburban communities driving accessibility retrofits for aging-in-place demand.
United States
Sun Belt metros including Phoenix, Austin, and Tampa generate concurrent demand for window replacement and HVAC retrofits as climate adaptation intersects with aging housing stock. EPA lead-safe certification mandates under the Renovation, Repair and Painting Rule professionalize contractor training for pre-1978 housing renovations. The Pacific Northwest corridor from Seattle to Portland anchors mass timber adoption for residential additions and accessory dwelling units.
Germany
Energy-efficient building envelope upgrades dominate renovation activity as homeowners respond to heating cost pressures and building code tightening. The Federal Ministry for Economic Affairs and Climate Action's building energy efficiency funding programs subsidize insulation and window replacements. The Rhine-Ruhr metropolitan region concentrates specialized contractors for historic building renovations and energy retrofits.
Japan
Seismic retrofit demand and aging housing stock replacement drive structural reinforcement projects in metropolitan Tokyo and Osaka. METI's ZEH (Net Zero Energy House) roadmap mandates efficiency standards that accelerate envelope and systems upgrades. The Kanto region surrounding Tokyo anchors prefabricated housing component manufacturing that feeds renovation supply chains.
Australia
Climate-resilient housing modifications concentrate in Queensland and New South Wales as homeowners address flood and fire risk exposure. The Nationwide House Energy Rating Scheme elevates insulation and glazing specifications for renovation permits. Sydney's inner-ring suburbs drive whole-house remodeling demand among owner-occupiers seeking density-adapted living configurations.
Canada
Cold-climate envelope performance requirements in Ontario and Quebec accelerate window and insulation replacement cycles. Natural Resources Canada's Greener Homes Grant program subsidizes energy audits and retrofit measures. The Greater Toronto Area concentrates design-build firms bundling architectural services with construction execution for affluent homeowner segments.
Home Remodeling Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated structure where national retailers capture material flow while regional contractors dominate installation execution. The market fragments vertically between supply-chain aggregators and trade-specialized service providers. Three archetypes dominate: big-box retailers with captive logistics networks, building product manufacturers with direct-to-pro channels, and multi-trade contractors with design-build integration. Competitive moves concentrate on contractor loyalty program expansion and prefabrication capability acquisition.
Within the supply-chain aggregation tier, The Home Depot and Lowe's Companies, Inc. occupy positions as North American material flow coordinators, while Andersen Corporation anchors the engineered systems specialization vector. These three entities exemplify how scale-driven procurement platforms and product-specific technical expertise constitute alternative paths to contractor relationship capture.
| Leading Market Players |
|---|
| The Home Depot |
| Lowe's Companies, Inc. |
| Andersen Corporation |
| ABC Supply Co., Inc. |
| Ferguson Enterprises |
| Builders FirstSource Inc. |
| BELFOR |
| Window World, Inc. |
| Menards |
| Others |
Value Chain & Pricing Dynamics
Canadian softwood lumber concentration in British Columbia and Quebec directly determines margin allocation between structural framing suppliers and downstream renovation contractors across North America. This upstream consolidation forces project-based operators to absorb input volatility or pass through costs via escalation clauses.
Pricing Analysis
Cost-plus contracts with lumber futures indexation dominate large-scale renovation agreements, insulating contractors from spot price swings while compressing fixed-bid margins. Three-tier pricing structure across premium, standard, and economy levels separates Andersen Corporation's engineered window systems from commodity vinyl alternatives. Pricing pressure stems from engineered wood product cost compression as mass timber capacity expands in the Pacific Northwest. Real estate investors exhibit highest price sensitivity, prioritizing cosmetic turnaround speed over material grade, while aging-in-place homeowners accept premium positioning for accessibility modifications.
Supply Chain Analysis
Export-control regimes limiting cross-laminated timber technology transfer constrain supply diversification for residential addition projects. Manufacturing concentrates in Canada, China, and Germany for structural lumber, fastener hardware, and fenestration systems respectively. Raw material dependencies center on western red cedar, oriented strand board, and polyvinyl chloride resin. Single-source vulnerability runs through British Columbia coastal sawmills exposed to wildfire disruption. Distribution runs through big-box retailer pro desks and specialty distributor yards serving contractor loyalty programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home remodeling market fragmentation rewards specialized positioning as whole-home electrification retrofits create service bundling niches. Demand-side shifts toward climate adaptation and aging-in-place accessibility fragment procurement authority across multiple buyer archetypes.
For Market Incumbents: Pre-empt margin erosion in commodity window replacement by acquiring prefabrication capabilities that compress project timelines. Defend contractor relationships through captive financing tools for heat pump and panel upgrade bundles. Vertical integration into moisture-resistant composite manufacturing anchors premium positioning against fiber-cement alternatives. For New Entrants and Emerging Players: Pursue exurban contractor loyalty platforms where digital procurement tools remain underdeveloped outside major metro cores. Target Sun Belt room addition demand where municipal permit backlogs extend working capital cycles for incumbents. Lead with blower-door testing and air-sealing verification services that satisfy IECC envelope performance thresholds. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed multi-trade contractors lacking design-build integration. Five-to-ten year viability hinges on prefabrication workflow adoption and trade coordination software deployment. Acquire design-build firms bundling architectural services with construction execution in affluent suburban markets. Monitor Inflation Reduction Act incentive renewal cycles as inflection indicator for electrification retrofit demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Capability Acquisition | Mass timber ADU manufacturers compress framing timelines from weeks to days using crane logistics. |
| Contractor Loyalty Platform Launch | Digital procurement tools consolidate material ordering for dispersed pro customers in exurban markets. |
| Whole-Home Electrification Bundling | Heat pump and panel upgrade services capture IRA incentives spanning HVAC and electrical work. |
| Moisture-Resistant Composite Expansion | Fiber-cement siding production in humid climate zones commands premium against wood alternatives. |
| Design-Build Integration | Architectural planning bundled with construction execution captures margin pools in affluent homeowner segments. |
Study Parameters
Operator-level perspectives from renovation contractors, building product distributors, municipal permit officials, and HVAC trade specialists anchored the qualitative base. Primary interviews combined with secondary validation from EPA RRP certification databases, IECC adoption tracking, and big-box retailer pro-customer disclosures. Bottom-up project pipeline analysis triangulated against top-down housing stock age demographics.
Scenario-bracketing framed projections across the analysis window using permit issuance velocity, labor pipeline constraints, and material cost index trajectories. Segmentation dimensions modeled include project type, material specification tier, end-user archetype, and regional climate adaptation intensity. CAGRs derived from housing unit replacement cycle analysis and energy code adoption schedules. Forecast inputs incorporated Sun Belt metro inventory expansion patterns and skilled trade labor scarcity indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated building product manufacturers would shift outcomes. Assumptions reflect current EPA certification requirements and state-level energy code adoption trajectories. Material shifts in federal incentive program duration or municipal inspector capacity expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Global DIY Home Improvement Market