
 Bean Bag Chairs Market | 2026-2036
Bean Bag Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Bean Bag Chairs Market Analysis
Subscription-based cover replacement programs is restructuring how bean bag manufacturers monetize repeat engagement. The Lovesac Company leverages its modular Sac system to sustain recurring accessory revenue. Yogibo LLC anchors its brand strength through proprietary bead technology and experiential retail. Fatboy the Original B.V. competes on design heritage and European channel control.
A bean bag chair consists of a fabric or leather outer shell filled with polystyrene beads, shredded foam, or similar compressible material, engineered to conform to body contours through displacement rather than rigid frame support. The primary commercial purpose spans residential lounging, commercial waiting areas, educational collaborative spaces, and gaming environments where ergonomic adaptability outweighs fixed posture requirements. Classic and microfiber product types occupy the volume base, while leather variants concentrate margin pools in premium residential and hospitality channels. The gaming end-user segment represents the fastest-growing structural pocket, driven by dedicated streaming setups and tournament venues requiring extended-duration seating flexibility.
The US Consumer Product Safety Commission governs flammability standards for upholstered furniture fillings, while the EU REACH regulation restricts hazardous substances in textile and foam components. California's Proposition 65 disclosure requirements add a state-level compliance layer for brands distributing across American retail channels. Stakeholders must monitor evolving chemical disclosure mandates and bead recyclability standards as sustainability criteria harden procurement specifications.
Market Dynamics
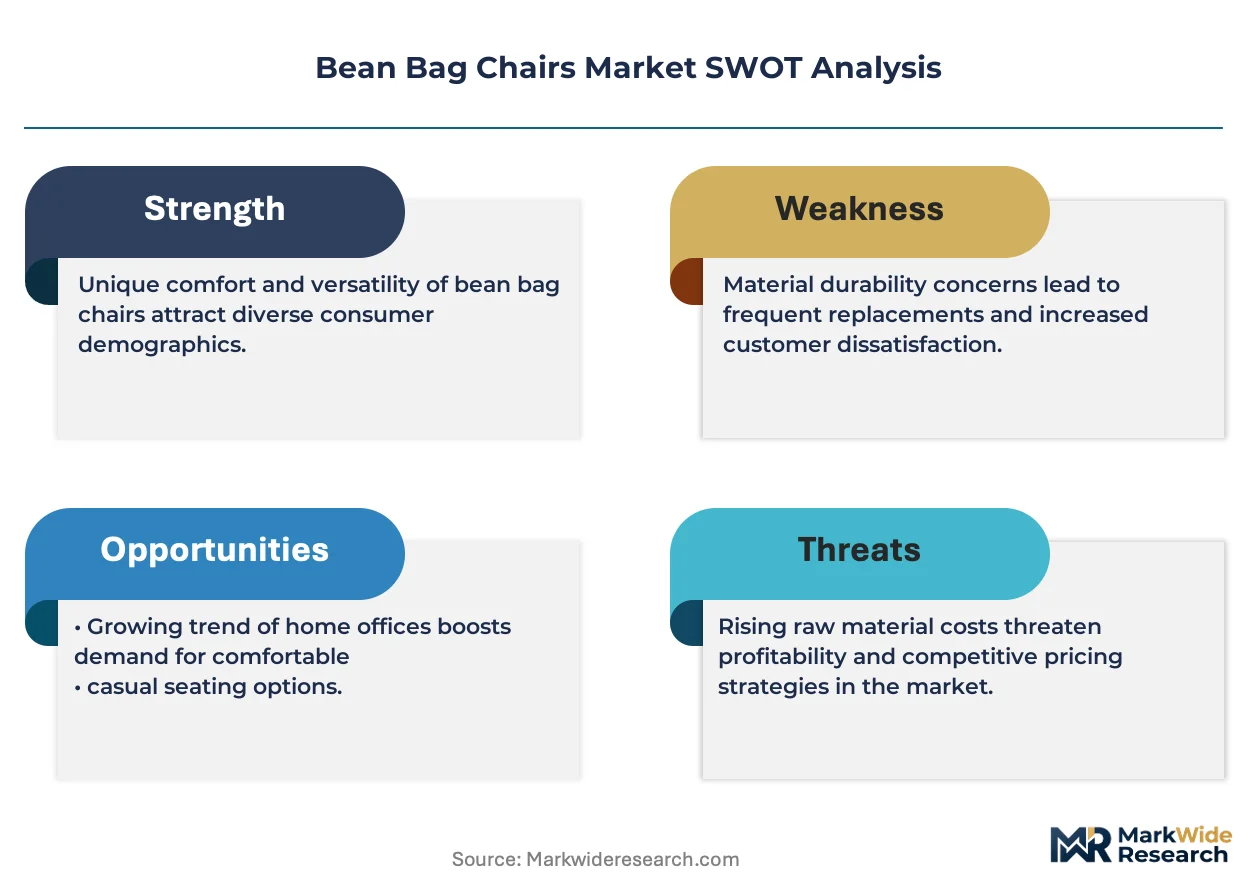
EU REACH chemical disclosure mandates on textile fillings are compressing supplier margins while simultaneously creating compliance-based differentiation for manufacturers with certified foam and bead supply chains.
Growth Catalysts
- Gaming lounge proliferation:Dedicated esports venues and streaming setups require flexible seating configurations that adapt to extended-duration use without fixed posture constraints.
- REACH-certified material sourcing:European manufacturers leveraging compliant foam and fabric suppliers command premium placement in regulated retail channels.
- Direct-to-consumer channel expansion:Specialty brands bypass traditional furniture retail through owned digital storefronts, capturing margin pools previously absorbed by intermediaries.
Market Restraints
- Polystyrene bead volatility:Petrochemical input costs fluctuate with crude oil indices, compressing gross margins for volume producers dependent on virgin bead stock.
- Asian manufacturing concentration:Fabric weaving and foam shredding capacity clusters in coastal Chinese provinces, exposing brands to shipping rate spikes and tariff uncertainty.
- Flammability compliance layering:The US Consumer Product Safety Commission standards overlap with California Proposition 65 disclosure requirements, forcing dual-track testing protocols.
Strategic Opportunities
- Subscription cover replacement:Modular shell systems enable recurring revenue streams through planned obsolescence of outer fabrics rather than full unit replacement.
- Hospitality specification channels:Boutique hotels and co-working lounges represent underpenetrated commercial segments where design-forward seating commands project-based premiums.
- Bead recyclability infrastructure:Emerging take-back programs for expanded polystyrene filling align with EU Green Deal circular economy targets and procurement specifications.
Industry Challenges
- Certification timeline compression:Multiple overlapping chemical safety frameworks require parallel testing tracks, extending product development cycles.
- Skilled upholstery labor scarcity:Domestic sewing and finishing capacity constraints limit rapid scaling for brands reshoring production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bean Bag Chairs Market |
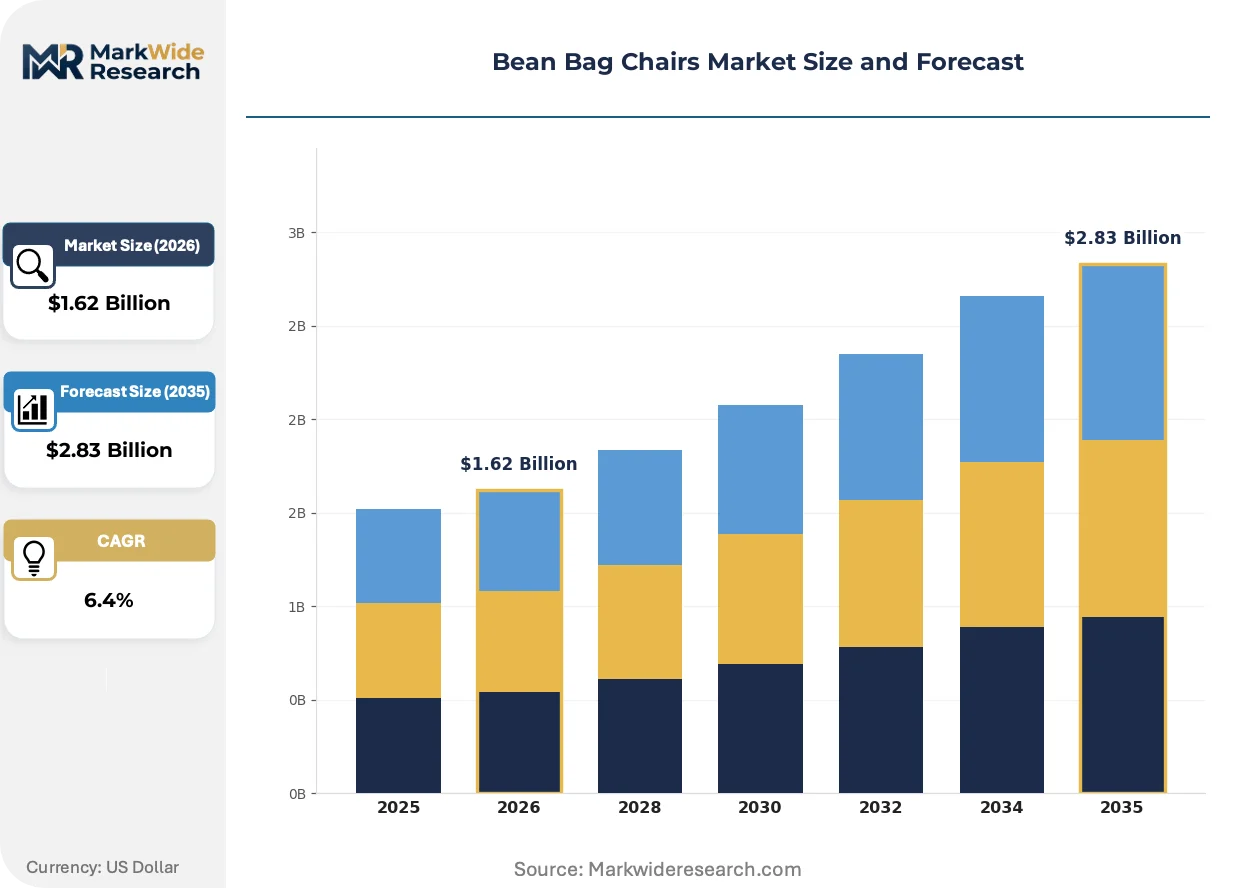
| Market Size in 2026 | $1.62 Billion |
| Market Size in 2035 | $2.83 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Microfiber, Leather, Cotton End User: Residential, Commercial, Educational, Gaming Size: Small, Medium, Large, Extra Large Design: Simple, Cartoon, Modern, Vintage |
| Companies Covered | The Lovesac Company, Yogibo LLC, Fatboy the Original B.V., Sumo Lounge International Corporation, Comfy Sacks Company, CordaRoy Company, Big Joe, Jaxx Bean Bags, Ryohin Keikaku Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bean Bag Chairs Market Emerging Trajectories
Material convergence and regulatory transparency are reshaping competitive positioning, with bead-to-foam hybrids and certified supply chains emerging as primary vectors of differentiation.
Memory-foam hybrid filling technology is unifying the pressure-distribution properties of shredded viscoelastic with the lightweight portability of traditional bead construction. Gaming peripheral manufacturers specify these hybrids for tournament-grade seating where thermal regulation and shape retention matter. The technology is compressing the historical trade-off between comfort density and transportability that segmented the residential and commercial markets.
REACH substance-of-very-high-concern listings are forcing reformulation of flame-retardant additives across polyurethane foam supply chains. Manufacturers serving EU distribution channels must maintain dual inventory streams or absorb transition costs for compliant chemistry. Leather-upholstered premium variants face the steepest compliance burden due to tanning agent disclosure requirements.
Cover replacement programs are displacing full-unit replacement cycles in residential channels. Direct-to-consumer brands bundle fabric shell subscriptions with original purchases, locking in recurring engagement. The United States exhibits the highest attach rates for these programs, driven by urban consumers with limited storage for spare seating units.
Bean Bag Chairs Market Segmentation
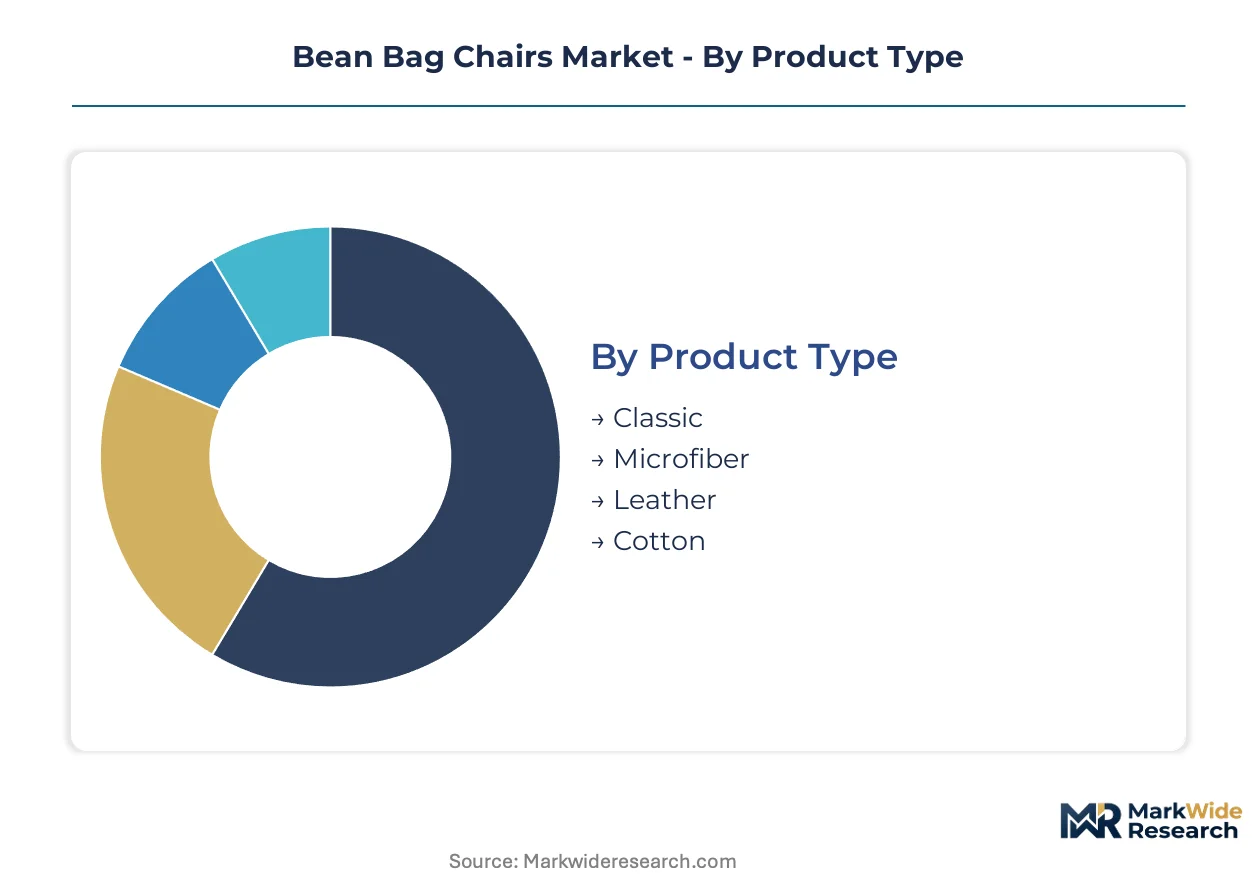
Bean bag chair segmentation tracks how material selection, use environment, and dimensional requirements fragment demand across price tiers and replacement cycles. Manufacturers configure production lines around these axes to balance inventory risk against margin capture.
Product Type:
Customization intensity varies sharply across this category, from commodity fabric shells to specification-grade leather requiring tannery coordination.
- Classic:Standard polyester or cotton twill shells with virgin polystyrene bead filling dominate volume production. Demand concentrates in mass-market retail channels across the United States where price sensitivity overrides material specifications. Margin pressure from petrochemical input volatility constrains branded differentiation.
- Leather:Full-grain or bonded leather upholstery commands hospitality and premium residential specification. EU REACH tanning agent disclosure requirements elevate compliance costs for European distribution, compressing supplier margins while creating certified supply chain differentiation.
- Microfiber:Synthetic suede variants offer stain resistance for family-oriented residential use.
- Cotton:Natural fiber shells appeal to sustainability-focused procurement in educational and co-working segments.
Leading the category by volume: Classic. Expanding most quickly: Leather.
End User:
Application context determines durability specifications, with commercial contracts demanding fire-retardant certifications absent in residential channels.
- Gaming:Tournament venues and streaming setups require extended-duration seating with thermal regulation properties. Memory-foam hybrid fillings displace traditional beads in this segment where shape retention and posture adaptability command premium placement. The US Consumer Product Safety Commission flammability standards overlay with California Proposition 65 disclosure requirements for brands distributing through American retail channels.
- Commercial:Boutique hotels and co-working lounges specify design-forward seating for project-based premiums. REACH-certified material sourcing enables European manufacturers to command placement in regulated procurement channels.
- Residential:Volume base for replacement cover programs and direct-to-consumer distribution.
- Educational:Collaborative learning spaces drive demand for lightweight, reconfigurable seating.
Dominant by revenue scale: Residential. Steepest expansion trajectory: Gaming.
Size:
Dimensional segmentation correlates with shipping economics and storage constraints in urban consumer markets.
- Large:Multi-person configurations anchor family room and lounge installations. Demand concentrates in suburban United States residential markets where floor space availability reduces storage friction. Direct-to-consumer brands bundle these with subscription cover replacement programs to lock recurring engagement.
- Medium:Single-adult seating represents the standard configuration for commercial and educational procurement.
- Small:Child-scale variants serve educational and residential ancillary seating.
- Extra Large:Statement pieces for hospitality specification and gaming lounge centerpieces.
Highest shipment volume: Medium. Gaining share fastest: Large.
Design:
Aesthetic segmentation separates specification-driven commercial procurement from impulse residential purchases.
- Modern:Clean lines and neutral palettes dominate hospitality and co-working channel specifications. European manufacturing clusters leverage design heritage to control premium placement in regulated markets. EU Green Deal circular economy targets drive emerging take-back programs for filling materials in this segment.
- Simple:Unbranded, functional forms occupy mass-market retail and educational procurement.
- Cartoon:Licensed character merchandising targets child-oriented residential demand.
- Vintage:Retro styling appeals to niche residential and specialty retail channels.
Controlling specification channel share: Modern. Growing fastest: Simple.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in coastal Chinese provinces while consumption concentrates in North American and European urban markets. Shipping rate volatility and tariff exposure shape procurement strategies for brands serving Western retail channels. Regulatory divergence between jurisdictions forces parallel compliance investments.
United States
Direct-to-consumer brands and specialty retailers dominate premium segment placement. The US Consumer Product Safety Commission flammability standards overlap with California Proposition 65 disclosure requirements, forcing dual-track testing protocols. Gaming lounges in Los Angeles and esports venues in Seattle command flexible seating configurations for extended-duration use.
Germany
REACH-certified material sourcing enables premium placement in regulated European retail channels. ECHA substance-of-very-high-concern listings force reformulation of flame-retardant additives across polyurethane foam supply chains. Manufacturing clusters in North Rhine-Westphalia maintain dual inventory streams for compliant chemistry transitions.
China
Fabric weaving and foam shredding capacity concentrates in Guangdong and Zhejiang provinces. MIIT industrial standards and dual carbon goals pressure petrochemical-dependent bead suppliers toward efficiency improvements. Shenzhen-based exporters navigate shipping rate spikes and tariff uncertainty affecting Western-bound container volumes.
United Kingdom
Co-working lounges and boutique hotels in London specify design-forward seating for project-based premiums. Post-Brexit regulatory alignment with REACH maintains chemical disclosure mandates for textile fillings. Midlands manufacturing maintains upholstery finishing capacity despite skilled labor scarcity constraints.
Japan
Experiential retail formats in Tokyo and Osaka anchor brand strength through proprietary technology demonstration. METI energy efficiency guidelines and JIS standards shape product specifications for residential channels. Kanto region distribution networks prioritize compact shipping formats suited to urban storage constraints.
Bean Bag Chairs Market Vendor Landscape
Top-tier vendors anchor premium modular systems and experiential retail, while mid-market fabricators compete on cover replacement programs and volume scale. The vendor base stratifies across three tiers: design-forward specialists with certified supply chains, direct-to-consumer brands with subscription revenue models, and private-label manufacturers serving mass retail. Dominant competitive moves include backward integration into foam shredding capacity and geographic expansion through owned digital storefronts.
Within the premium modular tier, The Lovesac Company and Yogibo LLC exemplify divergent strategic archetypes—one leveraging subscription-based cover replacement for recurring engagement, the other anchoring brand strength through proprietary bead technology and in-store experience. Fatboy the Original B.V. occupies a position emphasizing European design heritage and channel control. These three represent the spectrum from manufacturing-integrated to experience-centric competitive positioning.
| Leading Market Players |
|---|
| The Lovesac Company |
| Yogibo LLC |
| Fatboy the Original B.V. |
| Sumo Lounge International Corporation |
| Comfy Sacks Company |
| CordaRoy Company |
| Big Joe |
| Jaxx Bean Bags |
| Ryohin Keikaku Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Memory-foam hybrid filling technology is compressing the traditional cost-comfort trade-off while simultaneously concentrating production expertise in Guangdong and Zhejiang provinces. This dual shift elevates pricing power for manufacturers with certified foam shredding capacity while exposing commodity bead-dependent competitors to petrochemical input volatility.
Pricing Analysis
Margin tightening in the classic polyester segment reflects virgin polystyrene bead price volatility tied to crude oil indices. Three-tier pricing structure across premium leather, mid-grade microfiber, and economy classic levels segments buyers by certification tolerance and durability requirements. Cost-down pressure on volume producers accelerates as REACH-compliant foam commands procurement premiums in European channels. Mass-market retail buyers in the United States exhibit highest price sensitivity, while hospitality specifiers absorb leather premiums for fire-retardant certification.
Supply Chain Analysis
Skilled upholstery labor scarcity in Midlands manufacturing and North Rhine-Westphalia constrains rapid scaling for brands reshoring finishing operations. Fabric weaving and foam shredding capacity clusters in Guangdong and Zhejiang, with tanning agent supply chains anchored in Italy and India. Raw material dependencies rest on expanded polystyrene resin, polyurethane foam precursors, and REACH-certified flame-retardant additives. Single-source vulnerability in Chinese coastal manufacturing exposes brands to shipping rate spikes and tariff uncertainty. Distribution runs through direct-to-consumer digital storefronts and specialty retail channels bypassing traditional furniture intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic sewing and finishing capacity constraints prop pricing for manufacturers with captive upholstery operations, creating defendable margin pools for integrated producers.
For Market Incumbents: Deploy backward integration into foam shredding capacity to secure bead-to-foam hybrid supply chains against petrochemical volatility. Lock in REACH-certified tanning agent partnerships to maintain European channel access as ECHA substance-of-very-high-concern listings expand. Channel control through owned experiential retail formats defends against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Capture boutique hotel and co-working lounge specification channels where design-forward seating commands project-based premiums underserved by mass-market fabricators. Target gaming peripheral manufacturers seeking tournament-grade memory-foam hybrid seating with thermal regulation specifications. Launch through subscription cover replacement programs to lock recurring engagement before incumbent brands replicate the model. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by furniture conglomerates seeking direct-to-consumer capabilities and certified European supply chains. Long-term viability hinges on circular economy alignment through bead recyclability infrastructure and take-back program scalability. Watch EU Green Deal procurement specification tightening as the inflection signal for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Shredding | Captive supply of memory-foam hybrid filling insulates margin from petrochemical volatility in Guangdong. |
| REACH-Certified Supply Chain Certification | ECHA-compliant tanning agent sourcing unlocks premium placement in regulated European retail channels. |
| Subscription Cover Replacement Launch | Recurring fabric shell revenue locks urban United States consumers with limited storage for spare units. |
| Hospitality Specification Channel Development | Boutique hotel and co-working lounge procurement commands project-based premiums absent in mass retail. |
| Bead Recyclability Infrastructure Buildout | Take-back programs align with EU Green Deal circular economy targets and hardening procurement specifications. |
Methodological Framework
Document review covered trade customs data, SEC filings from furniture and textile manufacturers, and EU ECHA regulatory databases, complemented by interviews with bean bag product development executives, foam supply chain procurement leads, hospitality interior specification consultants, and direct-to-consumer brand operations directors. Secondary validation drew from CPSC flammability standard documentation, California Proposition 65 disclosure registries, and REACH substance-of-very-high-concern listings. Bottom-up demand modeling and top-down supply capacity estimates were triangulated against shipment data from coastal Chinese manufacturing clusters.
Volume and value trajectories across the projection horizon reflect segmented modeling by product type, end-user application, size tier, and design aesthetic, with additional dimensioning by certification grade and channel structure. CAGRs were derived from elasticity-adjusted demand curves incorporating gaming lounge proliferation rates and REACH compliance transition timelines. Industry-specific inputs included petrochemical price indices for expanded polystyrene resin and hospitality construction pipeline data for commercial seating procurement.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal circular economy mandate acceleration and skilled upholstery labor availability in reshoring geographies. Forecasts reflect documented assumptions on gaming venue expansion trajectories and chemical disclosure framework evolution. Material deviation in REACH substance-of-very-high-concern listing velocity or container shipping rate volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Canada Home Furniture Market
Furniture
Europe and Middle East Demountable Partitions Market
Furniture
Luxury Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Italy Office Furniture Market
Furniture
China Upholstered Furniture Market
Furniture
Global Home Furniture Market
Furniture
United States Upholstered Furniture Market
Furniture
Brazil Furniture Market
Furniture
Indonesia Furniture Market
Furniture
India Home Furniture Market
Furniture
Canada Secondary Wood Products Market
Furniture
United Kingdom Home Furniture Market
Furniture
Global Smart Furniture Market
Furniture
Children Furniture Market
Furniture
US Sustainable Furniture Market