
 Melamine Door Market | 2026-2036
Melamine Door Market Size, Share, and Industry Trends Forecast 2026-2036
Melamine Door Market Foresight
After-sales maintenance contracts and finish-touchup subscription services is restructuring how melamine door suppliers capture lifetime value from commercial installations. Masonite International Corporation leverages its North American distribution network to anchor large-scale residential projects with standardized flush door configurations. JELD-WEN Holding, Inc. competes through vertically integrated lamination facilities that control substrate-to-surface quality across multiple thickness grades. Egger Group specializes in European-specified low-emission melamine surfaces that sustain premium positioning in institutional builds.
Melamine doors consist of engineered wood substrates—typically medium-density fiberboard or particleboard—surfaced with thermally fused melamine-impregnated decorative paper, offering scratch resistance, color stability, and moisture protection for high-traffic interior environments. Flush doors dominate volume production due to manufacturing simplicity and compatibility with automated lamination lines, while fire-rated applications command specialized certification premiums in commercial and institutional channels. Paneled doors retain share in residential segments where aesthetic differentiation supports higher price realization, and acoustic-rated configurations are gaining specification in healthcare and education builds.
EPA formaldehyde emission standards under TSCA Title VI govern composite wood products in the United States, directly affecting substrate sourcing for melamine door manufacturers serving North American customers. REACH compliance across Europe restricts certain resin chemistries, pushing suppliers toward MUF and PUF adhesive systems with lower free formaldehyde content. China's GB/T 39600-2021 and evolving MEE enforcement create parallel compliance tracks for export-oriented producers. Stakeholders must monitor divergence between regional emission thresholds and assess whether dual-certification investments or geographic product segmentation delivers superior margin protection.
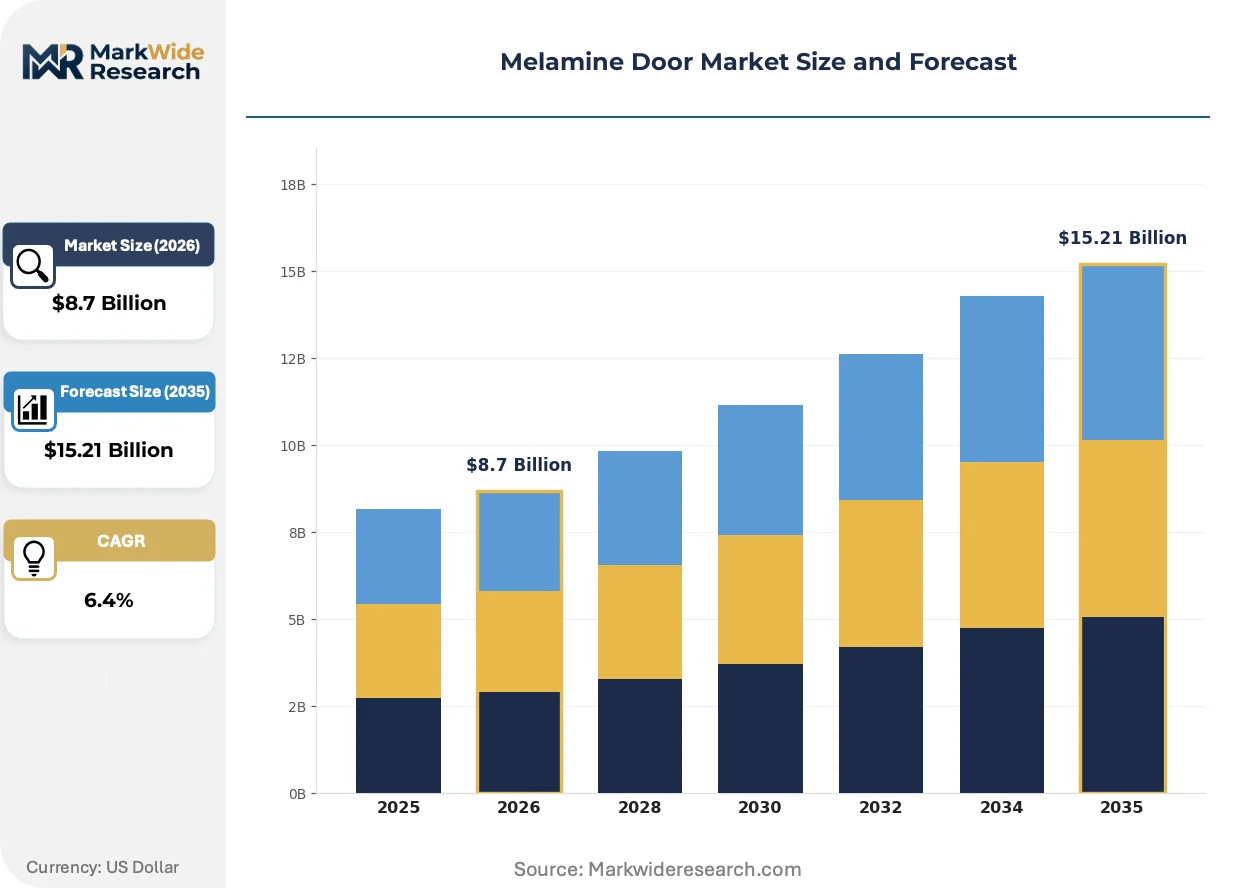
Market Dynamics
China's GB/T 39600-2021 formaldehyde emission standards are compressing supplier margins while forcing substrate reformulation across export-oriented manufacturing clusters. The regulatory tightening is consolidating procurement power among vertically integrated door fabricators capable of dual-certification compliance.
Growth Catalysts
- Urban Housing Expansion:Residential construction across Vietnam's manufacturing corridor near Ho Chi Minh City is absorbing larger volumes of melamine-faced door products as urban housing stock expands.
- REACH Compliance Migration:European-specified low-emission melamine surfaces are sustaining premium positioning in institutional builds as MUF and PUF adhesive systems replace legacy resin chemistries.
- Acoustic Specification Uptake:Healthcare and education builds are specifying acoustic-rated melamine door configurations for high-traffic interior environments.
Market Restraints
- Substrate Cost Volatility:Medium-density fiberboard and particleboard input costs fluctuate with regional pulp supply disruptions and energy pricing.
- Supplier Concentration Risk:Export-oriented door fabrication clusters concentrate near Ho Chi Minh City, creating single-geography exposure for North American and European buyers.
- Fire-Rated Certification Barriers:Specialized certification premiums in commercial channels require capital-intensive testing protocols that exclude smaller fabricators.
Strategic Opportunities
- After-Sales Service Unbundling:Finish-touchup subscription services and maintenance contracts are restructuring how suppliers capture lifetime value from commercial installations.
- Flush Door Automation:Manufacturing simplicity and compatibility with automated lamination lines is consolidating volume production around standardized configurations.
- Dual-Carbon Alignment:China's MEE enforcement and evolving dual carbon goals are creating preferential procurement status for low-emission substrate suppliers.
Industry Challenges
- Formaldehyde Testing Talent Scarcity:Laboratory certification for GB, EPA TSCA Title VI, and REACH compliance requires specialized analytical chemistry capabilities in short supply.
- Lamination Line Capex Burden:Vertically integrated facilities controlling substrate-to-surface quality across multiple thickness grades demand significant capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melamine Door Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flush Doors, Paneled Doors, Bi-Fold Doors, French Doors End User: Commercial, Residential, Institutional, Industrial Thickness: Standard, Custom, Lightweight, Heavyweight Application: Interior, Exterior, Fire-Rated, Acoustic |
| Companies Covered | Masonite International Corporation, JELD-WEN Holding, Inc., Winzone Doors, Supa Doors, Inc., Best Industrial PTE LTD, CREO P.iva, Lanz Cabinets Incorporated, Egger Group, Kronospan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melamine Door Market Shifts & Advancements
Thermally fused melamine-impregnated decorative paper is consolidating manufacturing scale advantages while regulatory divergence between EPA, REACH, and GB standards fragments certification requirements. Three interconnected developments are reshaping competitive positioning.
Digital printing on melamine surfaces is consolidating color-matching precision and short-run customization capabilities previously requiring separate production lines. High-end residential developers are adopting digitally printed wood-grain alternatives to veneer at compressed lead times. This technology is consolidating small-batch premium production into centralized facilities capable of rapid design iteration.
EPA formaldehyde emission standards under TSCA Title VI are governing composite wood products in the United States and directly affecting substrate sourcing decisions. Manufacturers serving North American customers must maintain separate inventory streams or reformulate universally. Fire-rated commercial applications face the steepest compliance cost escalation as third-party certification timelines extend.
Specification-driven procurement is compressing supplier qualification cycles from multi-year frameworks to project-by-project bidding. General contractors in Southeast Asia are unbundling door supply from full-fit contracts, creating direct relationships with melamine door fabricators. Vietnam's export-oriented clusters are capturing this channel shift fastest through English-language specification support and North American delivery logistics.
Melamine Door Market Segmentation
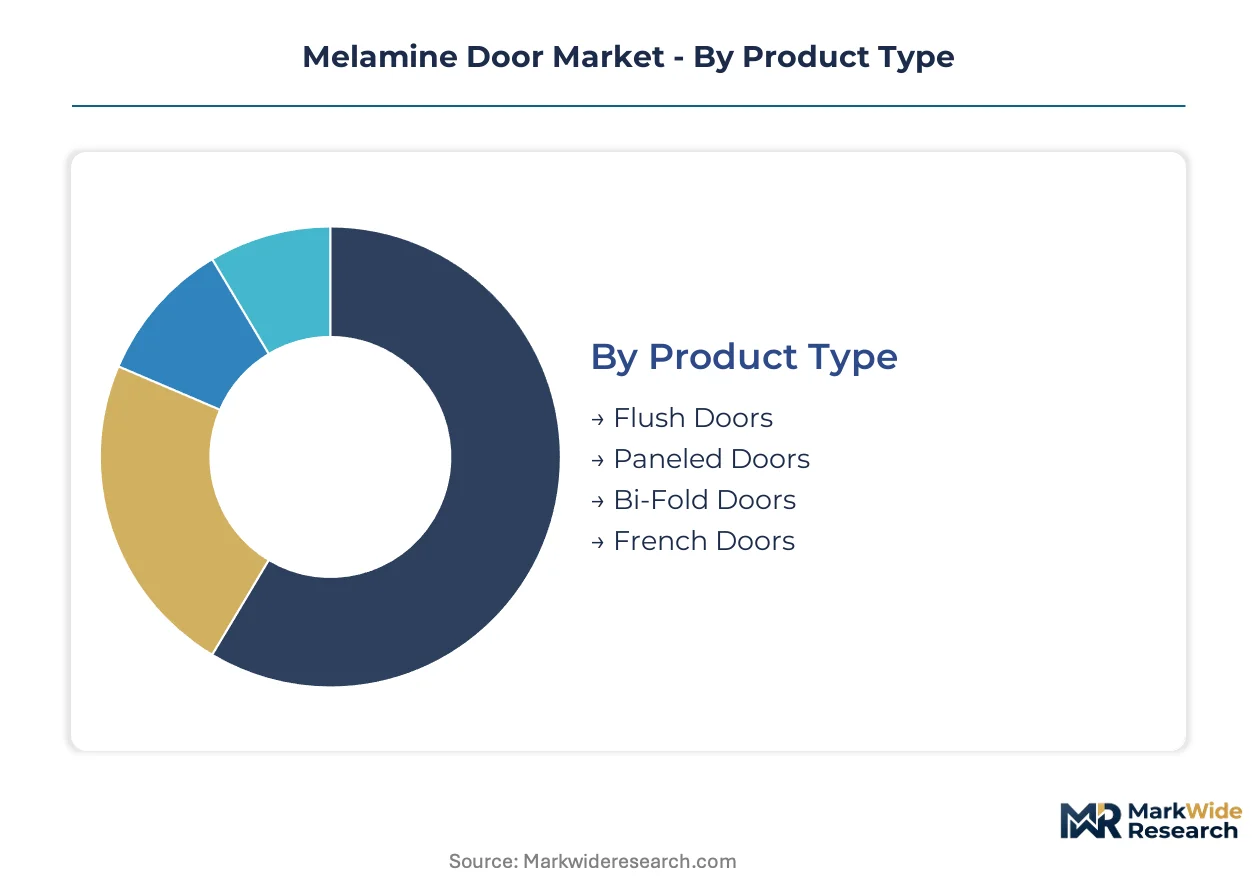
Melamine door procurement decisions cascade through four distinct category hierarchies. Product type determines manufacturing automation compatibility and margin structure. End-use concentration in Vietnam's export corridor reshapes how thickness grades and application specifications align with regional building codes.
Product Type:
Buyers prioritize manufacturing simplicity and lamination line throughput when selecting door configurations for volume deployment.
- Flush Doors:Flat slab construction from MDF or particleboard substrates enables continuous automated lamination. Demand concentrates in North American multi-family residential projects where standardized dimensions reduce field modification costs.
- Paneled Doors:Routed substrate profiles create aesthetic differentiation through simulated stile-and-rail geometry. Premium residential developers in Southeast Asia specify these for single-family detached housing where visual warmth commands price premiums.
- Bi-Fold Doors:Hinged panel pairs fold against wall planes to maximize usable floor area in compact urban dwellings.
- French Doors:Full-light configurations with divided-lite mullions serve terrace and balcony access points in tropical climate zones.
Volume sits with Flush Doors; growth tilts toward Paneled Doors.
End User:
Application environments dictate emission certification tiers and hardware durability specifications.
- Commercial:High-traffic office and retail installations demand scratch-resistant surfaces with 10-year finish warranties. Procurement concentrates in Vietnam's Ho Chi Minh City manufacturing corridor for export to North American and European fit-out contractors.
- Residential:Single-family and multi-family housing absorbs the majority of standard-thickness production. China's updated GB/T 39600-2021 formaldehyde standards are compressing supplier margins while forcing substrate reformulation across export-oriented clusters.
- Institutional:Healthcare and education builds specify acoustic-rated and fire-rated configurations with extended lifecycle cost analysis.
- Industrial:Utility and warehouse applications prioritize moisture resistance over aesthetic refinement.
Commercial procurement dominates export volume; institutional specification drives premium margin capture.
Thickness:
Structural performance requirements and hardware compatibility anchor thickness selection decisions.
- Standard:35mm to 40mm profiles accommodate standard mortise locksets and meet most interior door frame tolerances.
- Custom:Non-standard dimensions serve historic renovation and architect-specified openings requiring millwork integration.
- Lightweight:Reduced-density cores lower shipping costs for containerized export from Vietnamese fabrication clusters.
- Heavyweight:Solid-core construction enhances acoustic dampening for hotel and conference room applications.
Standard thickness anchors production planning; custom fabrication expands most quickly in high-end residential channels.
Application:
Building code jurisdiction and insurance requirements separate interior decorative applications from performance-rated specifications.
- Interior:Non-rated doors for room separation constitute the baseline volume category across all end-use segments.
- Exterior:Weather-resistant edge sealing and UV-stable surface formulations serve covered porch and service entrance applications.
- Fire-Rated:20-minute to 90-minute rated assemblies require intumescent seals and specialized core materials. Third-party certification timelines extend procurement cycles and exclude smaller fabricators from commercial bidding.
- Acoustic:STC-rated configurations with perimeter gasketing gain specification in healthcare patient rooms and education facilities where speech privacy is mandated.
Interior applications absorb baseline capacity; fire-rated and acoustic specifications command the steepest certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ho Chi Minh City's manufacturing corridor concentrates export-oriented melamine door fabrication for North American and European buyers, with Vietnam's urban housing expansion absorbing larger production volumes as residential construction accelerates.
United States
Multi-family residential projects in Texas and Florida drive standardized flush door specifications, with EPA TSCA Title VI formaldehyde standards governing composite wood substrate sourcing. Masonite International Corporation leverages its distribution network to anchor large-scale developments.
Germany
Institutional builds in Bavaria and North Rhine-Westphalia specify low-emission melamine surfaces for healthcare and education applications. REACH compliance restricts legacy resin chemistries, pushing fabricators toward MUF and PUF adhesive systems with reduced free formaldehyde content.
China
GB/T 39600-2021 standards are tightening material specifications across the Yangtze River Delta and Pearl River Delta manufacturing zones. The country's MEE enforcement creates parallel compliance tracks for export-oriented producers serving divergent regional emission thresholds.
Vietnam
Export fabrication clusters near Ho Chi Minh City serve North American and European procurement channels with English-language specification support. Urban housing stock expansion absorbs larger volumes of melamine-faced door products as residential construction intensifies.
France
Île-de-France commercial fit-out contractors specify acoustic-rated configurations for high-traffic office environments. ECHA oversight of REACH implementation sustains premium positioning for European-specified low-emission surfaces in institutional channels.
Melamine Door Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered supply positions. Vertically integrated lamination facilities control substrate-to-surface quality across multiple thickness grades, while specialized fabricators concentrate on project-specific certification compliance. Three archetypes dominate: North American distributors with standardized flush configurations, European specialists in low-emission institutional surfaces, and Southeast Asian export clusters with automated production lines. Competitive moves center on dual-certification investments for regulatory divergence and after-sales service unbundling through maintenance contracts.
Among North American-headquartered corporations, Masonite International Corporation and JELD-WEN Holding, Inc. exemplify scale-driven distribution architectures, while Egger Group represents European specialization in emission-compliant surfaces for premium institutional specification.
| Leading Market Players |
|---|
| Masonite International Corporation |
| JELD-WEN Holding, Inc. |
| Winzone Doors |
| Supa Doors, Inc. |
| Best Industrial PTE LTD |
| CREO P.iva |
| Lanz Cabinets Incorporated |
| Egger Group |
| Kronospan |
| Others |
Supply & Pricing Matrix
EPA TSCA Title VI certification requirements for North American multi-family residential projects are compressing supplier qualification timelines and forcing export-oriented fabricators toward dual-certified substrate inventories that carry cost premiums. This specification-driven procurement pressure reshapes how Vietnamese manufacturing clusters position their pricing against European REACH-compliant alternatives.
Pricing Analysis
Margin tightening in standard-thickness flush door tiers reflects automated lamination line throughput competition among Ho Chi Minh City export clusters. Three-tier pricing structure across premium low-emission, standard certified, and economy non-rated levels separates institutional healthcare specifications from residential multi-family volume contracts. Cost-down pressure on lightweight export configurations accelerates because containerized shipping cost fluctuations now exceed substrate material differentials. Commercial contractors demonstrate highest price sensitivity due to unbundled procurement from general fit-out contracts, while institutional buyers absorb certification premiums for fire-rated and acoustic-rated assemblies.
Supply Chain Analysis
Medium-density fiberboard supply rests on Malaysian and Indonesian pulp processing capacity integrated with Vietnamese lamination facilities. Melamine-impregnated decorative paper feeds from Chinese specialty chemical producers subject to MEE environmental enforcement actions. Raw particleboard draws from Thailand's rubberwood processing clusters and domestic Vietnamese eucalyptus plantations. Single-geography concentration near Ho Chi Minh City creates tariff exposure vulnerability for North American buyers. Distribution runs through direct specification relationships with general contractors, bypassing traditional distributor markups in Southeast Asian commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over substrate-to-surface quality certification determines qualification for institutional procurement channels. Players are pursuing captive lamination capacity as the decisive downstream lever.
For Market Incumbents: Anchor position through backward integration into low-emission substrate production that satisfies simultaneous EPA TSCA Title VI and GB/T 39600-2021 compliance. Defend against emerging Southeast Asian export clusters by securing multi-year maintenance contract relationships with North American multi-family developers. Prioritize acoustic-rated certification investment to capture healthcare and education specification premiums before fire-rated barriers harden further. For New Entrants and Emerging Players: Digital printing technology for short-run wood-grain customization offers a technology-first wedge against centralized veneer-alternative production. Target high-end residential developers in Vietnam's urban expansion corridors where compressed lead times command price premiums. Pursue direct-to-contractor specification support bypassing traditional distribution layers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated fabricators with existing dual-certification laboratory capabilities. Long-term viability hinges on emission testing talent retention as regulatory divergence between EPA, REACH, and GB standards fragments compliance requirements. Monitor MEE enforcement intensity in China's Yangtze River Delta as the signal for substrate cost inflection and supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Laboratory Investment | GB/T 39600-2021 and EPA TSCA Title VI compliance unlocks simultaneous North American and European institutional bidding. |
| Automated Lamination Line Expansion | Continuous flush door production in Ho Chi Minh City clusters captures multi-family residential volume contracts. |
| After-Sales Service Unbundling | Finish-touchup subscription contracts restructure lifetime value capture from commercial installation relationships. |
| Digital Printing Surface Technology | Short-run customization consolidates premium residential specification previously requiring separate veneer production lines. |
| Acoustic-Rated Certification Pathway | STC-rated configurations penetrate healthcare patient room and education facility mandates with extended procurement cycles. |
Research Methodology
Trade customs databases, SEC 10-K filings from North American building products corporations, and Vietnam General Statistics Office export records formed the secondary backbone. Primary interviews with door fabrication plant managers, procurement leads at multi-family residential developers, specification writers at commercial general contractors, and distribution channel partners in Southeast Asia combined with this secondary validation. Bottom-up production capacity modeling and top-down end-use consumption estimates were triangulated across analysis sources.
Historical trendline analysis of melamine-faced door export volumes from Vietnamese customs data established baseline growth patterns across the projection horizon. The analytical framework modeled segmentation dimensions including product type configuration, end-use application environment, thickness grade specification, and regional regulatory compliance tier. CAGRs were derived from elasticity-adjusted demand projections incorporating urban housing stock expansion rates and formaldehyde standard implementation timelines. Industry-specific forecast inputs included pulp fiber cost indices and containerized freight rate volatility assumptions.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Vietnamese export access, unforeseen raw material substitution technologies, and accelerated regulatory harmonization between EPA and GB emission thresholds. Forecasts reflect documented assumptions about certification timeline stability and laboratory testing capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Home Improvement Market