
 Australia Do-It-Yourself (DIY) Home Improvement Retailing Market | 2026-2036
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market Insights
Australia's National Construction Code energy efficiency provisions is repositioning demand toward insulation, sealing products, and efficient fixtures. Bunnings Warehouse leverages its national store network and trade-focused counters to sustain contractor loyalty. Total Tools anchors the professional-grade power equipment segment with specialized inventory depth. Mitre 10 competes through localized store formats and community-based supplier relationships.
Do-it-yourself home improvement retailing encompasses the sale of tools, building materials, decorative finishes, and installation supplies to non-professional consumers undertaking residential renovation, repair, or construction projects; products typically include timber, fasteners, paints with specified VOC content, and cordless power tools rated by voltage and torque output. The distribution channel dimension reveals structural concentration, with hardware stores capturing the bulk of transaction volume while online platforms absorb the fastest growth in repeat consumables and click-and-collect orders. Price tier segmentation shows margin pools clustering in premium cordless tool systems and specialist coatings, while budget tiers drive traffic volume in bulk fasteners and basic structural timber.
TGA product safety standards and Australian Competition and Consumer Commission mandatory reporting requirements shape product compliance obligations for electrical and gas-fitting goods sold through retail channels. The Building Code of Australia, administered by the Australian Building Codes Board, dictates material specifications that filter through to retail stocking decisions. Stakeholders must monitor state-level planning reforms that accelerate renovation approvals and assess how embedded energy-rating disclosures shift homeowner upgrade priorities.
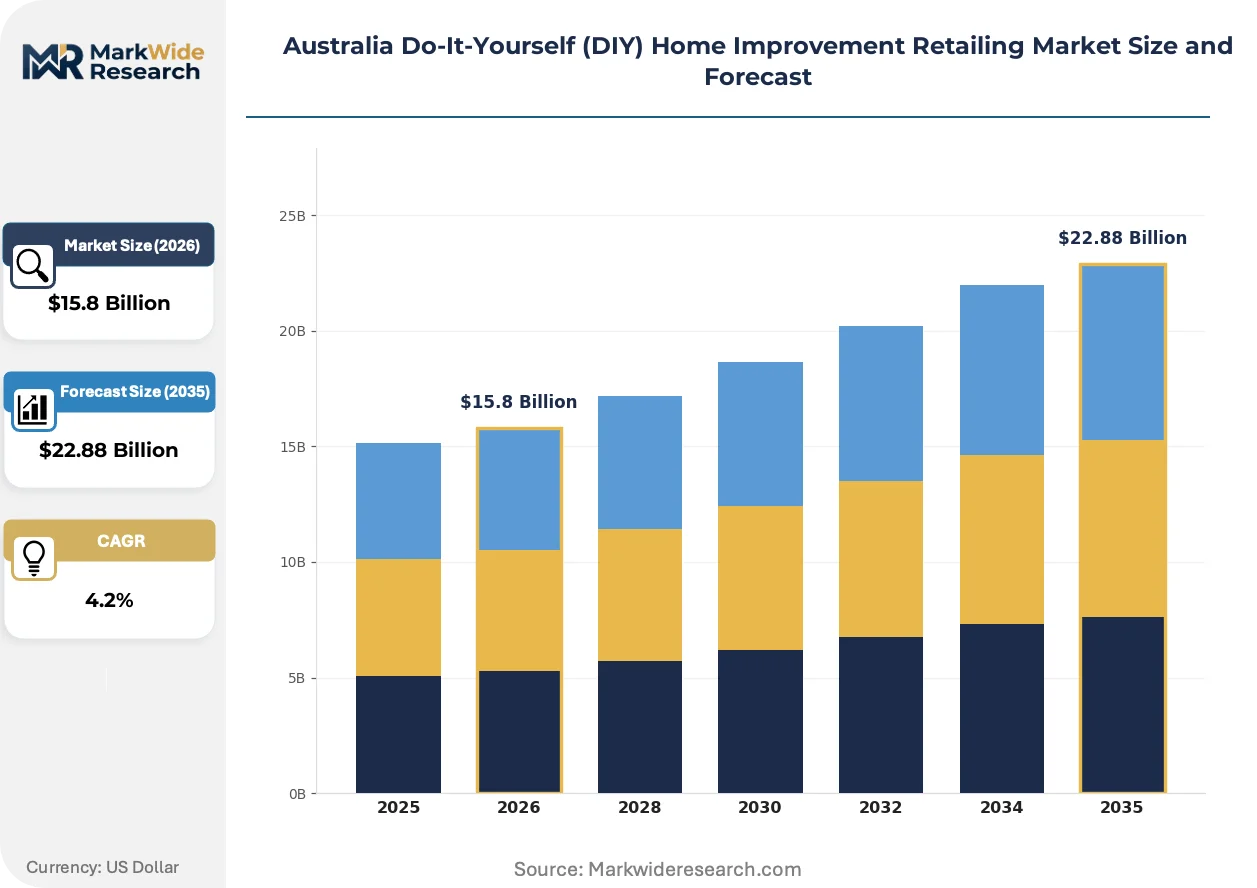
Market Dynamics
Australia's National Construction Code energy efficiency upgrades are compressing replacement cycles for insulation, glazing, and HVAC components while redirecting homeowner spending toward compliance-grade materials.
Growth Catalysts
- Energy efficiency mandates:The National Construction Code's thermal performance requirements are accelerating renovation timelines as households preempt mandatory disclosure obligations.
- Aging housing stock:Inner-ring Sydney and Melbourne suburbs contain pre-1980 dwellings requiring structural timber, roofing, and weatherproofing replacement.
- Trade counter professionalization:Licensed contractors now represent the dominant transaction volume at major retail networks, shifting inventory toward commercial-grade specifications.
Market Restraints
- Timber supply volatility:Structural softwood availability fluctuates with plantation harvest cycles and import dependency from New Zealand and Southeast Asia.
- Electrical goods compliance:TGA and Australian Competition and Consumer Commission mandatory reporting requirements extend product registration timelines for power tools and gas-fitting equipment.
- DIY skill erosion:Younger owner-occupiers demonstrate lower technical confidence with structural and electrical work, constraining addressable demand to cosmetic and outdoor categories.
Strategic Opportunities
- Embedded energy ratings:State-level planning reforms mandating pre-sale efficiency disclosures create pull-through demand for insulation, sealing systems, and efficient fixtures.
- Click-and-collect infrastructure:Online platforms capturing repeat consumables orders present channel expansion potential for metropolitan fulfillment networks.
- Regional Victoria and Queensland:Underpenetrated markets outside Greater Sydney and Melbourne offer whitespace for localized inventory and contractor relationship development.
Industry Challenges
- Certification timeline compression:Australian Building Codes Board material specification updates require rapid SKU turnover and obsolete stock management.
- Last-mile delivery costs:Bulky timber and sheet goods resist economical direct-to-consumer shipping, constraining pure-play digital penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Do-It-Yourself (DIY) Home Improvement Retailing Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $22.88 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tools, Paints, Flooring, Lighting End User: Homeowners, Contractors, Retailers, Property Managers Distribution Channel: Online, Supermarkets, Hardware Stores, Specialty Stores Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | National Building Suppliers Group, Total Tools, Bunnings Warehouse, B&Q Limited, Hardware and Building Traders (HBT), Mitre 10, Thrifty-Link, Miniso Australia, Home Hardware, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market Trends and Innovations
Digital tools and compliance frameworks are compressing decision cycles while elevating specification precision across Australia's renovation supply chain.
Smart home automation systems are expanding into residential retrofit projects as owner-occupiers prioritize integrated climate and security control. Mid-market households in Melbourne's eastern suburbs and Sydney's north shore are adopting these systems at accelerating rates. The technology is expanding into traditional electrical and HVAC contractor relationships, requiring retailers to stock compatible wiring and control modules alongside conventional trade supplies.
The National Construction Code's 2022 thermal performance updates are tightening glazing and insulation specifications for existing dwelling alterations. Builders and owner-builders must now source higher-grade materials to satisfy compliance documentation. Victoria and New South Wales are experiencing the most acute specification shifts, with retailers adjusting shelf space toward certified products.
Project-based buying patterns are fragmenting historical brand loyalty as households research specifications through digital channels before entering stores. Hardware retailers respond with augmented inventory visibility and specialist staffing at trade counters. This behavioral shift concentrates in Greater Sydney and Melbourne where renovation approval volumes remain highest.
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market Segmentation
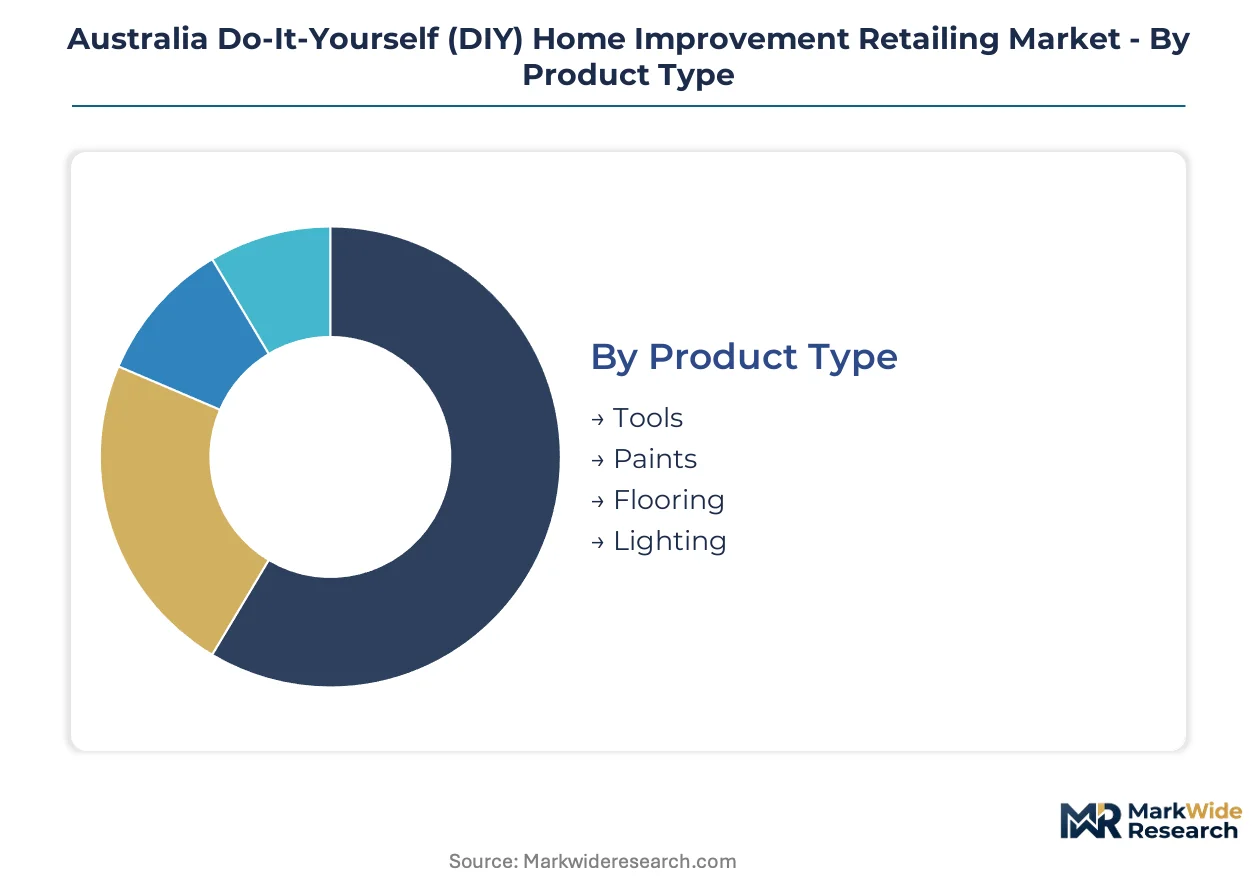
Segmentation in Australia's DIY home improvement retailing market reveals how purchase behavior fragments across project complexity, professional involvement, and channel preference. Understanding these divides helps retailers align inventory depth, staffing models, and fulfillment infrastructure with actual transaction patterns.
Product Type:
Integration depth varies sharply: tools and paints function as standalone purchases with minimal installation support, while flooring and lighting increasingly require embedded system compatibility.
- Tools:Cordless power systems dominate trade counter transactions, with voltage ratings and battery platform compatibility driving replacement cycles. Demand concentrates in Greater Sydney and Melbourne where contractor licensing requirements elevate specification awareness. The National Construction Code's electrical safety provisions are compressing registration timelines for imported equipment.
- Paints:Low-VOC formulations now capture regulatory-driven renovation work, with VOC content thresholds set by Australian Building Codes Board amendments. Melbourne's inner-ring suburbs show the steepest specification shifts as pre-sale disclosure requirements tighten. TGA product safety standards extend testing obligations for antimicrobial and specialty coating claims.
- Flooring:Hybrid and engineered products require subfloor moisture testing and acoustic underlay compliance. Queensland's humidity-exposed markets show elevated demand for moisture-resistant substrates.
- Lighting:LED retrofits and smart control integration dominate residential replacement, with Australian Competition and Consumer Commission electrical safety mandates shaping SKU availability.
Tools lead volumes today; paints are gaining share fastest through compliance-grade specification upgrades.
End User:
Cost tier stratification separates occasional DIY households from trade professionals with recurring material requirements and credit account structures.
- Homeowners:Project-based purchasing with high digital research intensity before store entry. Sydney's eastern suburbs and Melbourne's north shore show elevated smart home integration spending.
- Contractors:Licensed trade professionals now represent dominant transaction volume at major retail networks, with commercial-grade inventory and dedicated trade counters capturing loyalty. Regional Victoria and Queensland show underpenetrated contractor relationship potential.
- Retailers:Smaller independent hardware operators sourcing inventory for resale, with consolidated buying power concentrated among regional distribution cooperatives.
- Property Managers:Maintenance-grade purchasing for rental portfolios, with bulk consumables and rapid-turnaround repair materials driving repeat transactions.
Contractors lead volumes today; property managers are expanding most quickly through portfolio maintenance standardization.
Distribution Channel:
Volume concentration follows bulky goods handling economics, with last-mile constraints protecting physical retail for timber and sheet goods while digital platforms capture replenishment cycles.
- Online:Repeat consumables and click-and-collect orders show steepest expansion, with metropolitan fulfillment networks capturing paint, fasteners, and small tools. Bulky timber resists economical direct shipping.
- Supermarkets:Limited SKU ranges target emergency repair and basic maintenance, with convenience positioning in suburban catchments lacking dedicated hardware presence.
- Hardware Stores:National networks with trade counter professionalization dominate structural timber, power tools, and compliance-grade materials. Inventory depth anchors contractor loyalty.
- Specialty Stores:Tile, flooring, and lighting specialists capture specification-intensive projects with design consultation and installation referral services.
Hardware stores lead volumes today; online is climbing the fastest through consumables replenishment automation.
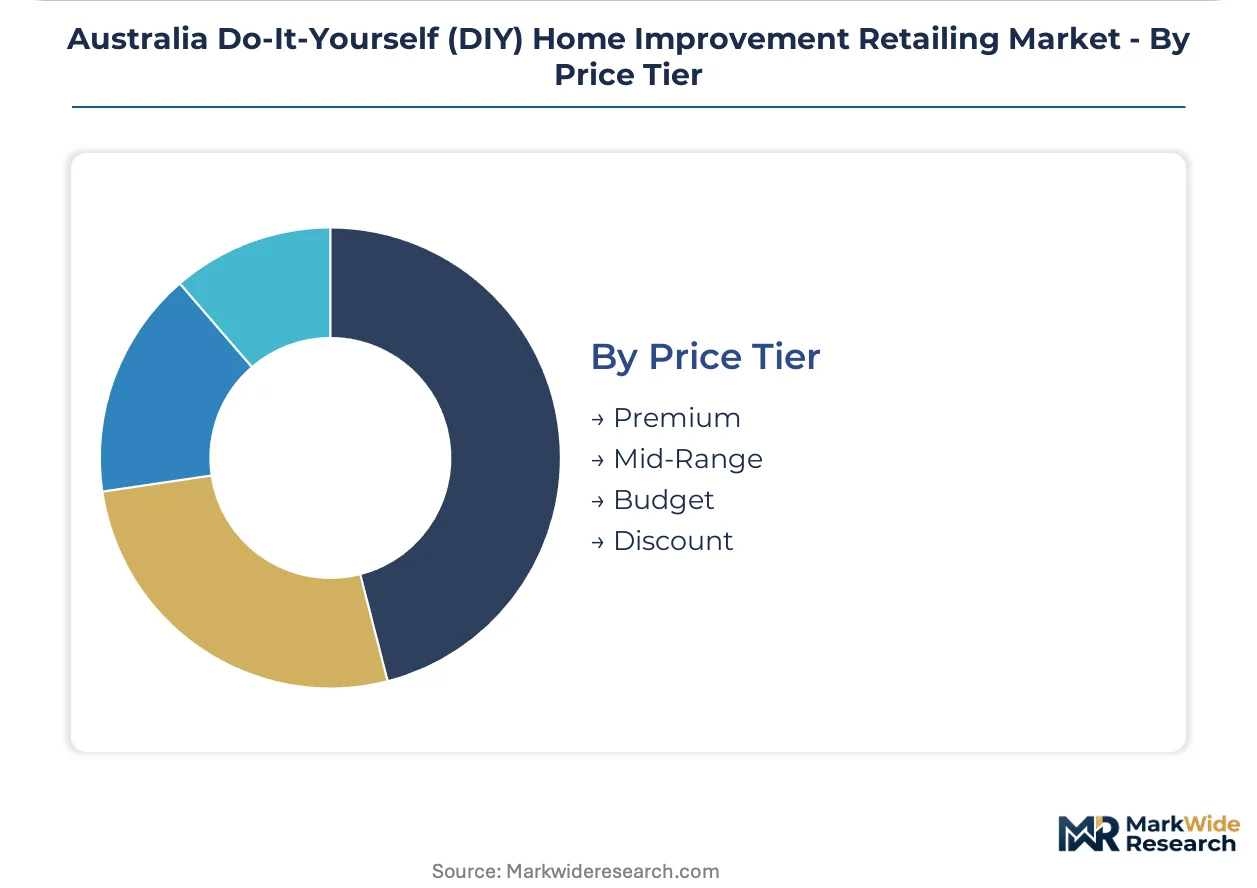
Price Tier:
Margin pools cluster where technology differentiation or certification complexity creates specification lock-in, while traffic-driving categories compete on volume scale.
- Premium:Cordless tool platforms with battery ecosystem lock-in and specialist coatings with extended durability warranties. Melbourne and Sydney premium suburbs concentrate demand.
- Mid-Range:Balanced specification and availability for standard renovation projects, with brand recognition driving selection among confident DIY households.
- Budget:Bulk fasteners, basic structural timber, and entry-grade power tools drive store traffic volume. Price transparency from digital comparison shopping compresses differentiation.
- Discount:Closeout inventory, seasonal clearance, and private-label alternatives targeting single-project purchasers with minimal brand loyalty.
Budget tiers lead volumes today; premium positioning shows steepest expansion trajectory through battery platform ecosystems and certified coating systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's DIY home improvement retail sector traces its modern scale to post-war suburban expansion, when hardware cooperatives and independent merchants established the foundation for today's national networks. The industry now distributes through state-level regulatory environments that shape inventory and compliance requirements.
New South Wales
Greater Sydney's inner-ring suburbs drive replacement demand for aging pre-1980 housing stock. The state's planning reforms accelerate renovation approval timelines, compressing project initiation cycles. Eastern suburbs households show elevated specification awareness for smart home integration and energy-efficient fixtures.
Victoria
Melbourne's northern and eastern corridors concentrate contractor-grade transaction volumes at trade-specialized counters. The Victorian Building Authority enforces stringent electrical safety inspections that filter through to retail stocking decisions for power tools and wiring accessories. Regional centers outside Geelong and Ballarat present underdeveloped contractor relationship potential.
Queensland
Brisbane's subtropical climate elevates demand for moisture-resistant flooring substrates and external weatherproofing systems. The Queensland Building and Construction Commission mandates licensed tradesperson involvement for structural alterations, reinforcing professional channel dominance. Southeast Queensland's corridor development sustains new construction material flows alongside renovation activity.
Western Australia
Perth's isolated market position creates distinct supply chain economics with elevated inventory carrying costs. The state's Building Commission administers energy efficiency disclosure requirements that redirect homeowner spending toward compliance-grade insulation and glazing. Resource sector wage cycles historically correlate with discretionary renovation expenditure in metropolitan catchments.
South Australia
Adelaide's compact metropolitan footprint supports efficient distribution networks with shorter last-mile delivery radii for bulky timber and sheet goods. The South Australian Planning Commission's heritage overlay regulations constrain external alteration options, concentrating retail demand on interior finishes and fixture upgrades. Regional centers show dependency on Adelaide-based distribution hubs for specialist product availability.
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market Competitive Landscape
Capital-heavy warehouse operators compete with asset-light specialty retailers for transaction share across Australia's DIY home improvement sector. National networks with owned distribution infrastructure dominate structural timber and bulk materials, while focused specialists capture premium tool and equipment segments through curated inventory depth. Three archetypes define competitive positioning: scale-driven warehouse operators, trade-specialized equipment suppliers, and cooperative independent networks. Consolidation pressure operates through property portfolio expansion and contractor account acquisition rather than horizontal product line mergers.
Among scale-driven warehouse operators, Bunnings Warehouse anchors national coverage through extensive metropolitan and regional store networks. Total Tools occupies the professional-grade equipment tier with specialized power tool and machinery focus. Mitre 10 represents the cooperative independent archetype, aggregating localized merchant relationships under unified procurement and branding systems.
| Leading Market Players |
|---|
| National Building Suppliers Group |
| Total Tools |
| Bunnings Warehouse |
| B&Q Limited |
| Hardware and Building Traders (HBT) |
| Mitre 10 |
| Thrifty-Link |
| Miniso Australia |
| Home Hardware |
| Others |
Pricing and Supply Chain Analysis
Structural softwood input costs cascade through Australia's DIY retail tiers, with plantation harvest cycles in New Zealand and Southeast Asia compressing margins at the budget end while premium cordless tool platforms maintain pricing power through battery ecosystem lock-in.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates battery-platform ecosystems from specification-grade trade tools from entry-grade DIY equipment. Price differentiation hinges on certification tier under Australian Building Codes Board standards and volume scale at trade counters. Cost compression in budget timber and fasteners is intensifying because of import dependency and currency fluctuation. Property managers show highest price sensitivity due to portfolio maintenance standardization, while contractors prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Melbourne and Sydney anchor hub-and-spoke fulfillment patterns, with Adelaide and Perth operating as secondary nodes with elevated inventory carrying costs. Geographic supply concentration draws from New Zealand plantation forests, Southeast Asian plywood mills, and Chinese power tool manufacturing. Raw material dependencies rest on structural softwood, lithium-ion cells, and petroleum-derived coatings. Single-source vulnerability in battery cell supply creates exposure. Distribution runs through national warehouse networks with trade counter professionalization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's National Construction Code thermal performance updates compound demand for compliance-grade materials, making this market a regulatory compounder where efficiency mandates drive replacement cycles.
For Market Incumbents: Hedge against timber supply volatility through backward integration into certified plantation partnerships or long-term offtake agreements with New Zealand suppliers. Reinforce trade counter loyalty by embedding energy-rating documentation services that streamline contractor compliance workflows. Defend against pure-play digital entrants by expanding click-and-collect infrastructure for consumables replenishment. For New Entrants and Emerging Players: Click-and-collect automation presents the most penetrable route into metropolitan Sydney and Melbourne, where repeat consumables orders show steepest digital adoption. Target regional Victoria and Queensland contractor relationships as whitespace with localized inventory depth. Pursue embedded energy-rating software partnerships that differentiate specification support beyond price. For Investors and Strategic Acquirers: Roll-up economics work for regional independent cooperative networks because fragmented procurement power concentrates under unified branding systems. Mid-term viability across the analysis window favors consolidators with last-mile infrastructure for bulky goods. Monitor state-level planning reform acceleration as the signal for renovation approval volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Trade Counter Professionalization | Captures licensed contractor loyalty through commercial-grade inventory and credit account structures at Bunnings and Total Tools locations. |
| Click-and-Collect Infrastructure Expansion | Metropolitan fulfillment networks absorb repeat consumables growth while protecting timber volume through physical retail anchoring. |
| Energy-Rating Embedded Services | Pre-sale disclosure compliance support differentiates specification-grade retailers from price-driven competitors under National Construction Code mandates. |
| Regional Distribution Cooperative Roll-Up | Aggregates Mitre 10 and independent merchant relationships under unified procurement systems with scale advantages. |
| Smart Home Control Module Stocking | Expands electrical and HVAC contractor relationships beyond traditional trade supplies into integrated automation retrofits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hardware retail executives, trade counter managers, contractor licensing authorities, and building code administration officials with secondary validation. Sources included Australian Bureau of Statistics construction activity data, Australian Building Codes Board amendment records, state planning commission approval databases, and customs import records for timber and power equipment. Bottom-up transaction modeling and top-down sector sizing were cross-referenced for triangulation.
Segment-weighting approaches distributed volume and value across product type, end user archetype, distribution channel, and price tier dimensions throughout the forecast period. CAGRs were derived from regression analysis against housing stock age profiles, renovation approval trajectories, and regulatory implementation timelines. Inputs incorporated National Construction Code adoption schedules, plantation harvest cycle projections, and battery platform replacement curves.
Timber supply disruption, regulatory timeline compression, and contractor channel consolidation are the dominant revision risks that could alter trajectory. Forecasts reflect documented assumptions about code enforcement intensity and import pathway stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Brazil Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
United Kingdom Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
China Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Home Improvement Market
Home Improvement and Renovation
North America Fiberglass Doors Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Double-Hung Windows Market
Home Improvement and Renovation
Home Remodeling Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Home Improvement Spending Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Automatic Curtain Market
Home Improvement and Renovation
Bays and Bows Window Market