

Luxury Wood Doors For Residential Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Wood Doors For Residential Interiors Market Insights
Specialty dealer networks is fragmenting as direct-to-builder platforms and showroom consortia capture specification flow from traditional lumberyard channels. JELD-WEN leverages multi-brand architecture to span price tiers without diluting premium positioning. Masonite International Corporation anchors its luxury portfolio through sustained investment in architectural-grade MDF-core technologies. Simpson Door Company differentiates via Craftsman-era design heritage and made-to-order sizing flexibility.
Luxury wood doors for residential interiors are engineered architectural joinery products, typically constructed from solid stile-and-rail frames with raised or flat panels, finished with species-specific veneers or solid hardwood laminates, and designed to meet precise dimensional tolerances for climate stability and acoustic performance. Panel doors occupy the dominant share of specification activity among architects, while sliding door systems represent the fastest-growing configuration as open-plan residential layouts eliminate swing-clearance requirements. Teak wood commands the highest material-tier pricing due to supply scarcity and marine-grade durability associations, though oak wood sustains broader volume through established North American and European sourcing infrastructure.
EPA TSCA Title VI governs formaldehyde emissions in composite wood components, compelling manufacturers to certify supply chains or risk exclusion from federally funded residential projects. FSC chain-of-custody certification operates as a de facto market-access filter for luxury segments, with architects increasingly writing forest-provenance requirements into specifications. Stakeholders must monitor evolving state-level embodied-carbon disclosure rules and decide whether to front-run compliance through verified lifecycle data or absorb retrofit costs as mandates proliferate.
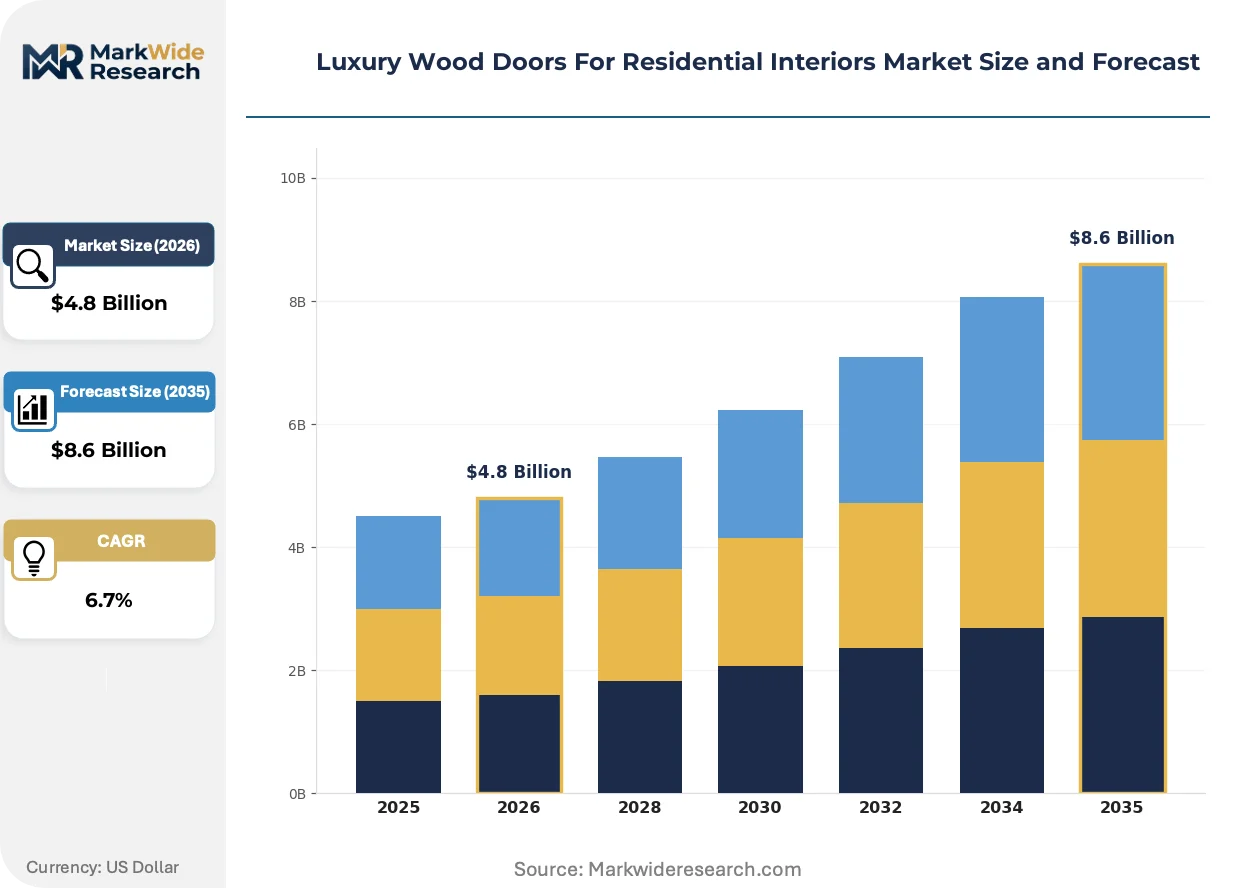
Market Dynamics
EPA TSCA Title VI compliance costs are compressing margins for composite-core door manufacturers while simultaneously creating certification-based segmentation between verified low-emission suppliers and uncertified competitors. This regulatory pressure is reshaping material sourcing, adhesive chemistry, and supply chain documentation requirements across the value chain.
Growth Catalysts
- Net-zero building mandates:California's Title 24 energy code and similar state-level decarbonization frameworks are embedding FSC-certified wood products into residential construction specifications, creating pull-through demand for verified sustainable door systems.
- Open-plan architecture proliferation:Residential designers are specifying sliding door systems at elevated rates to eliminate swing clearance in compact luxury footprints, expanding addressable square footage per project.
- Formaldehyde emission standards:TSCA Title VI certification operates as a de facto market-access filter, with compliant manufacturers capturing specification flow from federally funded housing developments and green building portfolios.
Market Restraints
- Teak supply scarcity:Myanmar logging restrictions and Indonesian export quotas have concentrated premium tropical hardwood sourcing among a shrinking pool of certified suppliers, amplifying price volatility for marine-grade veneer applications.
- Adhesive chemistry transition costs:Manufacturers face capital-intensive retooling to shift from urea-formaldehyde to soy-based or phenolic resin systems required for TSCA Title VI compliance, with payback periods extending across multiple production cycles.
- Regional mill concentration:Architectural-grade MDF-core substrate production clusters in the Pacific Northwest and upper Midwest, exposing national distributors to freight-cost inflation and weather-related supply interruptions.
Strategic Opportunities
- Smart home integration:Concealed motorized hardware and biometric entry systems are converging with traditional stile-and-rail joinery, enabling premium positioning for technology-enabled door systems in automated luxury residences.
- Direct-to-builder platforms:Digital specification tools are bypassing traditional lumberyard distribution, allowing manufacturers to capture margin and project data through integrated design-to-delivery workflows.
- Embodied-carbon disclosure readiness:Early adoption of ISO 14040-compliant lifecycle assessment documentation positions suppliers for impending state-level carbon transparency mandates in California, New York, and Washington.
Industry Challenges
- Master craftsperson scarcity:Traditional mortise-and-tenon joinery skills are aging out of the workforce faster than vocational programs can replenish qualified labor for bespoke production lines.
- Dual-certification complexity:Simultaneous pursuit of FSC chain-of-custody and TSCA Title VI compliance creates documentation burden and audit fatigue for mid-tier manufacturers with limited quality infrastructure.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Wood Doors For Residential Interiors Market Trends and Innovations
Digital fabrication and material science advances are compressing lead times for custom architectural joinery while regulatory pressure on emissions and provenance is hardening certification requirements. These forces are simultaneously expanding design possibility and raising operational barriers to market participation.
Cross-laminated timber (CLT) core technology is replacing traditional solid-wood stiles in high-performance door systems, delivering dimensional stability across humidity zones. California and Pacific Northwest architects are specifying CLT-core doors for passive house projects at accelerating rates. The technology is rendering obsolete conventional solid-core construction methods that fail to meet stringent thermal-bridge requirements in net-zero building envelopes.
EPA TSCA Title VI third-party certification is now mandatory for composite wood components in federally assisted housing, with accredited bodies conducting unannounced mill audits. Manufacturers without CARB ATCM Phase II equivalency documentation face automatic disqualification from specification pools for government-backed residential developments. The regulation most acutely affects MDF-core door producers serving the multifamily luxury segment, driving consolidation toward vertically integrated suppliers with captive certification infrastructure.
Builder procurement teams are consolidating vendor relationships around full-opening-category suppliers capable of delivering coordinated entry, interior, and patio door systems under single-source contracts. This bundling behavior is displacing specialty door-only distributors in the custom home channel. The shift is most visible in Texas and Florida markets where production homebuilders are scaling luxury product lines and demanding consolidated logistics and warranty administration.
Luxury Wood Doors For Residential Interiors Market Segmentation
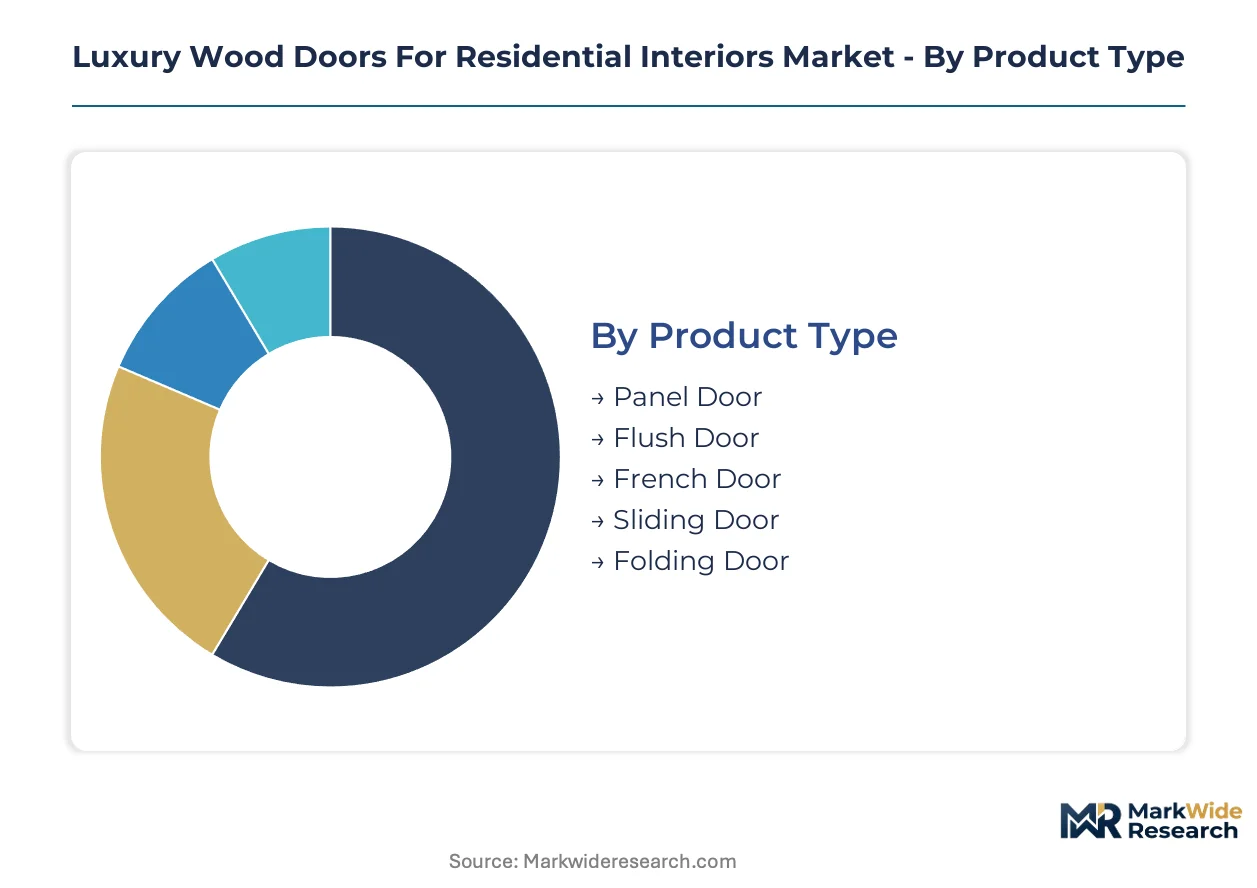
Specification patterns in luxury residential interiors diverge sharply across product configuration, material provenance, and procurement channel. Architects and builders prioritize different performance attributes than direct homeowners, creating tiered demand clusters that manufacturers must navigate through distinct certification and distribution strategies.
Product Type:
Use-case spectrum spans traditional swing configurations to space-saving sliding systems, each commanding distinct specification logic in open-plan versus compartmentalized layouts.
- Panel Door:Stile-and-rail construction with raised or flat panels dominates architect specifications for formal living zones and primary circulation paths. California and Texas custom home corridors sustain the highest specification density, driven by heritage aesthetic requirements in Mediterranean and Craftsman revival estates.
- Sliding Door:Concealed-track hardware systems eliminate swing clearance in compact luxury footprints, expanding addressable square footage per project. Florida architects specify these at elevated rates for indoor-outdoor transition zones where hurricane-rated glazing integration is mandatory.
- Flush Door:Minimalist slab construction with veneer-wrapped MDF cores serves contemporary minimalist interiors where visual quiet is prioritized.
- French Door:Paired swing leaves with divided-light glazing maintains traditional proportioning in transitional and classical residential vocabularies.
- Folding Door:Multi-panel accordion systems enable complete wall elimination for seasonal indoor-outdoor living configurations.
Established volume favors Panel Door; emerging adoption favors Sliding Door.
Material Type:
Cost tier stratification separates scarcity-driven tropical hardwoods from domestically sourced temperate species with mature certification infrastructure.
- Teak Wood:Marine-grade durability and natural oil content command the highest material-tier pricing in the segment. Myanmar logging restrictions and Indonesian export quotas have concentrated supply among certified importers serving coastal Florida estates and California wine country compounds.
- Oak Wood:White and red oak varieties sustain the broadest volume through established North American and European FSC-certified sourcing infrastructure. Texas Hill Country and Pacific Northwest architects specify quarter-sawn white oak for dimensional stability in wide-plank applications.
- Maple Wood:Fine, uniform grain accepts light stains and painted finishes for contemporary interiors requiring color consistency.
- Mahogany:Rich reddish-brown tones and workability sustain demand in traditional and colonial revival architectural vocabularies.
- Walnut:Dark chocolate coloring and dramatic grain figuring command premium positioning in mid-century modern and contemporary luxury interiors.
Volume concentration rests with Oak Wood; steepest expansion trajectory belongs to Teak Wood despite supply constraints.
Application:
Margin structure varies by installation complexity, hardware specification, and moisture-exposure risk profiles across residential zones.
- Main Entrance:Oversized single or paired units with integrated sidelights and transoms carry the highest per-unit value in the segment. Florida and California coastal markets drive specification of impact-rated and thermally broken jamb systems for energy code compliance.
- Interior Room:Standard-height passage doors constitute the volume base, with specification differentiation around acoustic ratings and concealed hinge hardware. Texas production luxury builders consolidate procurement around coordinated interior door packages with matching trim profiles.
- Closet:Bifold and bypass configurations prioritize hardware durability and panel stability over joinery refinement.
- Bathroom:Moisture-resistant core specifications and privacy locksets address humid zone performance requirements.
- Balcony:Exterior-rated jamb seals and multi-point locking hardware integrate with weatherproofing systems.
Procurement consolidation centers on Interior Room; premium margin capture concentrates in Main Entrance.
End User:
Customer type determines specification authority, with architects and interior designers controlling material-grade decisions that homeowners validate through showroom visualization.
- Architects:Specification gatekeepers for custom residential projects above defined construction value thresholds, writing FSC chain-of-custody and TSCA Title VI compliance into bid documents. California and New York practices increasingly require embodied-carbon disclosure for wood product selections.
- Interior Designers:Surface finish and hardware curation specialists who influence veneer grade and patina treatment decisions in renovation and furnishing-phase projects.
- Homeowners:Direct purchasers in renovation contexts, prioritizing showroom visualization and lead-time certainty over technical specification depth.
- Contractors:Value-engineering agents in production luxury segments, substituting specified grades with certified equivalents to maintain margin.
Specification control resides with Architects; volume throughput flows through Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California custom home corridors command 40% pricing premiums over Texas Hill Country equivalents for equivalent teak-veneer specifications, reflecting coastal scarcity premiums and stringent energy-code compliance costs that inland markets avoid.
United States
California, Texas, and Florida concentrate specification activity for bespoke entry systems, with high-net-worth homeowners commissioning oversized single units with integrated sidelights. EPA TSCA Title VI mandates formaldehyde emission certification for composite wood components in federally assisted housing. Los Angeles and Miami metropolitan clusters drive demand for impact-rated and thermally broken jamb systems.
Germany
Passive house architects specify CLT-core door systems for thermal-bridge compliance in net-zero residential envelopes. ECHA REACH regulations govern adhesive chemistry and wood preservative treatments across the value chain. Bavaria and Baden-Württemberg fabrication clusters specialize in precision-engineered stile-and-rail joinery for export markets.
China
Yangtze River Delta luxury residential developers import FSC-certified North American white oak for heritage aesthetic projects. MIIT national standards for formaldehyde emissions in wood-based panels align with export-market compliance requirements. Guangdong Province manufacturing bases supply veneer-wrapped MDF cores to Southeast Asian markets.
United Arab Emirates
Dubai and Abu Dhabi high-end residential towers specify marine-grade teak for humidity-resistant performance in coastal environments. MOHAP building product safety regulations intersect with municipality-level green building codes. Sharjah fabrication facilities serve GCC markets with customized Islamic geometric panel designs.
Canada
British Columbia and Ontario custom home builders source FSC-certified temperate hardwoods for net-zero residential projects. Health Canada PMRA regulates wood preservative treatments for interior applications. Vancouver architectural practices increasingly require embodied-carbon disclosure documentation from door system suppliers.
Luxury Wood Doors For Residential Interiors Market Competitive Landscape
Multi-brand conglomerates and specialized architectural-grade fabricators split the market between scale-driven standardization and bespoke craftsmanship capabilities. The vendor base concentrates around vertically integrated suppliers with captive certification infrastructure for TSCA Title VI and FSC chain-of-custody compliance. Three archetypes dominate: diversified building-products conglomerates, door-specialist manufacturers with heritage positioning, and regional millwork operations serving custom home corridors. Competitive moves center on direct-to-builder platform development and smart hardware integration partnerships.
Within the diversified conglomerate tier, JELD-WEN and Masonite International Corporation occupy positions spanning multiple price tiers without diluting premium positioning. Simpson Door Company and TruStile Doors exemplify the heritage-specialist archetype, with the former emphasizing Craftsman-era design lineage and the latter anchoring architectural-grade MDF-core technology investment. Woodgrain Millwork represents the integrated millwork model with captive substrate production capabilities.
| Leading Market Players |
|---|
| JELD-WEN |
| Masonite International Corporation |
| Pella Corporation |
| Simpson Door Company |
| TruStile Doors |
| Woodgrain Millwork |
| Steves and Sons |
| Bayer Built Woodworks |
| Lynden Door |
| Others |
Pricing and Supply Chain Analysis
Myanmar logging restrictions and Indonesian export quotas on premium tropical hardwoods compress supply availability for marine-grade teak while simultaneously widening price spreads between certified and uncertified veneer tiers across North American and European markets.
Pricing Analysis
Configured-to-order pricing for bespoke stile-and-rail joinery with species-specific veneer selection commands substantial premiums over standard flush-door specifications with MDF-core substrates. Price differentiation rests on FSC chain-of-custody certification tier and customization depth for dimensional tolerances and hardware integration. Cost compression in composite-core segments is intensifying because EPA TSCA Title VI compliance investments are amortizing across thinner margin bases. Production luxury builders in Texas and Florida exhibit highest price sensitivity, while California coastal architects commissioning heritage estates demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration for architectural-grade MDF-core substrates centers on Pacific Northwest and upper Midwest mill clusters, with captive veneer-wrapping operations concentrated in Guangdong Province serving Southeast Asian export markets. Geographic supply concentration spans Indonesia and Myanmar for tropical hardwoods, North America for temperate oak and maple, and China for engineered core components. Raw material dependencies include phenolic resin adhesives, tropical hardwood logs, and FSC-certified temperate lumber. Single-source vulnerability runs through Myanmar teak suppliers facing sustained export restrictions. Distribution runs through direct-to-builder platforms and consolidated full-opening-category suppliers displacing traditional lumberyard channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as specification authority fragments between architects writing certification requirements and procurement teams consolidating around bundled door system contracts, creating niche openings for specialized compliance and smart hardware capabilities.
For Market Incumbents: Insulate premium positioning through captive FSC chain-of-custody certification infrastructure that automatic disqualifies uncertified competitors from federally funded housing specifications. Deepen backward integration into CLT-core substrate production to secure thermal-bridge-compliant supply for passive house architects. Lock in long-term phenolic resin supply agreements before adhesive chemistry transitions accelerate cost inflation. For New Entrants and Emerging Players: Build out smart home integration capabilities for concealed motorized hardware and biometric entry systems, targeting the technology-enabled door segment where established joinery specialists lack embedded systems expertise. Penetrate the Florida hurricane-rated sliding door market where impact glazing integration requirements create specification complexity incumbents underinvest in. Pursue showroom consortia partnerships to bypass fragmented dealer networks. For Investors and Strategic Acquirers: EPA TSCA Title VI third-party certification mandates reshape the acquisition landscape toward vertically integrated suppliers with captive audit infrastructure rather than asset-light distributors. Long-term viability favors targets with ISO 14040-compliant lifecycle assessment documentation positioning for embodied-carbon disclosure mandates. Watch California Title 24 energy code amendments as the inflection signal for thermal-performance specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Builder Platform Development | Bypasses traditional lumberyard intermediaries, capturing margin and project specification data from Texas and Florida production luxury builders. |
| CLT-Core Technology Investment | Replaces solid-wood stile construction for passive house thermal-bridge compliance demanded by California and Pacific Northwest architects. |
| Smart Hardware Integration Partnership | Converges concealed motorized systems with traditional joinery for automated luxury residences in high-net-worth coastal markets. |
| FSC Chain-of-Custody Certification | Operates as de facto market-access filter for luxury segments with forest-provenance requirements written into architect specifications. |
| Embodied-Carbon Disclosure Readiness | Positions suppliers for impending state-level mandates in California, New York, and Washington through verified lifecycle data. |
Research Methodology
The analysis maps panel door, sliding door, flush door, and folding door configurations, each validated through primary interviews with custom home architects, production builder procurement directors, millwork fabrication plant managers, and specialty dealer network operators. Secondary validation drew from EPA TSCA Title VI certification databases, FSC chain-of-custody audit records, state energy code filings, and customs trade data for tropical hardwood imports. Bottom-up project pipeline analysis triangulated against top-down construction spending allocation models.
Assumptions held fixed include prevailing EPA formaldehyde emission standards, Myanmar logging restriction continuity, and California Title 24 energy code stringency trajectories across the projection horizon. Segmentation dimensions modeled span product configuration, material provenance tier, application zone, and end-user specification authority. CAGRs derived from regression against historical custom home permitting data and luxury residential square footage expansion patterns. Industry-specific inputs included architect specification surveys and builder procurement consolidation behavior indices.
Stress conditions across teak supply disruption severity, adhesive chemistry transition cost trajectories, and state-level embodied-carbon mandate adoption timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including trade policy volatility on tropical hardwoods and vocational training pipeline gaps for traditional joinery skills. Quarterly review of architect specification database entries, certification audit volumes, and state regulatory dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.