
 Global Backscatter X-Ray Devices Market | 2026-2036
Global Backscatter X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Backscatter X-Ray Devices Market Foresight
Software-defined threat-detection algorithms delivered through recurring firmware subscriptions is broadening revenue models beyond hardware sales. OSI Systems leverages its installed base of portal systems to sustain recurring service contracts across North American airport authorities. Nuctech Company Limited anchors its expansion in customs inspection corridors through integrated hardware-software packages. Smiths Detection competes on R&D intensity, particularly in dual-energy algorithm development for explosives trace detection.
Backscatter X-ray devices employ Compton scattering physics to generate images from reflected radiation, operating typically at 50-150 keV energy ranges with single-sided inspection geometry for penetrating clothing and surface layers of vehicles. These systems serve primary commercial purposes in security screening where transmission-based methods face physical constraints. Portal systems dominate installed value across airport checkpoint infrastructure, while handheld devices represent the fastest-expanding segment driven by law enforcement demand for portable contraband detection. Mobile units command concentrated margin pools in military and border-protection tenders requiring rapid deployment capabilities.
The FDA regulates radiation-emitting electronic product performance standards under 21 CFR Subchapter J, while the TSA mandates operational certification for aviation checkpoint deployment. The EU AI Act imposes algorithmic transparency requirements on automated threat-detection systems used in Schengen-area border crossings. China's NMPA and GB standards enforce radiation dose limits for security equipment deployed in public transit hubs. Stakeholders must monitor evolving algorithmic accountability frameworks that could reshape procurement specifications and compliance costs across multi-jurisdictional deployments.
Market Dynamics
Software-defined detection architectures are compressing hardware refresh cycles across airport and border-security procurement, forcing incumbent manufacturers to restructure revenue around firmware subscriptions and predictive maintenance contracts.
Growth Catalysts
- EU AI Act transparency mandates:Automated threat-detection systems deployed in Schengen-area crossings face new algorithmic accountability requirements, creating procurement pull for vendors with interpretable machine-learning pipelines.
- Mobile backscatter units:German federal police modernization programs prioritize rapid-deployment screening for vehicle inspections at border control points.
- Handheld device proliferation:US airport authorities are layering portable secondary-screening systems at congested checkpoint chokepoints.
Market Restraints
- Scintillator crystal supply concentration:Cadmium zinc telluride detector substrates rely on a narrow base of specialty-materials suppliers concentrated in East Asian refining corridors.
- Ionizing radiation dose thresholds:FDA 21 CFR Subchapter J certification timelines extend 18-24 months for novel energy-range configurations, freezing product pipelines.
- Millimeter-wave substitution:Active mm-wave body scanners compete for aviation checkpoint slots where transmission geometry is operationally feasible.
Strategic Opportunities
- India transit-hub modernization:Metro rail networks in Delhi, Mumbai, and Bengaluru are piloting backscatter baggage screening for high-throughput stations.
- Dual-energy algorithm convergence:Explosives trace-detection modules are integrating with backscatter imagers to reduce false-positive rates in customs inspection corridors.
- Recurring firmware monetization:Threat-signature databases delivered through subscription models capture lifetime value beyond initial hardware placement.
Industry Challenges
- Machine-learning engineering talent scarcity:Automated detection algorithm development requires rare cross-training in radiation physics and computer vision.
- Legacy portal system integration:New handheld and mobile units must interoperate with decade-old centralized screening architectures at major airport hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Backscatter X-Ray Devices Market |
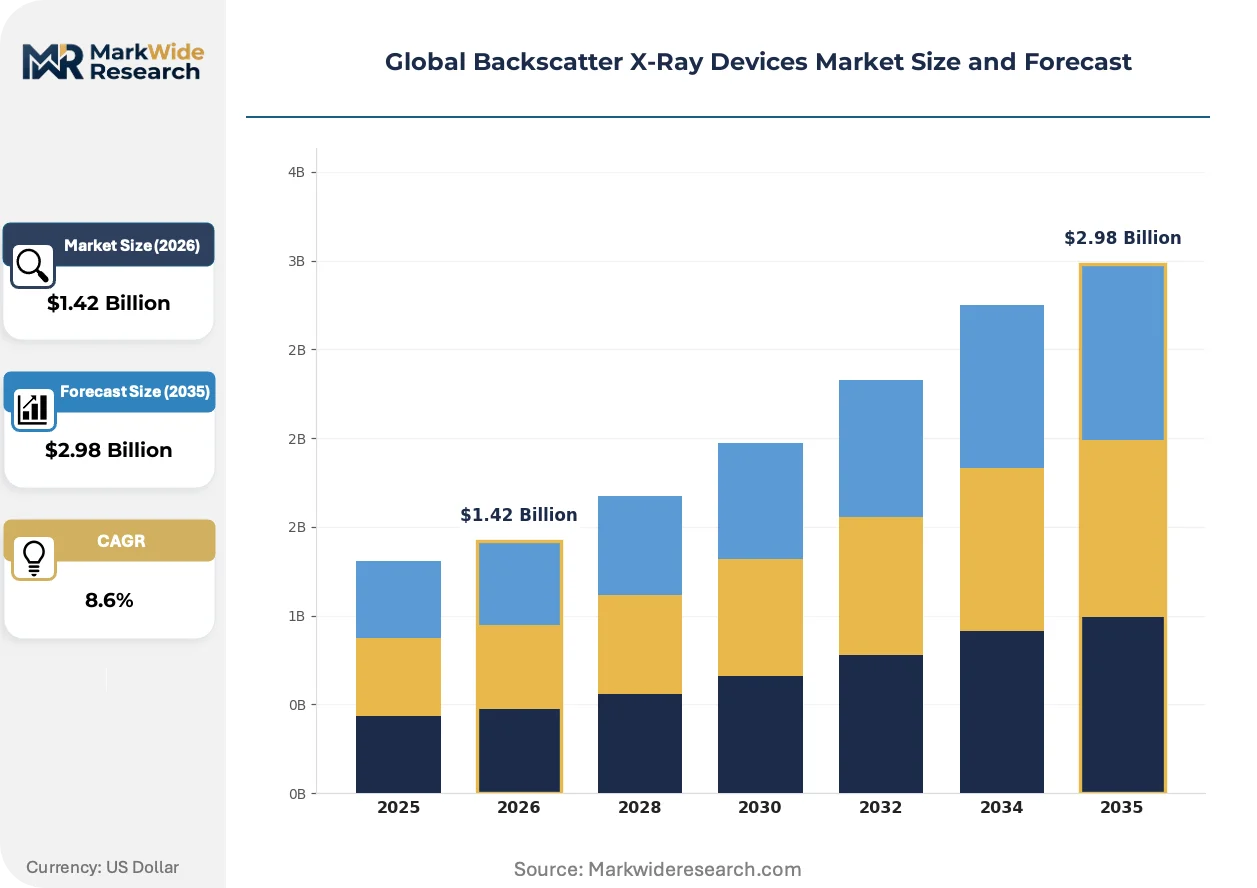
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Portal Systems, Mobile Units, Fixed Installations Technology: Backscatter, Transmission, Dual-Energy, Computed Tomography Application: Security Screening, Contraband Detection, Cargo Inspection, Event Security, Checkpoint Control End User: Airports, Ports, Law Enforcement, Customs Agencies |
| Companies Covered | OSI Systems, Tek84, Rapiscan Systems, ADANI Systems, Autoclear, Nuctech Company Limited, Viken Detection, Scanna MSC, Smiths Detection, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Backscatter X-Ray Devices Market Shifts & Advancements
Detection hardware is decoupling from proprietary software stacks, enabling modular upgrades that extend fielded system lifespans without full replacement.
Deep-learning inference engines are converging with edge-computing substrates to enable real-time threat classification without cloud connectivity. Airport authorities in the United States are piloting these architectures at secondary screening nodes. This convergence is compressing the competitive moat of vertically integrated incumbents who previously bundled hardware and algorithm IP.
China's NMPA radiation dose limits for public transit security equipment are tightening certification pathways for foreign manufacturers seeking deployment in metro and rail hubs. Domestic vendors with pre-established GB standards compliance capture accelerated approval timelines. European and North American suppliers are responding by establishing joint-venture manufacturing within Chinese regulatory jurisdiction.
Service unbundling is fragmenting traditional procurement bundles. North American airport authorities now separate hardware acquisition from algorithm licensing and maintenance obligations. This shift is most visible in TSA-coordinated procurement cycles, where multi-vendor interoperability specifications favor modular system architectures over integrated single-source contracts.
Global Backscatter X-Ray Devices Market Segmentation
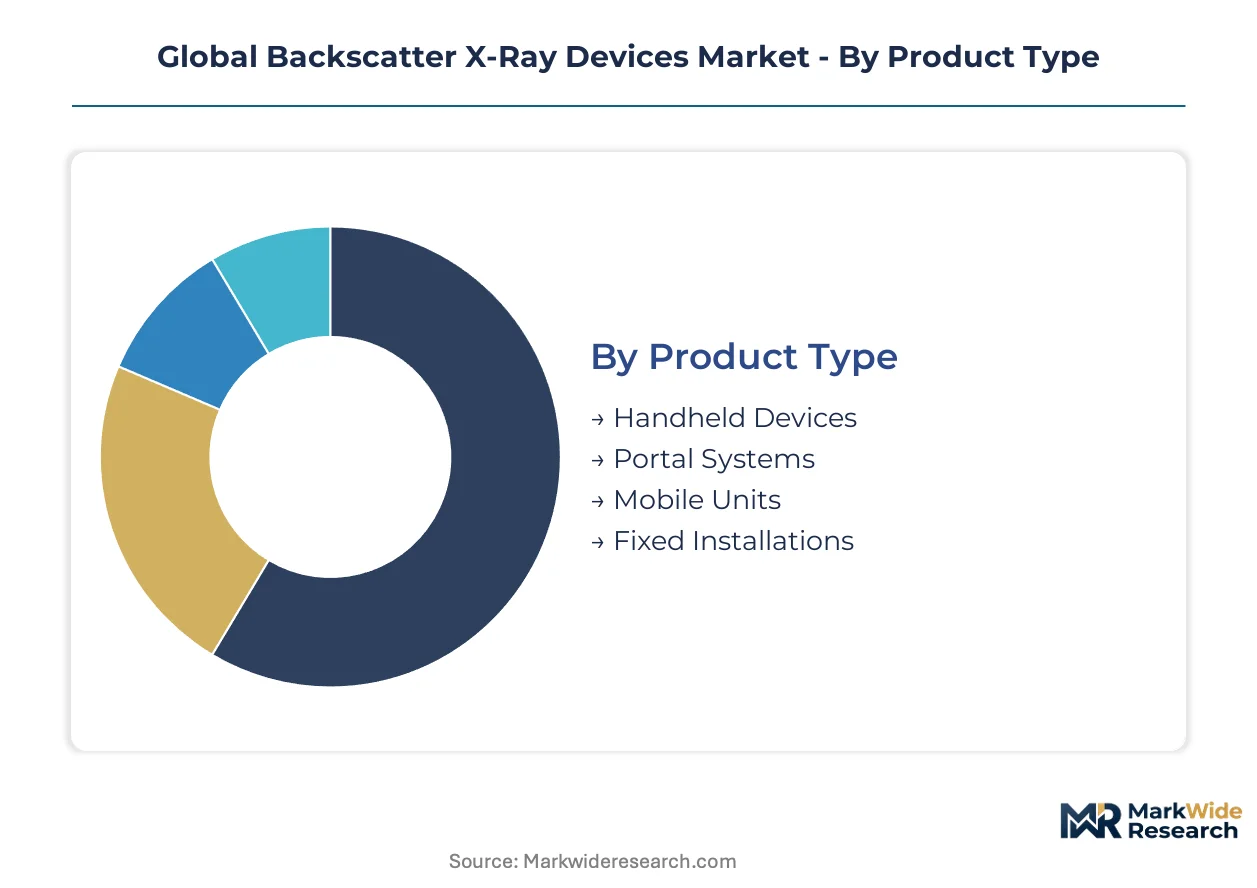
Backscatter X-ray device segmentation reveals distinct procurement patterns across security infrastructure layers. Technology differentiation and deployment mobility drive purchasing decisions more than unit economics alone.
Product Type:
Device mobility specifications determine operational use cases across checkpoint architectures.
- Handheld Devices:Portable single-sided imagers operating at reduced energy ranges enable law enforcement officers to screen vehicles and confined spaces without fixed infrastructure. US airport authorities deploy these units at secondary chokepoints to relieve congestion during peak travel periods.
- Portal Systems:Walk-through screening architectures dominate installed value across aviation checkpoints, integrating automated threat-detection algorithms with high-throughput passenger processing. German federal police specify these units for permanent border crossing installations.
- Mobile Units:Rapid-deployment platforms mounted on vehicle chassis serve military tenders and emergency response scenarios requiring relocatable screening capacity.
- Fixed Installations:Permanent cargo and vehicle inspection systems anchor customs corridors at major port facilities.
Portal systems lead on scale; handheld devices lead on momentum.
Technology:
Energy-range configurations and detection physics differentiate performance tiers across threat-detection requirements.
- Backscatter:Compton scattering-based imagers detect reflected radiation at 50-150 keV ranges, enabling single-sided inspection geometry where transmission access is impossible. Aviation security procurement favors these systems for passenger screening where physical constraints block dual-sided deployment.
- Dual-Energy:Spectral differentiation algorithms distinguish organic from inorganic materials, reducing false-positive rates in explosives trace detection. Customs agencies in Germany prioritize integrated dual-energy modules for baggage inspection corridors.
- Transmission:Conventional X-ray penetration requires opposing source-detector geometry, limiting deployment flexibility but delivering superior density resolution for cargo applications.
- Computed Tomography:Rotating gantry architectures generate volumetric reconstructions, commanding premium positioning in high-security event venues.
Backscatter technology leads on deployment breadth; dual-energy configurations lead on algorithmic sophistication.
Application:
Threat-detection objectives shape hardware specifications and integration requirements across operational environments.
- Security Screening:Passenger and baggage inspection at aviation checkpoints constitutes the dominant commercial application, with procurement cycles tied to TSA and EU regulatory frameworks.
- Contraband Detection:Law enforcement deployment focuses on intercepting narcotics and weapons concealed on persons or within vehicle compartments.
- Cargo Inspection:Port authorities employ high-penetration systems for container screening, with China's NMPA dose limits tightening certification pathways for foreign suppliers.
- Event Security:Temporary checkpoint deployment at sporting venues and political gatherings drives rental and lease revenue models.
- Checkpoint Control:Border crossing installations require interoperability with centralized threat databases and rapid alert protocols.
Security screening leads on procurement volume; contraband detection leads on portable device expansion.
End User:
Institutional procurement authority and operational jurisdiction determine specification priorities and contract structures.
- Airports:Aviation security authorities coordinate multi-vendor procurement through TSA-specified interoperability standards, unbundling hardware from algorithm licensing.
- Law Enforcement:Federal and municipal police agencies prioritize handheld mobility for warrant-based searches and traffic stop scenarios.
- Customs Agencies:Border control authorities integrate backscatter systems with legacy centralized architectures, creating retrofit compatibility requirements.
- Ports:Maritime cargo screening demands high-throughput automation to minimize vessel turnaround times.
Airports lead on installed base value; law enforcement leads on handheld procurement velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German federal police modernization programs prioritize mobile backscatter units for border control operations, while US airport authorities expand procurement of handheld screening systems for secondary checkpoint layers. These contrasting procurement patterns reflect divergent security infrastructure priorities across developed markets.
United States
Aviation security authorities deploy handheld devices at congested checkpoint chokepoints to relieve passenger processing bottlenecks. The FDA's radiation safety standards under 21 CFR Subchapter J tighten certification requirements for device manufacturers. TSA-coordinated procurement cycles in Atlanta and Dallas-Fort Worth metro hubs favor modular system architectures over integrated single-source contracts.
Germany
Federal police prioritize rapid-deployment screening for vehicle inspections at border crossing points. The EU AI Act imposes algorithmic transparency requirements on automated threat-detection systems used in Schengen-area crossings. Manufacturing clusters in Bavaria and Baden-Württemberg anchor production of high-precision detector substrates for European security equipment suppliers.
China
Metro rail networks in Beijing, Shanghai, and Shenzhen pilot backscatter baggage screening for high-throughput transit stations. The NMPA and GB standards enforce radiation dose limits for security equipment deployed in public transit hubs. Domestic vendors in the Yangtze River Delta capture accelerated approval timelines through pre-established regulatory compliance pathways.
India
Metro rail networks in Delhi, Mumbai, and Bengaluru pilot backscatter baggage screening for high-throughput stations. The Bureau of Indian Standards and Central Electricity Authority oversee radiation safety certifications for imported security electronics. Industrial corridors in Maharashtra and Karnataka host assembly operations for customs inspection equipment serving South Asian port authorities.
United Kingdom
Aviation security operators at Heathrow and Gatwick airports upgrade portal systems with firmware-subscription revenue models. The UK Information Commissioner's Office and Office for Product Safety and Standards coordinate on algorithmic accountability frameworks for automated screening. London-based security integrators unbundle hardware acquisition from algorithm licensing in procurement negotiations with airport authorities.
Global Backscatter X-Ray Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding premium positioning in airport and border-security tenders while component suppliers capture recurring revenue through detector substrate and firmware maintenance contracts. The vendor base organizes around three strategic archetypes: vertically integrated security conglomerates with established regulatory certification pipelines, specialized imaging technology firms focused on algorithm development, and regional equipment fabricators serving price-sensitive procurement channels. Consolidation pressure intensifies as software-defined detection architectures compress hardware refresh cycles, forcing incumbents to restructure around recurring service contracts and predictive maintenance obligations.
Within the integrated-system tier, OSI Systems and Smiths Detection exemplify vendors leveraging installed base relationships to sustain recurring service contracts across North American and European airport authorities. Nuctech Company Limited anchors the Asia-Pacific expansion vector through integrated hardware-software packages targeting customs inspection corridors. These three companies occupy positions that reflect divergent geographic anchoring and procurement channel specialization rather than uniform technology platforms.
| Leading Market Players |
|---|
| OSI Systems |
| Tek84 |
| Rapiscan Systems |
| ADANI Systems |
| Autoclear |
| Nuctech Company Limited |
| Viken Detection |
| Scanna MSC |
| Smiths Detection |
| Others |
Supply & Pricing Matrix
EU AI Act algorithmic transparency mandates gate both qualified supply and premium-tier pricing access, as vendors with interpretable machine-learning pipelines capture procurement preference at Schengen-area border crossings while legacy hardware manufacturers face compliance-driven margin compression.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for detector substrates, compressing margins for European and North American component suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 21 CFR Subchapter J certification tier and firmware-subscription bundling. Cost compression in the standard tier is intensifying because domestic Chinese vendors with pre-established GB standards compliance capture accelerated NMPA approval timelines. Customs agencies demonstrate the least price sensitivity due to integration complexity, while municipal law enforcement procurement shows acute sensitivity to per-unit hardware costs.
Supply Chain Analysis
Refurbishment flows for decade-old portal systems at major aviation hubs extend fielded asset lifespans, creating secondary markets for firmware-upgrade services and predictive maintenance contracts. Cadmium zinc telluride detector substrates draw from specialty-materials refining corridors concentrated in China, Japan, and South Korea. Scintillator crystal supply rests on a narrow base of East Asian suppliers, generating single-source vulnerability for European and North American system integrators. Distribution runs through security equipment integrators serving TSA-coordinated procurement cycles and federal police modernization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EU AI Act transparency mandates and FDA 21 CFR Subchapter J certification timelines driving sustained demand for compliant detection architectures.
For Market Incumbents: Anchor recurring revenue through firmware-subscription models that capture lifetime value beyond initial hardware placement. Defensive consolidation should prioritize predictive maintenance contracts for installed portal systems at Atlanta and Dallas-Fort Worth metro hubs, while certification investment in dual-energy algorithm development counters millimeter-wave substitution threats in aviation checkpoints. For New Entrants and Emerging Players: Direct-to-government sales channels bypass entrenched security equipment integrators and open procurement access at municipal law enforcement agencies. White-space targets include handheld device deployment for US airport secondary screening layers and mobile unit tenders for German federal police border control modernization. The most penetrable segment is portable contraband detection for traffic stop scenarios, where warrant-based search protocols favor rapid-deployment form factors. For Investors and Strategic Acquirers: Roll-up economics work for specialized imaging technology firms because software-defined detection architectures compress hardware refresh cycles and fragment vendor ecosystems. Long-term viability centers on algorithmic IP ownership rather than manufacturing scale. Acquisition target archetypes include computer vision startups with radiation physics cross-training capabilities. The signal to watch is TSA procurement specification shifts toward multi-vendor interoperability requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Monetization | Threat-signature databases delivered through recurring licenses capture lifetime value beyond hardware placement at North American airport authorities. |
| Dual-Energy Algorithm Development | Spectral differentiation capabilities reduce false-positive rates in German customs inspection corridors and explosives trace detection modules. |
| Joint-Venture Manufacturing Localization | Chinese regulatory jurisdiction establishment accelerates NMPA approval timelines for foreign suppliers targeting metro rail networks in Beijing and Shanghai. |
| Predictive Maintenance Contract Expansion | Service unbundling trends at TSA-coordinated procurement cycles favor modular architectures with separated hardware and algorithm licensing. |
| Edge-Computing Inference Integration | Real-time threat classification without cloud connectivity compresses competitive moats of vertically integrated incumbents at secondary screening nodes. |
Research Methodology
Direct dialogue with airport security procurement officers, federal police modernization program directors, customs agency technical specification leads, and biomedical engineers specializing in radiation safety grounded qualitative findings. Secondary validation drew from FDA 21 CFR Subchapter J filings, TSA procurement specifications, EU AI Act regulatory texts, NMPA GB standards documentation, and hospital procurement databases for security equipment. Bottom-up and top-down triangulation cross-referenced vendor shipment data with institutional procurement cycle analysis.
Bottom-up modeling segmented volume and value across handheld devices, portal systems, mobile units, and fixed installations, with technology tiers distinguishing backscatter, dual-energy, transmission, and computed tomography configurations. End-use segmentation captured airports, law enforcement, customs agencies, and ports. Across the analysis window, CAGRs derived from installed base replacement cycles, regulatory mandate implementation timelines, and firmware-subscription revenue conversion rates. Forecast inputs incorporated scintillator crystal supply constraints and machine-learning engineering talent scarcity.
The model assumes a particular technology adoption path; alternative pathways for millimeter-wave body scanner substitution would alter the outlook for backscatter portal system procurement at aviation checkpoints. Forecasts reflect assumptions about EU AI Act enforcement intensity, FDA certification timeline stability, and China's NMPA dose limit trajectory. Practitioners should monitor TSA interoperability specification drafts and German federal police tender announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
3D Sensing and Imaging Market
Imaging
Handheld Imaging Systems Market
Imaging
Virtual Reality Camera Market
Imaging
Camera Stabilizer Market
Imaging
360-Degree Camera Market
Imaging
Holographic Imaging Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Smartphone with Periscope Lens Market
Imaging
Webcam Market
Imaging
SWIR Camera Market
Imaging
North America Image Sensors Market
Imaging
Frame Grabber Market
Imaging
Micro Computed Tomography Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Global Computed Radiography Market
Imaging
Photography Equipment Market