
 Smart Haptic Devices Market | 2026-2036
Smart Haptic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Haptic Devices Market Analysis
A capital-intensity divergence between foundry-dependent and in-house actuator producers is redrawing competitive boundaries in smart haptics. Apple sustains upstream control over custom Taptic Engine design and semiconductor packaging for its device ecosystem. Immersion Corporation specializes in licensable haptic software stacks that anchor royalty revenue across Android and automotive Tier 1 suppliers. bHaptics dominates wearable haptic vest production for VR gaming through vertically integrated manufacturing in Seoul.
Smart haptic devices integrate electromechanical actuators, control algorithms, and sensory feedback loops to simulate touch sensations in digital interfaces, with actuator response times typically below 20 milliseconds for perceptual coherence. These systems serve industrial and commercial purposes ranging from surgical training simulation to driver-alert interfaces in vehicles where visual distraction poses safety risks. Wearable haptics and mobile haptics together occupy the largest value share, though tactile displays command premium pricing in medical and defense procurement channels. Ultrasonic wave technology leads R&D investment intensity, while vibration feedback retains volume dominance across consumer electronics.
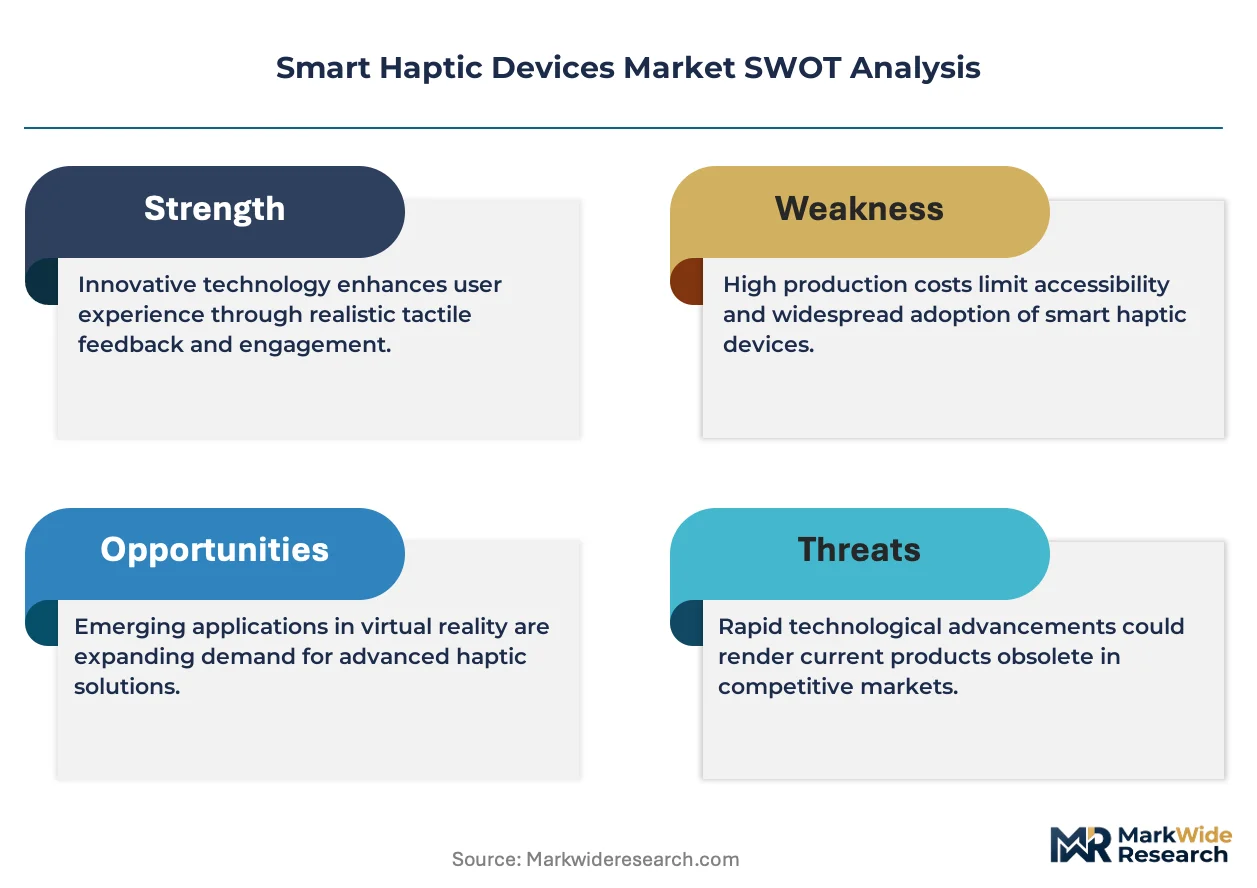
FCC equipment authorization rules in the United States govern electromagnetic emissions from haptic controllers, while the EU Green Deal and REACH chemical restrictions shape material selection for piezoelectric ceramics and conductive polymers. Japan's METI has incorporated haptic interface standards into its Society 5.0 human-machine interaction roadmap, creating compliance benchmarks for export-oriented manufacturers. Stakeholders must monitor divergence between regional electromagnetic compatibility standards and emerging medical-device classification rules for haptic surgical trainers.
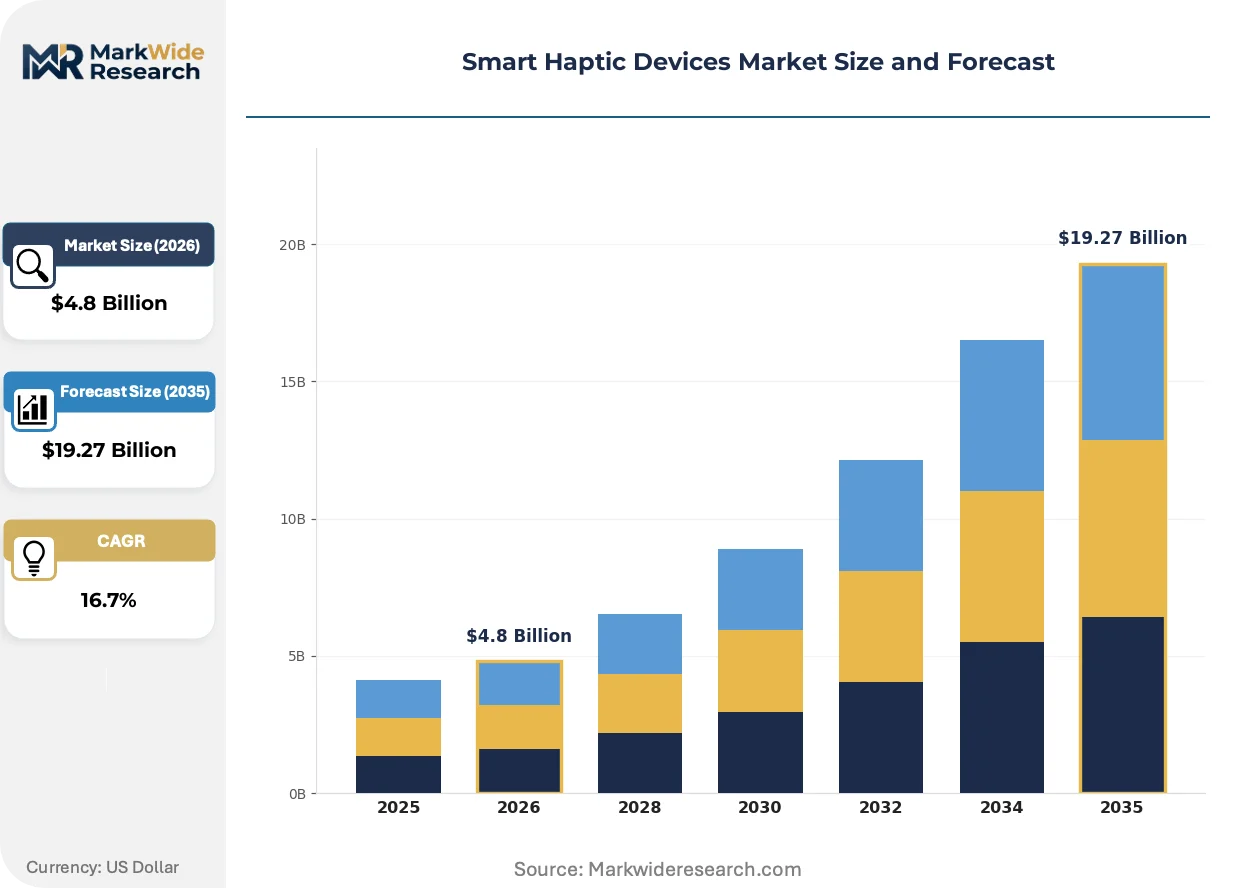
Market Dynamics
The EU AI Act's conformity requirements for biometric feedback systems are forcing automotive OEMs and consumer electronics manufacturers to redesign haptic interface architectures ahead of enforcement timelines. This regulatory pressure compounds with capital-intensity divergence between foundry-dependent and in-house actuator producers to reshape competitive boundaries.
Growth Catalysts
- Automotive cabin interface mandates:German and Japanese OEMs are expanding haptic procurement for next-generation vehicle cabins where visual distraction poses safety risks. Driver-alert interfaces now require tactile feedback loops.
- REACH chemical compliance:The EU Green Deal and REACH restrictions are accelerating material innovation in piezoelectric ceramics and conductive polymers. Suppliers investing in green chemistry capture premium positioning in medical and defense channels.
- Ultrasonic wave R&D intensity:Ultrasonic wave technology commands the highest research investment intensity among actuator types. South Korean manufacturing clusters around Seoul and Suwon concentrate fabrication capacity for next-generation tactile displays.
Market Restraints
- Piezoelectric ceramic supply concentration:Foundry-dependent producers face input cost volatility from concentrated ceramic substrate suppliers. Geographic concentration of rare earth processing creates vulnerability.
- FCC electromagnetic compatibility friction:Equipment authorization rules in the United States create certification bottlenecks for haptic controllers with wireless connectivity. Divergence with EU electromagnetic standards fragments product development roadmaps.
- Vibration feedback commoditization:Eccentric rotating mass motors face substitution pressure from linear resonant actuators and piezoelectric alternatives. Price compression in consumer electronics limits margin expansion for legacy actuator architectures.
Strategic Opportunities
- Surgical training simulation:Tactile displays command premium pricing in medical procurement channels where haptic surgical trainers face emerging device classification rules. Certification-driven demand creates defensible revenue pools.
- Japan Society 5.0 alignment:METI's human-machine interaction roadmap incorporates haptic interface standards for export-oriented manufacturers. Compliance with JIS benchmarks opens public procurement and healthcare verticals.
- Wearable VR haptic vests:Vertically integrated production in Seoul enables rapid iteration cycles for gaming peripherals. Direct-to-consumer channels bypass traditional electronics distribution markups.
Industry Challenges
- Multi-physics simulation talent scarcity:Electromechanical actuator design requires rare cross-disciplinary expertise spanning materials science, control algorithms, and perceptual psychology. Universities produce insufficient graduates with integrated haptics training.
- Legacy automotive integration complexity:Tier 1 suppliers struggle to embed haptic feedback into existing vehicle electrical architectures without redesigning power distribution and software stacks. Retrofit compatibility demands extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Haptic Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Haptics, Mobile Haptics, Tactile Displays, Controllers Technology: Vibration Feedback, Electrical Stimulation, Piezoelectric Actuation, Ultrasonic Waves End User: Gaming, Healthcare, Military, Automotive Application: Virtual Reality, Telecommunication, Robotics, Education |
| Companies Covered | Haptic Dynamics, Ultraleap, Apple, Nuance Communications, Immersion Corporation, Meta, bHaptics, Wearable Devices Inc., Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Haptic Devices Market Emerging Trajectories
Actuator architectures are fragmenting into specialized designs optimized for specific latency, force, and power constraints rather than universal platforms. This specialization is decomposing the market into distinct technology strata with diverging investment requirements.
Ultrasonic phased-array tactile surface technology is decomposing the dominance of mechanical vibration systems in high-fidelity applications. Medical device manufacturers and automotive designers are adopting ultrasonic wave approaches for sub-20-millisecond response coherence. The technology is decomposing traditional foundry business models by requiring custom semiconductor packaging capabilities that captive producers control.
The EU AI Act's risk-based classification for biometric feedback systems is tightening conformity assessment procedures for haptic devices with sensory data processing. Industrial consequence includes mandatory third-party auditing and documentation burdens for manufacturers serving European automotive and healthcare verticals. German automotive suppliers and French medical device firms are responding by consolidating regulatory affairs functions and pre-certifying component platforms.
Buyer concentration among South Korean consumer electronics contract manufacturers is compressing component negotiation cycles and demanding vendor-managed inventory arrangements. Tier 2 actuator suppliers face working capital strain from extended payment terms and forecast volatility. This procurement pressure is most visible in the Seoul-Suwon manufacturing corridor where Samsung and LG ecosystem vendors dominate haptic component sourcing.
Smart Haptic Devices Market Segmentation
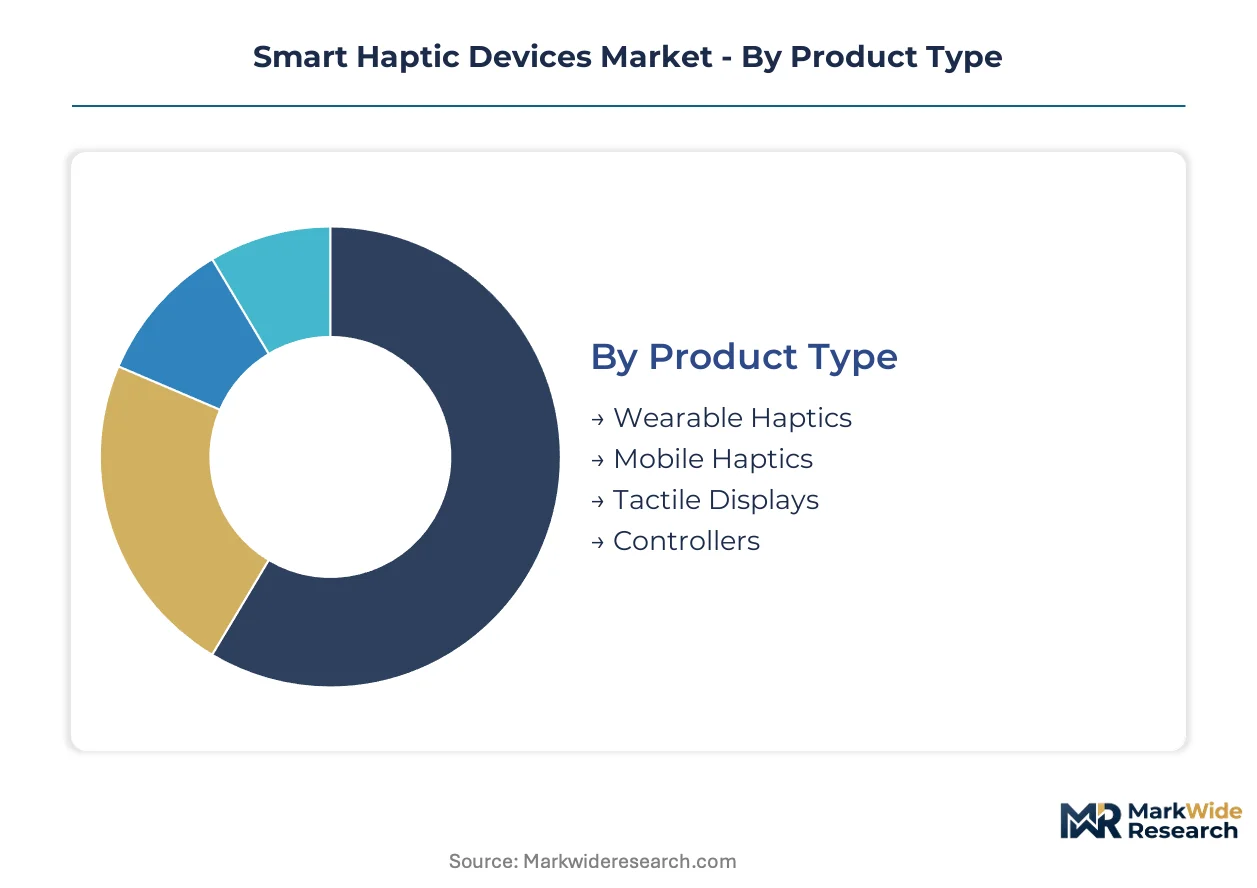
Haptic device architectures diverge sharply across product categories, with premium margin pools concentrating in specialized medical and defense applications while consumer electronics drives volume scale. Technology selection and end-user vertical together determine pricing power, certification burden, and supply chain configuration.
Product Type:
Margin pools concentrate in tactile displays for medical and defense procurement, where certification requirements create pricing insulation, while wearable haptics and mobile haptics compete on manufacturing efficiency at scale.
- Wearable Haptics:Integrated electromechanical systems deliver full-body tactile feedback through vests, gloves, and suits. Demand clusters in Seoul's VR gaming manufacturing corridor where bHaptics maintains vertically integrated production. Direct-to-consumer distribution bypasses traditional electronics retail markups.
- Mobile Haptics:Compact actuator modules embedded in smartphones and tablets simulate texture and pressure through localized vibration. Apple controls upstream design of custom Taptic Engines for its device ecosystem, while Android OEMs license software stacks from specialized vendors.
- Tactile Displays:High-density actuator arrays render surface textures and 3D shapes for surgical training and automotive interfaces. Premium pricing in medical procurement channels reflects emerging device classification rules and extended certification timelines.
- Controllers:Handheld input devices with integrated haptic feedback for gaming and industrial teleoperation. FCC equipment authorization rules in the United States create certification bottlenecks for wireless-enabled variants.
Wearable haptics holds installed capacity through Seoul-Suwon manufacturing concentration. Tactile displays is rotating up the share rankings on medical and automotive procurement expansion.
Technology:
Cost tier stratification separates commodity vibration motors from precision ultrasonic systems requiring custom semiconductor packaging capabilities.
- Vibration Feedback:Eccentric rotating mass and linear resonant actuators dominate consumer electronics volume through mature manufacturing economics. Price compression limits margin expansion as piezoelectric alternatives gain technical ground.
- Ultrasonic Waves:Phased-array tactile surfaces achieve sub-20-millisecond response coherence for high-fidelity medical and automotive applications. South Korean R&D investment intensity concentrates fabrication capacity in Seoul and Suwon for next-generation displays.
- Piezoelectric Actuation:Ceramic-based precision positioning systems enable fine-grain texture rendering in surgical interfaces. EU REACH chemical restrictions and the Green Deal accelerate material innovation in substrate formulations.
- Electrical Stimulation:Direct nerve activation through electrode arrays for prosthetic feedback and rehabilitation devices. Regulatory classification uncertainty under FDA and EMA frameworks constrains commercial deployment velocity.
Vibration feedback holds installed capacity across billions of consumer devices. Ultrasonic waves is rotating up the share rankings on medical and automotive design adoption.
End User:
Application maturity varies dramatically, with automotive cabin interfaces and surgical simulation commanding development priority while gaming sustains volume throughput.
- Gaming:VR peripherals and controller haptics represent the largest addressable volume pool. Seoul-based manufacturing clusters serve global demand through contract electronics assemblers with vendor-managed inventory arrangements.
- Automotive:Driver-alert interfaces in German and Japanese OEM next-generation cabins require tactile feedback loops where visual distraction poses safety risks. EU AI Act conformity requirements force architectural redesign ahead of enforcement timelines.
- Healthcare:Haptic surgical trainers face emerging medical-device classification rules that create defensible revenue pools through certification-driven demand. Tactile displays command premium pricing in this procurement channel.
- Military:Training simulation and teleoperation systems for remote vehicle and drone control. Defense procurement channels tolerate extended development cycles for hardened specifications.
Gaming holds installed capacity through consumer electronics scale. Healthcare is rotating up the share rankings on certification-premium capture and surgical simulation adoption.
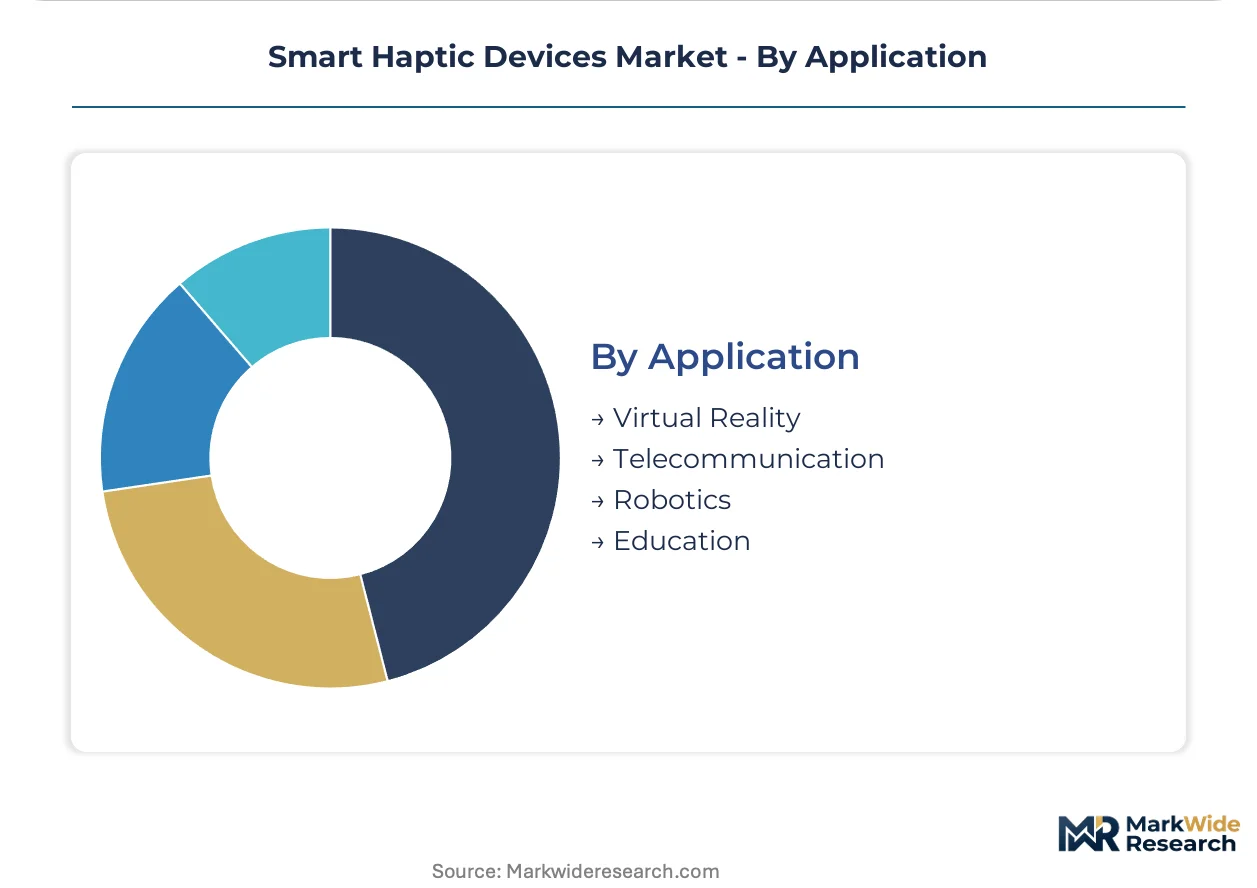
Application:
Customer type differentiation separates enterprise procurement with extended validation cycles from consumer markets demanding rapid iteration.
- Virtual Reality:Immersive environment rendering requires low-latency full-body haptic feedback for presence maintenance. Wearable vest systems from Seoul manufacturers anchor hardware supply.
- Robotics:Teleoperation and collaborative robot interfaces depend on force-feedback precision for safe human-machine interaction. Japan's METI Society 5.0 roadmap incorporates haptic standards for export-oriented manufacturers.
- Telecommunication:Remote tactile communication systems remain technically constrained by bandwidth and latency requirements. Commercial deployment lags technical demonstration.
- Education:STEM training and vocational simulation adopt haptic interfaces for skill acquisition without physical material consumption. Procurement cycles extend through institutional budget processes.
Virtual reality holds installed capacity through gaming and entertainment deployment. Robotics is rotating up the share rankings on industrial automation and teleoperation demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where automotive OEMs command premium haptic interfaces, while South Korean manufacturers compete on volume scale through Seoul-Suwon production clusters. This asymmetry shapes procurement patterns across the analysis window.
Germany
Automotive cabin interface mandates from BMW, Mercedes-Benz, and Volkswagen drive haptic procurement for next-generation vehicle cabins. The EU AI Act's conformity requirements for biometric feedback systems force architectural redesign ahead of enforcement timelines. Bavaria's Munich-Stuttgart corridor hosts Tier 1 suppliers consolidating regulatory affairs functions.
Japan
Driver-alert interface demand from Toyota, Honda, and Nissan prioritizes tactile feedback loops where visual distraction poses safety risks. METI's Society 5.0 roadmap incorporates JIS haptic interface standards for export-oriented manufacturers. Kanto's Tokyo-Yokohama cluster concentrates electromechanical actuator R&D facilities.
South Korea
Wearable haptics demand from Samsung and LG Electronics concentrates procurement in the Seoul-Suwon manufacturing corridor. The country's national semiconductor regulator shapes electromagnetic compatibility certification for wireless-enabled controllers. Suwon's vertically integrated production enables rapid iteration cycles for VR gaming peripherals.
United States
Medical device classification uncertainty under FDA frameworks constrains haptic surgical trainer deployment velocity. FCC equipment authorization rules create certification bottlenecks for haptic controllers with wireless connectivity. California's Bay Area clusters software stack developers for licensable haptic platforms.
China
Consumer electronics manufacturing scale in the Yangtze River Delta and Pearl River Delta drives vibration feedback motor demand. MIIT's GB standards for electromagnetic emissions shape product development roadmaps for export-bound manufacturers. Shenzhen's electronics assemblers face margin compression from Korean vendor-managed inventory arrangements.
Smart Haptic Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure with limited overlap. The vendor base separates into captive ecosystem producers, licensable software specialists, and vertically integrated hardware fabricators. Three strategic archetypes dominate: upstream-controlled device integrators, royalty-dependent IP licensors, and manufacturing-scale peripheral specialists. Competitive moves concentrate on backward integration into semiconductor packaging and pre-certification of component platforms for regulatory compliance.
Within the captive ecosystem tier, Apple exemplifies upstream control through custom actuator design and in-house semiconductor packaging. Among licensable software specialists, Immersion Corporation occupies a position anchoring royalty revenue across Android and automotive supply chains. At the vertically integrated end, bHaptics represents manufacturing-scale concentration through Seoul-based production of wearable haptic systems.
| Leading Market Players |
|---|
| Haptic Dynamics |
| Ultraleap |
| Apple |
| Nuance Communications |
| Immersion Corporation |
| Meta |
| bHaptics |
| Wearable Devices Inc. |
| Sony |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for piezoelectric ceramic substrates concentrate pricing power with Seoul-Suwon foundry operators while compressing margins for foundry-dependent actuator producers in Shenzhen and Taiwan. This inventory banding reinforces the divergence between captive in-house production and outsourced component sourcing across the smart haptics value chain.
Pricing Analysis
Customization-premium spreads separate standard vibration motor modules from configured-to-order tactile displays for surgical training systems. Three-tier pricing structure across medical-grade, automotive-qualified, and consumer electronics tiers reflects certification burden and response latency specifications. Cost compression in eccentric rotating mass motors stems from Korean vendor-managed inventory arrangements demanding extended payment terms. Consumer electronics OEMs exhibit highest price sensitivity, while defense procurement channels tolerate premium positioning for hardened specifications.
Supply Chain Analysis
Inventory-to-sales ratios at Seoul-Suwon contract manufacturers signal supply concentration across South Korea, Japan, and Germany for precision actuator fabrication. Piezoelectric ceramic substrates, rare earth processing, and custom semiconductor packaging draw from geographically concentrated upstream tiers. Single-source vulnerability in ceramic substrate supply creates exposure to REACH chemical restriction enforcement. Distribution runs through Tier 1 automotive suppliers and direct-to-consumer gaming peripheral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuator architecture fragmentation creates white-space opportunities as ultrasonic wave R&D intensity splits demand between precision medical applications and commoditized consumer vibration feedback. Surgical simulation procurement expansion generates niche entry points for specialized tactile display developers.
For Market Incumbents: Compound regulatory affairs consolidation by pre-certifying component platforms for EU AI Act conformity assessment ahead of enforcement timelines. Deepen backward integration into semiconductor packaging capabilities to defend margin position against ultrasonic phased-array entrants. Capture premium positioning in medical procurement channels where emerging device classification rules extend certification timelines and insulate pricing.
For New Entrants and Emerging Players: Lead with haptic surgical trainer specialization targeting FDA and EMA classification uncertainty gaps that constrain incumbent deployment velocity. Exploit underpenetrated teleoperation interfaces for collaborative robotics where Japan's METI Society 5.0 standards create compliance benchmarks. Pursue hospital system partnerships and GPO contracts as primary go-to-market mechanism bypassing consumer electronics distribution markups.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive Tier 1 suppliers divesting non-core haptic interface divisions amid legacy electrical architecture integration complexity. Long-term viability centers on software stack licensability and captive semiconductor packaging capabilities rather than discrete actuator manufacturing scale. Monitor FDA medical device classification rulemaking velocity as inflection signal for surgical simulation revenue pool accessibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certification of Component Platforms | EU AI Act conformity investment defends automotive and healthcare vertical access against audit burden fragmentation. |
| Backward Integration into Semiconductor Packaging | Captive packaging capabilities capture ultrasonic phased-array value migrating from mechanical vibration systems. |
| Surgical Simulation Partnership Development | Hospital system relationships establish defensible revenue pools amid emerging FDA classification rulemaking. |
| Direct-to-Consumer Channel Establishment | VR gaming peripheral sales bypass traditional electronics retail markups concentrated in Seoul manufacturing. |
| Regulatory Affairs Function Consolidation | Centralized compliance management reduces EU AI Act and REACH restriction adaptation costs across product lines. |
Methodological Framework
Desk research of customs trade databases, SEC semiconductor capex disclosures, and FDA medical device classification dockets preceded structured interviews with automotive Tier 1 supplier procurement leads, haptic software stack developers, and hospital biomedical engineering directors. Primary fieldwork with Seoul-Suwon contract manufacturing executives and German automotive platform engineers combined with secondary validation through ECHA REACH restriction filings and METI Society 5.0 roadmap documentation. Bottom-up actuator shipment aggregation and top-down OEM procurement budget analysis provided cross-verification.
Variance decomposition across technology type, end-user vertical, and geographic production cluster shaped the analytical framework over the projection horizon. Modeled segmentation spanned actuator architecture, certification grade, and regional regulatory environment. CAGRs derived from shipment volume trajectories and average selling price evolution by tier. Industry-specific inputs included piezoelectric ceramic supply concentration indices and automotive OEM haptic content-per-vehicle estimates.
Underlying assumptions cover sustained REACH chemical compliance cost pass-through and stable rare earth processing capacity, with deviation risk concentrated in FDA medical device reclassification and FCC electromagnetic compatibility rule divergence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Force Sensor Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Asia-Pacific Touch Sensor Market