
 Acoustic Sensors Market | 2026-2036
Acoustic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Sensors Market Intelligence
The performance gap between high-fidelity piezoelectric sensors and commodity-grade microphone sensors is realigning competitive dynamics. Murata Manufacturing Co., Ltd. specializes in miniaturized MEMS-based components for consumer electronics. Siemens AG leverages its industrial automation expertise to integrate acoustic sensors into factory diagnostics. Honeywell International Inc. positions its solutions for aerospace and structural health monitoring applications.
An acoustic sensor is a device that converts sound waves, or acoustic energy, into an electrical signal. These sensors operate across specific frequency ranges, from audible sound to high-frequency ultrasound, to detect pressure variations. Within product types, ultrasonic sensors command a significant share due to their use in automotive and industrial applications. The application segment for structural health monitoring represents the fastest-growing area, driven by infrastructure safety mandates.
Product design is shaped by multiple regulatory frameworks, including the US NHTSA's standards for vehicle safety systems and the EU's CE marking requirements for electronic devices. Concurrently, industrial workplace safety rules from bodies like OSHA in the United States influence the deployment of acoustic monitoring for machinery. Vendor success will hinge on navigating the disparate compliance pathways for consumer, industrial, and military end-user markets.
Market Dynamics
The acoustic sensors market is defined by the performance-cost trade-off between high-fidelity piezoelectric sensors and mass-market MEMS microphones. This dynamic forces vendors to specialize, either pursuing high-margin industrial and aerospace applications or high-volume consumer electronics integration.
Growth Catalysts
- Industrial IoT Integration:The adoption of predictive maintenance strategies within Industry 4.0 frameworks, particularly in Germany's automotive and machinery sectors, requires continuous acoustic monitoring to detect equipment anomalies and prevent unplanned downtime.
- Automotive Safety Mandates:Regulations from bodies like the US NHTSA for occupant detection and emergency call (eCall) systems in vehicles necessitate the integration of sophisticated in-cabin acoustic sensors for sound and voice recognition.
- MEMS Technology Advancement:Ongoing miniaturization and cost reduction of MEMS-based sensors enable their incorporation into a wider range of consumer electronics, including smart speakers, wearables, and hearables, expanding the total addressable market.
Market Restraints
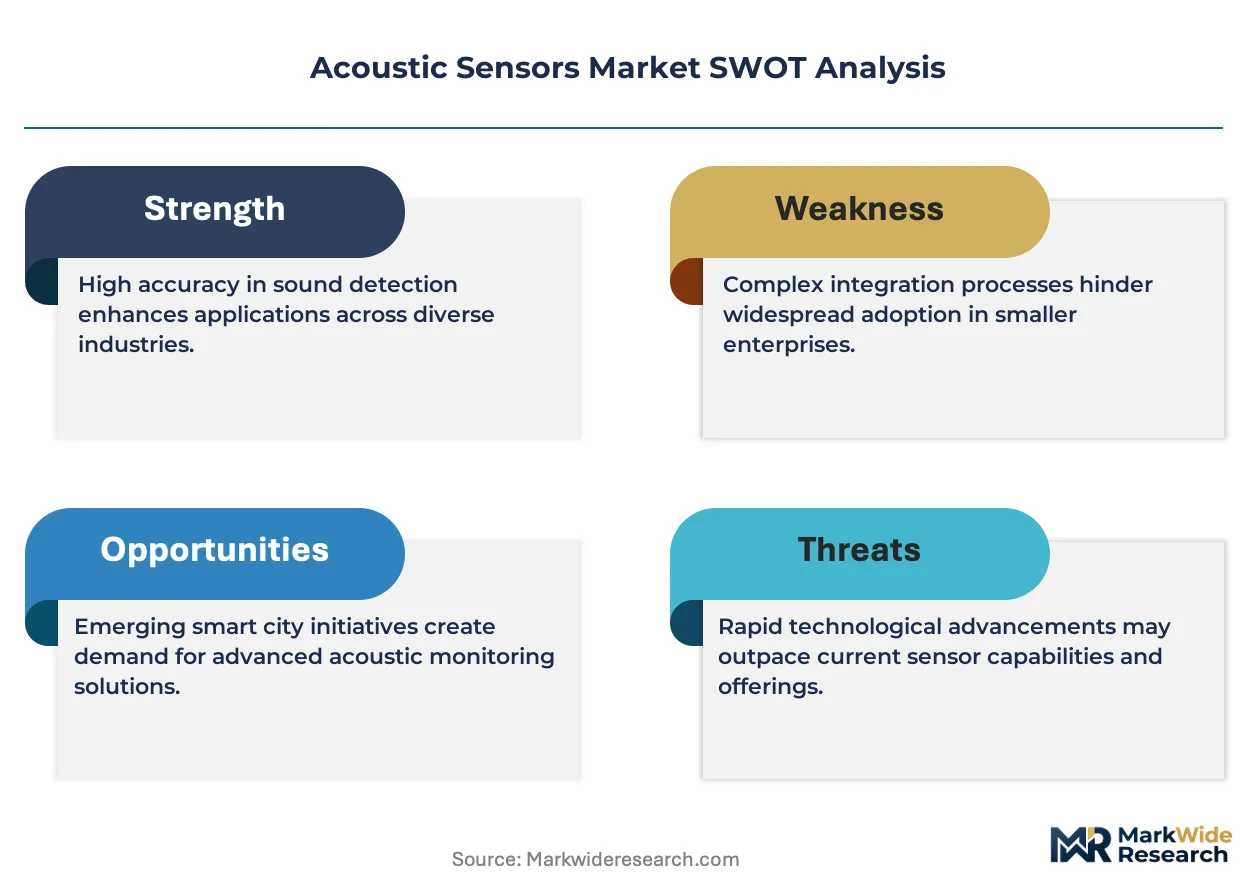
- Signal Processing Complexity:Extracting actionable insights from acoustic data requires significant onboard processing power and sophisticated algorithms, which increases the cost and design complexity of end-devices and can deter adoption in price-sensitive applications.
- Substitution by Alternative Sensors:In basic applications like proximity sensing or object detection, lower-cost technologies such as infrared (IR) or capacitive sensors present a persistent substitution threat to ultrasonic acoustic sensors.
- Piezoelectric Material Constraints:The supply of specialized ceramic materials essential for high-performance piezoelectric sensors is concentrated among a few suppliers, creating potential for supply chain bottlenecks and input cost volatility for manufacturers.
Strategic Opportunities
- Structural Health Monitoring:Aging public infrastructure in North America and Europe creates a significant opportunity for ultrasonic sensors in the continuous monitoring of bridges, tunnels, and buildings to ensure structural integrity and public safety.
- Non-Invasive Medical Diagnostics:The convergence of high-frequency ultrasound sensors with AI-powered analytics opens new frontiers in point-of-care and wearable medical devices for applications like respiratory monitoring or blood flow analysis.
- Precision Agriculture Applications:Underpenetrated use cases in smart farming, such as using acoustic sensors to monitor livestock respiratory health or to detect pest infestations in crops, offer a new growth vector for specialized vendors.
Industry Challenges
- Navigating Disparate Compliance:Vendors face complex and time-consuming certification processes that vary widely across end-markets, including CE marking for European consumer goods, AEC-Q100 for automotive, and stringent military specifications.
- Data Interpretation Skill Gaps:A shortage of data scientists and acoustic engineers capable of developing and interpreting the complex algorithms needed for diagnostics limits the effective deployment and value extraction from sensor systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Sensors Market |
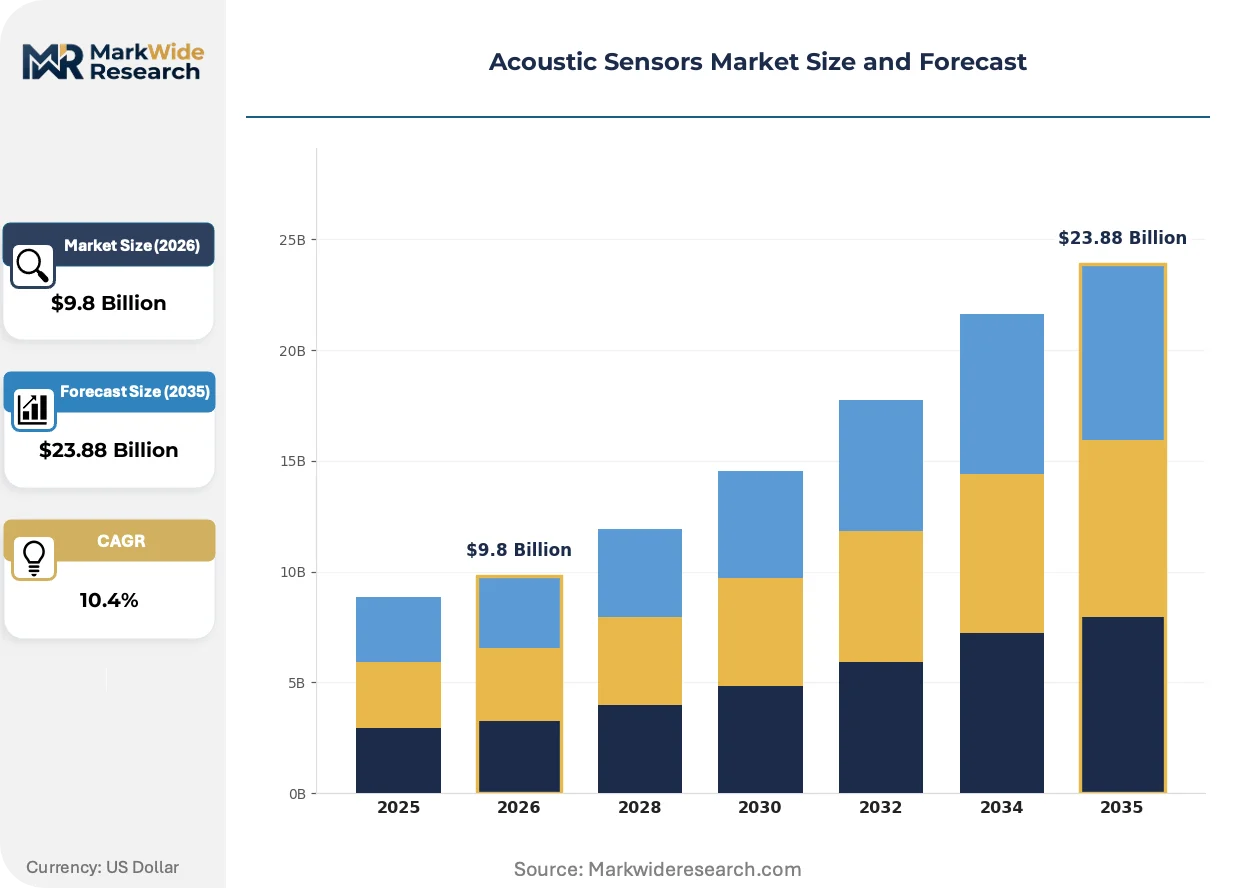
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $23.88 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphone Sensor, Ultrasonic Sensor, Piezoelectric Sensor, Capacitive Sensor, Resonant Sensor Technology: MEMS, Fiber Optic, Laser Doppler, Surface Acoustic Wave, Piezoelectric Effect Application: Structural Health Monitoring, Military Surveillance, Consumer Electronics, Industrial Machinery Diagnostics, Underwater Exploration End User: OEMs, Defense Agencies, Electronic Device Manufacturers, Research Laboratories, Marine Equipment Providers |
| Companies Covered | Honeywell International Inc., Siemens AG, Murata Manufacturing Co., Ltd., Panasonic Corporation, KYOCERA Corporation, Transense Technologies PLC, AVX Corp., Boston Piezo-Optics Inc., Microchip Technology Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Sensors Market Strategic Shifts & Innovations
The market's evolution is driven by the fusion of sensor hardware with advanced software and artificial intelligence. This combination is transforming acoustic sensors from simple data collectors into sophisticated tools for complex pattern recognition and autonomous decision-making across industries.
Edge AI integration is a defining product evolution. This involves embedding processing capabilities directly onto the sensor or a nearby microcontroller to analyze sound data locally, reducing latency and reliance on cloud infrastructure. Industrial automation and smart home device manufacturers are adopting this approach to enable real-time responses. This trend is decentralizing analytical intelligence away from centralized servers to the network edge, empowering devices with greater autonomy.
Regulatory frameworks for occupational health are tightening, creating new compliance-driven demand. The EU's Machinery Regulation and directives from the US Occupational Safety and Health Administration (OSHA) impose stricter requirements for noise exposure monitoring and machinery health assessment. This compels operators in heavy industry and manufacturing to deploy continuous acoustic monitoring systems. The energy, mining, and transportation sectors are most affected, accelerating investment in sensor networks.
A notable behavioral shift sees customers procuring complete solutions rather than discrete components. This model favors system integrators and specialized service providers who bundle sensor hardware with analytical software and ongoing support, displacing traditional component distributors. This integrated approach is most visible in complex fields like industrial predictive maintenance and infrastructure monitoring, where deep domain expertise is crucial for interpreting the acoustic data.
Acoustic Sensors Market Segmentation
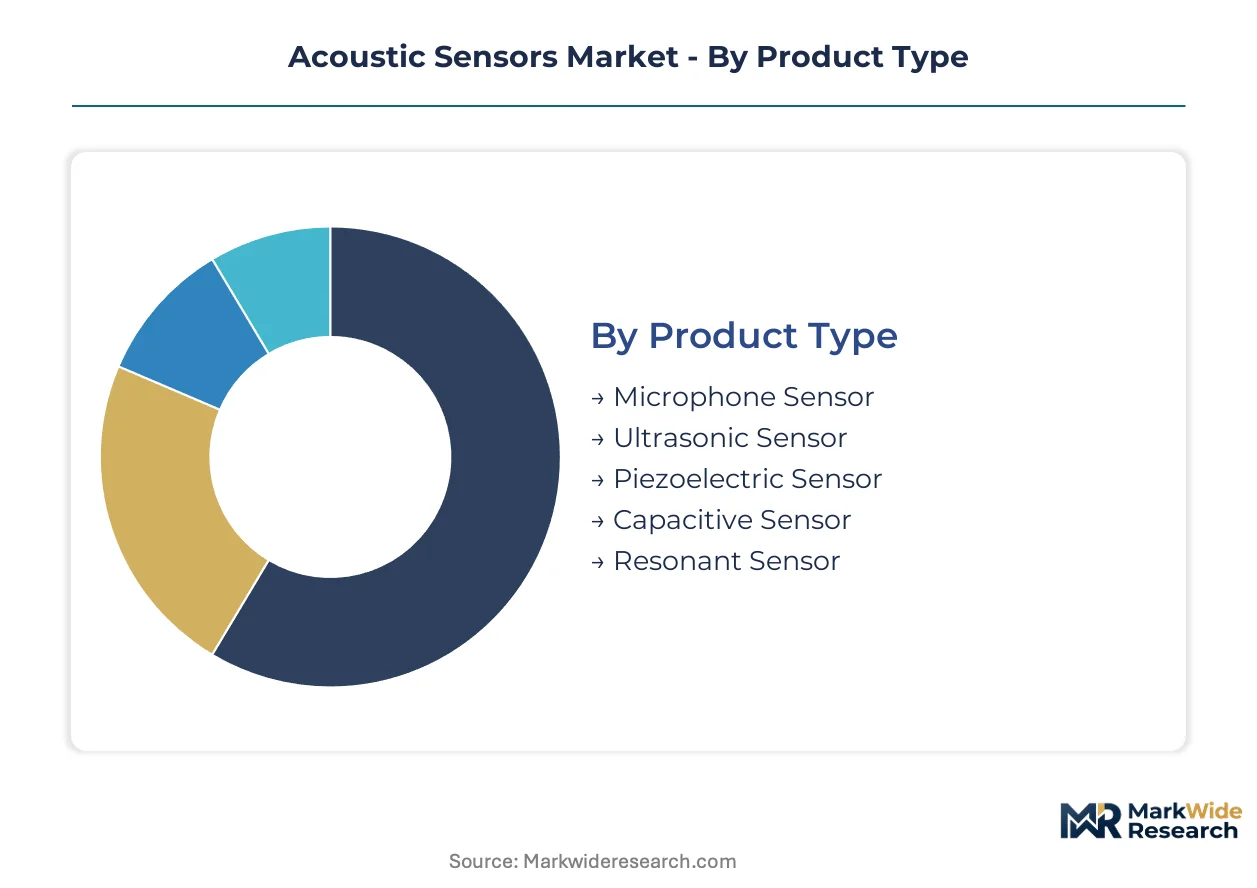
Acoustic sensor market segmentation reveals critical distinctions in product design, technological underpinnings, and target applications. Understanding these categories is essential for comprehending the varied competitive landscapes and strategic imperatives across different market niches. Each segment addresses specific user needs.
Product Type:
The integration depth of acoustic sensors varies significantly across product types, ranging from standalone detection units to highly embedded components.
- Ultrasonic Sensor:These sensors emit and receive high-frequency sound waves to detect objects, measure distances, or identify material flaws. Demand for ultrasonic sensors concentrates heavily within automotive manufacturing for parking assistance and industrial settings for process control.
- Piezoelectric Sensor:Utilizing the piezoelectric effect, these sensors convert mechanical stress from sound waves into electrical signals with high fidelity. Adoption is strong in industrial machinery diagnostics for predictive maintenance and in aerospace for structural health monitoring.
- Microphone Sensor:These commodity-grade sensors convert audible sound into electrical signals, seeing widespread use in consumer electronics for voice interfaces.
- Capacitive Sensor:Capacitive acoustic sensors detect sound pressure variations through changes in capacitance, finding niche applications in high-precision measurement.
- Resonant Sensor:Resonant acoustic sensors operate by detecting shifts in their resonant frequency due to external acoustic stimuli, often employed in specialized industrial sensing.
Ultrasonic Sensors leads volumes today; Piezoelectric Sensors is gaining share fastest.
Technology:
Technology segmentation highlights the diverse physical principles underpinning acoustic sensing, each offering distinct performance characteristics and cost profiles.
- MEMS:Micro-Electro-Mechanical Systems (MEMS) technology enables the miniaturization of acoustic sensors, integrating mechanical and electrical components on a single chip. This technology is critical for consumer electronics, including smart speakers and wearables, due to its small form factor and cost-effectiveness.
- Piezoelectric Effect:This technology relies on materials that generate an electric charge when subjected to mechanical stress or vibration from sound waves. Piezoelectric effect sensors are favored in high-precision industrial applications and structural integrity monitoring due to their sensitivity and reliability.
- Fiber Optic:Fiber optic acoustic sensors detect sound-induced strain on optical fibers, offering immunity to electromagnetic interference in harsh environments.
- Laser Doppler:Laser Doppler technology measures sound waves by detecting frequency shifts in reflected laser light, used for non-contact vibration analysis.
- Surface Acoustic Wave:Surface Acoustic Wave (SAW) technology utilizes acoustic waves propagating on a solid surface, finding applications in chemical and biological sensing.
MEMS technology commands the largest volume; Fiber Optic solutions are demonstrating rapid growth.
Application:
Application segments delineate the specific end-use cases for acoustic sensors, revealing where the most significant growth potential and regulatory drivers exist.
- Structural Health Monitoring:This application involves using acoustic sensors to continuously assess the integrity and safety of physical structures like bridges, buildings, and pipelines. Infrastructure safety mandates in Europe and North America drive demand for these systems, ensuring public safety.
- Industrial Machinery Diagnostics:Acoustic sensors are deployed here to monitor the operational health of industrial equipment, detecting anomalies indicative of impending failure. Industry 4.0 initiatives in Germany and other manufacturing hubs fuel the adoption of these sensors for predictive maintenance.
- Military Surveillance:Acoustic sensors provide passive detection and tracking capabilities for military and defense operations, enhancing situational awareness.
- Consumer Electronics:This segment integrates acoustic sensors into devices like smartphones, smart speakers, and wearables for voice control and sound detection.
- Underwater Exploration:Acoustic sensors are essential for sonar systems and hydrophones in marine research and oil and gas exploration, mapping the subsea environment.
Consumer Electronics applications currently hold the largest market share; Structural Health Monitoring is expanding most quickly.
End User:
The end-user segmentation highlights the diverse customer base for acoustic sensors, each with distinct procurement patterns and solution requirements.
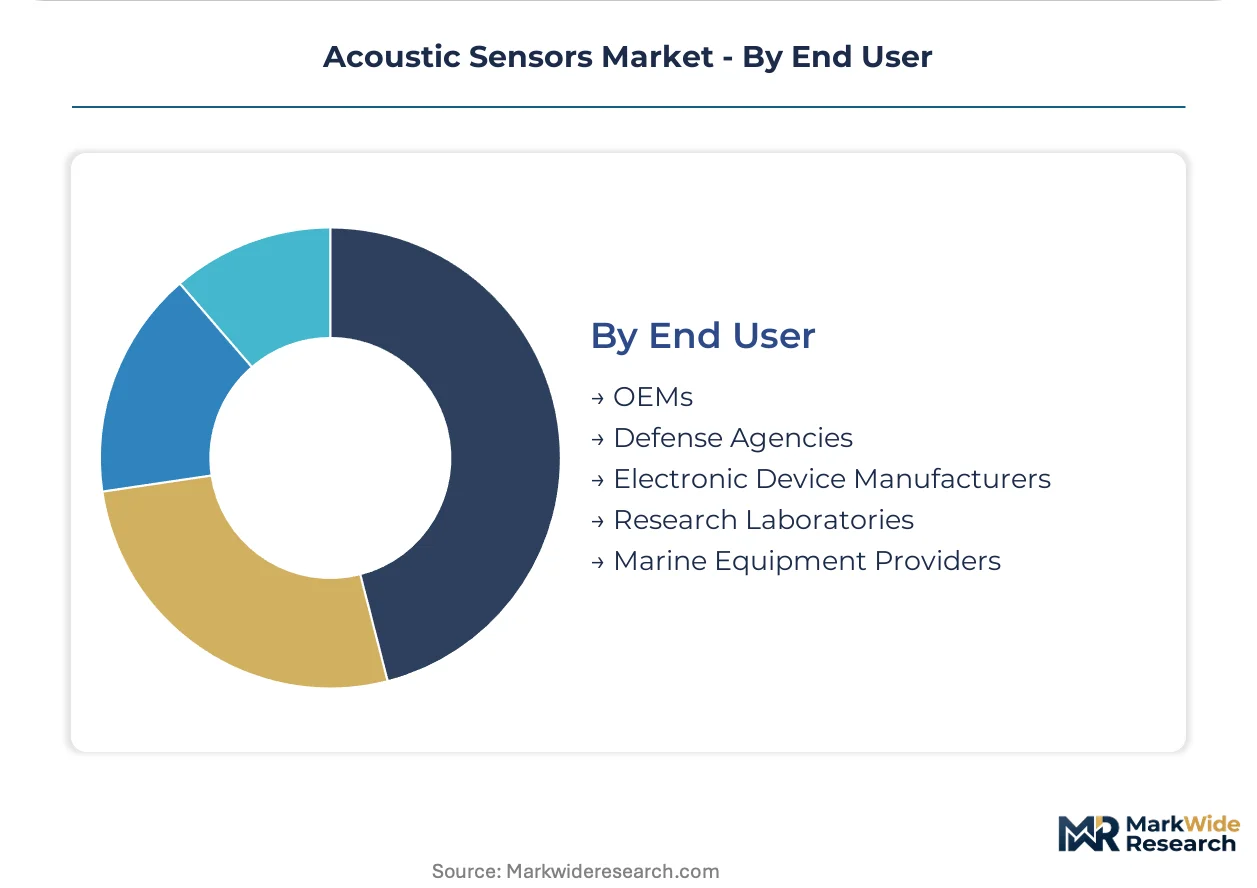
- OEMs:Original Equipment Manufacturers integrate acoustic sensors as components into their final products, requiring high-volume supply and specific technical specifications. Automotive manufacturers and smart home device producers represent significant OEM demand.
- Defense Agencies:These government entities procure specialized acoustic sensors for military intelligence, border security, and underwater defense applications.
- Electronic Device Manufacturers:These companies produce consumer electronics and similar devices, relying on miniaturized and cost-effective acoustic sensors for integration. Their procurement is driven by scale and the need for advanced features like voice recognition.
- Research Laboratories:Academic and corporate research institutions utilize acoustic sensors for scientific experimentation, material characterization, and new product development.
- Marine Equipment Providers:These providers supply specialized acoustic sensors for sonar, navigation, and oceanographic research equipment to commercial and scientific vessels.
OEMs account for the largest proportion of sensor sales; Electronic Device Manufacturers are increasing their procurement volumes rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's highly skilled engineering workforce, particularly concentrated in its automotive and advanced manufacturing sectors, anchors significant demand for acoustic sensors. This talent pool drives innovation in predictive maintenance and in-cabin systems. The market exhibits varied dynamics across key global regions, each influenced by distinct regulatory environments and industrial priorities.
Germany
Automotive manufacturing and advanced machinery diagnostics represent strong demand drivers for acoustic sensors in Germany. The EU's Machinery Regulation mandates stringent safety and operational standards for industrial equipment. Major industrial clusters in Bavaria and Baden-Württemberg actively integrate acoustic monitoring into Industry 4.0 initiatives to enhance operational efficiency.
United States
Demand for acoustic sensors in the United States stems from structural health monitoring in aging infrastructure and advanced aerospace applications. Regulations from the US NHTSA guide the integration of acoustic sensors into vehicle safety systems. Key aerospace and technology hubs in the Pacific Northwest and California drive innovation in high-fidelity sensing solutions.
Japan
Consumer electronics integration and precision industrial equipment drive the acoustic sensors market in Japan. The Ministry of Economy, Trade and Industry (METI) supports advanced materials research relevant to sensor development. The Kanto region, encompassing Tokyo, remains a center for electronics manufacturing and R&D, fostering miniaturized sensor advancements.
China
Rapid infrastructure development and a burgeoning consumer electronics market fuel the acoustic sensors sector across China. National GB standards for product quality and safety influence sensor design and application in various industries. Manufacturing powerhouses in the Yangtze River Delta region integrate acoustic sensors into smart factory solutions and consumer devices.
India
Growing automotive manufacturing and a focus on smart infrastructure projects contribute to the rising demand for acoustic sensors in India. The Bureau of Indian Standards (BIS) establishes quality benchmarks for electronic components, including sensors. Major IT and manufacturing hubs in Karnataka and Maharashtra are increasingly adopting acoustic monitoring for industrial and consumer applications.
Acoustic Sensors Market Key Industry Players
Top-tier vendors anchor the high-fidelity and specialized industrial segments, while mass-market component suppliers compete on volume and cost-effectiveness. This tiered structure defines competitive dynamics, with companies often specializing in either high-margin industrial applications or high-volume consumer electronics. Strategic archetypes include precision sensor manufacturers, industrial automation integrators, and MEMS component suppliers. Companies engage in strategic partnerships to bundle hardware with analytical software and pursue portfolio diversification to address varied end-user needs.
Within the high-margin industrial and aerospace archetype, Honeywell International Inc. occupies a position as a provider of advanced structural health monitoring solutions. Siemens AG exemplifies the industrial automation integrator archetype, leveraging its expertise to embed acoustic sensors into factory diagnostics platforms. Murata Manufacturing Co., Ltd. represents the high-volume consumer electronics integrator, specializing in miniaturized MEMS-based components for a wide array of devices.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Murata Manufacturing Co., Ltd. |
| Panasonic Corporation |
| KYOCERA Corporation |
| Transense Technologies PLC |
| AVX Corp. |
| Boston Piezo-Optics Inc. |
| Microchip Technology Incorporated |
| Others |
Cost & Logistics Intelligence
Specialized ceramic material prices, essential for high-fidelity piezoelectric sensors, directly influence the cost structure across the acoustic sensor supply chain. This volatility cascades into tiered pricing models, impacting high-margin industrial applications and cost-sensitive consumer electronics.
Pricing Analysis
The bundled-versus-unbundled service split significantly shapes acoustic sensor pricing. Project-based pricing dominates for complex structural health monitoring and industrial diagnostics, while per-unit transactional models apply to high-volume MEMS components. Price differentiation stems from strict certification levels like AEC-Q100 and the sensor's performance grade. Pricing softness is evident in the commodity microphone segment due to MEMS technology advancements. Consumer electronics manufacturers are highly price-sensitive, contrasting with defense agencies and aerospace firms.
Supply Chain Analysis
Skilled engineering workforce availability in manufacturing hubs like China, Japan, and Germany underpins the acoustic sensor supply chain. Production relies heavily on specialized ceramic materials for piezoelectric sensors and silicon wafers for MEMS components. A structural risk exists in the single-source vulnerability for certain high-performance ceramic inputs, leading to potential bottlenecks. Distribution primarily runs through OEMs for integration into final products, alongside specialized system integrators for complex industrial solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acoustic sensors market presents a compelling margin-expansion story, driven by the increasing demand for high-value structural health monitoring solutions. This shift towards premium applications allows vendors to capture greater value beyond commodity components.
For Market Incumbents: Anticipate the evolving demand for integrated solutions by investing heavily in edge AI capabilities for real-time data processing. Pursue strategic partnerships with analytics firms to bridge data interpretation skill gaps, a significant threat. Reinforce market position through rigorous certification investments, especially for automotive and aerospace applications, ensuring US NHTSA compliance.
For New Entrants and Emerging Players: Enter via underpenetrated niches such as precision agriculture or non-invasive medical diagnostics, leveraging specialized sensor designs. Precision agriculture represents the most penetrable application area for innovative solutions. Develop a go-to-market strategy focused on outcome-based service models, emphasizing actionable insights for customers.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software and analytics firms capable of transforming raw acoustic data into actionable intelligence. The market offers long-term viability, underpinned by expanding regulatory mandates for safety; target acquisition profiles should favor companies with proprietary algorithms or deep domain expertise in structural health monitoring. Watch for increasing government investment in smart infrastructure projects as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Edge AI Processors | Embeds real-time analytical intelligence directly into sensors, reducing latency for industrial automation. |
| Pursue AEC-Q100 Certification | Unlocks high-volume automotive OEM contracts for in-cabin and safety system integration. |
| Strategic Partnership with Infrastructure Firms | Accelerates deployment of structural health monitoring solutions for aging public assets. |
| Invest in High-Frequency Ultrasound R&D | Opens new frontiers in non-invasive medical diagnostics and point-of-care devices. |
| Bundle Hardware with Predictive Maintenance Software | Shifts customer procurement towards complete solutions, displacing traditional component distributors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, forming the foundation of this analysis. Primary research involved discussions with industrial automation engineers, automotive R&D leads, and MEMS component designers. Secondary validation drew from SEC filings, patent databases, and regulatory body reports, ensuring robust bottom-up and top-down triangulation.
Comparable historical periods anchored the forecast window, establishing baseline growth trajectories for each segment. The analytical framework modeled market dynamics across product type, technology, application, end-user, and regional industrial output. Compound annual growth rates were derived from a multi-factor regression analysis, incorporating industrial IoT adoption rates and automotive production volumes.
Inputs from public company financials and regulatory filings were available through the study window; gaps in emerging technology adoption data introduce uncertainty bands. Forecasts reflect assumptions regarding future supply chain stability and evolving regulatory frameworks. Material deviation in industrial output or infrastructure spending warrants re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Pressure Monitoring Market