
 Global Load Cell Market | 2026-2036
Global Load Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Global Load Cell Market Foresight
Precision-grade calibration standards for aerospace and pharmaceutical applications is unwinding legacy commodity pricing across the load cell industry. Honeywell International Inc. leverages its FAA-certified manufacturing footprint to dominate high-reliability segments for aircraft weighing systems. Siemens sustains technology leadership through integrated digital load cell platforms that feed directly into PLC-controlled automation architectures. Vishay Precision Group Inc. specializes in thin-film strain gauge production, anchoring its position in semiconductor and medical device metrology markets.
A load cell is a force transducer that converts mechanical load into an electrical signal, typically employing a bonded metallic foil strain gauge on a deforming element with rated capacities from grams to thousands of tonnes and accuracy classes spanning OIML R60 C3 to C6. Its primary purpose is to enable precise weight determination, force feedback, and process control across industrial, commercial, and scientific applications. Strain gauge load cells occupy the mature volume core of the market, while digital and wireless technologies are capturing margin pools through predictive maintenance integration and reduced cabling infrastructure. Fiber optic load cells are penetrating hazardous-environment applications where electromagnetic immunity determines specification viability.
The International Organization of Legal Metrology (OIML) and the National Institute of Standards and Technology (NIST) enforce traceability requirements that shape product design cycles and certification costs for manufacturers serving trade-approved installations. The EU Machinery Directive and FCC Part 15 regulations in the United States govern wireless load cell deployments, creating divergent compliance pathways that influence regional product portfolios. Stakeholders must monitor evolving cybersecurity mandates for networked sensor ecosystems as digital load cells become data nodes within broader operational technology infrastructure.
Market Dynamics
The transition from analog to digital load cell architectures is restructuring procurement priorities across industrial automation, as facilities retrofit legacy weighing infrastructure to meet networked Industry 4.0 protocols and predictive maintenance requirements.
Growth Catalysts
- EU Machinery Directive compliance mandates:European manufacturers face compulsory digital retrofit deadlines that accelerate replacement cycles for analog strain gauge systems with networked sensor arrays.
- Aerospace structural testing expansion:German and US aircraft certification programs demand precision force measurement systems with OIML R60 C6 accuracy classes for flight qualification protocols.
- Silicon carbide strain gauge adoption:Wide-bandgap semiconductor materials enable higher temperature tolerance and electromagnetic immunity in harsh-environment deployments.
Market Restraints
- Specialized alloy supply concentration:Maraging steel and precipitation-hardened stainless sources cluster in select East Asian and European foundries, exposing lead times to geopolitical friction.
- FCC Part 15 certification complexity:Wireless load cell manufacturers face divergent electromagnetic compliance pathways between US and EU regulatory frameworks that fragment product development resources.
- Piezoelectric force sensor substitution:Dynamic measurement applications in automotive crash testing and materials research increasingly specify quartz-based alternatives for high-frequency response requirements.
Strategic Opportunities
- India PLI scheme leverage:Production-linked incentives for electronics manufacturing and medical device assembly create localized demand for metrology-grade load cells in quality inspection lines.
- Subsea oil and gas fiber optic penetration:Intrinsic safety requirements in North Sea and Gulf of Mexico deepwater installations favor photonic force transducers over electrical alternatives.
- AI-driven predictive calibration:Machine learning algorithms applied to drift pattern analysis enable condition-based maintenance contracts that transform hardware sales into recurring revenue streams.
Industry Challenges
- Metrology software cybersecurity hardening:Networked digital load cells require IEC 62443-compliant firmware architectures that extend development timelines and certification costs.
- Strain gauge bonding technician scarcity:Precision adhesive application and thermal compensation tuning demand specialized craft skills that outpace vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Load Cell Market |
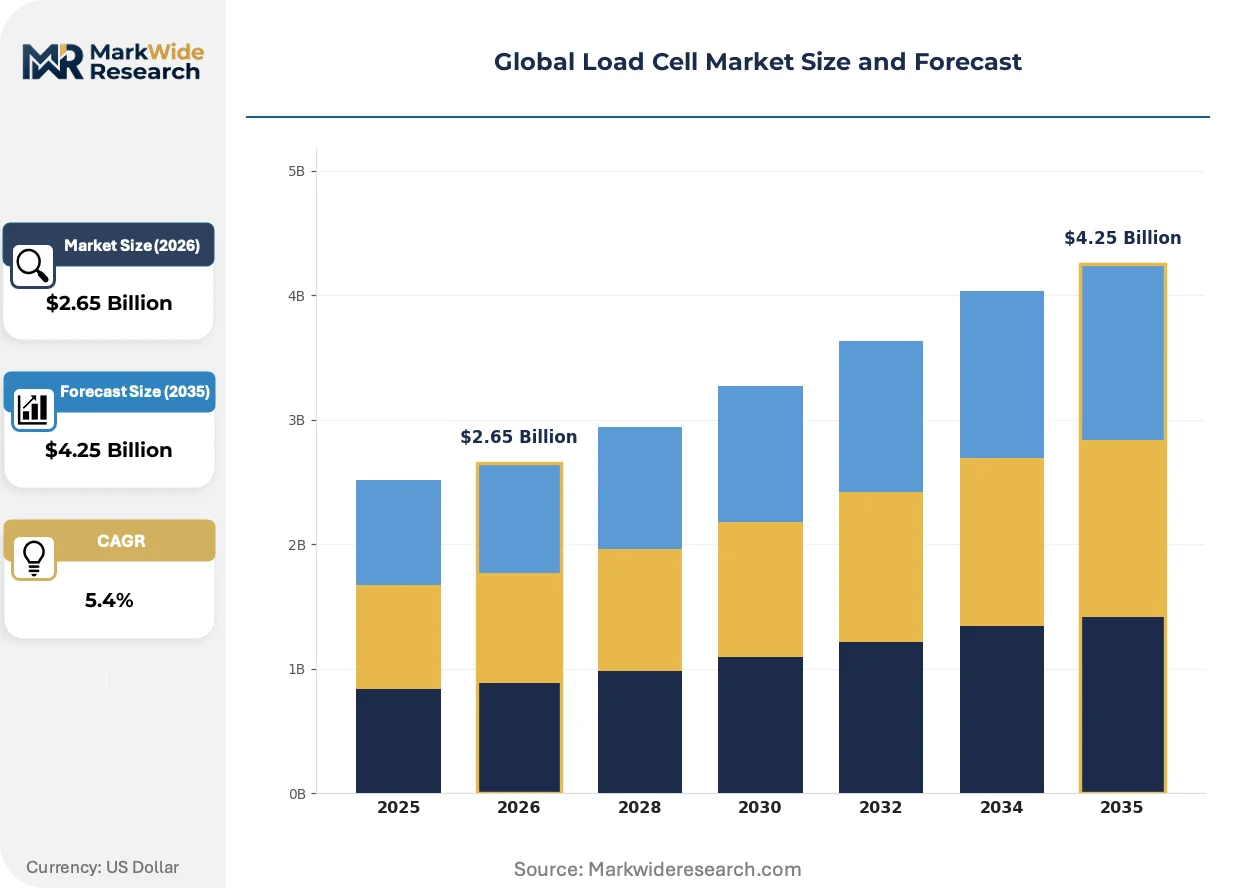
| Market Size in 2026 | $2.65 Billion |
| Market Size in 2035 | $4.25 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Load Cell Type: Strain Gauge, Capacitive, Hydraulic, Pneumatic, Piezoelectric, Magnetostrictive Technology: Analog, Digital, Wireless, Fiber Optic, MEMS, Quartz Application: Weighing, Material Testing, Automation Control, Force Measurement, Process Monitoring, Quality Inspection End User Industry: Manufacturing, Construction, Aerospace, Agriculture, Food Processing, Logistics |
| Companies Covered | Honeywell International Inc., Siemens, Spectris (Omega Engineering Inc.), Flintec, Amphenol Corporation (PCB Piezotronics, Inc.), TE Connectivity, Mettler-Toledo International Inc., FUTEK Advanced Sensor Technology, Inc., Vishay Precision Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Load Cell Market Shifts & Advancements
Digitalization protocols are penetrating force measurement hardware at the sensor level, compressing traditional distinctions between transducer manufacturing and industrial software ecosystems.
Silicon-on-insulator MEMS force sensors are displacing conventional foil strain gauge architectures in sub-500-gram measurement ranges. Medical device and semiconductor handling equipment manufacturers specify these microfabricated alternatives for cleanroom compatibility and hermetic packaging. The displacement is compressing margin pools for commodity load cell assemblers while concentrating value capture in wafer-level foundry operations.
REACH substance restrictions on lead-containing solder alloys are forcing metallurgical redesigns in strain gauge terminal connections. European manufacturers must certify RoHS-compliant bonding processes that maintain creep resistance and temperature stability. High-precision pharmaceutical weighing applications face the steepest compliance cost escalations given their sensitivity to long-term drift specifications.
Equipment-as-a-service contracting is restructuring capital deployment patterns in automotive and logistics end-uses. Tier-one suppliers now bundle load cell arrays with cloud-based weight data analytics, displacing traditional component procurement through operational expenditure models. This shift is most pronounced in German automotive assembly plants and Chinese e-commerce fulfillment networks where uptime guarantees determine vendor selection.
Global Load Cell Market Segmentation
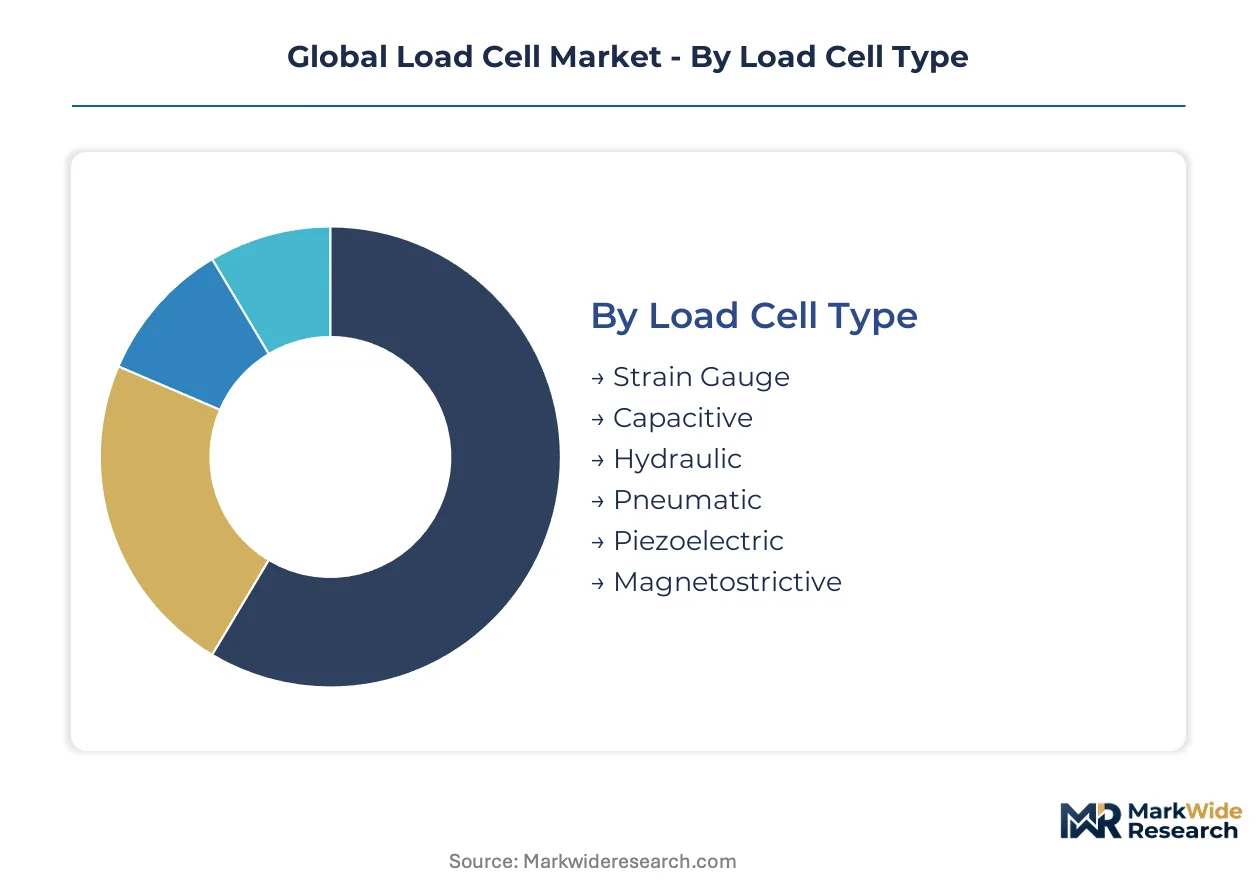
Load cell segmentation reveals where substitution pressures and technology transitions are restructuring procurement patterns. Engineers specify transducer architectures based on electromagnetic immunity requirements, calibration traceability needs, and integration complexity with existing automation infrastructure.
Load Cell Type:
Strain gauge architectures face mounting substitution pressure from solid-state alternatives in high-temperature and hazardous-environment deployments.
- Strain Gauge:Bonded metallic foil elements on deforming substrates deliver OIML R60 C3-C6 accuracy classes. Automotive assembly plants in Germany and China specify these for production-line weighing where cost-performance ratios dominate procurement decisions.
- Capacitive:Electrode-gap displacement measurement eliminates strain gauge creep and hysteresis errors. Semiconductor cleanroom equipment manufacturers in South Korea and Taiwan specify these for sub-gram precision in wafer handling systems.
- Hydraulic:Fluid-pressure transduction suits explosive atmospheres where electrical ignition risks preclude conventional sensors.
- Pneumatic:Air-pressure force balance systems serve legacy industrial platforms in mature manufacturing economies.
- Piezoelectric:Quartz-crystal charge generation captures dynamic force events in automotive crash testing and materials research laboratories.
- Magnetostrictive:Magnetoelastic strain sensing penetrates heavy-lift crane and subsea tension monitoring applications.
Strain gauge configurations retain volume leadership; capacitive variants hold the steepest expansion curve.
Technology:
Cost tier stratification separates retrofit-compatible analog systems from premium digital architectures commanding predictive maintenance premiums.
- Analog:Millivolt-per-volt output signals require external amplification and A/D conversion. Legacy food processing facilities in Italy and Spain delay replacement cycles due to capital constraints and operational disruption risks.
- Digital:Integrated microprocessors deliver temperature compensation, linearization, and networked communication via CANopen or EtherNet/IP protocols. German automotive OEMs mandate these for Industry 4.0 compliance under EU machinery directives.
- Wireless:Battery-powered or energy-harvesting transmission eliminates cable infrastructure in mobile weighing and rotating equipment applications.
- Fiber Optic:Photonic force transduction provides intrinsic safety in North Sea oil platforms and electromagnetic immunity in MRI-adjacent medical equipment.
- MEMS:Silicon-on-insulator microfabrication displaces foil gauges below 500-gram capacities in medical device and semiconductor handling equipment.
- Quartz:Piezoelectric crystal force sensors dominate high-frequency dynamic measurement in aerospace vibration testing.
Analog systems anchor installed-base economics; digital platforms are climbing the fastest on new-build specifications.
Application:
Application segmentation tracks how force measurement migrates from isolated weighing stations toward embedded process control nodes.
- Weighing:Static mass determination in commercial scales and industrial batching systems. Logistics fulfillment centers in the Netherlands and California deploy networked arrays for dimensional weight pricing compliance.
- Material Testing:Tensile, compression, and fatigue characterization in R&D and quality assurance laboratories. German automotive suppliers specify multi-axis load cells for chassis component validation.
- Automation Control:Real-time force feedback for robotic assembly and adaptive manufacturing processes.
- Force Measurement:General-purpose tension and compression sensing across industrial machinery.
- Process Monitoring:Continuous load tracking in chemical reactor vessels and extrusion equipment.
- Quality Inspection:Automated pass-fail determination in electronics and pharmaceutical packaging lines.
Weighing applications command the largest installed base; quality inspection is gaining share fastest on automation intensity.
End User Industry:
Customer-type concentration varies sharply between project-driven construction procurement and continuous manufacturing consumption patterns.
- Manufacturing:Discrete and process production lines require force measurement for assembly, packaging, and materials handling. Chinese electronics contract manufacturers in Shenzhen and Dongguan scale automated inspection lines driving metrology-grade demand.
- Aerospace:Aircraft weighing and structural testing demand OIML R60 C6 accuracy with FAA traceability certification. Boeing and Airbus supply chains in Washington State and Toulouse specify Honeywell and Vishay Precision Group systems.
- Construction:Crane load monitoring and materials testing equipment procurement tracks infrastructure investment cycles.
- Agriculture:Grain handling and livestock weighing systems serve cooperative and commercial farming operations.
- Food Processing:Hygienic design load cells with IP69K sealing and stainless steel construction meet USDA and EFSA sanitation requirements.
- Logistics:Conveyor scales and shipping dimensioning systems support e-commerce fulfillment network expansion.
Manufacturing retains volume leadership; aerospace holds the steepest expansion curve on precision certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Load cell manufacturing concentrates in Germany, the United States, and China, with precision-grade production clustering around aerospace certification centers and high-volume assembly scaling in eastern Chinese manufacturing corridors. Each geography maintains distinct regulatory pathways and end-use specializations that shape local competitive dynamics.
United States
Aerospace structural testing and aircraft weighing systems drive precision demand from Boeing supply chains in Washington State and Alabama. FAA certification requirements under 14 CFR Part 25 mandate OIML R60 C6 accuracy classes for flight qualification equipment. Greater Seattle and Wichita, Kansas host concentrated metrology-grade fabrication for defense and commercial aviation programs.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg mandate digital load cell retrofits under EU Machinery Directive 2006/42/EC compliance deadlines. Siemens and Honeywell manufacturing footprints in Munich and Berlin anchor high-reliability production for Industry 4.0 automation architectures. Stuttgart's automotive cluster specifications propagate across European supply chains.
China
Electronics contract manufacturers in Shenzhen and Dongguan scale automated quality inspection lines requiring sub-gram capacitive load cells. GB standards administered by SAMR govern metrology traceability for trade-approved installations. The Yangtze River Delta concentration of automotive and semiconductor plants absorbs volume production from domestic strain gauge assemblers.
India
PLI scheme incentives for electronics manufacturing and medical device assembly generate localized demand for metrology-grade quality inspection equipment. BIS certification requirements shape product design cycles for domestic market entry. Karnataka's Bengaluru-Tumkur corridor and Tamil Nadu's Sriperumbudur electronics cluster drive specification intensity.
Japan
Semiconductor handling equipment manufacturers in Tokyo and Osaka specify MEMS-based force sensors for cleanroom-compatible wafer processing. METI industrial standardization programs accelerate displacement of conventional foil strain gauges below 500-gram capacities. Chubu region precision component suppliers feed into global semiconductor capital equipment supply chains.
Global Load Cell Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision aerospace certification concentrated among FAA-accredited manufacturers and high-volume strain gauge assembly scaling through East Asian foundry networks. The vendor base separates into three strategic tiers: integrated industrial conglomerates with digital platform portfolios, specialized strain gauge and sensor technology pure-plays, and regional fabricators serving commodity weighing applications. M&A activity concentrates on digital telemetry capabilities and wireless communication module integration, while capacity expansion targets Indian and Vietnamese assembly operations.
Among diversified industrial technology groups, Honeywell International Inc. and Siemens occupy positions exemplifying integrated platform strategies that bundle force measurement with broader automation architectures. Vishay Precision Group Inc. represents the specialized component archetype, with thin-film strain gauge production anchoring penetration into semiconductor and medical device metrology markets. These three companies illustrate the competitive spectrum from system-level integration down to core sensor element supply.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens |
| Spectris (Omega Engineering Inc.) |
| Flintec |
| Amphenol Corporation (PCB Piezotronics, Inc.) |
| TE Connectivity |
| Mettler-Toledo International Inc. |
| FUTEK Advanced Sensor Technology, Inc. |
| Vishay Precision Group Inc. |
| Others |
Supply & Pricing Matrix
Silicon-on-insulator MEMS force sensor substitution below 500-gram capacities is simultaneously redrawing supply geography toward Japanese and Taiwanese wafer foundries and compressing margin pools for commodity foil gauge assemblers in China and India.
Pricing Analysis
OIML R60 certification tiers dictate the pricing tier structure across aerospace and pharmaceutical applications. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified C6 systems from industrial C3 grades and commodity trade-legal units. Cost compression in standard-tier analog strain gauge assemblies is intensifying because MEMS alternatives capture sub-gram medical and semiconductor handling volumes. Automotive OEMs in Germany exhibit lowest price sensitivity given Industry 4.0 compliance mandates, while logistics operators in emerging Asian markets drive hardest bargain on per-unit procurement.
Supply Chain Analysis
Extended lead times for maraging steel and precipitation-hardened stainless alloys now stretch 16-24 weeks at East Asian and European foundries. Manufacturing gravity centers on Germany for precision aerospace certification, China for high-volume strain gauge assembly, and Japan for MEMS wafer fabrication. Raw material sourcing rests on nickel-cobalt superalloys, high-purity copper for signal traces, and specialized epoxy adhesives for gauge bonding. Single-source vulnerability concentrates in German and Japanese precision alloy suppliers. Distribution runs through authorized metrology distributors serving calibration laboratories and direct OEM supply agreements for automotive and aerospace tier-ones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital load cell adoption sits at an early-cycle expansion story justified by EU Machinery Directive retrofit deadlines forcing analog replacement across European manufacturing footprints.
For Market Incumbents: Shield high-reliability aerospace margins by deepening captive supply of thin-film strain gauge elements against MEMS substitution threats. Accelerate IEC 62443 cybersecurity certification for digital load cell firmware architectures to defend platform positions against industrial software entrants. Prioritize backward integration into silicon carbide strain gauge materials for high-temperature applications.
For New Entrants and Emerging Players: Predictive calibration-as-a-service offerings represent the most exploitable service-layer gap where Honeywell and Siemens under-serve mid-market manufacturers. Target Indian electronics contract manufacturers under PLI scheme incentives with localized metrology-grade quality inspection solutions. Pursue fiber optic load cell penetration in North Sea oil platforms through intrinsic safety specifications that exclude electrical alternatives.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors specialized sensor technology pure-plays with digital telemetry capabilities over diversified industrial conglomerates. Long-term viability over the next decade hinges on software-enabled recurring revenue transformation. Watch AI-driven drift pattern analysis adoption rates as the signal indicating whether hardware vendors successfully convert to condition-based maintenance contracts.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Siemens CANopen and EtherNet/IP protocols embed load cells directly into PLC-controlled automation architectures. |
| Wireless Communication Module Acquisition | FCC Part 15 certification capabilities unlock US market access for European and Asian manufacturers. |
| MEMS Foundry Partnership | Tokyo and Osaka wafer-level operations displace conventional foil gauges in sub-500-gram medical device applications. |
| India Assembly Footprint Expansion | Karnataka and Tamil Nadu electronics clusters absorb PLI-driven demand for metrology-grade quality inspection equipment. |
| Cybersecurity Firmware Hardening | IEC 62443-compliant architectures extend development timelines but defend digital load cell positions in networked OT infrastructure. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with plant engineers at German automotive OEMs, procurement leads at Chinese electronics contract manufacturers, metrology laboratory directors in the United States, and calibration service technicians in India. Secondary validation drew from OIML certification registries, FAA manufacturing approvals, SAMR GB standards filings, and SEC 10-K disclosures from listed sensor technology suppliers. Bottom-up volume modeling triangulated against top-down industrial automation capex forecasts.
Across the analysis window, projections segmented by load cell type, technology architecture, application use case, and end-user industry concentration. CAGRs were derived from adoption curve modeling for digital and wireless platforms versus analog installed-base replacement rates. Forecast inputs incorporated EU Machinery Directive compliance deadlines, India PLI scheme incentive trajectories, and aerospace structural testing program pipelines at Boeing and Airbus supply chains.
Forecasts assume regulatory continuity in OIML, FAA, and SAMR certification regimes; material policy shifts in electromagnetic compliance or cybersecurity mandates would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market