
 Current Sensor Market | 2026-2036
Current Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Current Sensor Market Intelligence
Project finance for automotive electrification infrastructure is rewriting capital access rules for current sensor suppliers. Infineon Technologies leverages its integrated semiconductor manufacturing to anchor supply contracts with tier-one automotive module producers. Allegro MicroSystems specializes in Hall Effect architectures for traction motor inverters, while Honeywell International Inc. dominates aerospace-grade current sensing with extended temperature-range certifications.
A current sensor detects and measures electrical current flow through magnetic field induction or resistive voltage drop, typically operating across milliampere to kiloampere ranges with bandwidths exceeding 100 kHz for power electronics applications. Hall Effect Sensors occupy the largest installed base due to galvanic isolation and compact form factors, though Fluxgate Sensors command premium positioning in precision industrial metering where accuracy exceeds 0.1 percent. Digital technology interfaces are displacing analog outputs in automotive battery management systems, while the Renewable Energy end user segment attracts disproportionate R&D investment as grid-tied inverters require sub-microsecond fault detection.
IEC 61800-5-1 motor drive safety standards and the EU AI Act's industrial monitoring provisions shape product certification pathways for European market entry, while China's GB standards and NMPA-equivalent equipment safety rules govern import compliance for power conversion hardware. The US FAA and NHTSA impose distinct electromagnetic compatibility and functional safety thresholds for aerospace and electric vehicle applications respectively. Stakeholders must monitor regulatory divergence between automotive functional safety regimes and emerging grid code harmonization requirements to align certification roadmaps with procurement timelines.
Market Dynamics
Silicon carbide semiconductor integration is compressing switching frequencies and thermal envelopes, forcing current sensor architectures to shrink bandwidth requirements while maintaining isolation integrity across 800V automotive platforms.
Growth Catalysts
- IEC 61800-5-1 Motor Drive Standards:European industrial automation mandates galvanic isolation and fault detection protocols that favor Hall Effect sensor deployments in variable frequency drives.
- EV Powertrain Electrification:Traction motor inverters require sub-microsecond current monitoring for torque vectoring control, pulling high-bandwidth sensors into automotive battery management systems.
- Germany's Supplier Density:The concentration of automotive OEM module producers near Stuttgart and Munich creates localized demand clusters for precision current sensing in electrified drivetrains.
Market Restraints
- Rare Earth Magnet Cost Volatility:Neodymium and dysprosium price swings destabilize Hall Effect sensor bill-of-materials, compressing margins for mid-tier producers dependent on Chinese processed magnet supply.
- Fluxgate Precision Bottleneck:The 0.1% accuracy threshold requires exotic core materials and manual calibration protocols that resist automation, capping volume scalability for industrial metering applications.
- EU AI Act Industrial Monitoring Provisions:Emerging compliance requirements for AI-enabled predictive maintenance systems introduce certification friction that delays product launches by 8-14 months.
Strategic Opportunities
- Grid-Tied Inverter Fault Detection:Renewable energy installations require sub-microsecond arc-fault isolation, opening premium positioning for sensors with integrated digital signal processing.
- India PLI Scheme for Semiconductor Manufacturing:Production-linked incentives for domestic power electronics fabrication create localized assembly opportunities for current sensor module producers.
- Digital Interface Convergence:The shift from analog voltage outputs to SPI and I2C protocols in automotive battery management systems enables firmware-upgradeable sensor platforms with recurring revenue potential.
Industry Challenges
- Magnetic Core Characterization Talent Scarcity:The specialized knowledge required for hysteresis modeling and temperature drift compensation resides with a shrinking cohort of analog design engineers nearing retirement.
- ISO 26262 Functional Safety Certification Timelines:Automotive ASIL-D qualification for traction motor current sensing demands 18-24 month validation cycles that outpace product refresh rates.
- Legacy Analog System Integration Friction:Industrial retrofit projects face signal conditioning mismatches when digital-output sensors interface with 4-20mA PLC architectures from the 1990s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Current Sensor Market |
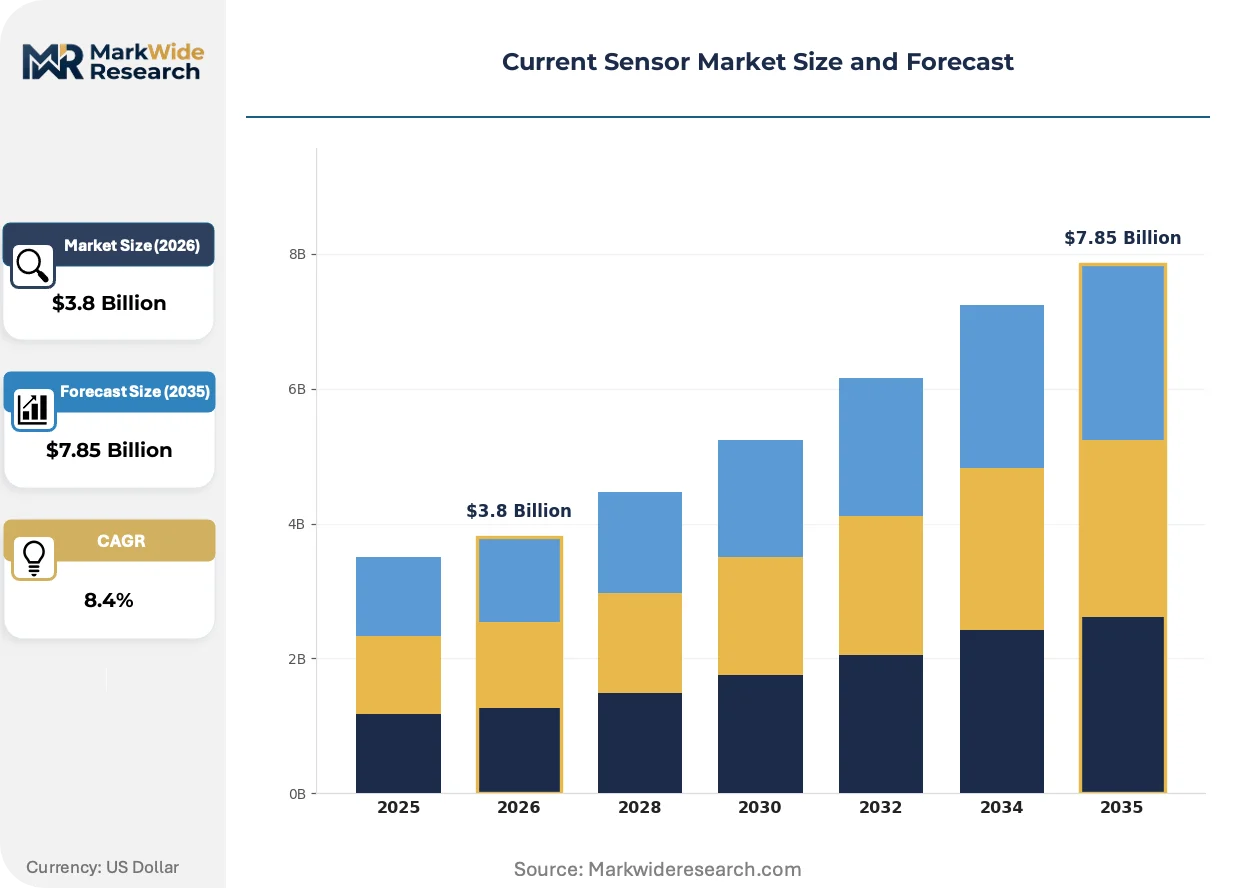
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
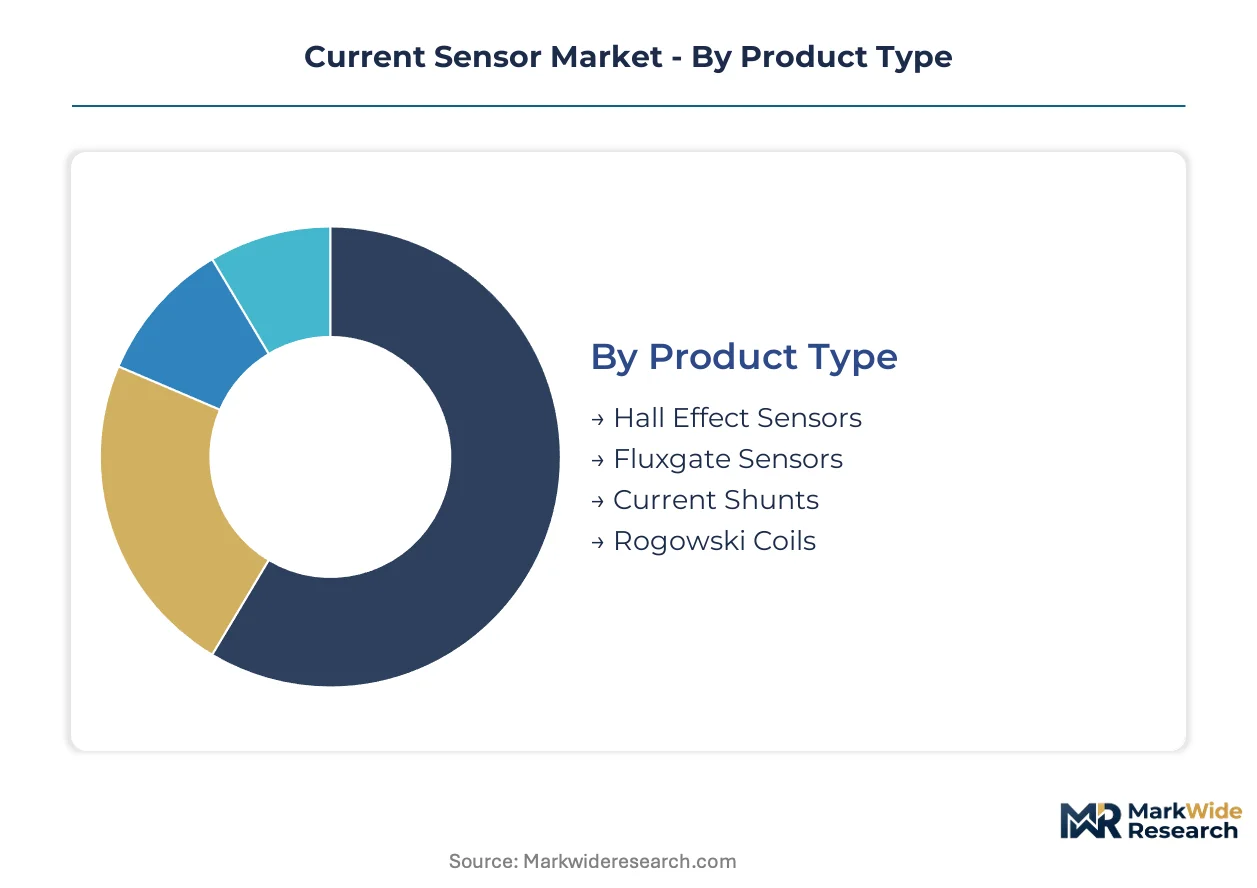
| Segmentation | Product Type: Hall Effect Sensors, Fluxgate Sensors, Current Shunts, Rogowski Coils Technology: Analog, Digital, Wireless, Optical End User: Industrial Automation, Automotive, Consumer Electronics, Renewable Energy Installation: Through-Hole, Surface Mount, Panel Mount, Embedded |
| Companies Covered | Infineon Technologies, Honeywell International Inc., Allegro MicroSystems, TDK Corporation, LEM International SA, STMicroelectronics, Asahi Kasei Corporation, Melexis, TAMURA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Current Sensor Market Strategic Shifts & Innovations
Silicon carbide power electronics are collapsing thermal management margins and switching transition times, forcing sensor designers to rethink magnetic field detection architectures from first principles.
Integrated magneto-resistive arrays with on-chip temperature compensation are rendering obsolete discrete Hall Effect configurations in 800V EV inverters. Tier-one automotive module producers in Germany and Japan are qualifying these solid-state alternatives for traction motor control. The technology is compressing form factor requirements by 60% while extending operational temperature ranges beyond 150°C.
The EU AI Act's industrial monitoring provisions now classify predictive maintenance current sensors as high-risk AI systems, triggering conformity assessment procedures that parallel existing CE marking pathways. Manufacturers must document algorithmic transparency and bias mitigation for machine-learning-based fault detection. Automotive and renewable energy segments are responding by segregating AI-enabled from deterministic sensor product lines to isolate certification scope.
Buyer concentration among automotive OEMs has compressed component sourcing cycles from 36-month platform commitments to 18-month rolling forecasts. Tier-two sensor suppliers now face working capital strain from inventory pre-positioning without volume guarantees. This pattern is most acute in Germany's Baden-Württemberg cluster, where Bosch, Continental, and ZF procurement teams synchronize supplier qualification timelines.
Current Sensor Market Segmentation
Current sensor procurement cycles diverge sharply across product architectures, with automotive traction inverters demanding 18-month qualification timelines while industrial retrofit projects tolerate decade-old analog interfaces. Technology selection directly determines margin structure, as digital-output platforms command firmware-upgradeable revenue streams that resist commoditization.
Product Type:
Hall Effect Sensors turn inventory fastest in automotive module production, while Fluxgate architectures face 24-month calibration bottlenecks that freeze working capital.
- Hall Effect Sensors:These devices exploit semiconductor Hall elements to detect magnetic fields induced by current flow, achieving galvanic isolation without physical conductor interruption. Demand concentrates in Germany's Baden-Württemberg automotive cluster, where Bosch and Continental procurement teams specify compact form factors for 800V traction inverters. IEC 61800-5-1 isolation mandates accelerate replacement of legacy current transformers in European variable frequency drives.
- Fluxgate Sensors:Saturable core architectures with excitation windings deliver measurement accuracy below 0.1% for precision industrial metering. Volume growth faces headwinds from manual calibration protocols and exotic permalloy core costs that resist automation scaling. Grid-tied inverter manufacturers in renewable energy applications specify these for revenue-grade energy monitoring where billing disputes demand forensic traceability.
- Current Shunts:Precision resistive elements with milliohm values generate proportional voltage drops for low-cost, high-bandwidth measurement in consumer power supplies.
- Rogowski Coils:Air-core toroidal windings enable flexible installation around busbars without circuit interruption, finding niche application in temporary power quality monitoring.
Hall Effect Sensors dominate installed base. Fluxgate Sensors is where expansion concentrates for precision industrial metering applications.
Technology:
Analog outputs retain cost advantage in legacy industrial retrofit, while digital interfaces capture automotive battery management system redesigns.
- Analog:Voltage and current output signals interface directly with 4-20mA PLC architectures prevalent in 1990s-era industrial automation infrastructure.
- Digital:SPI and I2C protocol integration enables on-chip signal processing with firmware-upgradeable compensation algorithms. Automotive tier-one module producers in Germany and Japan qualify these for traction motor control, where sub-microsecond latency requirements for torque vectoring exceed analog bandwidth limits.
- Wireless:RF telemetry eliminates galvanic isolation requirements in rotating machinery and hazardous environment installations where physical wiring introduces failure modes.
- Optical:Fiber-optic transmission paths provide immunity to electromagnetic interference in high-voltage switchgear and plasma research applications.
Analog maintains legacy lock-in. Digital is climbing the fastest as automotive platforms consolidate on deterministic communication buses.
End User:
Automotive qualification cycles stretch longest due to ISO 26262 ASIL-D requirements, while consumer electronics tolerates 6-month product lifecycles.
- Industrial Automation:Variable frequency drives and servo motor controllers specify Hall Effect architectures for IEC 61800-5-1 compliance, with Germany's machine tool builders driving premium positioning for integrated temperature compensation.
- Automotive:Traction motor inverters and battery management systems demand sub-microsecond current monitoring with isolation integrity across 800V platforms. Silicon carbide semiconductor integration compresses switching frequencies, forcing sensor bandwidth expansion while maintaining compact form factors.
- Consumer Electronics:Smartphones and laptop adapters prioritize cost minimization over accuracy, specifying shunt-based architectures with minimal signal conditioning.
- Renewable Energy:Grid-tied inverters require sub-microsecond arc-fault detection for safety shutdown, opening premium positioning for sensors with integrated digital signal processing and predictive maintenance algorithms.
Industrial Automation dominates installed base. Renewable Energy is where steepest expansion trajectory concentrates as grid code harmonization demands proliferate.
Installation:
Surface mount configurations align with high-volume automotive PCB assembly, while panel mount serves industrial retrofit with minimal redesign.
- Through-Hole:Pin-through-board mounting provides mechanical robustness for high-vibration environments in railway traction and aerospace applications.
- Surface Mount:Tape-and-reel packaging enables automated pick-and-place assembly at automotive electronics contract manufacturers. Miniaturization trends in 800V inverters favor these configurations for power density optimization.
- Panel Mount:Threaded housings with terminal blocks accommodate field wiring in industrial control panels without PCB redesign.
- Embedded:Direct integration into power semiconductor modules eliminates interconnect inductance, with Infineon and STMicroelectronics qualifying these for next-generation automotive inverters.
Panel Mount dominates legacy installed base. Embedded is gaining share fastest as power module integration consolidates supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive supplier clusters, while cost-sensitive procurement in China compresses margins for standard-grade Hall Effect architectures. Japan maintains premium positioning through magneto-resistive specialization. India's PLI scheme for semiconductor manufacturing is attracting module assembly investment. The United States anchors aerospace-grade certification demand.
Germany
Baden-Württemberg's automotive OEM density drives precision current sensing procurement for 800V traction inverters. IEC 61800-5-1 motor drive safety standards mandate galvanic isolation protocols that favor Hall Effect deployments in variable frequency drives. Stuttgart and Munich host concentrated procurement teams from Bosch, Continental, and ZF that synchronize supplier qualification timelines.
China
Domestic EV powertrain electrification absorbs high volumes of shunt-based and Hall Effect sensors for cost-optimized battery management systems. GB standards and NMPA-equivalent equipment safety rules govern import compliance for power conversion hardware. The Yangtze River Delta manufacturing belt concentrates surface-mount sensor assembly for consumer power supply exporters.
Japan
Magneto-resistive array development for automotive traction motor control commands premium R&D investment. METI industrial policy supports domestic semiconductor packaging capabilities for high-temperature sensor modules. The Nagoya-Chubu corridor anchors tier-one automotive electronics production with integrated current sensing in power modules.
United States
FAA electromagnetic compatibility thresholds and NHTSA functional safety requirements shape aerospace and electric vehicle sensor certification pathways. The IRA's clean energy manufacturing credits accelerate grid-tied inverter deployment requiring sub-microsecond arc-fault detection. Texas and Arizona attract power electronics fabrication investment with renewable energy integration mandates.
India
Production-linked incentives for semiconductor manufacturing create localized assembly opportunities for current sensor module producers. CEA grid code harmonization demands proliferate for renewable energy inverter installations. Gujarat and Tamil Nadu industrial corridors concentrate contract electronics manufacturing for automotive and industrial automation exports.
Current Sensor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in magnetic core characterization and signal conditioning. The vendor base stratifies across three tiers: integrated semiconductor manufacturers with captive sensor lines, pure-play magnetic sensing specialists, and industrial automation conglomerates with diversified instrumentation portfolios. Dominant competitive moves include backward integration into rare earth magnet supply chains and strategic partnerships for ISO 26262 ASIL-D qualification acceleration.
Among European integrated semiconductor manufacturers, Infineon Technologies and STMicroelectronics exemplify platform integrators with power module embedding capabilities. Allegro MicroSystems represents the magnetic sensing specialist archetype with focused Hall Effect expertise. Honeywell International Inc. anchors the diversified industrial conglomerate tier with aerospace-grade certification heritage. These three occupy distinct competitive positions without direct segment overlap.
| Leading Market Players |
|---|
| Infineon Technologies |
| Honeywell International Inc. |
| Allegro MicroSystems |
| TDK Corporation |
| LEM International SA |
| STMicroelectronics |
| Asahi Kasei Corporation |
| Melexis |
| TAMURA Corporation |
| Others |
Cost & Logistics Intelligence
Rare earth magnet processing concentration in China directly determines margin capture for Hall Effect sensor producers, with neodymium and dysprosium price volatility transferring downstream to automotive module pricing in Germany's Baden-Württemberg cluster.
Pricing Analysis
Configured-to-order pricing for ASIL-D certified automotive sensors commands 3-4x premiums over standard industrial-grade Hall Effect units. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-qualified traction motor sensors from IEC 61800-5-1 industrial drives and uncalibrated consumer shunts. Pricing pressure stems from silicon carbide integration forcing bandwidth expansion without corresponding bill-of-materials relief. Automotive OEMs exhibit lowest price sensitivity due to functional safety liability exposure, while consumer electronics procurement teams drive aggressive cost minimization.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese rare earth refineries, with secondary magnet alloy processing concentrated in Japan and Germany. Precision permalloy cores for Fluxgate architectures hinge on specialist mills in Japan and Switzerland. Single-source vulnerability pervades exotic core material supply, compounded by manual calibration bottlenecks that freeze working capital for 18-24 months. Distribution runs through tier-one automotive module producers in Germany and Japan who synchronize qualification timelines with power semiconductor packaging partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics anchored to EV powertrain electrification capex cycles, with silicon carbide semiconductor adoption cresting investment waves across automotive and renewable energy segments.
For Market Incumbents: Insulate margin pools by accelerating backward integration into rare earth magnet supply chains and captive ISO 26262 ASIL-D qualification capabilities. Threats from magneto-resistive array substitutes demand defensive R&D allocation toward integrated temperature compensation architectures. Channel control through embedded power module partnerships with Infineon and STMicroelectronics preserves pricing power.
For New Entrants and Emerging Players: Pursue white-space positioning in India's PLI-supported semiconductor assembly corridor, where localized production escapes China's magnet cost volatility. Grid-tied inverter fault detection offers the most penetrable segment given sub-microsecond arc-fault isolation requirements outpacing incumbent digital signal processing roadmaps. Go-to-market execution should anchor on CEA grid code harmonization compliance as a procurement entry wedge.
For Investors and Strategic Acquirers: Capital is best deployed toward magnetic core characterization specialists with irreplaceable hysteresis modeling talent pools nearing retirement. Long-term viability across a 5-10 year window favors acquisition targets possessing algorithmic transparency documentation for EU AI Act industrial monitoring provisions. The inflection signal to watch is procurement cycle compression from 36-month to 12-month platform commitments among German automotive OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Backward Integration | Captive neodymium supply insulates Hall Effect sensor margins from Chinese export quota volatility. |
| ASIL-D Certification Acceleration | Compressed 18-month qualification cycles align with silicon carbide inverter platform refresh rates. |
| Digital Interface Platformization | SPI and I2C protocol dominance enables firmware-upgradeable recurring revenue in automotive battery management. |
| India PLI Localization | Gujarat and Tamil Nadu assembly corridors escape magnet cost volatility while serving export markets. |
| EU AI Act Compliance Segregation | Isolating deterministic from AI-enabled sensor lines contains certification scope and accelerates time-to-revenue. |
Research Approach
Desk research of IEC standard documentation, automotive OEM technical specifications, and rare earth trade flow data preceded structured interviews with Hall Effect sensor design engineers, tier-one automotive module procurement managers, power electronics system architects, and magnetic core material specialists. Secondary validation drew from semiconductor foundry capacity disclosures, customs import records for neodymium alloys, and FERC grid interconnection filings. Bottom-up bill-of-materials modeling triangulated against top-down segment revenue allocation across product architectures and end-use applications.
Assumptions held fixed include silicon carbide semiconductor penetration rates in 800V automotive platforms and IEC 61800-5-1 regulatory enforcement timelines, while EV production volume trajectories and rare earth magnet price indices varied across sensitivity scenarios. Segmentation modeling incorporated product type, technology interface, end-use vertical, and installation configuration dimensions. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns in traction motor inverters and grid-tied renewable energy installations.
Sensitivities concentrate around Chinese rare earth export policy shifts and EU AI Act industrial monitoring provision implementation timelines. Cross-checking against IHS Markit vehicle production databases and EIA grid interconnection queues is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Tip Location Devices Market