
 Global PH Sensor Market | 2026-2036
Global PH Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global PH Sensor Market Outlook
Direct distribution from manufacturers to industrial end users is narrowing as sensor vendors consolidate field service networks. Honeywell International Inc. leverages its building automation channel to bundle pH sensors with broader process control packages. ABB Ltd. anchors European utility contracts through long-term calibration service agreements. Thermo Fisher Scientific Inc. specializes in laboratory-grade installations where accuracy tolerances reach ±0.01 pH units.
A pH sensor measures hydrogen ion activity in aqueous solutions through electrochemical or optical transduction, typically operating across a 0–14 range with temperature compensation circuits to offset thermal drift in glass electrode membranes. Industrial process control remains its dominant commercial purpose, enabling real-time adjustment of chemical dosing in continuous manufacturing lines. Digital sensor formats command premium positioning due to embedded diagnostics and predictive maintenance algorithms that reduce unplanned downtime. ISFET technology captures the fastest expansion trajectory as silicon-chip fabrication enables miniaturization for point-of-use medical and food safety applications. Optical pH sensing remains niche but holds margin pools in bioreactor environments where electrical interference compromises electrode performance.
EPA effluent limitation guidelines and EU Urban Waste Water Treatment Directive enforcement tighten accuracy and calibration documentation requirements, pushing utilities toward digitally certified sensor platforms. FDA process analytical technology initiatives in pharmaceutical manufacturing mandate in-line pH monitoring as a critical process parameter, accelerating validation protocols for sensor suppliers. Stakeholders must monitor convergence between water quality regulations and pharmaceutical manufacturing standards as dual-compliance sensors become the procurement default for multi-sector industrial conglomerates.
Market Dynamics
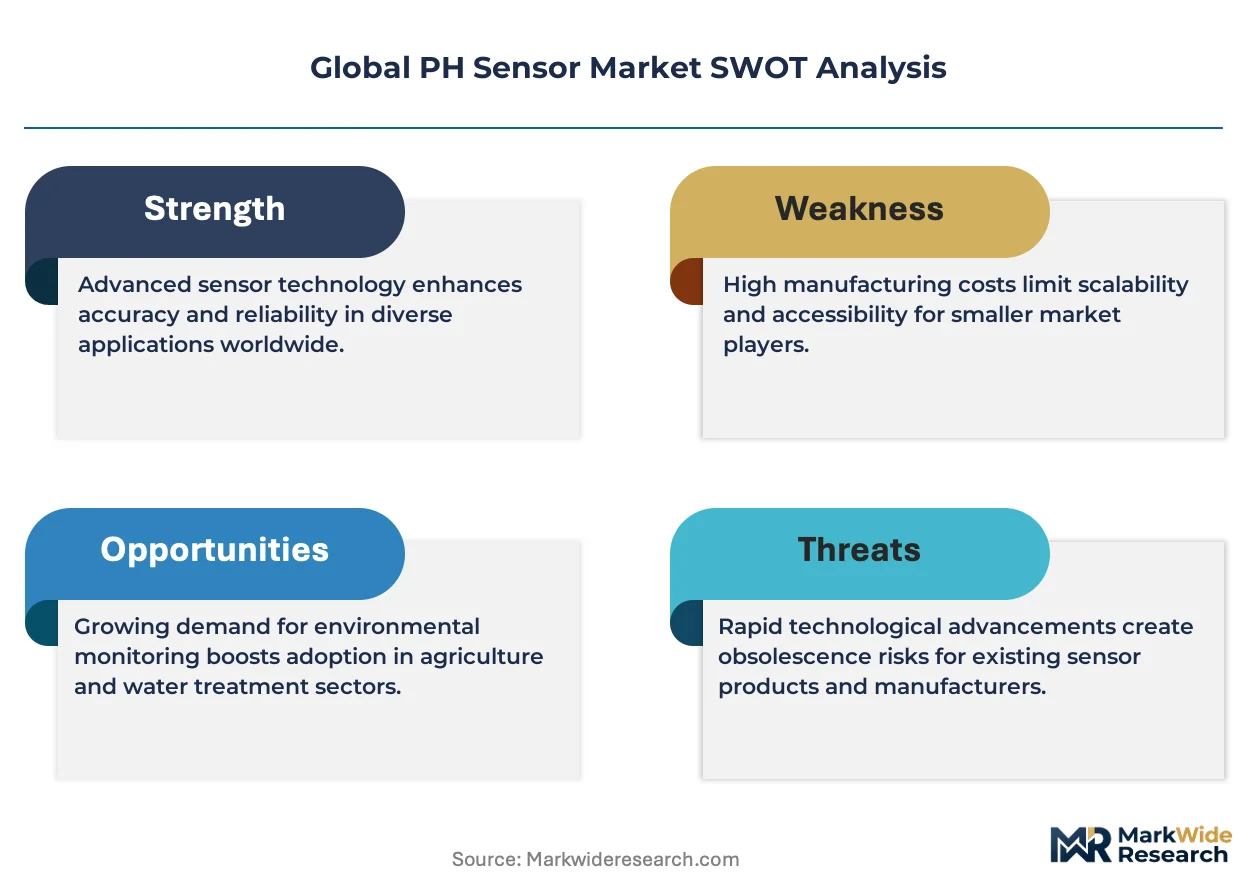
ISFET solid-state architectures are collapsing the cost floor for pH sensing, eroding the installed base of glass electrode systems across pharmaceutical cleanrooms and food processing lines while forcing recalibration of vendor R&D priorities.
Growth Catalysts
- EU Urban Waste Water Treatment Directive:German and French municipal utilities face mandatory real-time effluent monitoring, triggering sensor replacement cycles in aging treatment plants.
- Silicon-chip miniaturization:ISFET fabrication advances enable point-of-use medical diagnostics and wearable pH monitors, opening volume markets previously inaccessible to electrochemical designs.
- China's provincial environmental bureaus:Chemical processing zones in Jiangsu and Zhejiang provinces enforce continuous pH reporting, driving industrial wastewater monitoring deployments.
Market Restraints
- Platinum group metal volatility:Reference electrode assemblies depend on palladium and platinum coatings, exposing manufacturers to spot price swings that compress gross margins.
- Glass membrane supply concentration:Specialized borosilicate formulations for traditional electrodes source predominantly from German and Japanese specialty glass foundries, creating single-source vulnerability.
- Optical pH sensing substitution:Fluorescent dye-based systems capture bioreactor applications where electrical interference disqualifies electrode methods, capping electrochemical addressable market.
Strategic Opportunities
- India's pharmaceutical manufacturing corridor:Hyderabad and Ahmedabad clusters lack validated in-line pH monitoring infrastructure, creating first-mover openings for FDA-compliant digital sensor platforms.
- Food safety automation:Continuous pH tracking in dairy and brewing operations remains underpenetrated outside Western Europe, with ISFET durability enabling harsh CIP/SIP washdown cycles.
- Dual carbon goals alignment:China's MEE incentivizes sensor-driven chemical dosing optimization, positioning predictive maintenance algorithms as energy efficiency enablers.
Industry Challenges
- Metrology technician scarcity:Field calibration of digital sensors demands electrochemistry expertise that utilities and mid-sized manufacturers struggle to recruit and retain.
- IEC 60746 compliance timelines:Validation protocols for pharmaceutical-grade sensors extend 18-24 months, delaying revenue recognition and straining working capital.
- Legacy 4-20mA integration:Digital sensor outputs require protocol converters in brownfield process control environments, complicating retrofit sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PH Sensor Market |
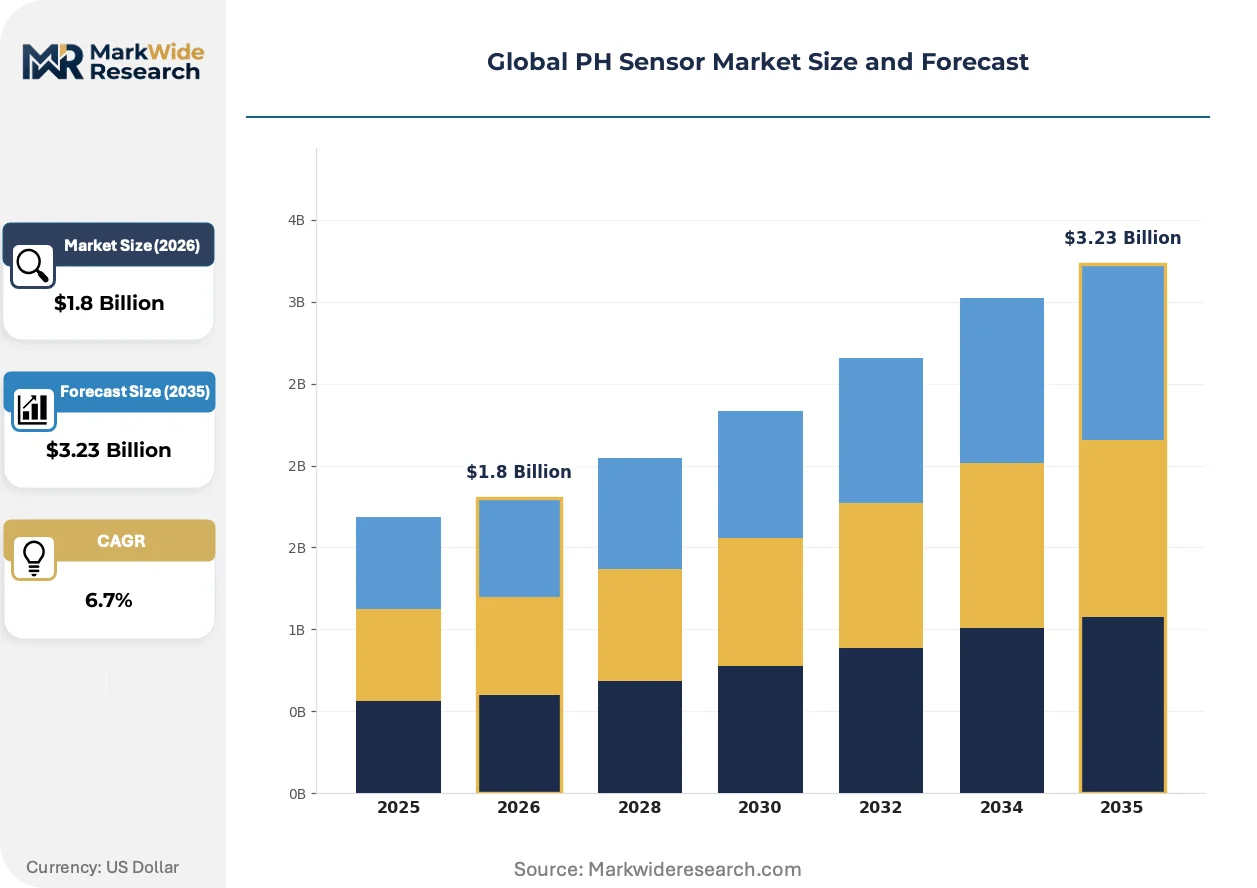
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
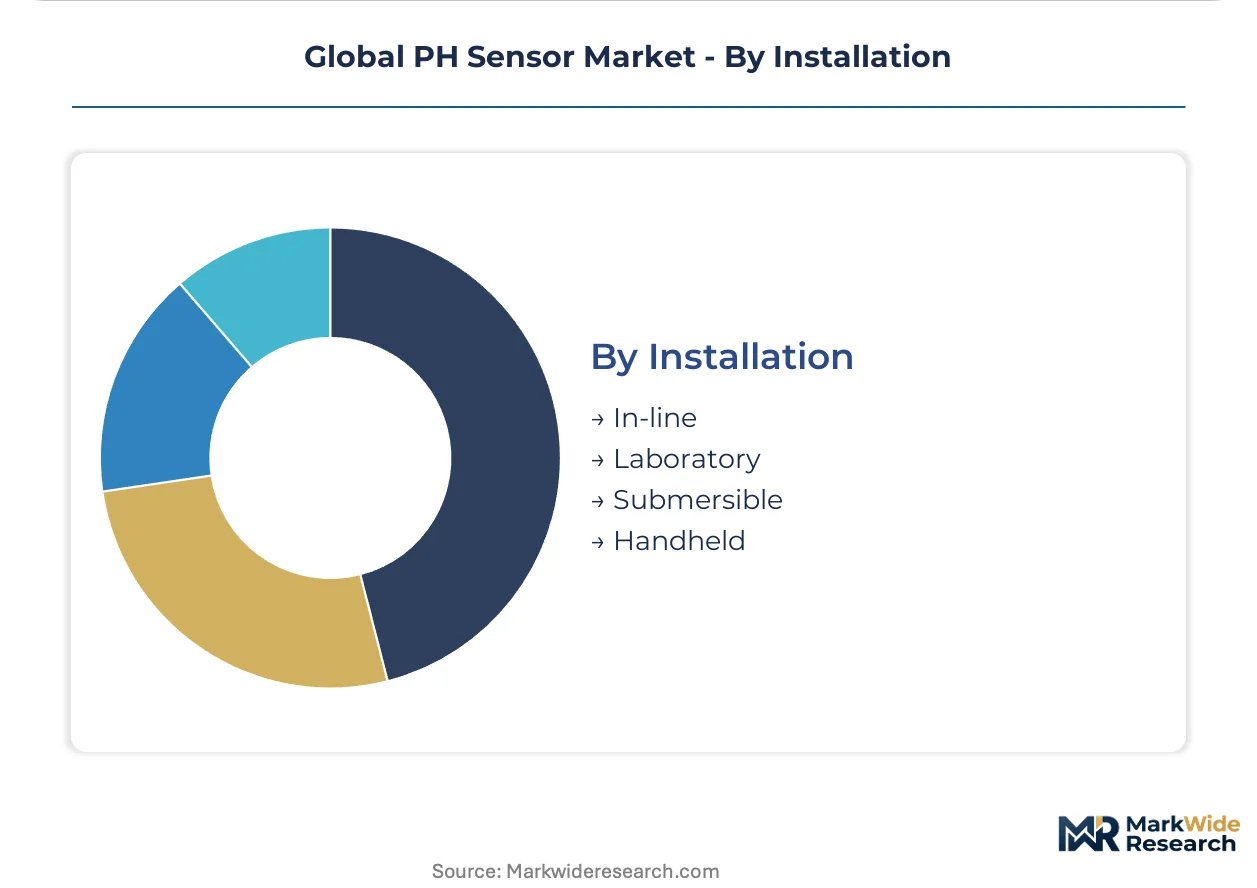
| Segmentation | Product Type: Analog Sensors, Digital Sensors, Industrial Sensors, Portable Sensors Technology: Glass Electrode, ISFET, Optical, Solid State End User: Water Treatment, Food & Beverage, Pharmaceuticals, Chemical Processing Installation: In-line, Laboratory, Submersible, Handheld |
| Companies Covered | Honeywell International Inc., ABB Ltd., Thermo Fisher Scientific Inc., Yokogawa Electric Corp., Hach Co., Endress+Hauser Group Services AG, Emerson Electric Co., Mettler-Toledo, Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PH Sensor Market Strategic Shifts
Electrochemical transduction is yielding to solid-state and optical alternatives, while regulatory documentation requirements and service model unbundling reshape how sensors are specified, purchased, and maintained across industrial verticals.
ISFET technology is collapsing the minimum viable form factor for pH sensing. Silicon microfabrication deposits the sensing element, reference electrode, and temperature compensation onto single chips measuring millimeters across. Pharmaceutical cleanroom operators in Switzerland and Singapore now embed these chips directly into disposable bioreactor bags, eliminating sterilization validation burdens. The technology is collapsing capital barriers to continuous monitoring in single-use manufacturing workflows.
REACH substance restrictions on mercury-containing reference electrodes force European sensor vendors to accelerate solid-state reference architectures. The regulation eliminates a calibration stability advantage that glass electrodes held over ISFET alternatives, accelerating displacement timelines. German chemical processors now specify mercury-free designs as procurement defaults, compressing competitive windows for legacy product lines.
Service unbundling is fragmenting the traditional sensor procurement bundle. Industrial buyers in the United States increasingly separate hardware acquisition from calibration contracts, pitting specialized metrology service firms against manufacturer field organizations. Chemical processing clusters along the Texas Gulf Coast now source sensors through distributors while contracting third-party technicians for EPA-mandated documentation, compressing vendor margin capture.
Global PH Sensor Market Segmentation
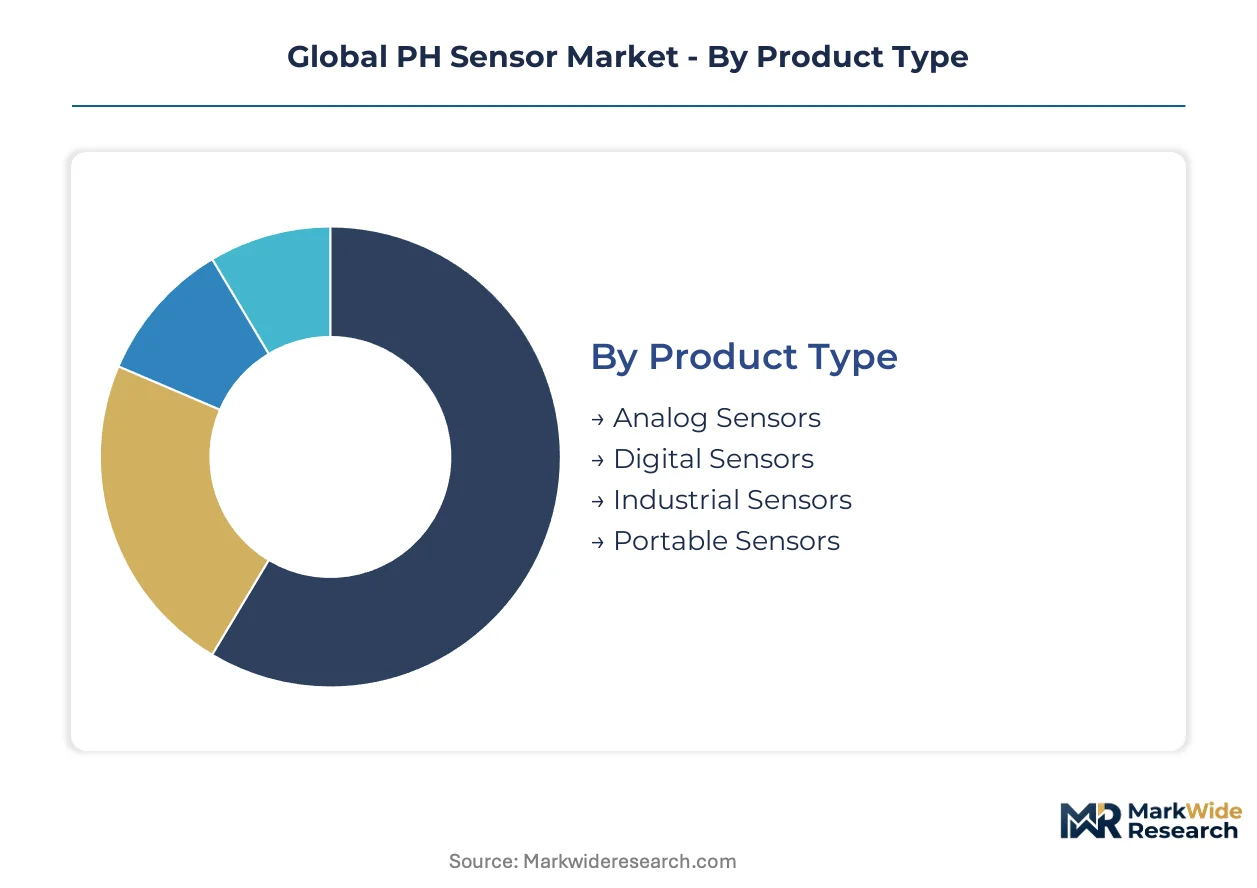
pH sensor procurement patterns diverge sharply across product formats, with digital architectures commanding premium positioning while analog systems defend installed-base replacement cycles. Technology selection increasingly determines total cost of ownership calculations as solid-state alternatives disrupt traditional electrode economics.
Product Type:
Mature analog designs coexist with emerging digital platforms, creating a bifurcated procurement landscape where specification engineers weigh capital expenditure against lifecycle calibration burdens.
- Analog Sensors:Continuous 4-20mA output signals dominate legacy process control infrastructure across German chemical processing corridors. BASF and Bayer facilities along the Rhine maintain extensive analog fleets despite digital migration pressures, constrained by brownfield integration costs and technician retraining timelines.
- Digital Sensors:Embedded diagnostics and predictive maintenance algorithms reduce unplanned downtime in pharmaceutical continuous manufacturing. Thermo Fisher and ABB deploy these platforms for FDA process analytical technology compliance, where ±0.01 pH accuracy tolerances mandate automated calibration logging.
- Industrial Sensors:Harsh-environment housings withstand CIP/SIP washdown cycles in dairy processing plants.
- Portable Sensors:Battery-powered handheld units serve field auditing applications in China's provincial environmental enforcement.
Analog sensors retain volume leadership across installed-base replacement cycles; digital sensors hold the steepest expansion curve as regulatory documentation requirements tighten.
Technology:
Cost tiers separate mature glass electrode production from emerging silicon-chip fabrication, with optical methods occupying specialized niches where electrical interference disqualifies conductive sensing.
- Glass Electrode:Specialized borosilicate membrane formulations deliver Nernstian response across 0-14 pH range with temperature compensation circuits. German and Japanese specialty glass foundries concentrate supply, creating single-source vulnerability for traditional reference electrode assemblies dependent on palladium and platinum coatings.
- ISFET:Silicon microfabrication deposits sensing element, reference electrode, and temperature compensation onto single chips measuring millimeters across. Swiss and Singaporean pharmaceutical cleanroom operators embed these into disposable bioreactor bags, eliminating sterilization validation burdens in single-use manufacturing workflows.
- Optical:Fluorescent dye-based systems capture bioreactor applications where electromagnetic interference compromises electrode performance.
- Solid State:Polymer-based reference architectures eliminate mercury content for REACH compliance in European procurement specifications.
Glass electrode technology anchors current installed-base revenue; ISFET platforms are climbing the fastest as miniaturization opens medical diagnostics and wearable monitoring applications.
End User:
Application-specific accuracy requirements and regulatory exposure create distinct customer segments with divergent procurement authority structures and validation timelines.
- Water Treatment:Municipal utilities in Germany and the United States deploy continuous monitoring to meet tightening effluent discharge rules under the EU Urban Waste Water Treatment Directive and EPA Clean Water Act frameworks. Real-time pH reporting mandates from China's provincial environmental bureaus drive industrial wastewater monitoring deployments in Jiangsu and Zhejiang chemical processing zones.
- Pharmaceuticals:FDA process analytical technology initiatives mandate in-line pH monitoring as a critical process parameter, accelerating validation protocols for sensor suppliers. Hyderabad and Ahmedabad manufacturing clusters lack validated infrastructure, creating first-mover openings for FDA-compliant digital platforms.
- Food & Beverage:Continuous pH tracking in dairy and brewing operations remains underpenetrated outside Western Europe.
- Chemical Processing:China's MEE incentivizes sensor-driven chemical dosing optimization for dual carbon goals alignment.
Water treatment commands current procurement volume; pharmaceutical applications are expanding most quickly as continuous manufacturing adoption accelerates validation-grade sensor demand.
Installation:
Volume concentration favors permanent process integration over portable auditing equipment, though field calibration requirements sustain handheld demand for regulatory documentation.
- In-line:Direct process integration enables real-time chemical dosing adjustment with automated control loop feedback. Texas Gulf Coast petrochemical clusters specify these for EPA-mandated effluent monitoring, increasingly separating hardware acquisition from third-party calibration contracts.
- Laboratory:Benchtop configurations serve quality control validation with ±0.01 pH accuracy tolerances for pharmaceutical release testing.
- Submersible:Immersion-rated housings withstand continuous exposure in municipal aeration basins and clarifier systems.
- Handheld:Portable units support spot-check auditing and regulatory field inspections across distributed treatment networks.
In-line installations dominate capital expenditure allocation; laboratory-grade systems are gaining share fastest as pharmaceutical quality control automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine River chemical corridor connects Germany's industrial heartland to Rotterdam's port infrastructure, anchoring Europe's densest concentration of continuous process monitoring installations. This waterway network underwrites sustained sensor replacement cycles across continental chemical processing.
United States
Texas Gulf Coast petrochemical clusters drive in-line pH monitoring deployments for EPA-mandated effluent documentation. The EPA Clean Water Act enforcement tightens calibration record-keeping requirements, pushing utilities toward digitally certified platforms. Houston-area refineries increasingly separate hardware procurement from third-party metrology service contracts.
Germany
Rhine-Main industrial zones anchor municipal utility sensor modernization under the EU Urban Waste Water Treatment Directive. BASF and Bayer facilities along the Ludwigshafen corridor maintain extensive analog fleets constrained by brownfield integration costs. REACH substance restrictions on mercury-containing electrodes accelerate solid-state reference architecture adoption.
China
Jiangsu and Zhejiang provincial environmental bureaus enforce real-time pH reporting from chemical processing zones along the Yangtze River Delta. The MEE dual carbon goals incentivize sensor-driven chemical dosing optimization for energy efficiency. Shanghai's industrial wastewater monitoring sector commands the steepest deployment curve.
India
Hyderabad and Ahmedabad pharmaceutical manufacturing corridors lack validated in-line pH monitoring infrastructure for FDA process analytical technology compliance. CDSCO regulatory alignment with international standards accelerates validation-grade sensor demand. Gujarat's chemical processing belt drives industrial wastewater monitoring procurement.
Switzerland
Basel-region pharmaceutical cleanrooms embed ISFET chips directly into disposable bioreactor bags, eliminating sterilization validation burdens. Swissmedic manufacturing standards mandate continuous process parameter monitoring for biologics production. The country's precision instrumentation heritage supports specialized sensor calibration service networks.
Global PH Sensor Market Competitive Environment
On the supply side, the industry is consolidating around integrated process control platforms that bundle sensing hardware with predictive maintenance software. Tiered competitive positioning separates multi-industry conglomerates with building automation channels from specialized metrology firms with laboratory-grade accuracy credentials. Strategic archetypes include full-stack automation vendors, precision instrument specialists, and regional calibration service providers. Dominant competitive moves encompass long-term service agreement anchoring and silicon-chip fabrication integration for solid-state miniaturization.
Among diversified industrial technology conglomerates, Honeywell International Inc. and ABB Ltd. exemplify platform bundling strategies that leverage existing building automation and process control channels. Thermo Fisher Scientific Inc. occupies a position within the precision instrumentation tier, representing laboratory-grade specialization where accuracy tolerances mandate automated calibration logging. These three anchors illustrate how vendor positioning stratifies between scale-driven system integration and accuracy-driven metrology expertise.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd. |
| Thermo Fisher Scientific Inc. |
| Yokogawa Electric Corp. |
| Hach Co. |
| Endress+Hauser Group Services AG |
| Emerson Electric Co. |
| Mettler-Toledo |
| Hamilton Company |
| Others |
Value Chain & Pricing Dynamics
Platinum group metal volatility in reference electrode assemblies compresses gross margins while simultaneously widening pricing tier spreads between mercury-compliant legacy designs and REACH-certified solid-state alternatives. This input-cost instability forces sensor vendors to restructure procurement contracts and accelerate silicon-chip fabrication partnerships that decouple pricing from precious metal spot markets.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade digital platforms with ±0.01 pH accuracy from standard industrial analog sensors. Pricing stratifies across FDA-validated premium tiers, EPA-compliant standard tiers, and economy tiers for non-regulated process monitoring. Cost compression in the analog segment is intensifying because ISFET miniaturization collapses capital barriers for point-of-use applications. Municipal utilities exhibit highest price sensitivity due to public procurement constraints, while pharmaceutical manufacturers prioritize accuracy over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in specialized borosilicate glass formulations draws from German and Japanese specialty foundries, creating single-source vulnerability for traditional electrode membranes. Palladium and platinum coatings for reference electrodes hinge on South African and Russian mining output. Tariff exposure on Chinese-manufactured ISFET silicon wafers compounds cost uncertainty. Distribution runs through building automation channel partners for bundled process control packages and direct field service networks for calibration-dependent utility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pH sensor market functions as a service-attach opportunity where predictive maintenance software and calibration documentation subscriptions expand faster than hardware unit sales. Recurring revenue from EPA-mandated compliance logging and FDA validation protocols now exceeds sensor replacement cycles in lifetime value calculations.
For Market Incumbents: Insulate installed-base revenue by anchoring long-term calibration service agreements before third-party metrology firms capture documentation mandates. Acquire silicon-chip fabrication capabilities or exclusive ISFET foundry partnerships to secure supply chain control against platinum group metal volatility. Lock pharmaceutical cleanroom operators into disposable bioreactor bag-embedded chip supply contracts that eliminate sterilization validation burdens for competitors. For New Entrants and Emerging Players: Build out FDA-compliant digital sensor platforms targeting Hyderabad and Ahmedabad pharmaceutical corridors where validated in-line monitoring infrastructure remains underdeveloped. Penetrate food safety automation in dairy and brewing operations outside Western Europe using ISFET durability against harsh CIP/SIP washdown cycles. Pursue direct distribution to industrial end users rather than competing through consolidated field service networks dominated by incumbents. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision instrumentation specialists with silicon-fabrication integration over diversified conglomerates dependent on glass electrode legacy portfolios. Long-term viability centers on vendors controlling both solid-state reference architectures and predictive maintenance algorithm development. Watch ISFET cost curves crossing glass electrode parity as the inflection signal for accelerated displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Chip Fabrication Integration | Enables ISFET miniaturization for disposable bioreactor applications in Swiss pharmaceutical manufacturing. |
| Calibration Service Unbundling | Separates hardware procurement from EPA-mandated documentation contracts along Texas Gulf Coast chemical clusters. |
| REACH-Compliant Reference Architecture | Eliminates mercury content for European procurement defaults under ECHA substance restrictions. |
| Predictive Maintenance Algorithm Development | Reduces unplanned downtime in pharmaceutical continuous manufacturing under FDA process analytical technology. |
| Regional Foundry Partnership | Secures borosilicate glass supply against German and Japanese specialty foundry concentration risk. |
Study Parameters
Cross-validation between primary interviews with plant engineers, metrology technicians, and procurement leads at municipal utilities and pharmaceutical manufacturers anchors the qualitative findings. Secondary validation draws from EPA effluent limitation guidelines, EU Urban Waste Water Treatment Directive enforcement records, FDA process analytical technology guidance documents, and SEC filings of diversified industrial technology conglomerates. Bottom-up sensor deployment counts across Jiangsu and Zhejiang chemical processing zones triangulate against top-down market sizing from process control automation expenditure data.
Calibration against historical replacement cycles in German Rhine-Main industrial zones and Texas Gulf Coast petrochemical clusters refines the analytical framework. Modeled segmentation spans analog versus digital product formats, glass electrode versus ISFET versus optical technology tiers, and water treatment versus pharmaceutical versus food and beverage end-use verticals. CAGRs derive from regression analysis of regulatory enforcement timelines and silicon fabrication cost curve projections. Forecast inputs incorporate REACH substance restriction implementation schedules and China's MEE dual carbon goals enforcement intensity.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration into ISFET foundry capacity by Honeywell or ABB would shift competitive outcomes beyond modeled parameters. Cross-checking against customs data on borosilicate glass import volumes and platinum group metal price indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Motion Control Encoders Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Acoustic Breathing Sensor Market