
 Underwater Ultrasonic Sensor Market | 2026-2036
Underwater Ultrasonic Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Ultrasonic Sensor Market Insights
China is tilting toward domestic production of high-frequency piezoelectric ceramics for subsea sensing arrays. Teledyne Technologies Incorporated leverages its vertical integration across transducer manufacturing and signal processing modules. Kongsberg Gruppen ASA anchors its position through R&D intensity in multibeam echo sounder architectures. L3Harris Technologies, Inc. competes on defense-grade underwater imaging systems with hardened telemetry protocols.
An underwater ultrasonic sensor converts electrical energy into acoustic pressure waves, typically operating between 10 kHz and 2 MHz, to detect objects or map submerged terrain through time-of-flight measurement. Its primary industrial purpose is to enable non-contact sensing in opaque aquatic environments where optical or electromagnetic methods fail. Transducers command the largest installed base due to their ubiquity across sonar platforms, while digital signal processing architectures represent the fastest-expanding technology segment as navies and research institutes replace legacy analog front ends. Echo sounders retain stable margins in commercial fishing and hydrographic survey contracts where calibration certification creates switching costs.
The International Maritime Organization's performance standards for navigation equipment shape transducer accuracy requirements for merchant vessels. The EU Marine Strategy Framework Directive and the U.S. NOAA hydrographic survey standards collectively drive demand for certified depth measurement systems in territorial waters. China's GB standards for marine electronic equipment add a parallel compliance layer for suppliers accessing port infrastructure projects. Stakeholders must weigh certification investments against the fragmentation of national approval pathways as procurement specifications diverge.
Market Dynamics
The EU Marine Strategy Framework Directive is compressing procurement timelines for certified seabed monitoring systems, forcing sensor manufacturers to pre-certify hardware against divergent national hydrographic standards before contract bidding.
Growth Catalysts
- Offshore decommissioning mandates:Norway's Petroleum Safety Authority requires legacy platform inspection using multibeam echo sounder arrays, creating replacement demand for aging analog sonar infrastructure.
- Marine protected area expansion:The EU Marine Strategy Framework Directive mandates continuous benthic habitat monitoring, pulling high-frequency transducer orders from research institutes and environmental consultancies.
- Piezoelectric ceramic localization:China's domestic production of high-frequency ceramic substrates is reducing import dependency for subsea sensing arrays deployed in port infrastructure projects.
Market Restraints
- Transducer material cost volatility:Lead zirconate titanate ceramic supply concentrates among Japanese and Chinese specialty chemical producers, exposing sensor assemblers to rare earth price swings.
- Calibration certification fragmentation:Divergent national hydrographic survey standards between the U.S. NOAA, the EU, and China's GB protocols force redundant testing investments for multi-jurisdiction suppliers.
- Acoustic interference saturation:Dense sonar deployment in the North Sea corridor creates signal cross-talk that degrades measurement accuracy below regulatory thresholds.
Strategic Opportunities
- Autonomous underwater vehicle integration:Swarm-deployable micro-transducers for AUV docking and navigation represent unserved demand from offshore wind farm operators in the North Sea.
- Dual-use defense-commercial crossover:Hardened telemetry protocols developed for naval mine countermeasures are migrating into commercial pipeline inspection contracts with stricter cybersecurity clauses.
- Real-time seabed monitoring as-a-service:Subscription-based data delivery models are displacing capital-heavy sensor ownership for smaller hydrographic survey contractors in Norway and the UK.
Industry Challenges
- Acoustic engineer scarcity:Specialized expertise in transducer array design and beamforming algorithms concentrates among aging workforces at legacy sonar manufacturers.
- Legacy analog front-end replacement complexity:Digital signal processing retrofits require hardware-software integration that exceeds in-house capabilities at mid-sized fishing fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Ultrasonic Sensor Market |
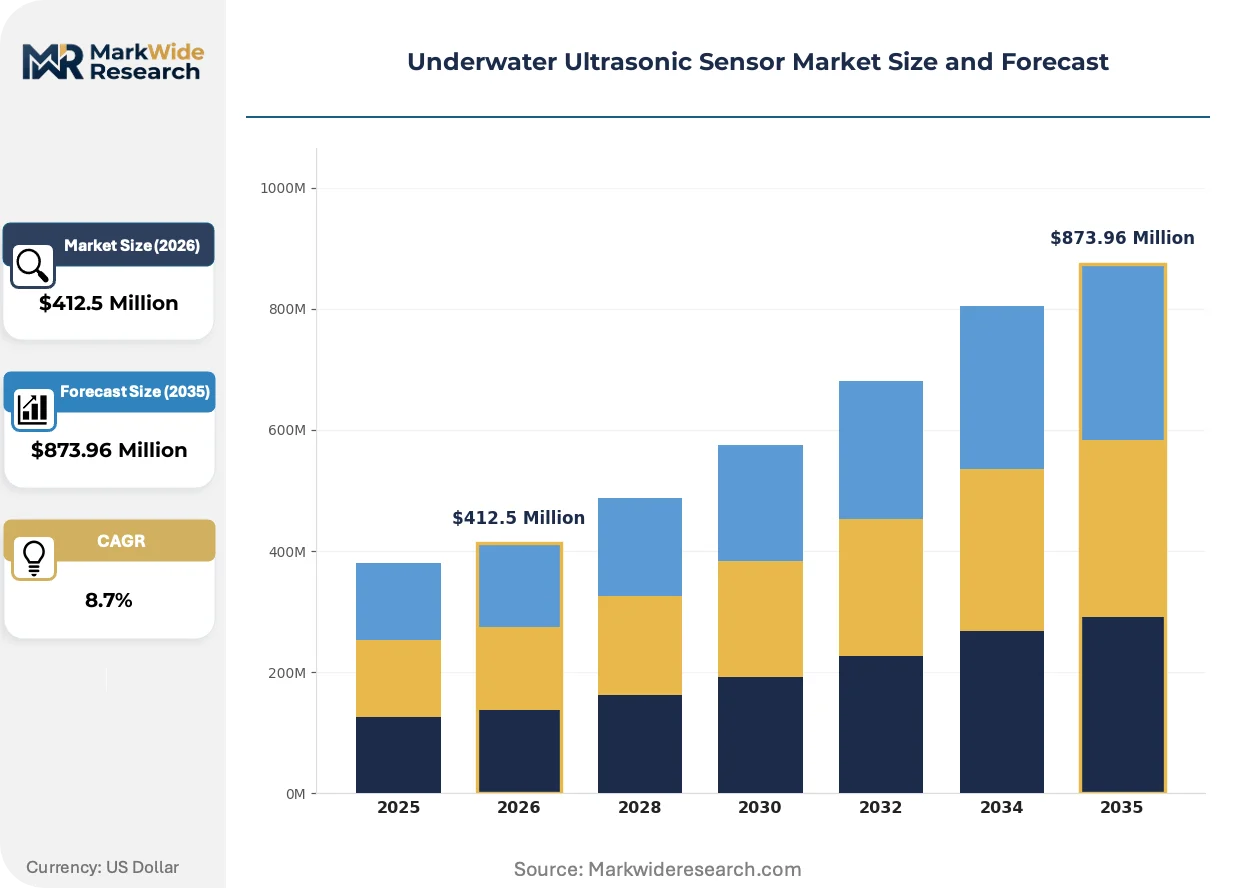
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transducers, Echo Sounders, Fish Finders, Underwater Imaging Systems End User: Marine Research, Oil & Gas, Defense, Aquaculture Application: Surface Mapping, Depth Measurement, Object Detection, Marine Mammal Monitoring Technology: Analog, Digital, Wireless, Passive |
| Companies Covered | Teledyne Technologies Incorporated, Kongsberg Gruppen ASA, Lockheed Martin Corporation, Thales S.A., L3Harris Technologies, Inc., Furuno Electric Co., Ltd., Garmin Ltd., RTX Corporation, Amphenol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Ultrasonic Sensor Market Trends and Innovations
Digital signal processing architectures are compressing the performance gap between commercial and defense-grade sonar, while regulatory data-sharing mandates are forcing interoperability investments across previously proprietary platforms.
Phased array transducer technology is migrating from naval mine-hunting platforms to commercial offshore wind turbine foundation inspection. European energy majors are adopting these systems to reduce dive-team dependency in high-current North Sea conditions. The technology shift is compressing contract durations for traditional bathymetric survey firms that rely on single-beam mechanical scanning.
The EU Marine Strategy Framework Directive's benthic habitat reporting requirements are mandating standardized data formats for seabed classification outputs. Hydrographic survey contractors must now deliver interoperable acoustic backscatter datasets to national environmental agencies. This regulatory pressure is most acute in the North Sea corridor, where Norwegian and UK regulators coordinate cross-border habitat assessments.
Sensor manufacturers are unbundling hardware sales from post-deployment calibration services. Offshore oil and gas operators in Norway now procure transducer arrays separately from multiyear measurement accuracy contracts. This service model rotation is visible among North Sea drilling contractors seeking to convert capital expenditures into operational budget line items.
Underwater Ultrasonic Sensor Market Segmentation
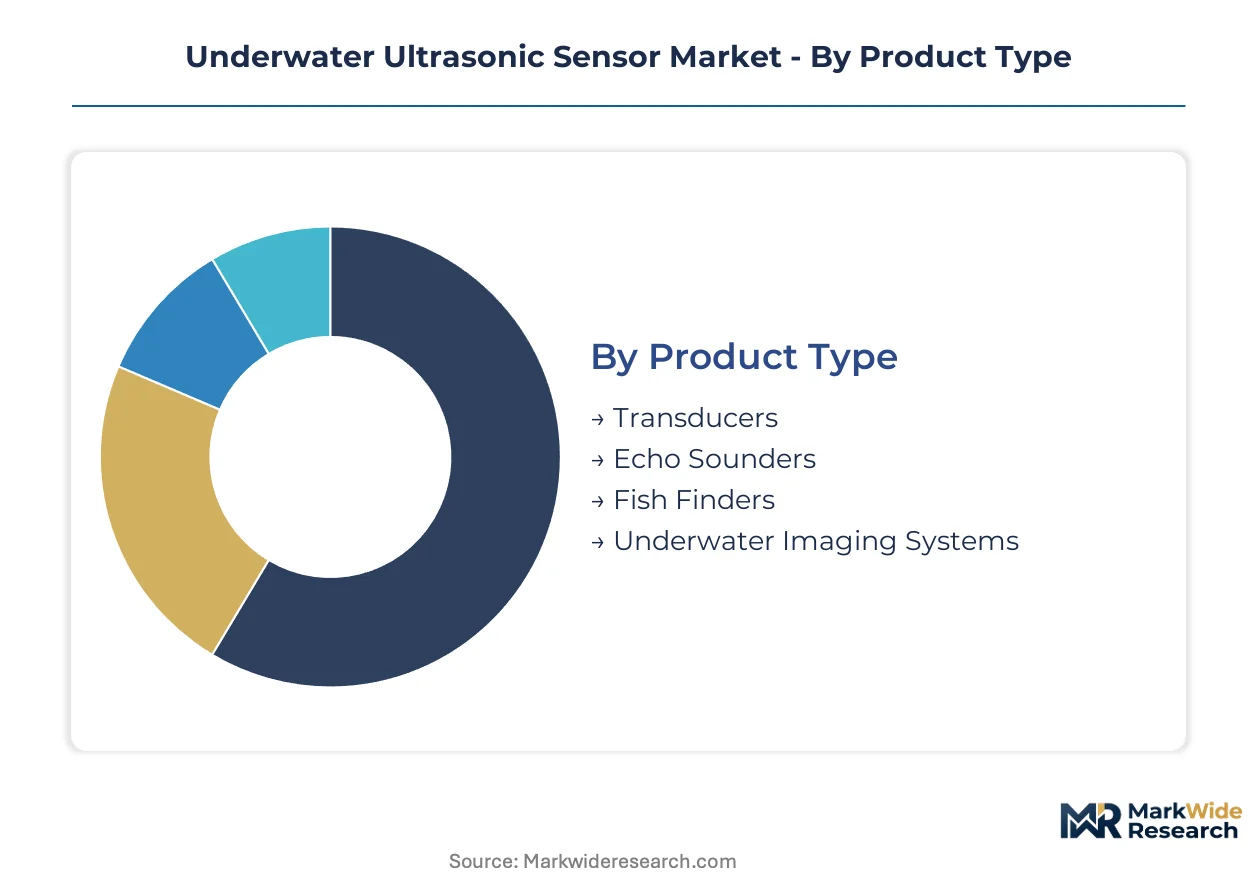
Underwater ultrasonic sensor procurement diverges sharply across operational environments, with defense-grade specifications demanding hardened telemetry while aquaculture favors cost-optimized bulk deployments. Understanding these segment boundaries clarifies where technology premiums command pricing power versus where standardization drives margin compression.
Product Type:
Mature hardware categories with established certification pathways dominate installed base economics, while emerging digital-native formats are capturing replacement cycles in legacy analog fleets.
- Transducers:Piezoelectric ceramic assemblies converting electrical pulses to acoustic pressure waves, typically housed in oil-filled or polyurethane boots for pressure tolerance. Demand concentrates in Norway's North Sea corridor where multibeam arrays replace aging single-beam units under Petroleum Safety Authority inspection mandates.
- Echo Sounders:Integrated transceiver packages with embedded signal processing for depth measurement and bottom classification. Commercial fishing fleets and hydrographic survey contractors in UK territorial waters drive orders where calibration certification against NOAA standards creates switching costs.
- Fish Finders:Single-frequency or chirp-enabled consumer-grade units for recreational and small-scale commercial vessels.
- Underwater Imaging Systems:High-resolution sonar arrays for seabed mapping and infrastructure inspection.
Transducers retain volume leadership across the installed base; underwater imaging systems hold the steepest expansion curve as offshore wind developers substitute sonar surveys for dive-team inspections.
End User:
Defense and oil & gas procurement operates on multi-year capital cycles with embedded service contracts, while marine research and aquaculture purchasing follows grant funding and seasonal harvest patterns respectively.
- Marine Research:University and government laboratory deployments for benthic habitat mapping and climate monitoring. EU Marine Strategy Framework Directive reporting requirements in the North Sea corridor pull high-frequency transducer orders from environmental consultancies coordinating cross-border assessments.
- Oil & Gas:Subsea infrastructure inspection and pipeline survey operations. Norway's offshore decommissioning mandates require legacy platform assessment using certified multibeam systems, generating replacement demand for analog sonar infrastructure approaching end-of-service life.
- Defense:Naval mine countermeasures, submarine navigation, and harbor security applications.
- Aquaculture:Net pen monitoring and predator detection for salmon and shellfish operations.
Oil & gas retains volume leadership in value terms; marine research holds the steepest expansion curve as benthic monitoring mandates proliferate across European territorial waters.
Application:
Surface mapping and depth measurement applications carry established regulatory certification requirements, while object detection and marine mammal monitoring face evolving technical standards.
- Surface Mapping:Bathymetric survey and seabed terrain modeling for nautical chart production. Hydrographic agencies in Norway and the UK coordinate cross-border habitat assessments under EU Marine Strategy Framework Directive data-sharing protocols.
- Depth Measurement:Navigation safety and dredging operations requiring certified accuracy. Merchant vessel compliance with International Maritime Organization performance standards sustains transducer replacement cycles in commercial shipping corridors.
- Object Detection:Pipeline inspection, wreck location, and debris identification.
- Marine Mammal Monitoring:Passive acoustic monitoring for cetacean presence detection.
Depth measurement retains volume leadership; marine mammal monitoring is expanding most quickly as offshore wind developers face mandatory pre-construction baseline surveys.
Technology:
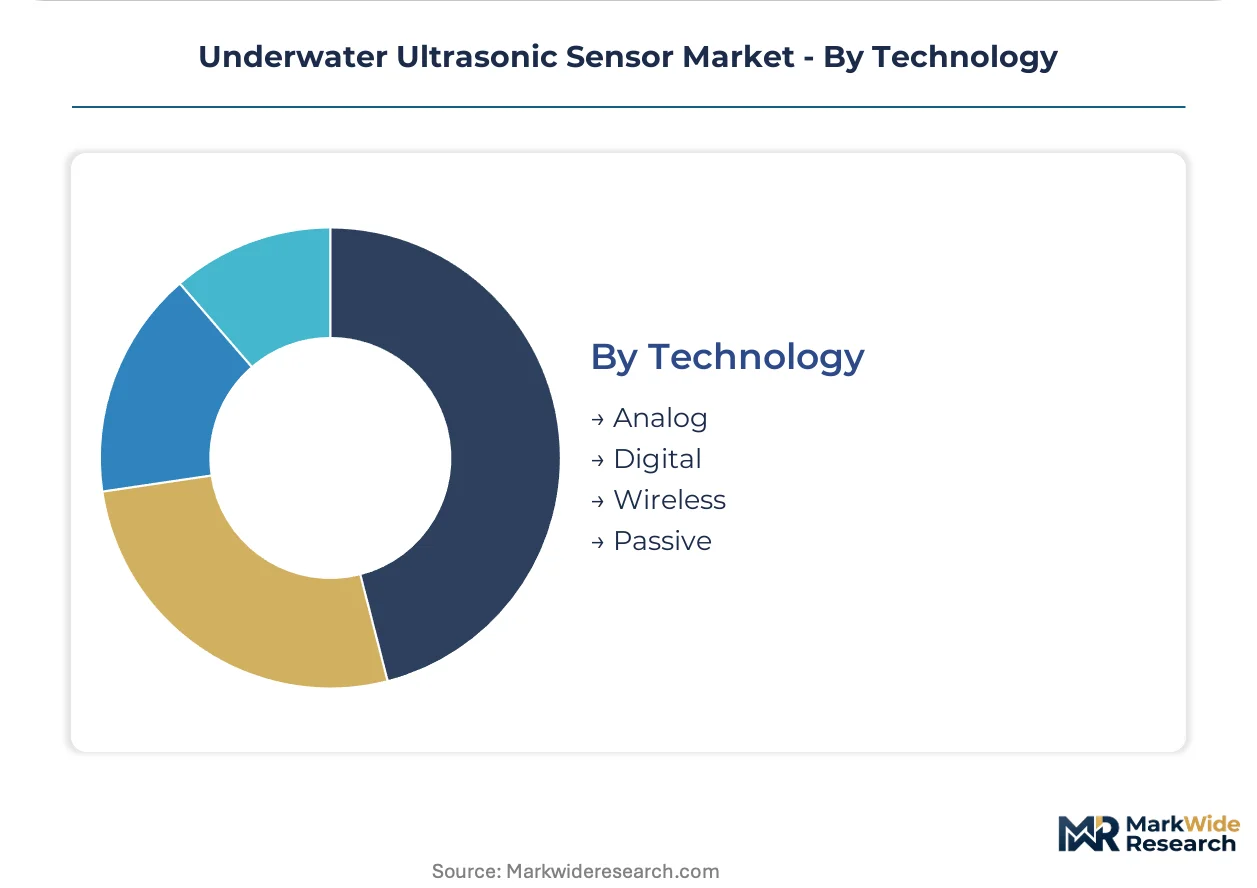
Analog architectures still dominate legacy installed bases, though procurement is tilting toward digital and wireless formats as navies and research institutes modernize front-end processing capabilities.
- Analog:Legacy transducer designs with discrete component signal conditioning. Mid-sized fishing fleet operators in Norway face hardware-software integration complexity when retrofitting digital processing capabilities.
- Digital:Embedded DSP architectures with software-defined beamforming and real-time filtering. Defense-grade implementations with hardened telemetry protocols are migrating into commercial pipeline inspection contracts with stricter cybersecurity clauses.
- Wireless:Acoustic modem and networked sensor arrays for AUV integration.
- Passive:Receive-only hydrophone arrays for ambient noise and mammal monitoring.
Analog retains volume leadership in installed base terms; digital is gaining share fastest as procurement specifications mandate software-upgradeable architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ceramic substrate production clusters in Japan and China supply the dominant share of piezoelectric transducer materials, while final sensor assembly concentrates near North Sea offshore energy corridors and Western defense procurement hubs.
Norway
Petroleum Safety Authority decommissioning mandates for legacy platforms drive multibeam echo sounder replacement cycles. The EU Marine Strategy Framework Directive coordinates cross-border seabed monitoring with UK regulators. Stavanger and Bergen host concentrated subsea inspection contractor clusters executing platform surveys.
United States
NOAA hydrographic survey standards enforce certified depth measurement procurement for territorial water mapping contracts. The International Maritime Organization performance standards shape transducer accuracy requirements for merchant vessel navigation safety. Gulf Coast ports and Pacific Northwest shipyards sustain replacement demand for commercial fishing fleet sonar systems.
China
Domestic high-frequency piezoelectric ceramic production reduces import dependency for port infrastructure sensing arrays. GB standards for marine electronic equipment create parallel compliance requirements for equipment suppliers. Yangtze River Delta shipyards and South China Sea port expansion projects anchor regional demand concentration.
United Kingdom
Offshore wind farm developers face mandatory pre-construction marine mammal baseline surveys pulling high-frequency transducer orders. The EU Marine Strategy Framework Directive benthic habitat reporting requirements standardize acoustic backscatter data formats. Aberdeen and Great Yards marine clusters coordinate North Sea corridor cross-border assessments with Norwegian counterparts.
Germany
Industrial sonar component fabrication supplies transducer assemblies to European hydrographic survey contractors. CE marking and EU Marine Strategy Framework Directive compliance shape hardware certification pathways for seabed monitoring equipment. Hamburg and Bremerhaven port technology clusters drive precision navigation sensor demand.
Underwater Ultrasonic Sensor Market Competitive Landscape
Defense-electronics conglomerates and specialized maritime technology firms split the market into distinct capability tiers. Consolidation pressure concentrates among transducer material suppliers and digital signal processing module integrators. Two strategic archetypes dominate: vertically integrated sensor-platform builders and component-specialist suppliers focused on ceramic substrate or telemetry subsystems. Competitive moves center on backward integration into piezoelectric material supply and technology licensing agreements for hardened data transmission protocols.
Within the defense-grade imaging tier, L3Harris Technologies, Inc. and Teledyne Technologies Incorporated exemplify hardened telemetry protocol development. Kongsberg Gruppen ASA anchors the multibeam echo sounder architecture specialization segment. These three entities occupy positions spanning the technology spectrum from ceramic transducer fabrication through integrated sonar platform delivery, representing the dominant competitive anchors in procurement specifications across North Sea offshore energy and naval mine countermeasures applications.
| Leading Market Players |
|---|
| Teledyne Technologies Incorporated |
| Kongsberg Gruppen ASA |
| Lockheed Martin Corporation |
| Thales S.A. |
| L3Harris Technologies, Inc. |
| Furuno Electric Co., Ltd. |
| Garmin Ltd. |
| RTX Corporation |
| Amphenol Corporation |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta ceramic substrate producers anchor global piezoelectric material supply, with their capacity utilization rates directly transmitting into transducer assembly pricing power for North Sea sensor manufacturers facing decommissioning contract deadlines.
Pricing Analysis
The EU Marine Strategy Framework Directive dictates the pricing tier structure across the underwater ultrasonic sensor market, separating certified multibeam systems for seabed monitoring from uncertified single-beam units. Three-tier pricing structure across premium, standard, and economy levels reflects calibration grade against national hydrographic standards and bundled post-deployment service contracts. Cost compression in economy-tier fish finder segments is intensifying because Chinese domestic ceramic production erodes material cost premiums. Commercial fishing fleet operators exhibit highest price sensitivity, while defense procurement offices prioritize hardened telemetry over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese specialty chemical producers to transducer assemblers are compressing working capital cycles throughout the supply chain. Manufacturing concentrates in China, Japan, and Germany, with piezoelectric ceramic substrates, signal processing modules, and polyurethane pressure housings as critical inputs. Single-source vulnerability in lead zirconate titanate ceramic supply exposes sensor manufacturers to rare earth price volatility. Distribution runs through offshore energy service contractors in Norway and hydrographic survey firms in the UK.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as regulatory data-sharing mandates splinter procurement specifications across national hydrographic authorities, creating niche openings for specialized certification service providers and regional sensor integrators.
For Market Incumbents: Build certification moats by pre-qualifying hardware against divergent EU, US, and Chinese standards before contract bidding cycles compress. Anchor backward integration into piezoelectric ceramic supply to offset Japanese and Chinese material cost volatility. Capture replacement demand from Norway's Petroleum Safety Authority decommissioning mandates by embedding multiyear calibration service contracts.
For New Entrants and Emerging Players: Build out swarm-deployable micro-transducer architectures for autonomous underwater vehicle navigation in North Sea offshore wind installations. Target marine research institutes in the UK facing EU Marine Strategy Framework Directive benthic habitat reporting requirements. Lead with subscription-based real-time seabed monitoring as-a-service to displace capital-heavy sensor ownership among smaller hydrographic contractors.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-commercial crossover play because hardened telemetry protocols developed for naval mine countermeasures are migrating into commercial pipeline inspection with stricter cybersecurity clauses. Acquisition targets should cluster around digital signal processing module integrators with software-defined beamforming capabilities. Watch for acoustic interference saturation thresholds in the North Sea corridor forcing regulatory intervention on sonar deployment density.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Supply | Captures margin from Japanese and Chinese piezoelectric material producers while hedging rare earth price volatility. |
| Pre-Certification Against Divergent National Standards | Compresses procurement timelines for EU Marine Strategy Framework Directive seabed monitoring contracts. |
| Subscription-Based Monitoring-as-a-Service Launch | Converts capital expenditures to operational budgets for Norwegian and UK hydrographic survey contractors. |
| Swarm-Deployable Micro-Transducer Development | Addresses unserved demand from North Sea offshore wind farm operators for AUV docking and navigation. |
| Dual-Use Defense-Commercial Protocol Migration | Transfers hardened naval mine countermeasures telemetry into commercial pipeline inspection cybersecurity clauses. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with subsea inspection contractors, hydrographic survey firm technical directors, offshore oil and gas procurement officers, defense electronics program managers, and piezoelectric ceramic material suppliers. Secondary validation drew from EU Marine Strategy Framework Directive implementation reports, NOAA hydrographic survey standards documentation, China's GB standards for marine electronic equipment, International Maritime Organization performance standards, and customs trade data on piezoelectric ceramic substrate flows. Bottom-up segment sizing triangulated against top-down market aggregation.
Calibration against historical replacement cycles in Norway's North Sea corridor and documented procurement patterns under Petroleum Safety Authority mandates anchored volume projections across the analysis window. Segmentation dimensions modeled include product type, end user archetype, application environment, and technology architecture. CAGRs derived from regression analysis of certified system deployment rates against regulatory deadline schedules, with cross-reference to analog-to-digital retrofit penetration curves in commercial fishing fleets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated defense-electronics conglomerates or state-backed Chinese ceramic producers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Fingerprint Module Market