
 Embolic Protection Systems Market | 2026-2036
Embolic Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Embolic Protection Systems Market Foresight
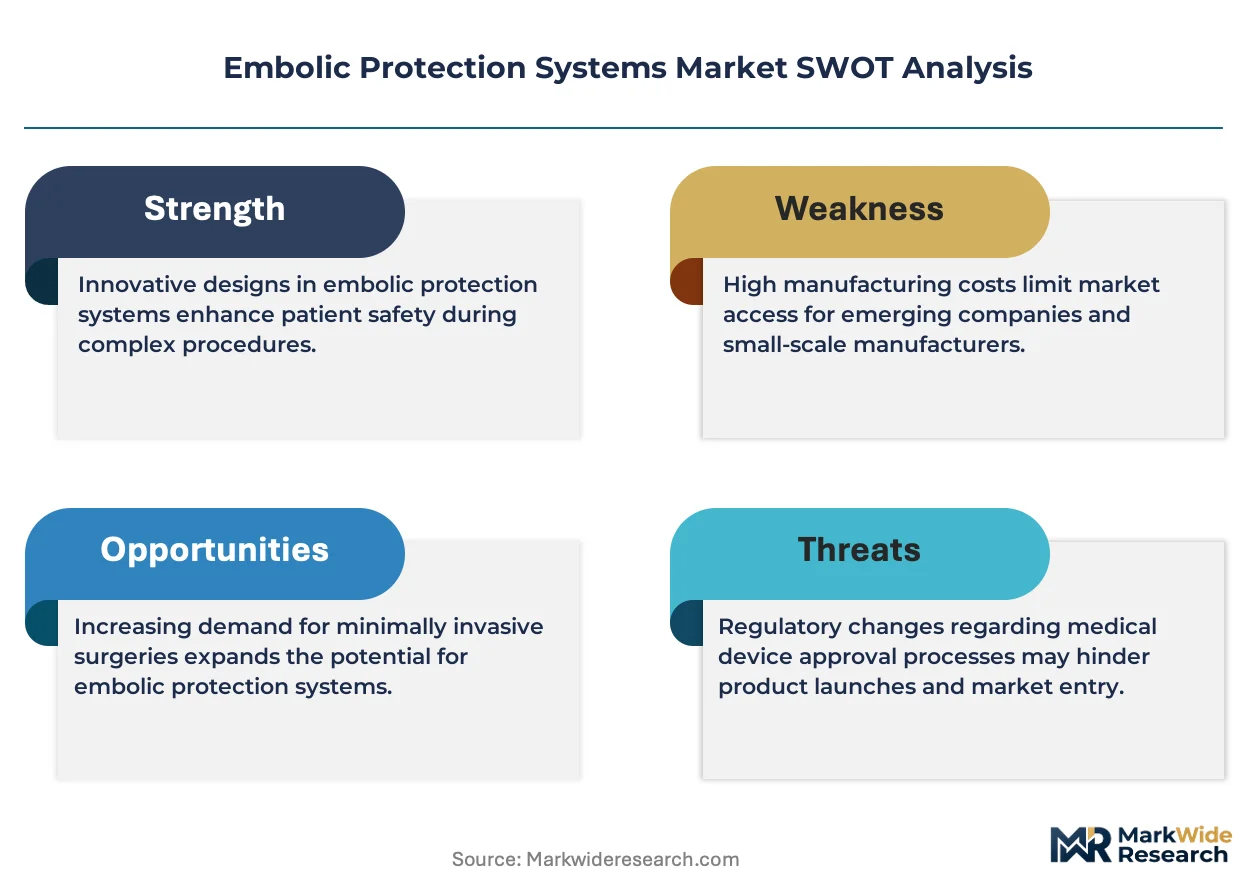
Consolidation among integrated health systems is recalibrating procurement leverage for embolic protection devices. Boston Scientific Corporation sustains broad catheterization lab penetration through its interventional portfolio depth. Abbott Laboratories differentiates via structural heart and vascular device synergies that bundle protection systems into procedure kits. Medtronic Plc anchors market presence through its global endovascular platform and clinician training infrastructure.
Embolic protection systems are intravascular devices—typically filter-based or balloon-occlusion mechanisms—that capture embolic debris released during stenting, atherectomy, or transcatheter valve procedures, with pore sizes generally ranging from 80 to 150 microns to intercept clinically relevant particulate while preserving antegrade flow. Their primary purpose is reducing periprocedural stroke and myocardial infarction risk during endovascular interventions. Filter devices occupy the largest installed base due to established clinical familiarity and broad compatibility with guide catheter platforms. Distal protection devices command premium positioning in carotid and saphenous vein graft interventions where embolic load is highest. Bioabsorbable solutions within the technology dimension represent an emerging development vector focused on eliminating retrieval steps and reducing vessel trauma.
FDA 510(k) clearance requirements and EU MDR conformity assessments impose substantial clinical evidence and quality system burdens on device manufacturers seeking market access. The EPA and ISO 10993 biocompatibility frameworks additionally govern material selection and sterilization validation for polymeric filter components. Stakeholders must monitor evolving reimbursement determinations from CMS and parallel national health technology assessment bodies that increasingly tie coverage to randomized stroke-reduction outcomes rather than device-centric endpoints.
Market Dynamics
Integrated health system procurement consolidation is compressing pricing power for device manufacturers while simultaneously elevating clinical evidence requirements for contract eligibility.
Growth Catalysts
- EU MDR conformity pathways:Stricter clinical evidence mandates for Class II cardiovascular devices are filtering out marginal competitors and concentrating volume among established manufacturers with robust quality systems.
- Distal filter technology:Carotid stenting protocols at tertiary hospitals are embedding embolic protection as standard-of-care, expanding procedural volumes beyond historical elective case mixes.
- Japan's aging surgical population:PMDA reimbursement determinations now explicitly cover neuroprotection devices for high-risk endovascular interventions, accelerating hospital capital allocation.
Market Restraints
- Nitinol price volatility:Superelastic alloy supply concentration in Chinese smelting operations creates input cost unpredictability for filter frame manufacturing.
- FDA 510(k) evidentiary burden:Predicate device comparisons now require larger safety datasets, extending clearance timelines and freezing smaller competitors in regulatory backlog.
- Balloon-occlusion substitution:Proximal protection systems from competing vascular platforms capture price-sensitive saphenous vein graft cases where filter retrieval complexity deters adoption.
Strategic Opportunities
- German outpatient clinic expansion:Ambulatory surgical center licensing reforms enable same-day carotid stenting with protection devices, creating channel diversification beyond traditional hospital purchasing.
- Bioabsorbable polymer convergence:Elimination of retrieval catheter steps through resorbable filter membranes addresses vessel trauma concerns in tortuous anatomy cases.
- CMS bundled payment incentives:Stroke-reduction outcome metrics in cardiac procedure reimbursement are aligning hospital procurement toward protection systems with demonstrated neurological event reduction.
Industry Challenges
- Interventional neuroradiology fellowship scarcity:Specialized operator training programs are not scaling with procedural volume growth, constraining safe deployment of distal protection in community settings.
- ISO 10993 biocompatibility recertification:Updated cytotoxicity testing protocols for polymeric filter components are forcing material reformulations and sterilization validation repeats across existing product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embolic Protection Systems Market |
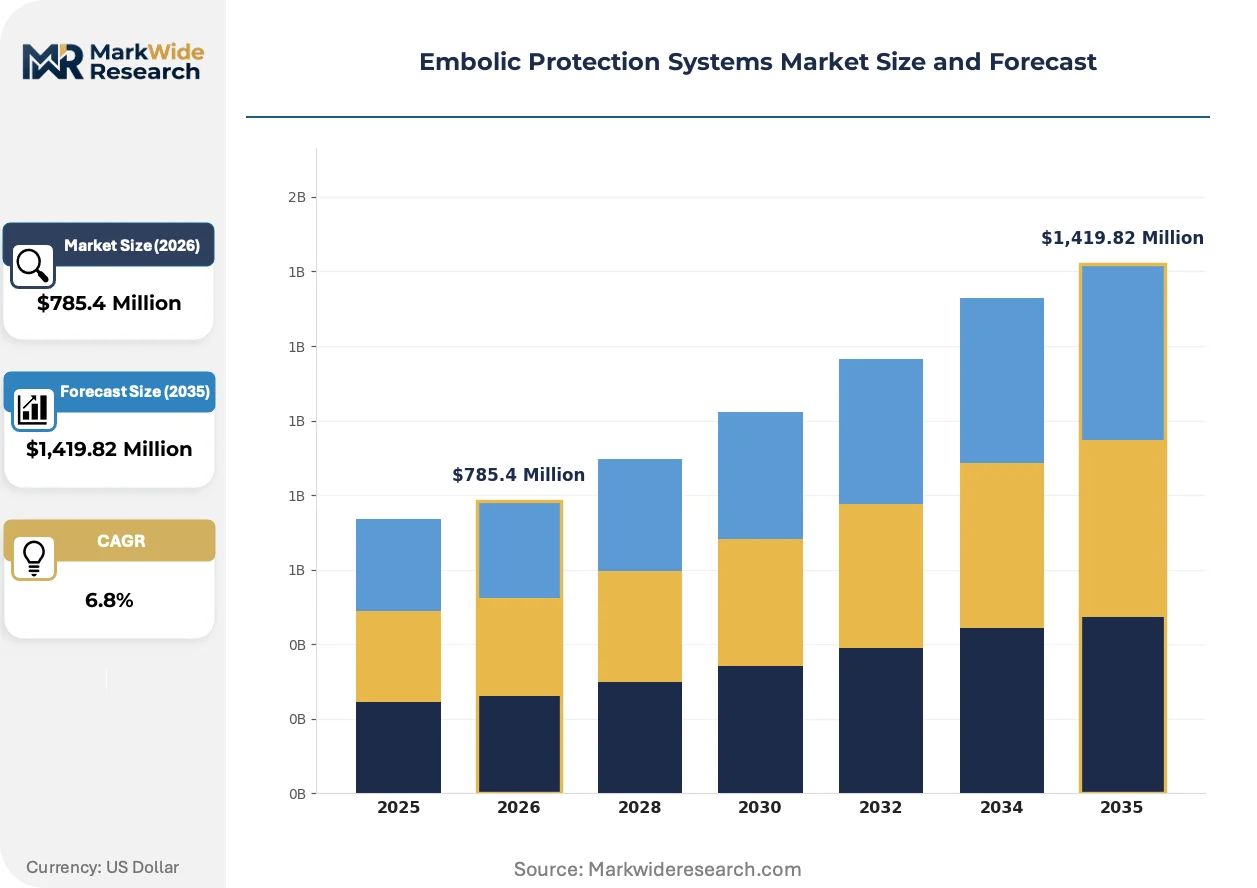
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,419.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filter Devices, Balloon Occlusion Devices, Distal Protection Devices, Proximal Protection Devices End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Cardiology Units Technology: Mechanical Filters, Umbrella Filters, Bypass Technologies, Bioabsorbable Solutions Application: Cerebral Embolism, Myocardial Infarction, Aortic Aneurysm, Peripheral Vascular Disease |
| Companies Covered | Boston Scientific Corporation, Medtronic Plc, Abbott Laboratories, Cardinal Health, Edwards Lifesciences Corporation, Hellman & Friedman LLC (Cordis), Silk Road Medical Inc, Contego Medical LLC, W.L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embolic Protection Systems Market Shifts & Advancements
Device architecture is pivoting toward retrieval-free deployment models while regulatory frameworks increasingly predicate market access on neurological outcome data rather than technical performance metrics alone.
Filter-based systems are integrating pore-size gradients that capture 80-150 micron embolic debris without occluding antegrade flow, a capability that interventional cardiologists at US teaching hospitals are adopting faster than community practitioners. This technical advance is compressing the competitive window for balloon-occlusion alternatives by eliminating the ischemia tolerance limitations that previously constrained case selection.
REACH material safety assessments and EU MDR clinical evaluation requirements are mandating extended follow-up data for implantable cardiovascular devices, forcing manufacturers to maintain post-market surveillance infrastructure that smaller competitors cannot sustain. German notified bodies are applying these standards most stringently, creating a regulatory bottleneck that delays CE marking for novel filter geometries.
Hospital value analysis committees are unbundling device procurement from procedure kit bundling, demanding line-item transparency that disrupts traditional portfolio-anchoring strategies. This behavioral shift is most pronounced in United States integrated delivery networks, where supply chain directors now negotiate protection devices separately from guide catheter and stent purchases, compressing vendor margin structures.
Embolic Protection Systems Market Segmentation
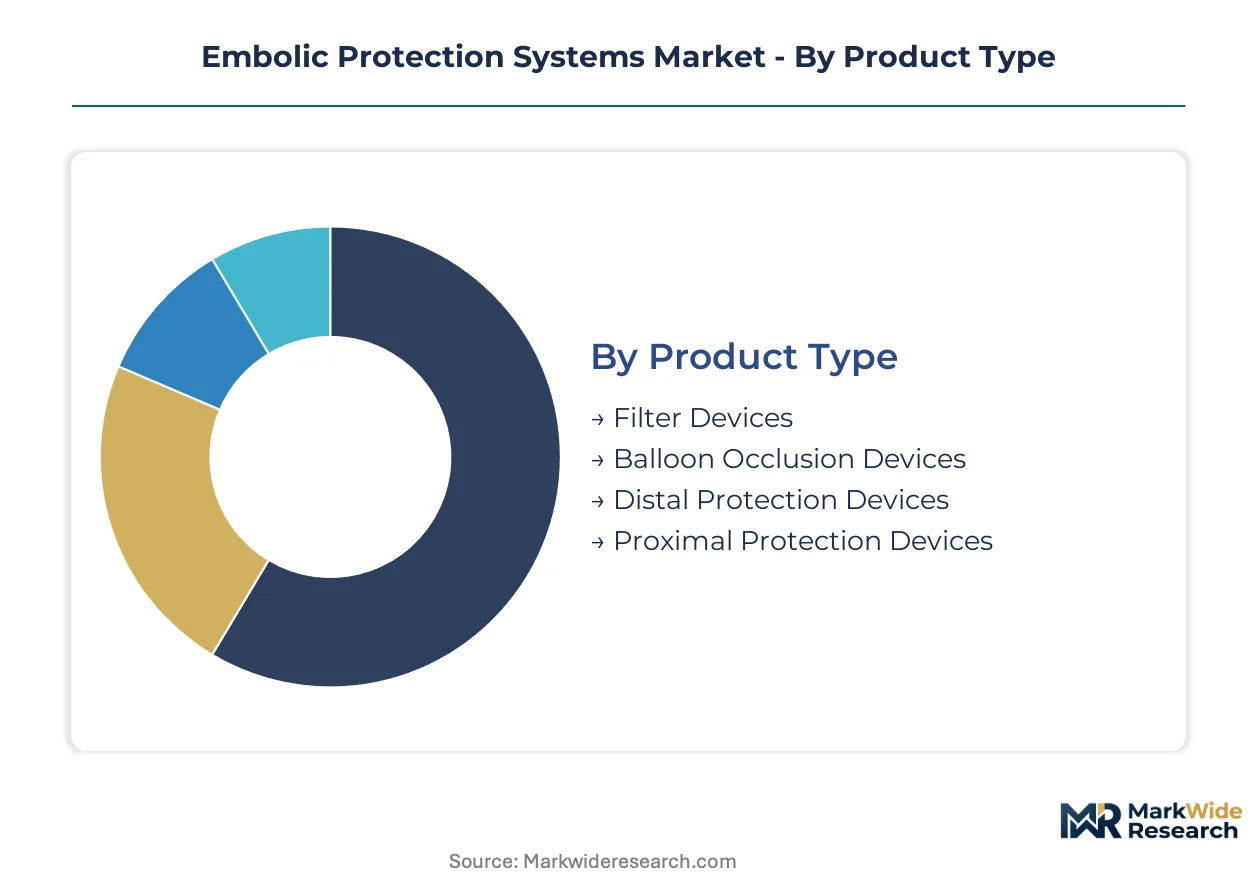
Segmentation in embolic protection systems reveals how regulatory pathways, procedural settings, and material technologies partition commercial opportunity. Manufacturers must align product development with specific certification requirements and end-user workflows rather than pursuing undifferentiated market entry.
Product Type:
FDA 510(k) clearance dominates filter-based platforms, while balloon occlusion systems face additional hemodynamic safety studies under Class II cardiovascular device pathways. EU MDR conformity assessments impose stricter clinical evidence burdens on novel geometries than predicate-based submissions.
- Filter Devices:Polymeric mesh membranes with pore sizes of 80-150 microns capture embolic debris while maintaining antegrade flow. Demand concentrates in United States tertiary hospitals where carotid stenting protocols mandate distal protection as standard-of-care.
- Balloon Occlusion Devices:Inflatable distal balloons halt blood flow during debris capture, requiring careful ischemia tolerance management. German outpatient clinics are expanding adoption for same-day saphenous vein graft procedures under recent ambulatory licensing reforms.
- Distal Protection Devices:Positioned beyond the lesion site to intercept downstream embolization during stent deployment.
- Proximal Protection Devices:Balloon-based flow reversal systems that protect without crossing the lesion, appealing to tortuous anatomy cases.
Filter Devices sits at the top of the volume ranking, with Bioabsorbable Solutions climbing the fastest.
End User:
Procurement authority varies sharply across settings, with integrated health systems extracting line-item transparency while ambulatory centers prioritize bundled procedure economics. Capital allocation cycles differ: hospitals refresh protection device inventories through centralized supply chain committees, whereas specialty clinics respond directly to operator preference.
- Hospitals:Interventional cardiology and neuroradiology departments at tertiary centers drive procedural volume. United States integrated delivery networks are unbundling device procurement from stent and catheter kit purchases, compressing vendor margins.
- Ambulatory Surgical Centers:Same-day discharge protocols demand simplified retrieval mechanisms and reduced staff training requirements. German regulatory reforms enabling outpatient carotid stenting are accelerating capital allocation to these channels.
- Specialty Clinics:Focused vascular intervention facilities with concentrated operator expertise and rapid case turnover.
- Cardiology Units:Hospital-based departments with embedded catheterization labs and established protection device protocols.
Hospitals command the dominant revenue share, though Ambulatory Surgical Centers are expanding most quickly.
Technology:
Material selection determines regulatory classification and sterilization validation requirements. ISO 10993 biocompatibility frameworks govern polymeric components, while metallic frame structures face additional fatigue testing under cardiovascular device standards.
- Mechanical Filters:Nitinol frame structures with laser-cut struts provide superelastic deployment and retrieval. Chinese smelting concentration for nitinol feedstock creates input cost volatility that manufacturers must hedge through long-term supply agreements.
- Umbrella Filters:Conical membrane geometries optimized for vessel wall apposition without flow obstruction. Japanese PMDA reimbursement determinations explicitly cover neuroprotection devices, accelerating hospital adoption of these platforms.
- Bypass Technologies:Flow diversion systems that shunt blood past the intervention site during debris release.
- Bioabsorbable Solutions:Resorbable polymer membranes eliminate retrieval catheter steps and reduce vessel trauma. REACH material safety assessments and extended EU MDR follow-up requirements are forcing manufacturers to maintain post-market surveillance infrastructure that smaller competitors cannot sustain.
Mechanical Filters retains the largest installed base, with Bioabsorbable Solutions gaining share fastest.
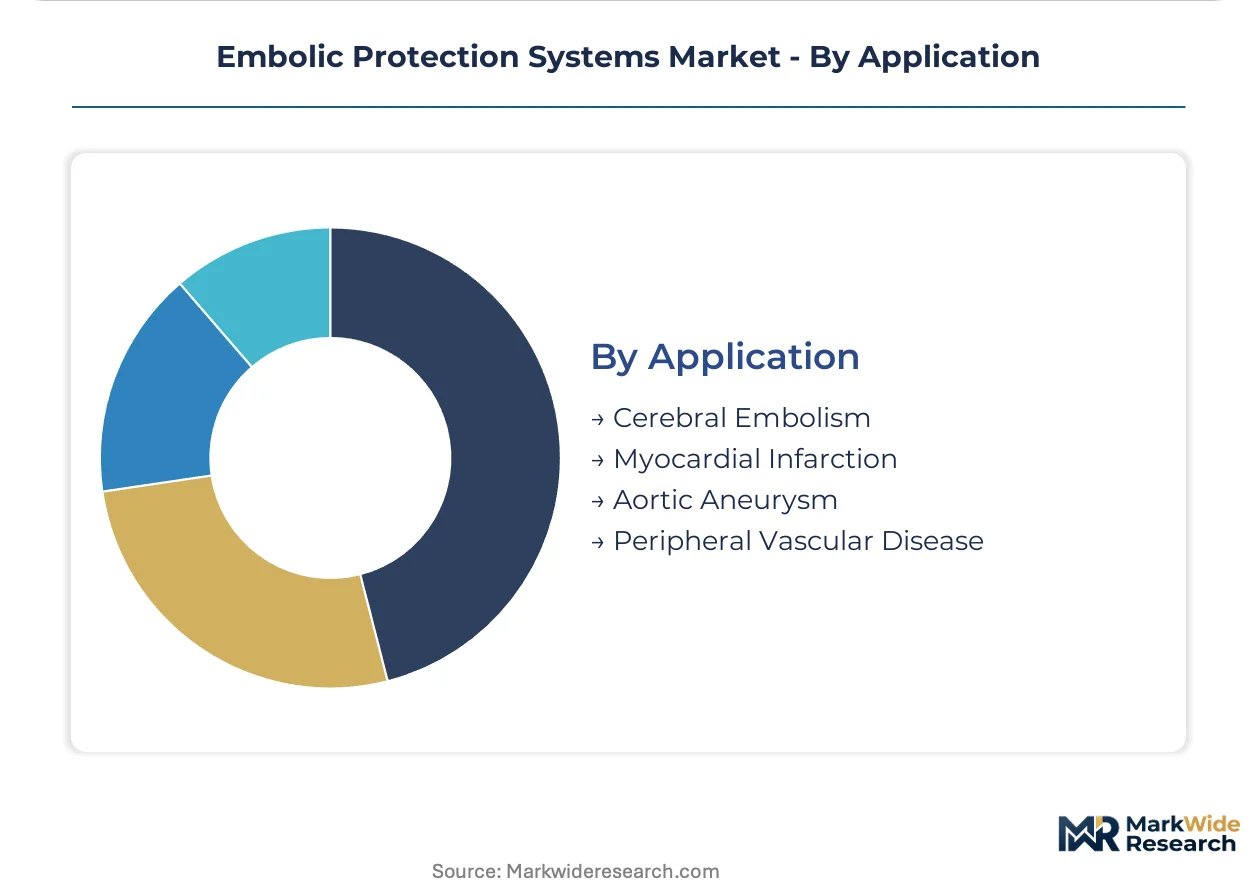
Application:
Clinical indication shapes device specification requirements, with cerebral protection demanding smaller delivery profiles and myocardial applications prioritizing large-bore compatibility. Reimbursement coding varies by indication, influencing hospital procurement prioritization.
- Cerebral Embolism:Carotid and intracranial interventions require filter pore sizes calibrated to capture 80-150 micron particles associated with stroke risk. United States CMS bundled payment incentives now tie cardiac procedure reimbursement to stroke-reduction outcomes, aligning procurement toward protection systems with demonstrated neurological event reduction.
- Myocardial Infarction:Saphenous vein graft and native coronary interventions generate substantial embolic load during stent deployment. Proximal protection systems from competing vascular platforms capture price-sensitive cases where filter retrieval complexity deters adoption.
- Aortic Aneurysm:Thoracic endovascular repair procedures with embolic risk during graft deployment.
- Peripheral Vascular Disease:Lower extremity interventions where distal protection adoption remains below cardiac and cerebral applications.
Cerebral Embolism leads procedural volume, with Myocardial Infarction applications showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional neuroradiology fellowship programs concentrate in tertiary medical centers across the United States, Germany, and Japan, anchoring procedural expertise for embolic protection deployment. These talent clusters determine regional adoption velocity and shape manufacturer training investments.
United States
Integrated delivery networks in Texas and the Northeast Corridor drive procurement consolidation for filter-based platforms. FDA 510(k) clearance pathways impose larger safety datasets on predicate comparisons, extending timelines for novel geometries. Boston and Cleveland clinic clusters embed distal protection as standard-of-care in carotid stenting protocols.
Germany
Ambulatory surgical center licensing reforms enable same-day carotid procedures with protection devices in Bavaria and North Rhine-Westphalia. EU MDR conformity assessments from German notified bodies apply REACH material safety standards most stringently, creating regulatory bottlenecks for CE marking. Munich and Hamburg hospital systems unbundle device procurement from stent kit purchases.
Japan
PMDA reimbursement determinations now explicitly cover neuroprotection devices for high-risk endovascular interventions, accelerating capital allocation in Tokyo and Osaka. METI industrial policy supports domestic manufacturing of nitinol frame components. Kanto region teaching hospitals pioneer filter deployment in tortuous anatomy cases.
China
NMPA regulatory harmonization with ISO 10993 biocompatibility frameworks governs polymeric filter sterilization validation. Nitinol smelting concentration in Chinese feedstock operations creates input cost volatility for global manufacturers. Shanghai and Beijing medical centers expand interventional cardiology departments with imported protection platforms.
United Kingdom
NICE technology appraisals tie NHS coverage to randomized stroke-reduction outcomes rather than device-centric endpoints. London and Manchester health systems prioritize protection systems with demonstrated neurological event reduction. MHRA post-market surveillance requirements align with EU MDR extended follow-up mandates for implantable cardiovascular devices.
Embolic Protection Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the embolic protection systems market. The vendor base stratifies into three tiers: integrated cardiovascular device portfolios with catheterization lab anchoring, vascular-focused mid-cap specialists with regional training infrastructure, and emerging technology developers pursuing bioabsorbable differentiation. Consolidation among health systems elevates procurement scale requirements, filtering marginal competitors from contract eligibility. Dominant competitive moves include portfolio bundling into procedure kits and backward integration into nitinol frame manufacturing to hedge supply concentration.
Among diversified cardiovascular device manufacturers, Boston Scientific Corporation and Abbott Laboratories exemplify portfolio-anchoring strategies that embed protection systems within broader interventional offerings. Medtronic Plc occupies a position representing global endovascular platform scale with clinician training infrastructure. These three entities anchor the premium tier where health system procurement consolidation concentrates volume.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic Plc |
| Abbott Laboratories |
| Cardinal Health |
| Edwards Lifesciences Corporation |
| Hellman & Friedman LLC (Cordis) |
| Silk Road Medical Inc |
| Contego Medical LLC |
| W.L. Gore & Associates |
| Others |
Supply & Pricing Matrix
Filter-to-balloon tier divergence separates premium distal protection from economy proximal alternatives, with FDA 510(k) predicate pathways and nitinol frame costs driving divergent margin structures across procurement channels. This bifurcation manifests in hospital contract negotiations where integrated delivery networks extract line-item transparency from filter manufacturers while ambulatory surgical centers accept bundled pricing for simplified balloon systems.
Pricing Analysis
Capacity additions in Chinese nitinol smelting operations are reshaping price floors for mechanical filter frames while German notified body bottlenecks sustain premium positioning for CE-marked devices. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from procurement unbundling in United States integrated delivery networks. Ambulatory surgical centers exhibit highest price sensitivity; tertiary hospital catheterization labs demonstrate lowest sensitivity due to outcome-based contract structures.
Supply Chain Analysis
Regional distribution centers in Minnesota, Bavaria, and Osaka coordinate hub-and-spoke patterns for sterile device deployment. Manufacturing concentrates in China, Ireland, and Costa Rica for nitinol frame production and final assembly. Raw material dependencies include superelastic nickel-titanium alloys, laser-cut polymeric meshes, and sterilization-grade packaging. Single-source vulnerability in Chinese nitinol feedstock creates exposure to export restriction scenarios. Distribution runs through GPO-managed hospital supply chains and direct-to-ASC specialty distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge between German outpatient licensing reforms and United States bundled payment constraints, with regulatory cost differentials favoring same-day procedure platforms in Bavaria and North Rhine-Westphalia over inpatient-dependent United States channels.
For Market Incumbents: Hedge against balloon-occlusion substitution by securing long-term nitinol supply agreements with Chinese smelters and accelerating bioabsorbable polymer R&D to eliminate retrieval complexity. Channel control through clinician training infrastructure defends position against mid-cap specialists. CE marking investment in German notified bodies maintains premium tier access. For New Entrants and Emerging Players: The premium-to-economy price-point gap in saphenous vein graft protection creates entry space for simplified proximal balloon systems. Target German ambulatory surgical centers as the most penetrable channel under recent licensing reforms. Reimbursement strategy alignment with PMDA neuroprotection coverage in Japan offers secondary geographic expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR conformity assessments filter marginal competitors from contract eligibility. Long-term viability favors manufacturers with captive nitinol supply and post-market surveillance infrastructure. Acquisition target archetype: mid-cap vascular specialists with German regulatory clearance and Japanese distribution. Signal to watch: CMS stroke-reduction outcome metrics shifting hospital procurement toward demonstrated neurological event reduction.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | German notified body engagement accelerates EU MDR access for novel filter geometries. |
| Backward Integration into Nitinol | Captive superelastic alloy supply hedges Chinese smelting concentration risks. |
| Hospital System Partnership | United States integrated delivery network contracts anchor catheterization lab placement. |
| Reimbursement Strategy | PMDA neuroprotection coverage alignment unlocks Japanese capital allocation cycles. |
| Software Companion Development | Deployment guidance algorithms address interventional neuroradiology fellowship scarcity. |
Research Methodology
Multiple input streams — primary interviews with interventional cardiologists and neuroradiologists, hospital procurement database analysis, and regulatory filing review — were reconciled to construct market estimates. Conversations with GPO contracts managers, biomedical engineers, and catheterization lab directors informed procedural volume assumptions. Secondary validation drew from FDA 510(k) databases, EU MDR notified body registers, PMDA reimbursement determinations, and CMS Medicare claims data. Bottom-up device shipment analysis and top-down healthcare expenditure triangulation cross-checked value estimates.
Data-stream reconciliation anchored volume projections across the analysis window through procedure-based modeling and installed-base replacement cycles. Segmentation dimensions included product type, end-user setting, material technology, and clinical application. CAGRs derived from trend extrapolation of procedural adoption curves and reimbursement policy trajectories. Forecast inputs incorporated nitinol price volatility indices and interventional fellowship program expansion rates.
The model assumes a particular technology adoption path; alternative pathways for bioabsorbable filter membranes would alter the outlook if resorption kinetics fail to match clinical expectations. Forecasts reflect predicate device clearance timelines and REACH material safety assessment evolution as binding constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Insulin Storage Devices Market
Medical Devices
Uterine Fibroid Treatment Device Market
Medical Devices
Assisted Walking Devices Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Wearable ECG Sensor Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Inversion Table Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
Prescription Lens Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
Cerebral Thrombectomy Devices Market
Medical Devices
Breathing Circuits Market
Medical Devices
Digital Migraine Treatment Device Market