
 Global Stent Graft Balloon Catheter Market | 2026-2036
Global Stent Graft Balloon Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stent Graft Balloon Catheter Market Foresight
Multi-source procurement of balloon catheter components is broadening as original equipment manufacturers diversify polymer and nitinol suppliers. Medtronic leverages captive manufacturing networks to sustain margin control across its endovascular portfolio. Boston Scientific anchors North American distribution through direct hospital contracting. Cook Medical specializes in custom fenestrated graft configurations for complex aortic anatomy.
A stent graft balloon catheter combines an inflatable balloon mechanism with a fabric-covered metallic scaffold for endovascular deployment, typically constructed from ePTFE or polyester graft material mounted on nitinol or stainless-steel frameworks and delivered through 12-24 French sheaths. Its primary purpose is to expand and seat stent grafts within diseased vasculature while maintaining positional accuracy during endovascular aneurysm repair. Peripheral stent grafts occupy mature volume positions in limb salvage procedures, while fenestrated stent grafts command premium positioning due to customization requirements for juxtarenal aneurysms. Drug-eluting technology extends into peripheral applications as paclitaxel coating protocols face renewed clinical scrutiny.
FDA premarket notification and EU MDR conformity assessment impose divergent evidence requirements on balloon catheter manufacturers seeking dual-market access. Japan's PMDA maintains distinct clinical trial expectations for stent graft approval that filter market entrants by development capacity. Stakeholders must monitor evolving reimbursement thresholds for endovascular versus open surgical repair across national health technology assessment frameworks.
Market Dynamics
EU MDR conformity assessment timelines are compressing product launch windows for balloon catheter manufacturers, forcing simultaneous FDA-PMDA dossier preparation and straining regulatory affairs capacity across the endovascular sector.
Growth Catalysts
- Endovascular aneurysm repair volume expansion:Vascular surgery centers in the United States, Germany, and Japan are scaling EVOR procedure throughput as patient eligibility criteria broaden.
- Fenestrated graft customization protocols:Juxtarenal aneurysm repair complexity is driving demand for patient-specific stent graft configurations with integrated balloon catheter delivery systems.
- Japan PMDA accelerated review pathways:Priority review designations for breakthrough devices are shortening time-to-market for novel catheter technologies.
Market Restraints
- Nitinol supply concentration:Shape-memory alloy sourcing remains dependent on limited superelastic wire producers, creating input cost volatility for catheter frame construction.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations and notified body capacity constraints are extending certification timelines.
- Open surgical repair substitution:Younger patient cohorts with favorable anatomy remain candidates for conventional aortic reconstruction, capping endovascular penetration.
Strategic Opportunities
- India CDSCO regulatory harmonization:Alignment with IMDRF standards is streamlining import licensing for established manufacturers.
- Drug-eluting balloon convergence:Paclitaxel coating integration with stent graft deployment systems addresses restenosis in peripheral applications.
- Direct hospital procurement platforms:Digital tendering systems are disintermediating traditional distributor networks in European markets.
Industry Challenges
- Polymer extrusion technician scarcity:Specialized ePTFE processing expertise is concentrated among veteran operators, constraining manufacturing scale-up.
- Dual FDA-PMDA clinical trial design:Divergent primary endpoint expectations between regulators complicate unified study protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stent Graft Balloon Catheter Market |
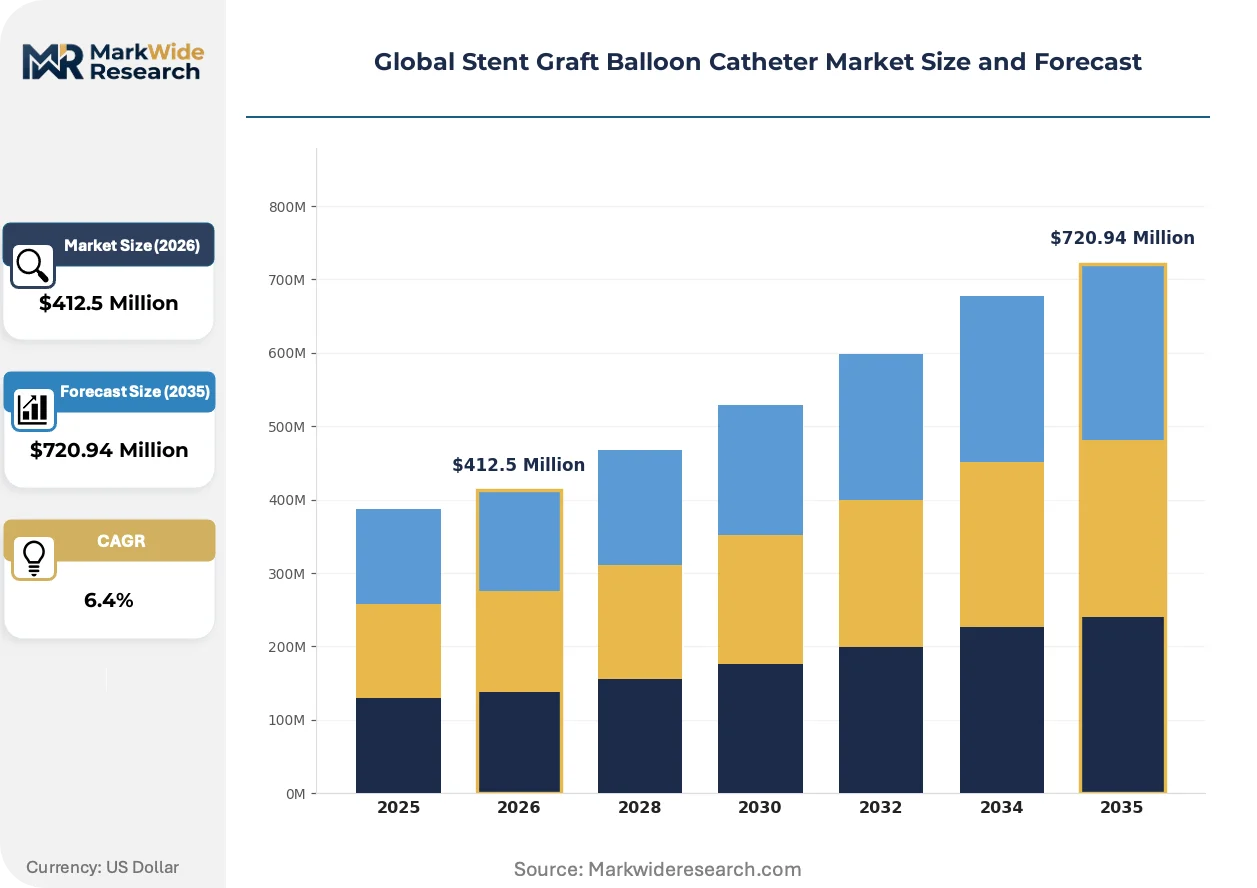
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peripheral Stent Grafts, Aortic Stent Grafts, Iliac Stent Grafts, Fenestrated Stent Grafts, Covered Balloon Catheters Technology: Balloon-Expandable, Self-Expanding, Drug-Eluting, Bioabsorbable, Coated Stent Technology Application: Endovascular Aneurysm Repair, Peripheral Artery Disease Treatment, Coronary Artery Reconstruction, Urological Interventions End User: Vascular Surgery Centers, Cardiology Clinics, Radiology Departments, Specialty Hospitals, Outpatient Surgical Facilities |
| Companies Covered | Medtronic, Boston Scientific, Abbott Laboratories, Cook Medical, Terumo Corporation, W. L. Gore & Associates, B. Braun Melsungen, MicroPort Scientific, JOTEC GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stent Graft Balloon Catheter Market Shifts & Advancements
Balloon catheter engineering is converging with advanced materials science and digital manufacturing, compressing development cycles while elevating precision requirements for complex aortic anatomies.
Electrospun nanofiber graft materials are electrifying stent graft sealing performance. Vascular surgery centers in Germany are adopting these constructs for challenging neck anatomies. The technology is electrifying competitive positioning among manufacturers with captive polymer processing capabilities.
EU MDR Article 117 requirements for drug-device combination products are elevating notified body scrutiny of paclitaxel coating protocols. Manufacturers must now submit standalone pharmaceutical quality documentation alongside technical files. Fenestrated stent graft programs face the steepest compliance burden due to custom device variability.
Consolidated procurement consortia in the United Kingdom are compressing vendor panels for endovascular devices. NHS Supply Chain frameworks now mandate outcome reporting clauses that tie reimbursement to procedure success metrics. Academic medical centers are responding by internalizing value analysis functions previously outsourced to group purchasing organizations.
Global Stent Graft Balloon Catheter Market Segmentation
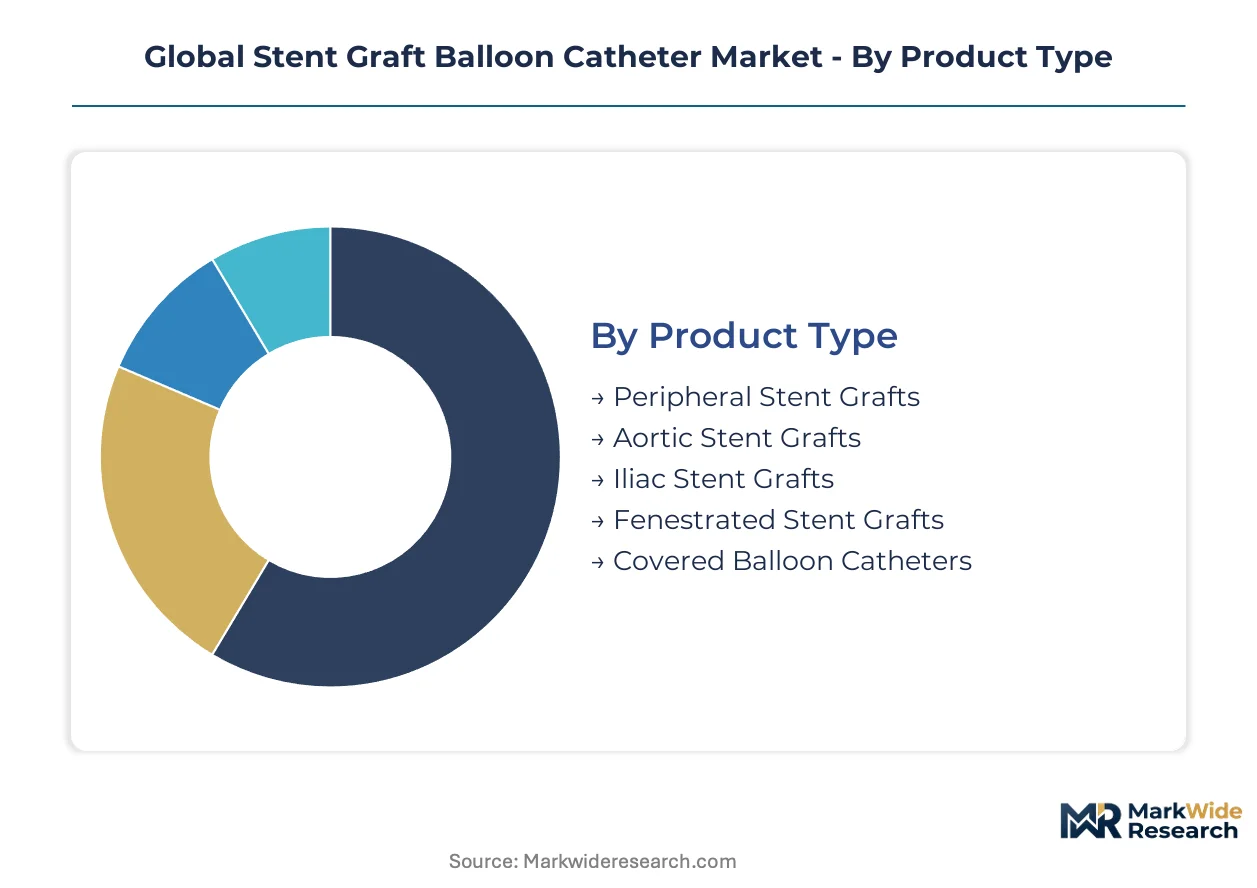
Stent graft balloon catheter purchasing decisions diverge sharply between integrated delivery networks and standalone facilities, with procurement sophistication dictating technology access. Segmentation reveals how product complexity, reimbursement pathways, and procedural volume interact to shape vendor selection criteria across care settings.
Product Type:
Integration depth varies substantially across graft configurations, with some serving as standalone implantable devices while others function as embedded components within comprehensive delivery systems.
- Aortic Stent Grafts:These infrarenal and thoracic configurations incorporate polyester or ePTFE fabric bonded to nitinol exoskeletons, delivered through 18-24 French sheaths. Demand clusters in United States academic medical centers performing high-volume EVAR procedures, driven by expanded Medicare coverage for complex anatomies. Volume placements concentrate in Aortic Stent Grafts; the faster expansion belongs to Fenestrated Stent Grafts.
- Fenestrated Stent Grafts:Patient-specific designs with laser-cut scallops and fenestrations for renal and visceral vessel preservation require 6-12 week manufacturing cycles. Germany's vascular surgery centers lead adoption for juxtarenal aneurysm repair, constrained by EU MDR custom device documentation burdens.
- Peripheral Stent Grafts:Lower-profile constructs for femoropopliteal and subclavian applications deploy through 12-16 French systems. Japan's PMDA maintains distinct sizing validation requirements that filter market entrants.
- Iliac Stent Grafts:Modular bifurcation extensions with ipsilateral and contralateral limbs address common iliac aneurysm extension. United Kingdom NHS Supply Chain procurement frameworks favor standardized configurations over custom geometries.
- Covered Balloon Catheters:Standalone occlusion devices with expandable polytetrafluoroethylene membranes for trauma and rupture scenarios. Outpatient surgical facilities in the United States deploy these for temporary hemorrhage control.
Procurement volume clusters around standardized aortic platforms; customization capabilities command premium positioning in complex anatomy centers.
Technology:
Cost tier stratification separates commoditized mechanical platforms from premium biopharmaceutical-enhanced systems, with reimbursement differentials widening across technology categories.
- Self-Expanding:Nitinol superelastic frameworks deploy at body temperature without balloon assistance, reducing procedural steps. Germany's outpatient surgical facilities favor these for streamlined throughput, constrained by nitinol wire supply concentration among limited superelastic alloy producers. Standard mechanical platforms dominate volume; drug-enhanced systems capture margin expansion.
- Drug-Eluting:Paclitaxel coating protocols target neointimal hyperplasia in peripheral applications. United States vascular surgery centers face renewed clinical scrutiny following safety signal analyses, compressing utilization in femoropliteal segments.
- Balloon-Expandable:Stainless-steel or cobalt-chromium platforms require inflation for precise diameter achievement. Cardiology clinics in Japan deploy these for coronary and renal artery applications demanding exact sizing.
- Coated Stent Technology:Carbon-based or phosphorylcholine surface modifications reduce thrombogenicity. Radiology departments prioritize these for anticoagulation-intolerant patients.
- Bioabsorbable:Magnesium or polymer scaffolds designed for complete resorption remain investigational. Academic medical centers in the United States participate in controlled clinical trials under FDA investigational device exemption protocols.
Mechanical expansion systems sustain placement volume; pharmaceutical integration faces reimbursement headwinds in peripheral indications.
Application:
Procedure maturity curves separate established volume applications from emerging indications, with regulatory pathway complexity determining commercial access timelines.
- Endovascular Aneurysm Repair:Infrarenal and thoracic aortic aneurysm exclusion through transfemoral delivery constitutes the foundational indication. United States vascular surgery centers perform these in hybrid operating suites with 3D fusion imaging, driven by favorable risk-adjusted outcomes versus open repair. Established abdominal procedures anchor volume; thoracic extensions gain share fastest.
- Peripheral Artery Disease Treatment:Femoropopliteal and tibial revascularization addresses limb salvage in diabetic and atherosclerotic populations. Germany's specialty hospitals integrate these with wound care protocols for chronic limb-threatening ischemia.
- Coronary Artery Reconstruction:Saphenous vein graft and native vessel interventions utilize lower-profile delivery systems. Cardiology clinics in Japan maintain distinct PMDA approval pathways separate from peripheral vascular frameworks.
- Urological Interventions:Iliac artery protection during pelvic surgery and ureteral stenting applications represent niche utilization. Outpatient surgical facilities deploy covered balloons for iatrogenic injury management.
Aortic aneurysm exclusion sustains procedural volume; peripheral limb salvage applications expand most quickly amid diabetes prevalence.
End User:
Customer type segmentation reveals divergent purchasing authority, with integrated delivery networks exercising consolidated procurement leverage unavailable to independent facilities.
- Vascular Surgery Centers:Dedicated endovascular suites with hybrid imaging capabilities perform complex fenestrated and branched procedures. United States centers of excellence negotiate direct manufacturer contracts, bypassing distributor markups. High-complexity centers dominate technology adoption; community hospitals expand access most rapidly.
- Cardiology Clinics:Coronary and peripheral diagnostic facilities with catheterization laboratory infrastructure. Japan's clinic-based specialists operate under distinct PMDA facility accreditation requirements.
- Radiology Departments:Interventional radiologists perform image-guided vascular access and embolization procedures. Germany's hospital-based radiology units integrate with vascular surgery for combined case management.
- Specialty Hospitals:Cardiovascular-focused institutions with concentrated procedural volume. United Kingdom independent sector treatment centers compete for NHS elective procedure contracts.
- Outpatient Surgical Facilities:Ambulatory surgery centers performing uncomplicated EVAR and peripheral interventions. United States Medicare site-of-service differentials drive case migration from inpatient settings.
Academic medical centers anchor technology diffusion; ambulatory settings capture case volume migration under payment reform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for stent graft balloon catheters concentrates in established interventional vascular centers with mature reimbursement frameworks and high procedural throughput. Centers of excellence in the United States, Germany, and Japan anchor volume placement, while emerging markets in India and Brazil expand access through regulatory harmonization and infrastructure investment.
United States
Vascular surgery centers in academic medical hubs perform complex fenestrated and branched endovascular repairs with hybrid imaging capabilities. FDA premarket approval pathways for breakthrough devices accelerate commercialization timelines for novel catheter technologies. Cleveland Clinic and Mayo Clinic anchor adoption of patient-specific graft configurations, driving demand for integrated balloon delivery systems.
Germany
Specialty hospitals in Bavaria and Baden-Württemberg lead European volume for juxtarenal aneurysm repair with custom fenestrated graft protocols. EU MDR conformity assessment requirements strain notified body capacity, compressing product launch windows for manufacturers seeking CE marking. Heidelberg and Munich vascular surgery clusters adopt electrospun nanofiber graft materials for challenging neck anatomies.
Japan
PMDA maintains distinct clinical trial expectations for stent graft approval that filter market entrants by development capacity and domestic clinical infrastructure. Tokyo and Osaka metropolitan areas concentrate interventional cardiology and vascular surgery expertise in university-affiliated hospitals. Priority review designations for breakthrough devices shorten time-to-market for novel catheter technologies addressing unmet anatomical challenges.
India
CDSCO regulatory harmonization with IMDRF standards streamlines import licensing for established multinational manufacturers. Delhi-NCR and Mumbai medical centers expand endovascular aneurysm repair capabilities through public-private partnerships and international training collaborations. Domestic procurement platforms are disintermediating traditional distributor networks, compressing margins for imported devices.
Brazil
ANVISA regulatory pathways for class III medical devices create extended approval timelines that favor established players with dedicated local regulatory affairs capacity. São Paulo and Rio de Janeiro anchor interventional vascular procedure volume through concentrated private hospital infrastructure. Reimbursement differentials between public and private payment systems fragment market access across patient populations.
Global Stent Graft Balloon Catheter Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent manufacturers expand across graft configurations and delivery platforms. The vendor base concentrates among integrated endovascular specialists with captive polymer processing and nitinol frame manufacturing capabilities. Three archetypes define competitive positioning: diversified medical technology conglomerates with vascular divisions, pure-play endovascular specialists with custom fabrication expertise, and emerging Asian manufacturers scaling through cost-optimized production. M&A activity and strategic technology licensing represent the dominant competitive moves, with players acquiring fenestrated graft design capabilities and balloon catheter engineering talent.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific exemplify integrated endovascular portfolio strategies, while Cook Medical occupies a specialist position in custom fenestrated configurations. These three anchors represent distinct archetypes: captive manufacturing networks sustaining margin control, direct hospital contracting bypassing distributor markups, and patient-specific design protocols for complex anatomies. Their collective positioning illustrates how regulatory affairs capacity, polymer processing expertise, and clinical training infrastructure constitute durable competitive moats in this market.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Abbott Laboratories |
| Cook Medical |
| Terumo Corporation |
| W. L. Gore & Associates |
| B. Braun Melsungen |
| MicroPort Scientific |
| JOTEC GmbH |
| Others |
Supply & Pricing Matrix
Nitinol wire price volatility cascades through stent graft balloon catheter manufacturing, compressing margins at the component tier while amplifying pricing power for captive producers with in-house superelastic alloy processing. EU MDR compliance costs and FDA premarket approval pathways stratify final device pricing across premium custom-fenestrated, standard aortic, and economy peripheral configurations.
Pricing Analysis
Volume concentrates in standardized aortic platforms while margins accrue to patient-specific fenestrated systems requiring 6-12 week manufacturing cycles. Price differentiation hinges on EU MDR certification tier and customization depth, with Germany's vascular surgery centers paying substantial premiums for Heidelberg and Munich-sourced complex anatomy solutions. Cost compression in peripheral stent graft tiers intensifies as India's CDSCO-harmonized import licensing expands competitor supply. Community hospital systems exhibit acute price sensitivity; academic medical centers with direct manufacturer contracting demonstrate elasticity for breakthrough device premiums.
Supply Chain Analysis
ISO 13485 and FDA establishment registration gating constrains supplier qualification, filtering balloon catheter component vendors to a narrow tier of validated polymer extrusion and nitinol processing specialists. Manufacturing concentrates in the United States, Germany, and Japan, with ePTFE graft material and superelastic nitinol wire anchoring critical input dependencies. Single-source vulnerability pervades shape-memory alloy supply, with limited superelastic wire producers creating exposure to raw material price swings. Distribution runs through direct hospital contracting for high-volume centers and specialized cardiovascular distributors for mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment timelines and expanded post-market surveillance obligations are forcing consolidation among balloon catheter manufacturers lacking regulatory affairs scale, eliminating marginal players from dual-market access.
For Market Incumbents: Anticipate nitinol supply concentration risk by securing long-term superelastic alloy offtake agreements or acquiring captive wire-drawing capabilities. Deepen polymer processing expertise through targeted hiring of veteran ePTFE extrusion technicians, as this capability scarcity constrains manufacturing scale-up for fenestrated graft programs. FDA-PMDA simultaneous dossier preparation demands expanded regulatory infrastructure investment to defend positioning against emerging Asian manufacturers. For New Entrants and Emerging Players: Specialty hospital procurement platforms in the United Kingdom offer the most penetrable channel, as NHS Supply Chain framework mandates disintermediate traditional distributor networks and reward outcome-reporting capabilities. Target India's CDSCO-IMDRF harmonized pathway for streamlined import licensing, leveraging domestic procurement platform digitization to bypass legacy distributor markups. Position around drug-eluting balloon convergence for peripheral applications, addressing restenosis with paclitaxel coating protocols amid renewed clinical scrutiny. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier endovascular specialists with captive fenestrated graft design capabilities in Germany, as EU MDR custom device documentation burdens strain notified body capacity and compress valuation multiples. Long-term viability across the analysis window rests on regulatory affairs scale and polymer processing depth rather than pure volume positioning. Monitor PMDA priority review designation frequency as the inflection signal for breakthrough device commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA-PMDA Simultaneous Submission | Accelerates time-to-market for novel catheter technologies addressing unmet anatomical challenges. |
| Captive Nitinol Wire Manufacturing | Insulates margin control from superelastic alloy supply concentration among limited producers. |
| Electrospun Nanofiber Graft Development | Differentiates sealing performance for challenging neck anatomies in German vascular centers. |
| Direct Hospital Contracting Expansion | Bypasses distributor markups in United States academic medical center procurement. |
| Drug-Eluting Coating Protocol Investment | Addresses restenosis in peripheral applications amid paclitaxel safety signal scrutiny. |
Research Methodology
Independent corroboration across vascular surgery center purchasing committees, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads underwrites the qualitative findings. Primary fieldwork with fenestrated graft program coordinators and nitinol wire procurement specialists combined with secondary validation from FDA 510(k) and PMA filings, EU MDR notified body documentation, PMDA approval summaries, and CMS Medicare reimbursement databases. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across the projection horizon isolates volume expansion from price-mix effects in infrarenal EVAR, thoracic extensions, and peripheral limb salvage applications. Segmentation dimensions encompass product configuration complexity, technology tier from mechanical to pharmaceutical-enhanced, procedural maturity curve positioning, and end-user purchasing authority concentration. CAGRs derive from logistic diffusion modeling of endovascular versus open surgical substitution elasticities, with Japan PMDA review pathway velocity and India CDSCO harmonization progress as industry-specific forecast inputs.
Caveats apply where EU MDR notified body capacity constraints, nitinol supply disruptions, or paclitaxel coating protocol regulatory reversals could materially shift the outlook. Forecasts reflect documented assumptions regarding procedure eligibility expansion and reimbursement parity maintenance. A model refresh is warranted upon material change in FDA breakthrough device designation velocity or Japan PMDA priority review pathway access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Knee Reconstruction Devices Market
Medical Devices
India Enteral Feeding Devices Market
Medical Devices
Medical Machine Battery Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Bone Power Tools Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Medical Device Outsourcing Market