
 Esophageal Stethoscopes Market | 2026-2036
Esophageal Stethoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Esophageal Stethoscopes Market Insights
Hospital procurement channels for esophageal stethoscopes is fragmenting as group purchasing organizations lose leverage to direct manufacturer contracts and specialty distributors. Medtronic leverages its cardiac care portfolio to anchor hospital system agreements across integrated delivery networks. Welch Allyn competes through its diagnostic device specialization, while Riester GmbH & Co. KG sustains European clinical relationships through precision German manufacturing standards.
An esophageal stethoscope is a flexible probe inserted into the esophagus to transmit heart and respiratory sounds to external auditory or electronic processing equipment, typically featuring temperature sensors and constructed from medical-grade silicone or PVC with integrated thermistor elements for simultaneous core body temperature monitoring during surgery. Single-use stethoscopes command the largest revenue pool as infection control protocols harden, while digital stethoscopes with wireless connectivity represent the fastest-expanding technology segment where Bluetooth-enabled auscultation is displacing analog headsets in modern operating theaters. Analog stethoscopes retain share in cost-sensitive surgical centers, though margin compression limits supplier interest in this tier.
The FDA regulates esophageal stethoscopes as Class II medical devices under 510(k) premarket notification requirements, while the EU MDR imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. ISO 13485 quality management certification shapes supplier qualification for hospital tenders, and Japan's PMDA maintains distinct technical standards that delay market entry for non-domestic manufacturers. Stakeholders must monitor how evolving digital health regulations in major markets will classify wireless-enabled esophageal stethoscopes and whether software validation requirements will reshape competitive barriers.
Market Dynamics
Hospital infection control protocols are hardening procurement standards for esophageal stethoscopes, with single-use designs displacing reusable alternatives as the default specification in surgical suites across major medical device markets.
Growth Catalysts
- FDA Reprocessing Guidance:Updated premarket notification requirements for reusable medical devices are accelerating hospital transitions to disposable esophageal stethoscope inventories.
- Bluetooth-Enabled Auscultation:Wireless digital stethoscopes with integrated temperature monitoring are capturing preference in modern operating theaters seeking real-time data integration.
- German Infection Control Mandates:Krankenhaus-Infektions-Schutz-Gesetz provisions are compelling surgical centers to eliminate cross-contamination vectors from reusable diagnostic equipment.
Market Restraints
- Medical-Grade Silicone Volatility:Specialized polymer feedstock costs fluctuate with petrochemical markets, compressing margins for single-use manufacturers.
- Japanese Technical Standards:PMDA certification timelines extend 18-24 months for non-domestic manufacturers, delaying market access.
- Capnography Substitution:End-tidal carbon dioxide monitors provide overlapping respiratory monitoring functions, limiting esophageal stethoscope expansion in anesthesia workflows.
Strategic Opportunities
- Indian Surgical Volume Expansion:Government-funded health infrastructure under Ayushman Bharat is creating first-time demand for disposable diagnostic accessories in tier-2 and tier-3 cities.
- EU MDR Digital Health Pathway:Wireless-enabled devices with software components may qualify for streamlined conformity assessment, reducing time-to-market for connected stethoscope platforms.
- Integrated Delivery Network Direct Contracting:Bypassing group purchasing organizations allows manufacturers to capture full margin from hospital system procurement.
Industry Challenges
- ISO 13485 Talent Scarcity:Quality management system expertise specific to Class II medical devices commands premium compensation, constraining manufacturer scale-up.
- Legacy Analog Inventory Rationalization:Surgical centers with sunk costs in traditional headsets resist full fleet replacement despite digital upgrade pathways.
- 510(k) Software Validation:FDA documentation requirements for Bluetooth connectivity modules extend regulatory timelines beyond hardware-only submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esophageal Stethoscopes Market |
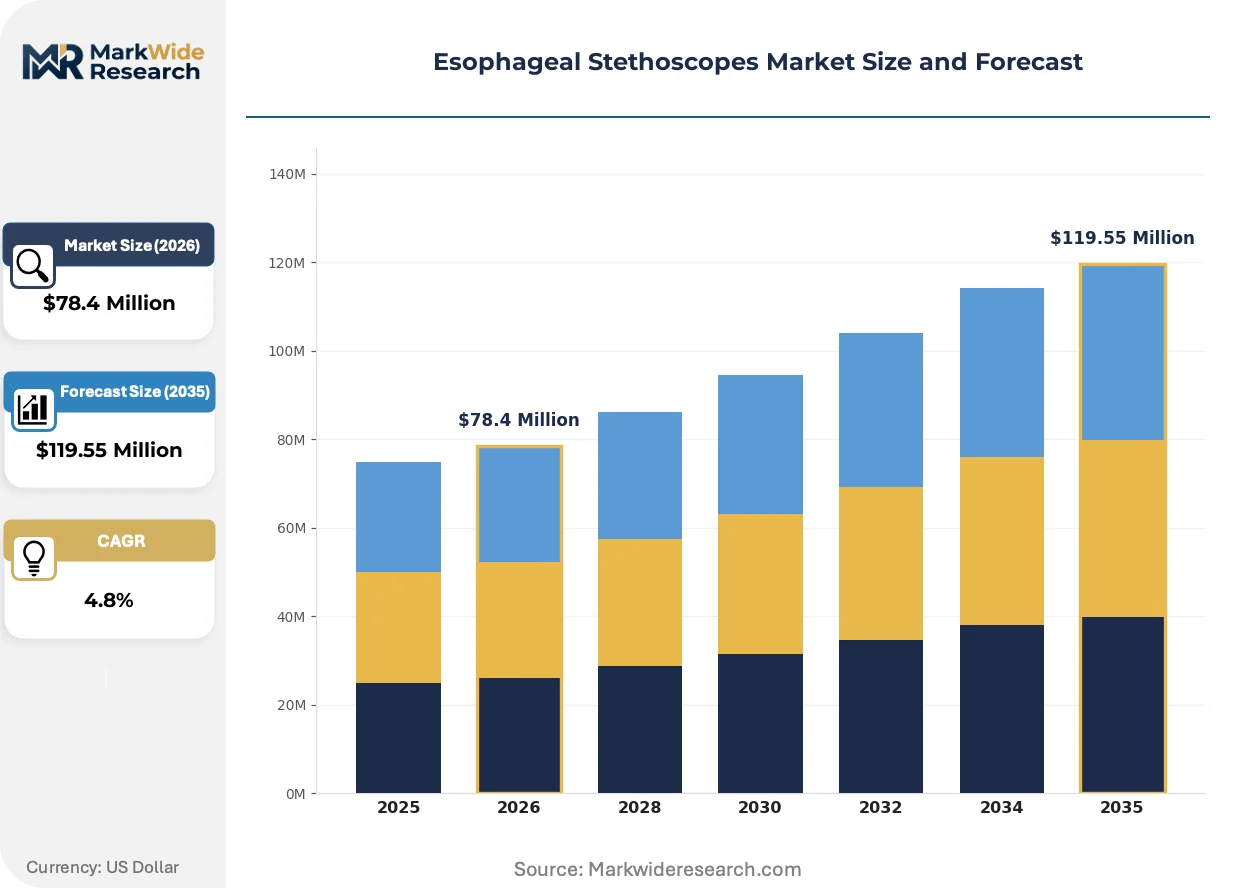
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $119.55 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Stethoscopes, Multi-Use Stethoscopes, Digital Stethoscopes, Analog Stethoscopes End User: Hospitals, Surgical Centers, Specialty Clinics, Home Healthcare Technology: Wireless Technology, Bluetooth Technology, Analog Technology, Digital Technology Application: Cardiovascular Monitoring, Pulmonary Monitoring, Anesthetic Monitoring, Gastrointestinal Assessment |
| Companies Covered | 3M, Medtronic, Welch Allyn, Medline Industries, American Diagnostic Corporation, GF Health Products, ICU Medical, Riester GmbH & Co. KG, DeRoyal Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esophageal Stethoscopes Market Trends and Innovations
Digital connectivity and disposable construction are converging to redefine esophageal stethoscope value propositions, with manufacturers racing to integrate wireless data transmission while eliminating reprocessing liability.
Wireless esophageal stethoscopes with embedded thermistors and Bluetooth Low Energy modules are rendering obsolete analog headsets tethered to standalone amplification units. Academic medical centers in the United States and university hospitals in Germany are piloting these platforms for integration with electronic anesthesia records. The shift compresses after-sales service revenue while opening subscription-based software maintenance streams.
EU MDR post-market surveillance obligations now require manufacturers to maintain clinical evidence portfolios for esophageal stethoscopes seeking CE marking renewal. This regulatory burden favors established suppliers with dedicated regulatory affairs functions. Smaller manufacturers are responding through notified body consolidation and shared post-market clinical follow-up studies.
Specialty distributors with dedicated anesthesia equipment expertise are displacing broad-line medical supply catalogs in esophageal stethoscope fulfillment. Anesthesiology group purchasing coalitions in the United States now negotiate directly with manufacturers for system-wide pricing. This channel compression concentrates volume with fewer intermediaries, rewarding distributors with clinical training capabilities and same-day logistics infrastructure.
Esophageal Stethoscopes Market Segmentation
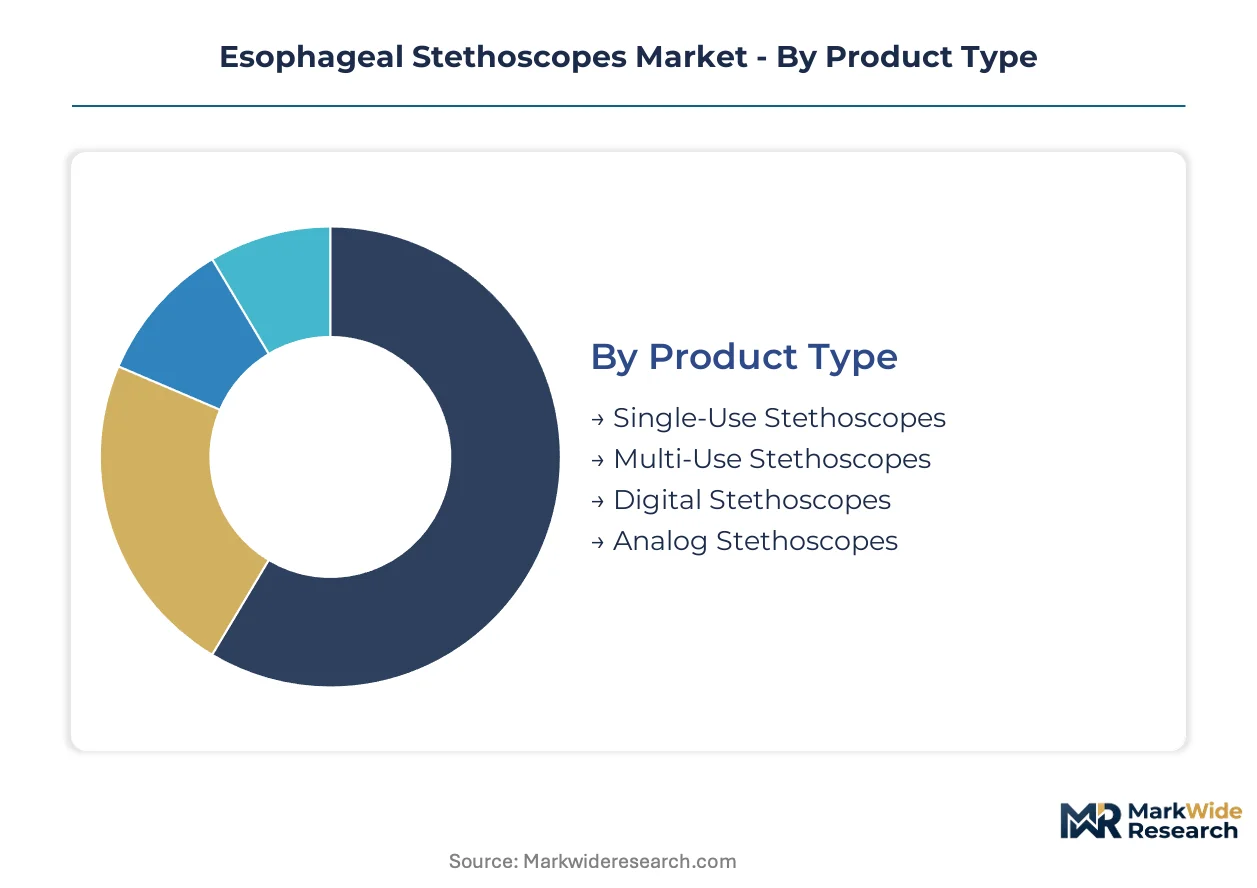
Esophageal stethoscope procurement varies sharply by clinical setting and infection control posture. Manufacturers must align product configurations with distinct regulatory, cost, and workflow requirements across these dimensions.
Product Type:
Mature disposable formats dominate procurement volumes while emerging digital platforms reshape premium tier competition.
- Single-Use Stethoscopes:Medical-grade silicone or PVC construction with integrated thermistors eliminates reprocessing liability. United States hospital systems specify these as default under FDA reprocessing guidance updates.
- Digital Stethoscopes:Wireless-enabled auscultation with Bluetooth Low Energy modules transmits real-time cardiac and respiratory data to electronic anesthesia records. German university hospitals pilot these for operating theater integration.
- Multi-Use Stethoscopes:Reusable designs face procurement erosion as infection control protocols harden across Western Europe.
- Analog Stethoscopes:Cost-sensitive surgical centers retain limited inventory where budget constraints override upgrade cycles.
Single-Use Stethoscopes retain volume leadership; Digital Stethoscopes hold the steepest expansion curve.
End User:
Customer scale determines pricing leverage and contract structure more than clinical application.
- Hospitals:Integrated delivery networks negotiate direct manufacturer contracts bypassing group purchasing organizations. United States academic medical centers drive specification for wireless-enabled platforms.
- Surgical Centers:Ambulatory facilities prioritize single-use disposables to minimize sterilization infrastructure. German outpatient surgery units comply with Krankenhaus-Infektions-Schutz-Gesetz mandates.
- Specialty Clinics:Cardiac and pulmonary focused practices require precision auscultation with temperature monitoring capabilities.
- Home Healthcare:Minimal current penetration given procedural complexity and supervision requirements.
Hospitals command procurement volume; Surgical Centers are expanding most quickly as outpatient migration accelerates.
Technology:
Connectivity standards differentiate premium offerings from commodity tiers.
- Bluetooth Technology:Low Energy modules enable seamless integration with anesthesia information management systems. FDA 510(k) submissions for software validation extend timelines for these configurations.
- Wireless Technology:Broader protocol flexibility supports multi-device operating theater ecosystems. EU MDR digital health pathway offers streamlined conformity assessment for connected platforms.
- Analog Technology:Legacy headset designs persist where capital replacement cycles lag clinical need.
- Digital Technology:Signal processing enhancements improve sound clarity without wireless transmission capabilities.
Bluetooth Technology anchors premium positioning; Wireless Technology gains share fastest through protocol flexibility.
Application:
Clinical use case shapes sensor configuration and monitoring priority.
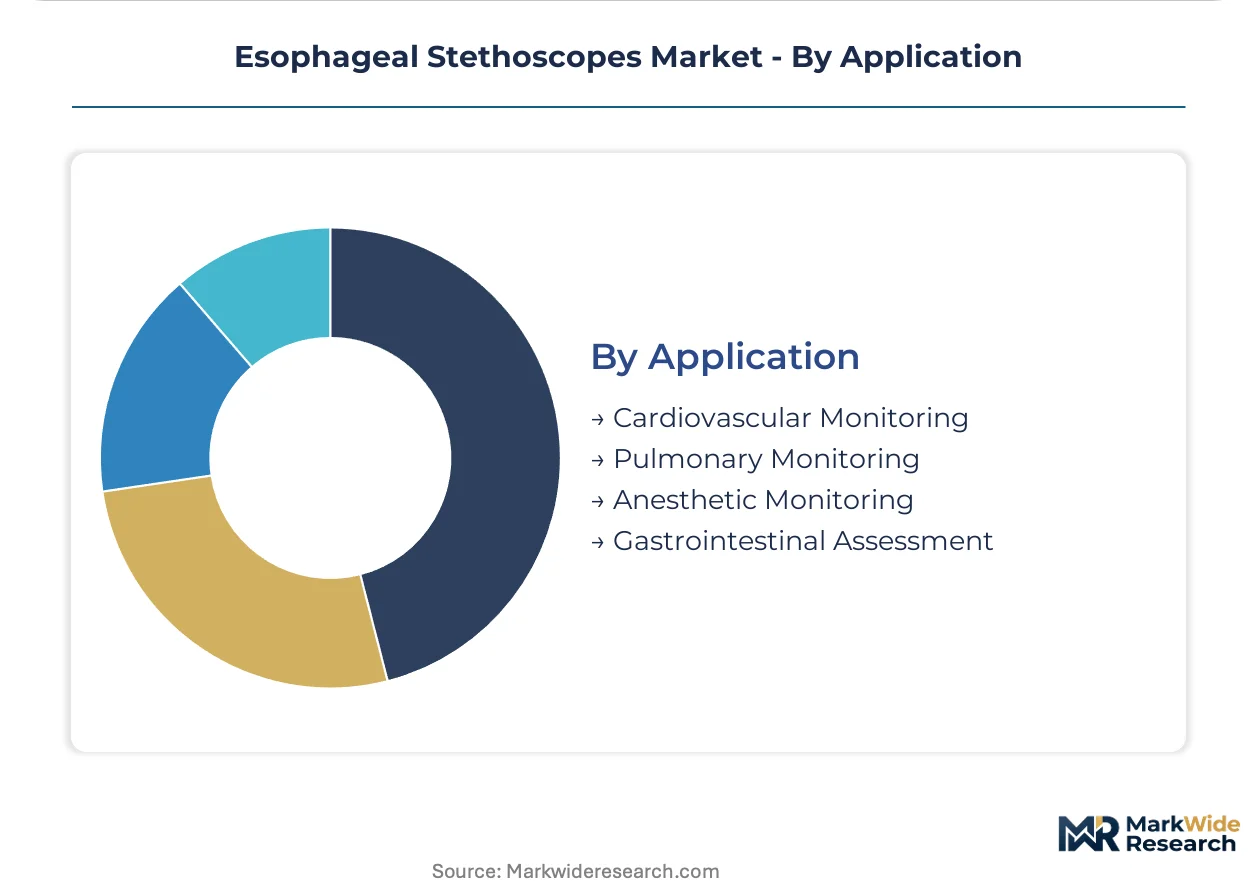
- Anesthetic Monitoring:Core body temperature tracking combined with cardiopulmonary auscultation during surgical sedation. United States operating theaters specify esophageal placement for continuous vital signs.
- Cardiovascular Monitoring:Heart sound amplification for ischemia detection and hemodynamic assessment. German cardiac surgery units demand precision thermistor calibration.
- Pulmonary Monitoring:Respiratory sound transmission competes with capnography for airway verification.
- Gastrointestinal Assessment:Limited esophageal deployment relative to dedicated endoscopic methods.
Anesthetic Monitoring retains procedural dominance; Cardiovascular Monitoring climbs fastest as cardiac surgery volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German university hospitals while procurement leverage fragments across United States integrated delivery networks. Japanese technical barriers sustain premium positioning for domestic incumbents. Indian surgical volume expansion is compressing per-unit margins despite volume acceleration.
United States
Academic medical centers in Boston and the Research Triangle specify wireless-enabled esophageal stethoscopes for anesthesia information management integration. FDA 510(k) premarket notification requirements for Bluetooth modules extend regulatory timelines beyond hardware-only submissions. The Cleveland Clinic and Mayo Clinic anchor procurement specification for disposable designs with integrated thermistor elements.
Germany
Cardiac surgery units in Munich and Heidelberg demand precision thermistor calibration for hemodynamic assessment during open-heart procedures. Krankenhaus-Infektions-Schutz-Gesetz mandates compel outpatient surgical centers to eliminate reusable diagnostic equipment from inventory. The Baden-Württemberg medical technology cluster around Tübingen sustains precision manufacturing relationships with hospital procurement networks.
Japan
Aging surgical demographics in Tokyo and Osaka metropolitan areas sustain demand for continuous core body temperature monitoring during prolonged procedures. PMDA certification timelines extend 18-24 months for non-domestic manufacturers, protecting domestic incumbent positions. The Nagoya medical device corridor concentrates production of specialized sensor elements for esophageal placement devices.
India
Government-funded health infrastructure under Ayushman Bharat creates first-time demand for disposable diagnostic accessories in tier-2 and tier-3 cities. CDSCO medical device rules impose quality management system requirements that filter import channels. The Hyderabad medical technology cluster and Bengaluru healthcare innovation corridor anchor domestic distribution networks for cost-optimized single-use designs.
United Kingdom
NHS procurement frameworks for anesthesia equipment prioritize infection control compliance in London and Manchester surgical hubs. MHRA post-Brexit regulatory alignment with EU MDR clinical evidence requirements extends conformity assessment timelines. The Oxford-Cambridge medical technology arc pilots wireless-enabled platforms for electronic patient record integration in teaching hospitals.
Esophageal Stethoscopes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor elements and polymer extrusions to finished device manufacturers. Market structure tiers across three distinct layers: diversified medical device conglomerates anchoring hospital system contracts, mid-scale diagnostic specialists competing through clinical training capabilities, and regional fabricators serving cost-sensitive surgical centers. Strategic archetypes include cardiac care portfolio bundlers, precision German manufacturers, and disposable supply chain optimizers. Dominant competitive moves encompass direct contracting with integrated delivery networks and regulatory capacity expansion for EU MDR notified body relationships.
Among diversified medical technology conglomerates, Medtronic leverages cardiac care portfolio breadth to anchor multi-year hospital system agreements. Welch Allyn occupies a position exemplifying diagnostic device specialization through clinical workflow integration capabilities. Riester GmbH & Co. KG represents precision manufacturing archetypes sustaining European clinical relationships through German engineering standards. These three anchors illustrate how competitive positioning stratifies across scale, specialization, and geographic manufacturing heritage rather than technology differentiation alone.
| Leading Market Players |
|---|
| 3M |
| Medtronic |
| Welch Allyn |
| Medline Industries |
| American Diagnostic Corporation |
| GF Health Products |
| ICU Medical |
| Riester GmbH & Co. KG |
| DeRoyal Industries |
| Others |
Pricing and Supply Chain Analysis
Medical-grade silicone feedstock volatility compresses margin buffers across all pricing tiers while simultaneously forcing manufacturers toward dual-sourcing strategies that reshape procurement geography. This input-cost uncertainty widens spreads between configured-to-order wireless platforms and standard single-use disposables as suppliers pass through petrochemical exposure selectively.
Pricing Analysis
Configured-to-order pricing for Bluetooth-enabled esophageal stethoscopes commands substantial premiums over standard single-use catalog pricing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared wireless platforms with software validation from CE-marked digital variants and basic analog disposables. Cost compression in the analog tier is intensifying because surgical centers with sunk headset investments resist fleet replacement cycles. Ambulatory surgical centers exhibit highest price sensitivity while academic medical centers in the United States prioritize specification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for thermistor elements and polymer extrusions rests with specialized medical device EMS providers in Malaysia, Mexico, and Costa Rica. Finished device assembly draws from medical-grade silicone suppliers in Germany and Japan alongside PVC compounders in the United States. Single-source vulnerability concentrates in Bluetooth Low Energy module supply from Taiwanese semiconductor fabricators. Distribution runs through specialty anesthesia equipment distributors with same-day logistics infrastructure displacing broad-line medical supply catalogs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital surgical volume cyclicality is recovering from pandemic-depressed baselines as elective procedure backlogs clear across Western European and North American health systems.
For Market Incumbents: Insulate market position through backward integration into medical-grade silicone compounding to neutralize petrochemical margin volatility, while expanding regulatory affairs capacity for EU MDR notified body relationships to defend against compliance-driven market exits. Capnography substitution threats in anesthesia workflows demand software companion development to embed esophageal stethoscope data within electronic anesthesia record platforms. For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities under government-funded health infrastructure expansion present the most penetrable white-space for cost-optimized single-use designs. CDSCO quality management system requirements filter import channels, creating partnership opportunities with Hyderabad medical technology cluster fabricators. Direct contracting with Ayushman Bharat-empaneled hospital chains bypasses established GPO leverage structures. For Investors and Strategic Acquirers: EU MDR post-market surveillance obligation enforcement reshapes the acquisition landscape toward targets with dedicated clinical evidence portfolios and notified body consolidation relationships. Five-to-ten year viability favors mid-scale diagnostic specialists with anesthesia workflow training capabilities over commodity disposable suppliers. Monitor FDA guidance timeline acceleration on reusable device reprocessing as inflection signal for disposable demand step-change.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Bluetooth-enabled platforms with software validation secure first-mover positioning in academic medical center procurement. |
| CE Marking Pathway Investment | EU MDR clinical evidence portfolios open renewal-cycle competitive moats against under-resourced competitors. |
| Hospital System Partnership | Integrated delivery network direct contracting captures full margin from bypassed group purchasing organization intermediaries. |
| Software Companion Development | Anesthesia information management system integration embeds device data within electronic patient record workflows. |
| Reimbursement Strategy | CPT code alignment for continuous core temperature monitoring during surgical procedures sustains procurement justification. |
Research Methodology
Initial hypotheses were tested against primary input from anesthesiology department heads, hospital purchasing committee chairs, biomedical engineers, and group purchasing organization contract managers and refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body conformity assessment records, hospital procurement contract repositories, and medical device trade flow customs data. Bottom-up surgical volume modeling and top-down medical device market sizing were triangulated to constrain estimate ranges.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end-user facility scale, connectivity technology, and clinical application. CAGRs were derived from procedure volume elasticity modeling and per-procedure device utilization rates. Forecast inputs incorporated FDA reprocessing guidance compliance timelines and German infection control mandate enforcement trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by wireless platform specialists or capnography manufacturers would shift outcomes through technology substitution acceleration. Quarterly review of FDA guidance document publication schedules and EU MDR notified body capacity allocation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Global Suture Anchor Devices Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Global Smart Contact Lenses Market
Medical Devices
Capsulotomy Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Bariatric Beds Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
X-Ray Stretchers Market
Medical Devices
Global Bone Cement Market
Medical Devices
Telehealth Device Market