
 Ophthalmology Surgical Devices Market | 2026-2036
Ophthalmology Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmology Surgical Devices Market Outlook
Modular instrument bundles paired with single-use consumables is realigning procurement patterns among ambulatory surgical centers. Alcon Inc. leverages its vertically integrated manufacturing footprint across phacoemulsification platforms. Johnson and Johnson Services Inc. anchors its position through sustained R&D investment in femtosecond laser systems. Carl Zeiss AG differentiates via precision optics technology leadership in diagnostic-guided surgical workflows.
Ophthalmology surgical devices encompass precision-engineered instruments, implants, and laser systems designed for intraocular manipulation with tolerances measured in micrometers, typically manufactured from medical-grade stainless steel, titanium, or biocompatible polymers under ISO 13485 quality management protocols. These devices enable restoration of visual function through corneal reshaping, lens replacement, or retinal reattachment procedures performed in sterile operating environments. Implants and instruments command the deepest margin pools due to recurring replacement cycles and proprietary design lock-in, while laser surgery technology represents the fastest-growing dimension as practices convert from manual to computer-guided ablation platforms. Ambulatory surgical centers now constitute the most dynamic end-user channel, displacing hospital outpatient departments through dedicated ophthalmology workflow efficiency and lower overhead structures.
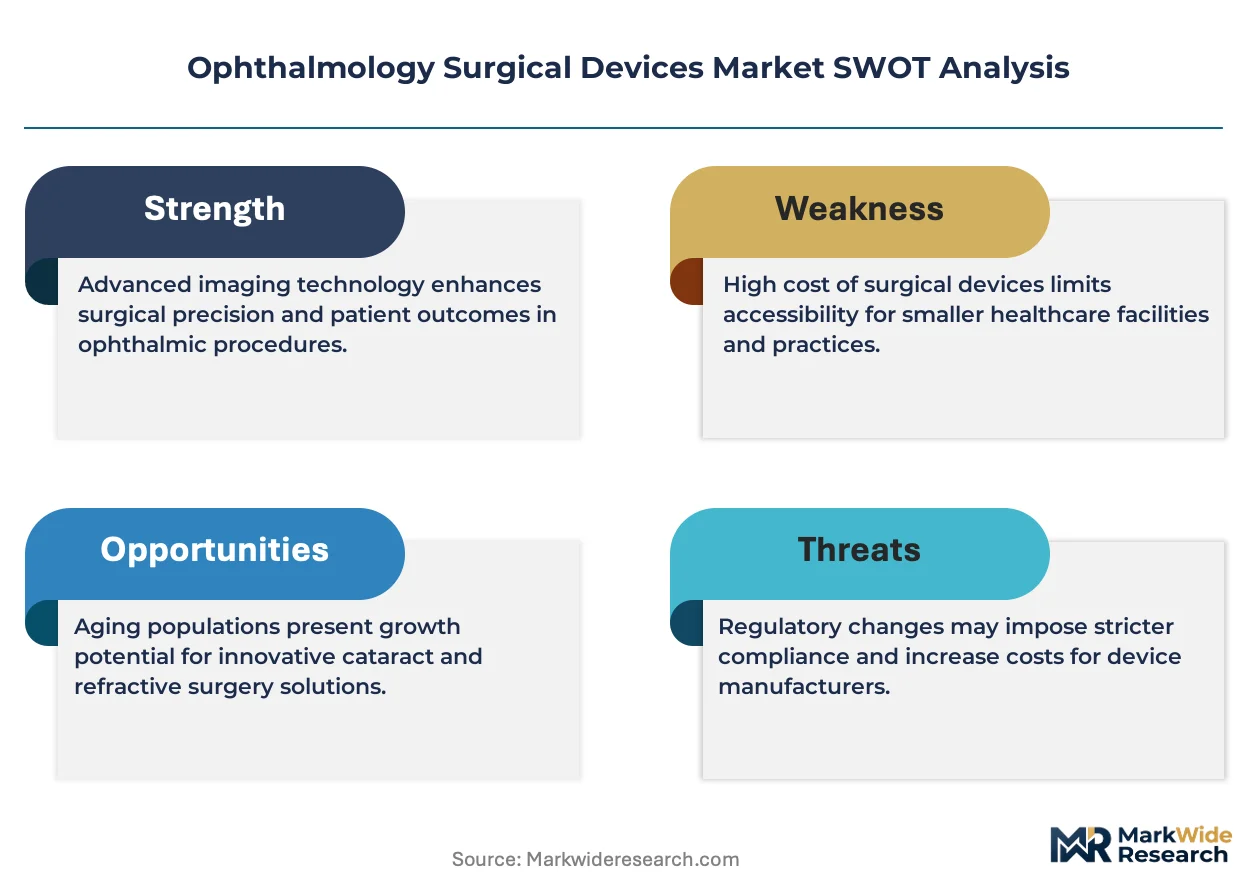
FDA premarket clearance requirements under 21 CFR Part 820 govern quality system regulation for U.S. device manufacturers, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for CE marking access across European markets. ISO 10993 biocompatibility testing protocols and IEC 60601 electrical safety standards further constrain product design choices and certification timelines. Stakeholders must monitor evolving reimbursement coding for femtosecond laser-assisted cataract procedures and track MDR notified body capacity constraints that could delay European market entry for novel surgical platforms.
Market Dynamics
Femtosecond laser platforms are compressing procedure times and expanding treatable patient populations, while EU MDR notified body capacity constraints are elongating certification timelines for novel surgical platforms.
Growth Catalysts
- Aging demographics in the United States:Medicare reimbursement frameworks sustain high-volume cataract procedure pipelines. Ambulatory surgical centers convert these volumes into predictable revenue streams.
- ISO 13485 quality management protocols:Standardized manufacturing benchmarks reduce regulatory friction for multi-market launches. Device manufacturers leverage these protocols to accelerate CE marking preparation.
- Femtosecond laser-assisted cataract surgery:Computer-guided ablation platforms reduce phacoemulsification energy requirements. Corneal specialists adopt these systems to improve capsulotomy precision.
Market Restraints
- EU MDR clinical evidence requirements:Stricter documentation standards for Class IIb surgical devices extend notified body review cycles. European market entry timelines stretch by 12-18 months for novel platforms.
- Titanium and medical-grade polymer supply concentration:Specialized metallurgical suppliers in Germany and Switzerland control premium alloy feedstocks. Price volatility in aerospace-grade titanium spills into medical device bill-of-materials.
- Manual microkeratome persistence in price-sensitive segments:Lower-cost blade-based systems retain share in emerging markets. Laser platform conversion rates stall where capital expenditure constraints dominate purchasing decisions.
Strategic Opportunities
- India's underserved cataract backlog:The country's national health mission targets 6 million annual procedures. Mobile surgical units and hub-and-spoke ASC networks address rural access gaps.
- Diagnostic-guided surgical workflow convergence:Integration of optical coherence tomography with femtosecond laser platforms enables real-time anatomical feedback. Surgeons customize ablation patterns based on preoperative biometric data.
- United States Medicare Advantage carve-out contracts:Payer direct contracting with ophthalmology ASC chains creates volume guarantees. Bundled payment structures align device procurement with episode-based reimbursement.
Industry Challenges
- Femtosecond laser technician certification bottlenecks:Manufacturer-specific training programs limit staff mobility between platforms. ASC administrators face scheduling constraints when certified technicians depart.
- ISO 10993 biocompatibility testing backlog:Contract research organization capacity constraints delay cytotoxicity and sensitization studies. Novel polymer introductions stall at the preclinical validation stage.
- Legacy phacoemulsification system interoperability:Proprietary fluidics management protocols resist integration with third-party consumable bundles. Hospital purchasing committees encounter vendor lock-in resistance during capital planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmology Surgical Devices Market |
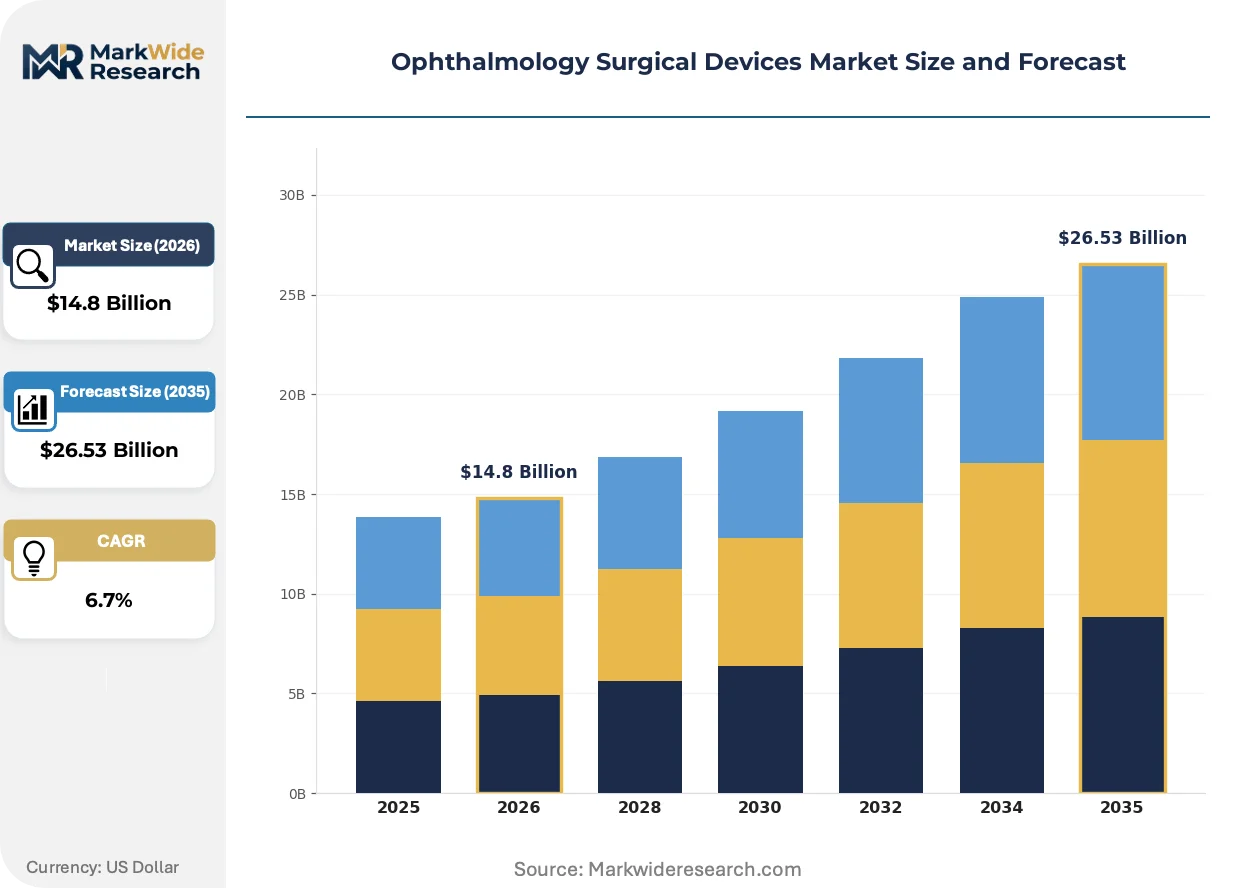
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Implants, Diagnostic Devices, Surgical Equipment End User: Hospitals, Ambulatory Surgical Centers, Clinics, Eye Care Centers Technology: Laser Surgery, Phacoemulsification, Vitrectomy, Cataract Surgery Application: Retina Repair, Cataract Removal, Corneal Surgery, Glaucoma Treatment |
| Companies Covered | Alcon Inc., Johnson and Johnson Services Inc., Bausch Health Companies Inc., Carl Zeiss AG, Glaukos Corp., HOYA Corp., STAAR Surgical Co., Topcon Corp., NIDEK Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmology Surgical Devices Market Strategic Shifts
Device architecture is fragmenting into interoperable subsystems, while regulatory jurisdictions impose divergent evidentiary standards for software-enabled surgical platforms.
Phacoemulsification handpiece design is modularizing around disposable silicone sleeve and titanium needle combinations. ASC procurement teams mix instrument bundles from competing suppliers to optimize per-procedure economics. This architecture compresses capital equipment replacement cycles while expanding aftermarket consumable attach rates.
The EU Medical Device Regulation's software-as-a-medical-device classification criteria are redefining predicate device pathways for AI-enabled surgical planning tools. Manufacturers must now submit standalone clinical validation studies for algorithm-driven ablation mapping. Retinal surgery platforms with integrated image-guidance face the steepest compliance cost escalation.
Ambulatory surgical centers in the United States are unbundling preventive maintenance contracts from capital equipment purchases. Third-party clinical engineering firms now service femtosecond laser platforms previously restricted to manufacturer technicians. This channel fragmentation concentrates in Florida and Texas, where ASC chains operate sufficient device density to justify independent service organization economics.
Ophthalmology Surgical Devices Market Segmentation
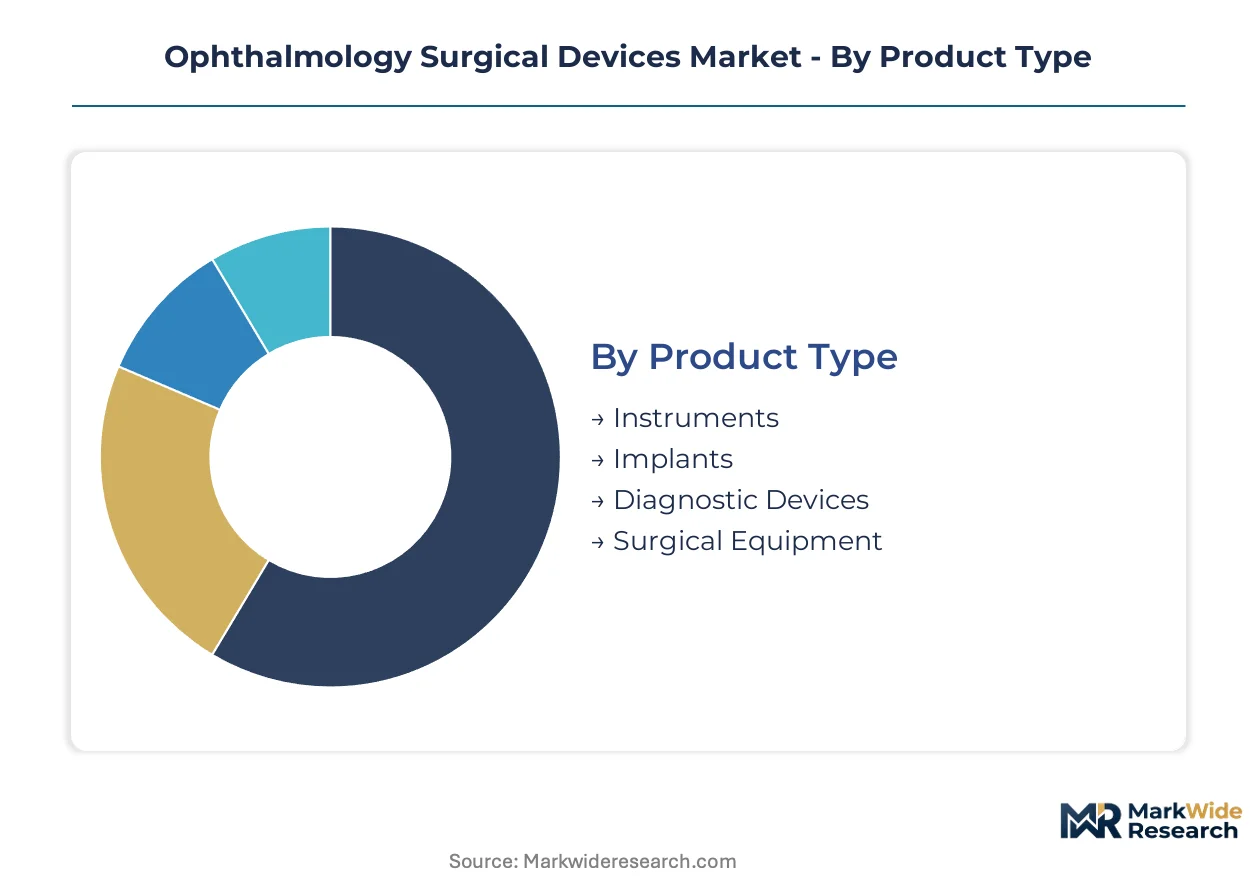
Segmentation in ophthalmology surgical devices reveals how procurement patterns diverge between high-volume ambulatory settings and capital-intensive hospital systems. Each dimension—product architecture, site of care, energy modality, and anatomical target—carries distinct margin profiles and replacement cycles that reshape vendor strategies.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized disposable instruments to proprietary implant designs locked to specific delivery systems.
- Implants:Intraocular lenses and glaucoma drainage devices incorporate hydrophobic acrylic or silicone optics with proprietary haptic geometries. Demand clusters in United States Medicare-funded cataract corridors where ASCs capture case volume through dedicated ophthalmology workflows. Reimbursement coding for premium toric and multifocal variants drives upgrade cycles.
- Surgical Equipment:Femtosecond laser platforms and phacoemulsification consoles represent capital-intensive infrastructure with decade-long depreciation schedules. Hospital purchasing committees in Germany and Japan prioritize interoperability with existing diagnostic suites over standalone performance metrics.
- Instruments:Titanium microforceps and silicone-tipped cannulas manufactured under ISO 13485 protocols support single-use or limited-reuse protocols depending on sterilization infrastructure.
- Diagnostic Devices:Optical coherence tomography systems and aberrometers feed preoperative planning data into surgical platforms through DICOM-compliant interfaces.
Most installed capacity flows through Surgical Equipment. Expansion is steepest in Implants.
End User:
Site-of-care economics dictate capital deployment velocity, with overhead structures and reimbursement pathways creating divergent procurement rhythms.
- Ambulatory Surgical Centers:Dedicated ophthalmology ASCs in Florida and Texas achieve case volumes exceeding 15,000 cataract procedures annually per facility. Bundled payment contracts with Medicare Advantage plans compress device procurement into per-episode cost targets. Workflow efficiency metrics—turnover time, sterile processing throughput—dominate vendor selection.
- Hospitals:Academic medical centers in the United States and university hospitals in France maintain hybrid portfolios serving both routine and complex surgical populations. Capital budgeting cycles extend 24-36 months, with procurement committees weighing research collaboration value alongside clinical performance.
- Clinics:Office-based surgical suites in India and Brazil concentrate on manual small-incision techniques where laser platform economics fail at low case density.
- Eye Care Centers:Integrated diagnostic-surgical facilities in South Korea and Japan emphasize premium IOL upsell pathways supported by corneal topography-guided selection algorithms.
Procedure volume concentrates in Ambulatory Surgical Centers. Capacity additions are climbing fastest in Eye Care Centers.
Technology:
Energy delivery modalities segment by capital intensity and consumable attach rates, with laser platforms commanding premium positioning against established ultrasound systems.
- Laser Surgery:Femtosecond platforms perform capsulotomy, lens fragmentation, and corneal flap creation through computer-guided ablation. United States corneal specialists adopt these systems to reduce phacoemulsification energy exposure and improve refractive predictability. FDA 510(k) clearance pathways for software updates create recurring regulatory engagement.
- Phacoemulsification:Ultrasound handpieces with peristaltic or venturi fluidics management remain the workhorse for lens removal across all geographies. Modular tip designs allow ASCs to source consumables from third-party suppliers, compressing OEM margin capture.
- Vitrectomy:Pneumatic and electric cutter systems address posterior segment pathology with gauge sizes trending smaller—27-gauge instruments reducing sclerotomy trauma.
- Cataract Surgery:Manual and automated techniques span the cost spectrum from manual small-incision cataract surgery in rural India to laser-assisted workflows in German university hospitals.
Phacoemulsification systems constitute the largest installed base. Laser Surgery platforms are gaining share fastest among new capital deployments.
Application:
Anatomical target selection determines device specifications, with posterior segment procedures requiring more complex visualization infrastructure than anterior segment workflows.
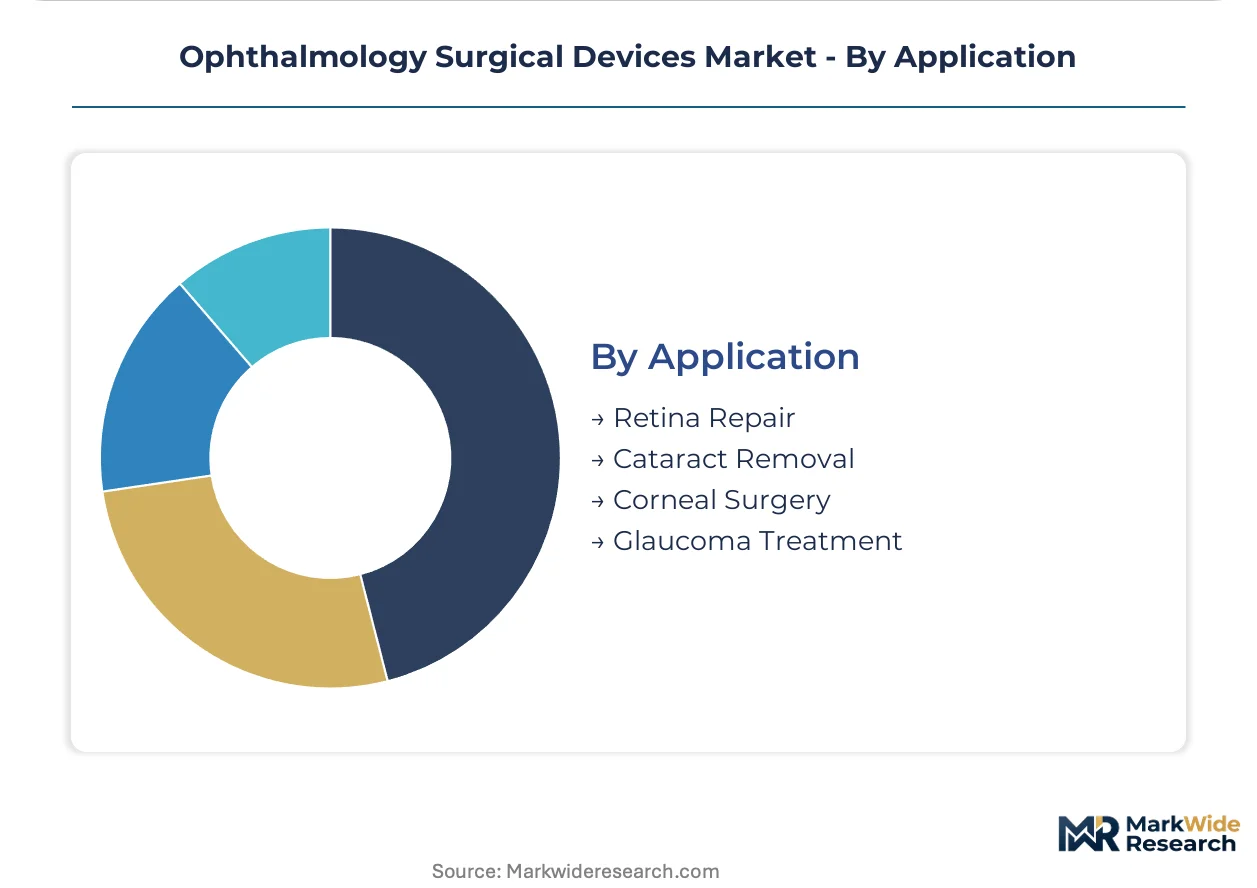
- Cataract Removal:Lens extraction with IOL implantation represents the highest-volume application globally, with procedure counts exceeding all other categories combined. United States Medicare reimbursement sustains predictable demand pipelines through aging demographic penetration.
- Retina Repair:Vitrectomy and membrane peeling for macular holes, retinal detachment, and diabetic retinopathy demand integrated microscope-illumination-cutter systems. German and Japanese retinal specialists drive adoption of heads-up 3D visualization platforms that reduce surgeon fatigue during lengthy cases.
- Corneal Surgery:Penetrating and lamellar keratoplasty, combined with refractive laser ablation, serve transplant and elective vision correction populations. DMEK and DSAEK techniques concentrate in specialized centers with active eye bank relationships.
- Glaucoma Treatment:Minimally invasive glaucoma surgery devices—stents, shunts, and ablation systems—target medication non-responders with lower risk profiles than trabeculectomy.
Cataract Removal absorbs the majority of device throughput. Retina Repair applications are expanding most quickly as diabetic population prevalence climbs in India and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ophthalmology surgical device manufacturing traces its industrial lineage to precision optics workshops in Jena, Germany, where Carl Zeiss AG pioneered microscope-integrated surgery in the early twentieth century. This German foundation established quality protocols that now govern ISO 13485-certified production across three continents. Contemporary demand clusters reflect both aging demographics and reimbursement infrastructure density.
United States
Medicare reimbursement frameworks sustain over 3.5 million annual cataract procedures, with ambulatory surgical centers in Florida and Texas capturing case volumes exceeding 15,000 per facility. The FDA's 510(k) premarket notification pathway under 21 CFR Part 820 governs Class II surgical device clearances. Boston and Minneapolis host concentrated clusters of phacoemulsification console engineering and femtosecond laser software development.
Germany
University hospitals in Heidelberg and Tübingen drive adoption of heads-up 3D visualization platforms for retinal surgery, while statutory health insurance maintains predictable reimbursement for premium intraocular lenses. The EU Medical Device Regulation imposes stricter clinical evidence standards through notified bodies in Berlin and Munich. The Stuttgart-Oberkochen corridor anchors precision optics manufacturing for diagnostic-guided surgical workflows.
Japan
Metropolitan Tokyo and Osaka eye care centers emphasize premium IOL upsell pathways supported by corneal topography-guided selection algorithms. The PMDA reviews software-as-a-medical-device classifications for AI-enabled surgical planning tools under harmonized IMDRF guidelines. Nagoya hosts specialized metallurgical suppliers controlling aerospace-grade titanium feedstock for microsurgical instrument production.
India
The national health mission targets 6 million annual cataract procedures, with mobile surgical units and hub-and-spoke ASC networks addressing rural access gaps in Maharashtra and Tamil Nadu. CDSCO regulates medical device imports and manufacturing under the Medical Devices Rules 2017. Aravind Eye Care System in Madurai demonstrates high-volume, low-cost surgical device utilization models now replicated across South Asia.
China
Domestic manufacturers in Suzhou and Shenzhen scale production of phacoemulsification handpieces for price-sensitive segments while NMPA accelerates review timelines for innovative ophthalmic implants. The 14th Five-Year Plan prioritizes domestic substitution in high-end medical equipment. Shanghai's Zhangjiang Hi-Tech Park concentrates foreign-invested R&D centers for femtosecond laser platform localization.
Ophthalmology Surgical Devices Market Competitive Environment
Premium-margin players sit above commodity-margin players across implant customization and laser platform sophistication. The vendor base organizes into three tiers: diversified multinationals with vertically integrated manufacturing, specialized ophthalmology pure-plays with proprietary delivery systems, and regional assemblers competing on per-procedure economics. Consolidation pressures concentrate among mid-scale instrument manufacturers facing ISO 13485 certification cost escalation. Dominant competitive moves include strategic partnerships for diagnostic-surgical workflow integration and capacity expansion in Indian and Chinese contract manufacturing.
Within the diversified multinational tier, Alcon Inc. and Johnson and Johnson Services Inc. occupy positions anchored by sustained infrastructure investment across phacoemulsification and femtosecond laser platforms. Carl Zeiss AG exemplifies the precision optics specialist archetype, with its Jena-based heritage informing diagnostic-guided surgical workflow convergence. These three entities represent contrasting strategic postures: Alcon Inc. leverages consumable attach rates, Johnson and Johnson Services Inc. emphasizes R&D depth in laser systems, and Carl Zeiss AG maintains technology leadership in optical coherence tomography integration.
| Leading Market Players |
|---|
| Alcon Inc. |
| Johnson and Johnson Services Inc. |
| Bausch Health Companies Inc. |
| Carl Zeiss AG |
| Glaukos Corp. |
| HOYA Corp. |
| STAAR Surgical Co. |
| Topcon Corp. |
| NIDEK Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into titanium needle manufacturing and proprietary silicone sleeve production anchors margin capture for phacoemulsification console suppliers while compressing third-party aftermarket opportunities. This captive supply structure concentrates pricing power with OEMs that control both capital equipment and recurring consumable streams, leaving independent instrument assemblers to compete on per-procedure economics in price-sensitive ambulatory settings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates femtosecond laser platforms from modular phacoemulsification systems and manual microkeratome alternatives. Price differentiation hinges on FDA clearance tier and ISO 13485 certification pedigree, with CE marking under EU MDR adding cost premiums for European market access. Margins are tightening due to third-party clinical engineering firms unbundling preventive maintenance contracts from capital sales. Ambulatory surgical centers in Florida and Texas exhibit highest price sensitivity, while German university hospitals prioritize interoperability premiums over per-unit cost.
Supply Chain Analysis
Domestic-content mandates in China's 14th Five-Year Plan and India's PLI scheme for medical devices are reshaping sourcing patterns for precision optics and aerospace-grade titanium feedstock. Manufacturing concentrates in Germany, Switzerland, and Japan for metallurgical components, while China scales phacoemulsification handpiece assembly. Raw material dependencies span German hydrophobic acrylic for intraocular lenses, Swiss titanium alloys for microsurgical instruments, and Japanese optical glass for diagnostic integration. Single-source vulnerability persists in femtosecond laser crystal supply. Distribution runs through ambulatory surgical center chains in the United States and hospital procurement committees in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ophthalmology surgical devices rests on consumable attach-rate optimization and premium IOL upsell conversion in Medicare Advantage corridors. Cost compression in manual instrument tiers creates acquisition opportunities for platform consolidators.
For Market Incumbents: Anticipate EU MDR notified body capacity constraints extending certification timelines for software-enabled surgical platforms by prioritizing early-stage clinical evidence generation. Defend consumable revenue streams by tightening proprietary fluidics management protocols against third-party instrument bundles. Capacity addition in Indian contract manufacturing addresses price competition from domestic assemblers in Suzhou and Shenzhen. For New Entrants and Emerging Players: FDA's 510(k) premarket notification pathway for Class II surgical devices opens a window for femtosecond laser platform entrants with predicate device strategies. White-space targets include mobile surgical units for India's rural cataract backlog and diagnostic-guided workflow convergence integrating optical coherence tomography. Go-to-market positioning through hub-and-spoke ASC networks in Maharashtra and Tamil Nadu bypasses capital-intensive hospital sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ISO 13485-certified instrument manufacturers because certification cost escalation pressures sub-scale competitors toward exit. Long-term viability favors platforms with recurring consumable revenue over pure capital equipment plays. Acquisition target archetype: specialized ophthalmology pure-plays with proprietary IOL delivery systems. Signal to watch: Medicare Advantage carve-out contract density in Texas and Florida as volume guarantee indicators.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend notified body review cycles for novel platforms. |
| Hospital System Partnership | Medicare Advantage bundled contracts with ASC chains align device procurement with episode reimbursement. |
| Software Companion Development | AI-enabled surgical planning tools face standalone validation studies under FDA software-as-medical-device criteria. |
| Reimbursement Strategy | Coding for femtosecond laser-assisted cataract procedures determines platform adoption velocity. |
| Backward Integration | In-house titanium needle production captures consumable margin pools from third-party suppliers. |
Study Parameters
Multiple input streams — surgeon interviews, ASC administrator panels, regulatory filing analysis, and procurement database mining — were reconciled to construct demand estimates. Primary engagement spanned cataract surgeons, biomedical engineering directors, GPO contracts managers, and femtosecond laser technicians across United States, German, and Japanese facilities. Secondary validation drew from FDA 510(k) clearances, EU MDR notified body registrations, CMS Medicare procedure data, and ISO 13485 certification directories. Bottom-up procedure volume modeling and top-down equipment installed base estimates were triangulated against manufacturer-reported platform placements.
Historical shipment data was cross-referenced against forward-looking panel input from purchasing committees and capital planning directors. Segmentation dimensions modeled encompass product architecture, site-of-care economics, energy delivery modality, and anatomical application target across the analysis window. CAGRs were derived from procedure volume trajectories, equipment replacement cycles, and consumable attach-rate assumptions. Industry-specific forecast inputs included Medicare demographic penetration curves and EU MDR implementation phase impacts on certification timelines.
Revisions become necessary when notified body capacity constraints intensify, aerospace-grade titanium supply disruptions materialize, or Medicare Advantage bundled payment structures shift episode definitions. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory pathway predictability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Uro Gynaecological Surgical Devices Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
US Surgical Sutures Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Minimally Invasive Surgical Instruments Market
Surgical Instruments
Dermal Curettes Market
Surgical Instruments
Robotic Surgery Market