
 Smear Mask Market | 2026-2036
Smear Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Smear Mask Market Insights
REACH compliance is repositioning the cost-of-entry calculus for European smear mask entrants, forcing reformulation investments that favor capitalized incumbents. Estée Lauder leverages its prestige R&D infrastructure to navigate complex toxicology dossiers ahead of smaller rivals. Shiseido anchors its competitive stance through deep vertical integration in active ingredient sourcing from Japanese biotech suppliers. PROYA dominates domestic e-commerce channels in China, sustaining margin through direct-to-consumer live-streaming operations.
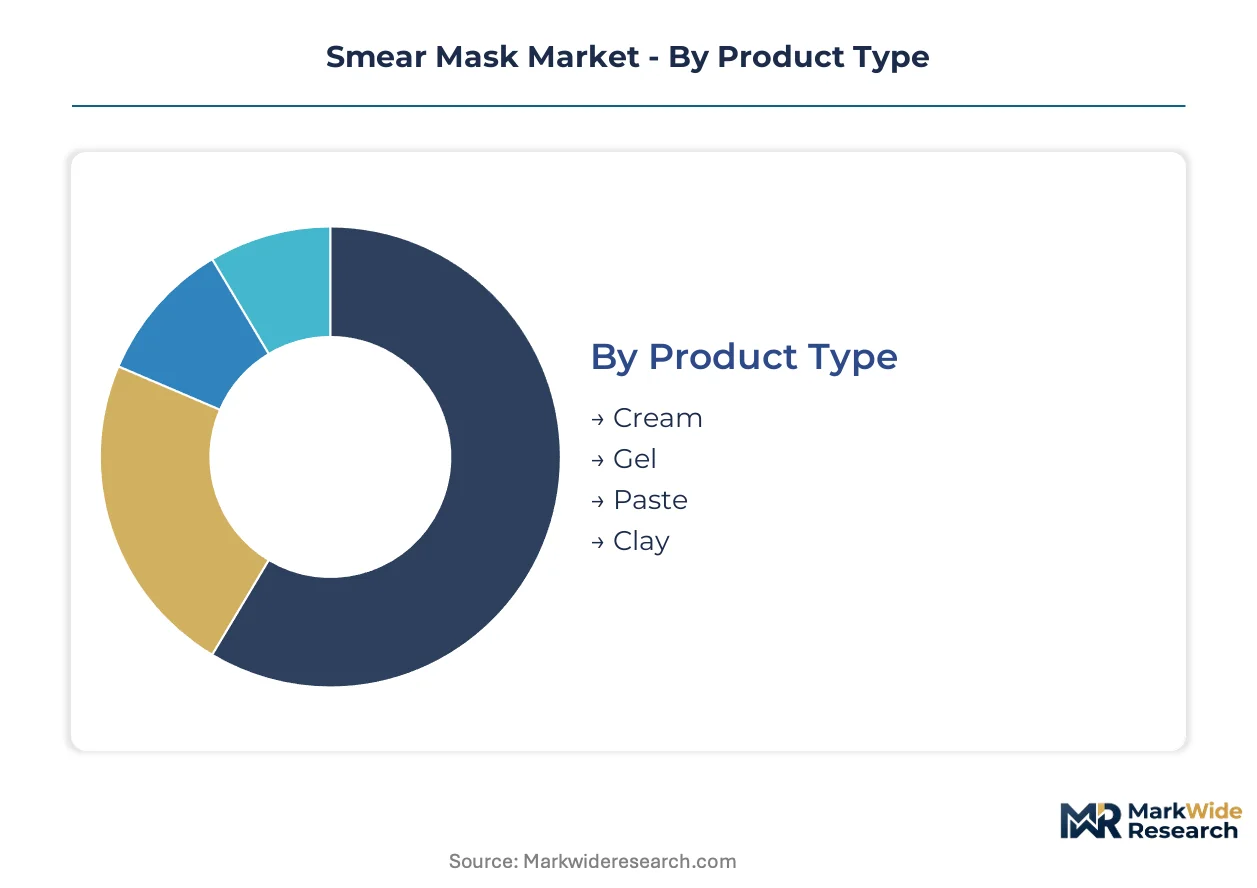
Smear masks are viscous topical formulations designed for controlled residence time on facial skin, typically incorporating humectants, clays, or bioactive extracts at concentrations between five and twenty percent to achieve targeted exfoliation, hydration, or sebum regulation. Cream-based smear masks command the largest revenue pool due to universal compatibility across skin types and lower per-unit manufacturing complexity. Gel formulations represent the fastest-expanding product type as consumers in aesthetic clinics and home-care segments prioritize lightweight, non-comedogenic textures for frequent application. Natural and herbal ingredient types capture premium pricing power, though synthetic segments retain volume leadership in mass-market salon channels where cost consistency matters.
FDA cosmetic labeling requirements and the EU Cosmetics Regulation jointly constrain formulation freedom, while China's NMPA registration pathway for imported cosmetics extends time-to-market for foreign brands. These frameworks elevate testing documentation burdens but simultaneously reward pre-qualified suppliers with durable shelf placements at regulated retail and clinical outlets. Stakeholders must weigh regulatory pre-investment against channel access velocity when sequencing geographic expansion priorities.
Market Dynamics
Professional aesthetic clinics are expanding facial treatment menus faster than home-care channels, compressing product development cycles and forcing suppliers to choose between salon-grade efficacy claims and mass-market accessibility. This bifurcation is restructuring competitive positioning around channel-specific certification pathways rather than universal formulations.
Growth Catalysts
- K-beauty innovation cycles:South Korean manufacturers accelerate premium smear mask launches through compressed R&D timelines, pulling global ingredient trends toward fermented extracts and microbiome-targeted actives.
- EU Cosmetics Regulation disclosure mandates:Stricter ingredient transparency rules are elevating consumer trust in documented formulations, creating shelf-space advantages for compliant suppliers at regulated retail outlets.
- Professional channel expansion:Aesthetic clinics in urban China and Southeast Asian metros are adding smear masks to post-procedure care protocols, generating volume pull-through for medical-grade hydration and barrier-repair variants.
Market Restraints
- REACH compliance costs:European toxicology dossier requirements for novel actives are forcing reformulation investments that disproportionately burden smaller entrants lacking capitalized R&D infrastructure.
- Active ingredient supply concentration:Japanese biotech suppliers dominate captive production of specialized fermented extracts, creating sourcing bottlenecks for brands without long-term offtake agreements.
- China NMPA registration timelines:Imported cosmetics face extended pre-market approval pathways, delaying revenue recognition for foreign brands targeting domestic e-commerce penetration.
Strategic Opportunities
- Live-streaming commerce penetration:Direct-to-consumer video commerce in China enables margin capture outside traditional retail markups, rewarding brands with in-house influencer networks and localized content studios.
- Gel texture substitution:Lightweight non-comedogenic formulations are displacing cream-based alternatives in clinic settings, opening white space for texture-innovation specialists.
- Natural ingredient premiumization:Herbal and botanical positioning commands pricing power in prestige channels, particularly where Korean and Japanese origin stories support clean-beauty narratives.
Industry Challenges
- Documentation burden compression:FDA cosmetic labeling and EU Cosmetics Regulation testing requirements are extending product development timelines, forcing trade-offs between geographic launch sequencing and revenue velocity.
- Formulation talent scarcity:Cosmetic chemists with dual expertise in regulatory compliance and aesthetic clinic efficacy standards command premium compensation, constraining mid-tier brand expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smear Mask Market |
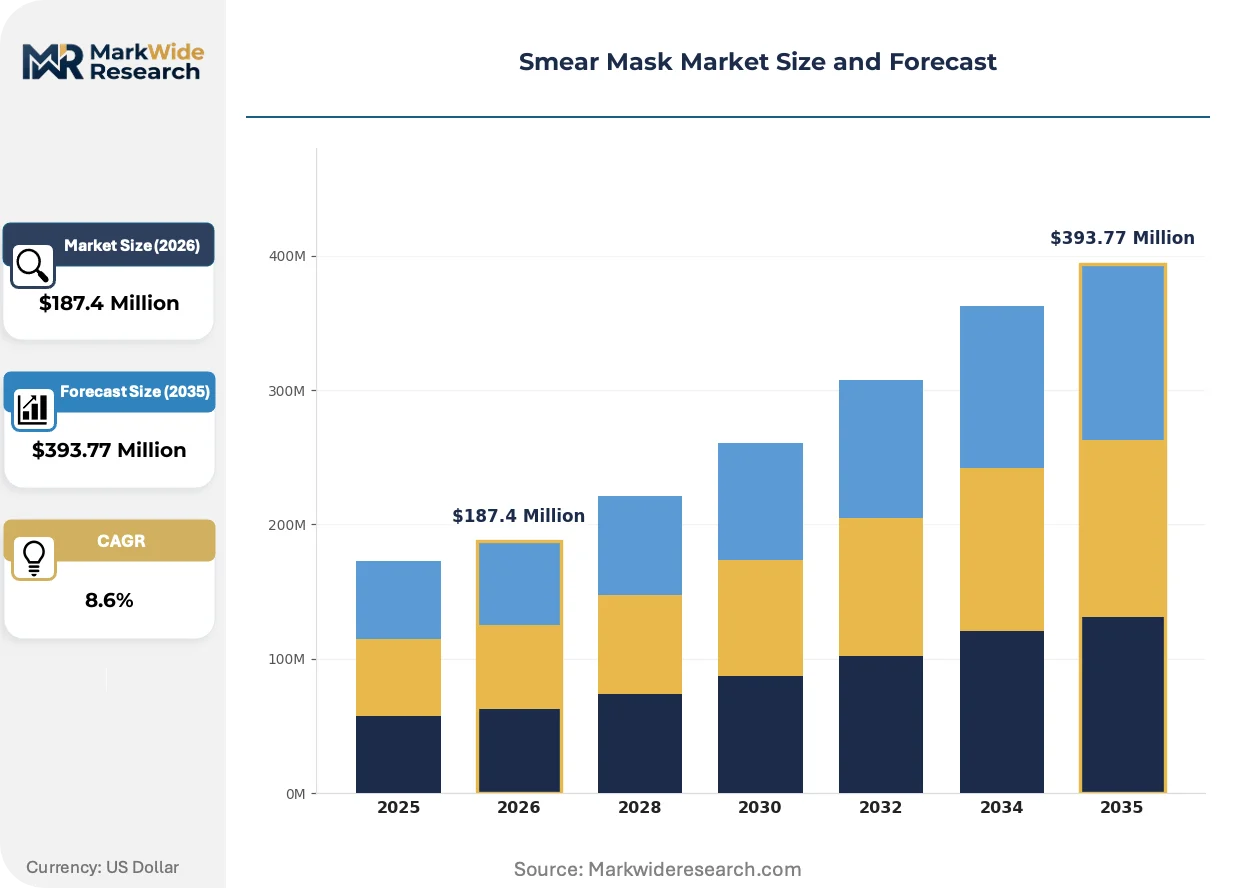
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Gel, Paste, Clay End User: Salons, Spa Centers, Home Care, Aesthetic Clinics Distribution Channel: Online, Offline, Specialty Stores, Direct Sales Ingredient Type: Natural, Organic, Synthetic, Herbal |
| Companies Covered | Unilever, Estée Lauder, Shiseido, AmorePacific, Mary Kay, Magic Holdings International Limited, PROYA, geoskincare, L'Oréal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smear Mask Market Trends and Innovations
Automation of quality assurance and texture engineering is compressing batch-to-batch variability while enabling personalized mask formulations. These shifts are redrawing capability boundaries between contract manufacturers and brand-owned production.
Encapsulation technology using stimuli-responsive polymers is automating controlled-release delivery of active ingredients during mask residence time. Aesthetic clinics in Seoul and Tokyo are adopting these systems for post-laser hydration protocols. The technology is automating consistency in professional settings previously dependent on technician application skill.
REACH authorization requirements for novel preservative systems are forcing substitution toward established INCI-listed alternatives. European formulators are retreating from experimental biocide combinations, consolidating demand around pre-approved supplier portfolios. Color-cosmetic crossover brands entering skincare are most affected, lacking legacy toxicology documentation.
Clinic procurement officers are consolidating vendor relationships around full-protocol suppliers offering masks, serums, and aftercare in unified sourcing agreements. Independent aesthetic chains in Shanghai and Shenzhen are displacing single-product orders with annual framework contracts. South Korean clinic networks demonstrate the most advanced procurement compression, bundling device and consumable spend.
Smear Mask Market Segmentation
Smear mask manufacturers face divergent formulation requirements across professional and consumer channels. Channel-specific efficacy standards and texture preferences fragment production planning, forcing suppliers to maintain parallel product architectures rather than unified platforms.
Product Type:
Customization intensity varies sharply across this category, with professional channels demanding bespoke viscosity profiles while mass-market SKUs prioritize manufacturing repeatability.
- Cream:Viscous oil-in-water emulsions incorporating humectants and occlusive agents at 10-20% active load. Demand concentrates in aesthetic clinics across Germany and France, where post-procedure hydration protocols favor rich, slow-absorbing textures that extend treatment perceived value.
- Gel:Hydrocolloid matrices delivering lightweight, non-comedogenic residence on skin. Clinics in Seoul and Tokyo are displacing cream alternatives for frequent-application protocols, prioritizing rapid absorption and minimal residue for compressed appointment schedules.
- Paste:High-solid-content formulations with elevated clay or powder fractions for targeted sebum absorption.
- Clay:Mineral-rich bases featuring bentonite or kaolin at 25-40% concentration for deep cleansing applications.
Most installed capacity flows through Cream formulations. Expansion is steepest in Gel textures.
End User:
Volume concentration tracks channel access velocity, with regulated clinical outlets imposing documentation burdens that favor pre-qualified suppliers.
- Salons:Service-oriented channels requiring cost-predictable, multi-skin-type compatible formulations with simplified technician training.
- Spa Centers:Experience-driven environments where ritual duration and sensory positioning command premium pricing power.
- Home Care:Self-application segments where packaging convenience and shelf stability outweigh professional-grade efficacy claims. Demand concentrates in China's live-streaming commerce channels, where direct-to-consumer margins reward localized influencer networks and rapid fulfillment infrastructure.
- Aesthetic Clinics:Medical-adjacent settings requiring documented barrier-repair and post-procedure hydration claims. Seoul clinic networks demonstrate the most compressed procurement cycles, bundling device and consumable spend under annual framework contracts.
Revenue gravity centers on Aesthetic Clinics. Volume expansion runs fastest through Home Care channels.
Distribution Channel:
Margin capture diverges by channel control depth, with owned digital assets outperforming third-party retail markups.
- Online:E-commerce platforms and brand-owned storefronts enabling direct consumer relationships. China's Tmall and Douyin ecosystems concentrate volume, where PROYA and domestic rivals sustain margin through live-streaming operations.
- Offline:Traditional retail and department store counters requiring trade spend and shelf placement investments.
- Specialty Stores:Curated beauty retailers where editorial positioning and staff training differentiate assortment.
- Direct Sales:Consultant-mediated channels with personalized skin assessment and regimen building.
Transaction velocity peaks in Online channels. Customer lifetime value concentrates in Direct Sales relationships.
Ingredient Type:
Regulatory documentation requirements and consumer narrative preferences split sourcing strategies between established INCI portfolios and experimental botanical positioning.
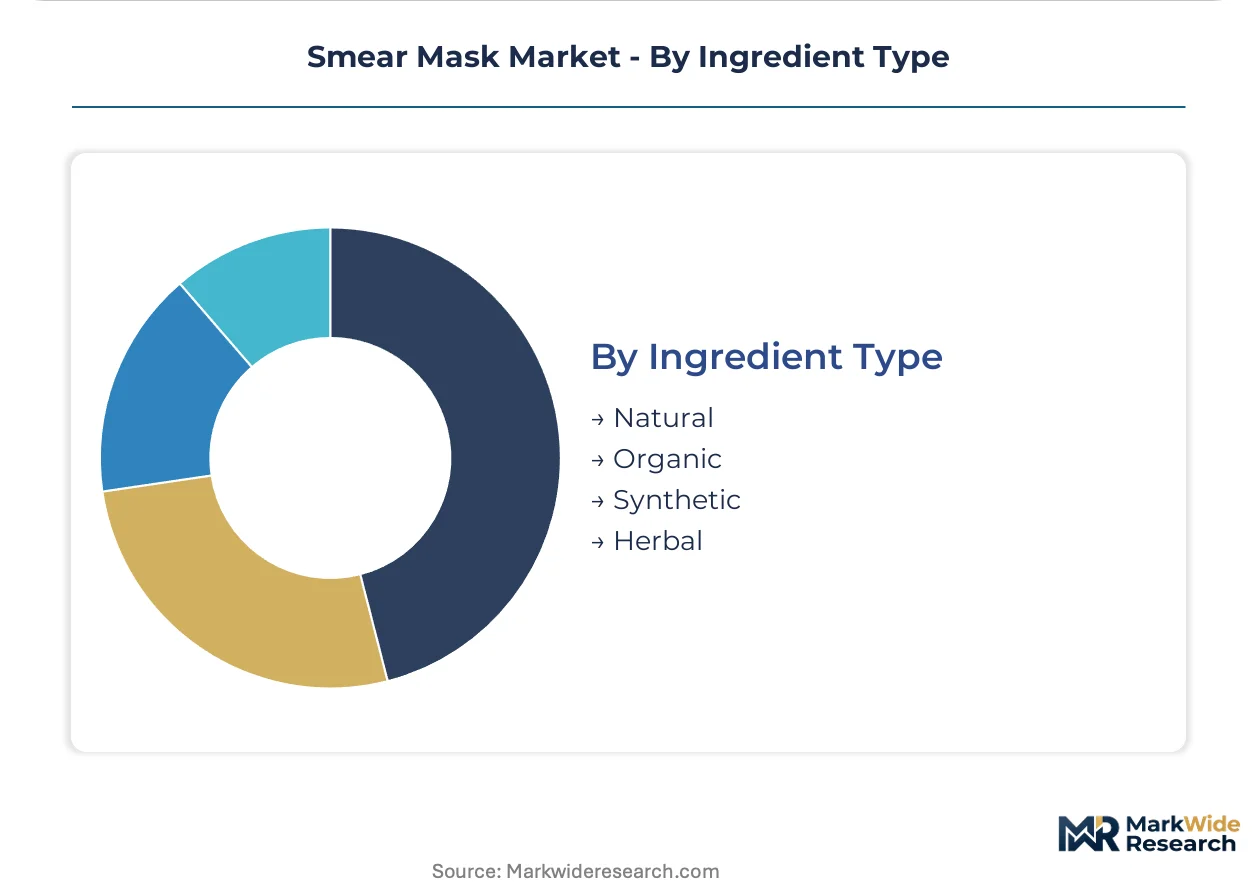
- Natural:Botanically derived actives with minimal processing claims. EU Cosmetics Regulation disclosure mandates elevate consumer trust in documented natural content, creating shelf-space advantages for compliant suppliers at regulated French and German retail outlets.
- Organic:Certified cultivation and extraction standards commanding prestige pricing in clean-beauty positioned channels.
- Synthetic:Laboratory-engineered actives with batch consistency and cost predictability. Mass-market salon channels retain synthetic leadership where formulation stability and margin control outweigh origin storytelling.
- Herbal:Traditional medicine-inspired positioning leveraging Korean and Japanese origin narratives for premium differentiation.
Pricing power concentrates in Natural and Herbal segments. Volume leadership remains with Synthetic formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional facial treatment protocols originated in French and German aesthetic clinics during the post-war period, establishing formulation standards that persist in European regulatory frameworks today. Channel expansion now concentrates in East Asian metropolitan clusters where compressed innovation cycles redefine product lifespans.
South Korea
Seoul clinic networks drive premium smear mask innovation through bundled device-and-consumable procurement contracts. The Ministry of Food and Drug Safety (MFDS) mandates pre-market notification for functional cosmetics, compressing launch timelines for documented formulations. Gangnam district aesthetic chains pilot microbiome-targeted actives, pulling global ingredient trends toward fermented extracts.
China
Live-streaming commerce channels in Shanghai and Hangzhou sustain margin capture for domestic brands through direct-to-consumer fulfillment infrastructure. The National Medical Products Administration (NMPA) extends registration timelines for imported cosmetics, delaying foreign brand penetration. Yangtze River Delta manufacturing clusters concentrate contract production capacity for gel-texture formulations.
Japan
Tokyo and Osaka aesthetic clinics anchor demand for medical-grade barrier-repair variants in post-procedure protocols. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees quasi-drug classifications for claims-intensive formulations. Kansai region biotech suppliers dominate captive production of specialized fermented extracts, constraining sourcing flexibility for brands without long-term agreements.
United States
New York and Los Angeles spa channels prioritize sensory positioning and ritual duration for premium pricing power. The FDA cosmetic labeling requirements constrain formulation freedom through mandatory ingredient disclosure and safety substantiation. California-based clean-beauty brands leverage state-level ingredient transparency mandates to differentiate at specialty retail.
Germany
Munich and Frankfurt aesthetic clinics favor rich, slow-absorbing cream textures that extend treatment perceived value. The EU Cosmetics Regulation's REACH compliance framework elevates toxicology documentation burdens for novel actives, favoring capitalized incumbents with established dossier libraries. Bavaria-based formulators specialize in post-procedure hydration protocols for regulated clinical outlets.
Smear Mask Market Competitive Landscape
The competitive structure tilts toward diversified multinational beauty conglomerates with captive R&D infrastructure and regional specialists with channel-specific certification depth. Tier-one players leverage prestige laboratories to navigate complex regulatory dossiers ahead of resource-constrained entrants. Mid-tier competitors concentrate on texture innovation and direct-to-consumer velocity. Dominant competitive moves include backward integration into active ingredient sourcing and geographic expansion through localized e-commerce operations.
Among Asia-Pacific specialists, AmorePacific and Shiseido exemplify the vertical-control archetype through in-house production of bioactive extracts, while PROYA anchors the digital-native tier with live-streaming commerce penetration in Chinese domestic channels. Estée Lauder occupies a position representing the prestige R&D infrastructure archetype, leveraging established toxicology documentation libraries to accelerate European market access. These three patterns—upstream control, digital velocity, and regulatory pre-qualification—structure competitive differentiation across professional and consumer channels.
| Leading Market Players |
|---|
| Unilever |
| Estée Lauder |
| Shiseido |
| AmorePacific |
| Mary Kay |
| Magic Holdings International Limited |
| PROYA |
| geoskincare |
| L'Oréal |
| Others |
Pricing and Supply Chain Analysis
Fermented extract commodity benchmarks cascade through South Korean and Japanese biotech supply tiers into three distinct pricing levels, compressing margins for brands lacking captive ingredient sourcing while rewarding vertically integrated incumbents with cost pass-through advantages.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the smear mask category, with premium tiers anchored by MFDS-registered functional claims and herbal origin narratives while economy tiers compete on per-unit manufacturing efficiency. Price differentiation hinges on certification grade and volume scale, with clinic-grade barrier-repair variants commanding substantial premiums over mass-market salon alternatives. Cost compression in the standard tier is intensifying because contract manufacturers face rising REACH compliance documentation burdens. Home-care channels exhibit highest price sensitivity, while aesthetic clinics demonstrate lowest sensitivity due to bundled protocol pricing.
Supply Chain Analysis
Regional distribution centers in Shanghai, Seoul, and Tokyo operate hub-and-spoke patterns feeding aesthetic clinic networks across East Asian metropolitan clusters. Manufacturing concentrates in South Korea, China, and Japan, with Yangtze River Delta clusters specializing in gel-texture contract production. Supply chains draw from specialized fermented extracts, stimuli-responsive polymer encapsulation systems, and pre-approved preservative portfolios. Single-source vulnerability from Japanese biotech suppliers constrains formulation flexibility for brands lacking long-term offtake agreements. Distribution runs through clinic procurement frameworks and live-streaming commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in the smear mask category rests on gel-texture premiumization and live-streaming channel control, offsetting compliance cost inflation through direct-to-consumer velocity capture.
For Market Incumbents: Acquire captive fermentation capacity to secure supply of microbiome-targeted actives against emerging biotech entrant competition. Invest in MFDS pre-registration dossiers ahead of functional cosmetics notification deadlines. Consolidate clinic procurement relationships through annual framework contracts bundling device and consumable spend.
For New Entrants and Emerging Players: Launch via Douyin and Tmall live-streaming ecosystems to bypass NMPA registration delays and capture margin outside traditional retail markups. Target gel-texture formulations for aesthetic clinic substitution opportunities where lightweight protocols displace cream alternatives. Prioritize texture innovation partnerships with Yangtze River Delta contract manufacturers.
For Investors and Strategic Acquirers: Asymmetric upside sits with digital-native brands possessing in-house influencer networks and localized content studios. Long-term viability favors enterprises with dual capability in regulatory pre-qualification and direct-to-consumer fulfillment infrastructure. Watch for MFDS notification pathway expansions as signal of functional cosmetics category acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermented Extract Production | Captive supply from Kansai biotech suppliers reduces formulation cost volatility for clinic-grade variants. |
| Live-Streaming Commerce Platform Launch | Douyin ecosystem penetration enables margin capture outside Tmall retail markups for domestic Chinese brands. |
| MFDS Functional Cosmetics Pre-Registration | Early notification pathway completion accelerates Seoul clinic network access ahead of rival launches. |
| Gel Texture Manufacturing Capacity Expansion | Lightweight formulation output addresses aesthetic clinic demand for compressed appointment protocols. |
| Annual Framework Contract Consolidation | Bundled device-and-consumable procurement agreements lock in multi-year clinic revenue streams. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cosmetic chemists, aesthetic clinic procurement officers, live-streaming commerce operators, and contract manufacturing executives with secondary validation through MFDS functional cosmetics notifications, NMPA registration filings, EU Cosmetics Regulation disclosure databases, and trade flow records. Bottom-up demand modeling from clinic network expansion and home-care channel penetration triangulated against top-down market sizing from manufacturer capacity disclosures.
Comparable historical reference periods anchored the projection horizon, with analytical frameworks modeling segmentation across product type, end-user channel, distribution format, and ingredient sourcing strategy. CAGRs derived from clinician protocol adoption curves and e-commerce transaction velocity indices. Forecast inputs incorporated REACH compliance cost trajectories and live-streaming penetration rates across Chinese metropolitan clusters.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA registration timeline extensions or fermented extract supply disruptions. Outputs reflect documented assumptions including clinic network expansion rates and regulatory pathway stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Sterilization Container Systems Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Suture Wire Market
Medical Supplies
Premixed IV Minibags Market
Medical Supplies
GCC Intravenous Solutions Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Specimen Containers Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
North America Hospital Supplies Market
Medical Supplies
North America Nasal Spray Market
Medical Supplies
Medical and Industrial Gloves Market
Medical Supplies
Hemodialysis Consumables Market