
 Malaysia Medical Tourism Market | 2026-2036
Malaysia Medical Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Medical Tourism Market Outlook
Malaysian Society for Quality in Health (MSQH) accreditation is collapsing the window for uncredentialed facilities seeking foreign patient revenue. Sunway Healthcare leverages its integrated campus model to sustain high patient throughput across specialties. KPJ Healthcare Berhad anchors its competitive position through a nationwide network of specialist hospitals. Gleneagles Hospital Malaysia differentiates via premium cardiac and oncology infrastructure targeting Southeast Asian referrals.
Medical tourism encompasses the organized travel of patients across borders to access clinical care, wellness interventions, or diagnostic services, typically involving pre-arranged appointments, medical visa facilitation, and post-treatment recovery protocols. The practice requires internationally standardized infection control, electronic health record interoperability, and coordinated discharge planning to ensure continuity of care. Cardiology and orthopedics command the largest service type volumes due to Malaysia's cost advantage relative to Singapore and Thailand for complex interventions. Private hospitals capture disproportionate value within the treatment facility dimension, as specialty clinics struggle to match their capital intensity for advanced imaging and surgical robotics.
Malaysia Healthcare Travel Council (MHTC) coordinates national promotion while the Ministry of Health enforces facility licensing and foreign patient quota regulations. The Medical Device Authority implements ASEAN Medical Device Directive alignment, shaping which equipment tiers hospitals may deploy for international cases. Stakeholders must monitor how Bank Negara Malaysia's evolving cross-border payment frameworks affect out-of-pocket and insurance-covered transaction flows.
Market Dynamics
Malaysia's Ministry of Health licensing requirements for foreign patient wards are compressing operational windows for uncredentialed facilities while concentrating patient flows into MSQH-accredited institutions.
Growth Catalysts
- Indonesian cardiac demand:Cost differentials against Singaporean alternatives are pulling Southeast Asian patients toward Penang's intervention centers.
- Bangladesh orthopedic referrals:Regional trauma specialists are establishing direct discharge protocols with Kuala Lumpur hospitals.
- ASEAN Medical Device Directive alignment:Malaysia's Medical Device Authority is accelerating equipment tier approvals for international cases.
Market Restraints
- Ringgit volatility:Out-of-pocket payments from Bangladesh face exchange rate compression against USD-pegged surgical costs.
- Penang facility concentration:Cardiac throughput bottlenecks at island hospitals limit spillover capacity from Kuala Lumpur.
- Indonesian domestic capacity buildout:Jakarta's emerging cardiac centers threaten historical referral flows to Malaysian providers.
Strategic Opportunities
- East Malaysian expansion:Kota Kinabalu and Kuching present underdeveloped hubs for Australian and Pacific Islander wellness segments.
- Telemedicine pre-consultation:Remote diagnostic triage is reducing no-show rates for Bangladeshi orthopedic scheduling.
- Bank Negara Malaysia cross-border frameworks:Evolving payment rails enable insurance-covered transaction flows from Indonesian group schemes.
Industry Challenges
- MSQH certification timelines:Foreign patient ward licensing delays are freezing capital deployment at mid-tier hospitals.
- Electronic health record interoperability:Fragmented systems between Indonesian referring clinics and Malaysian discharge planning create continuity gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Medical Tourism Market |
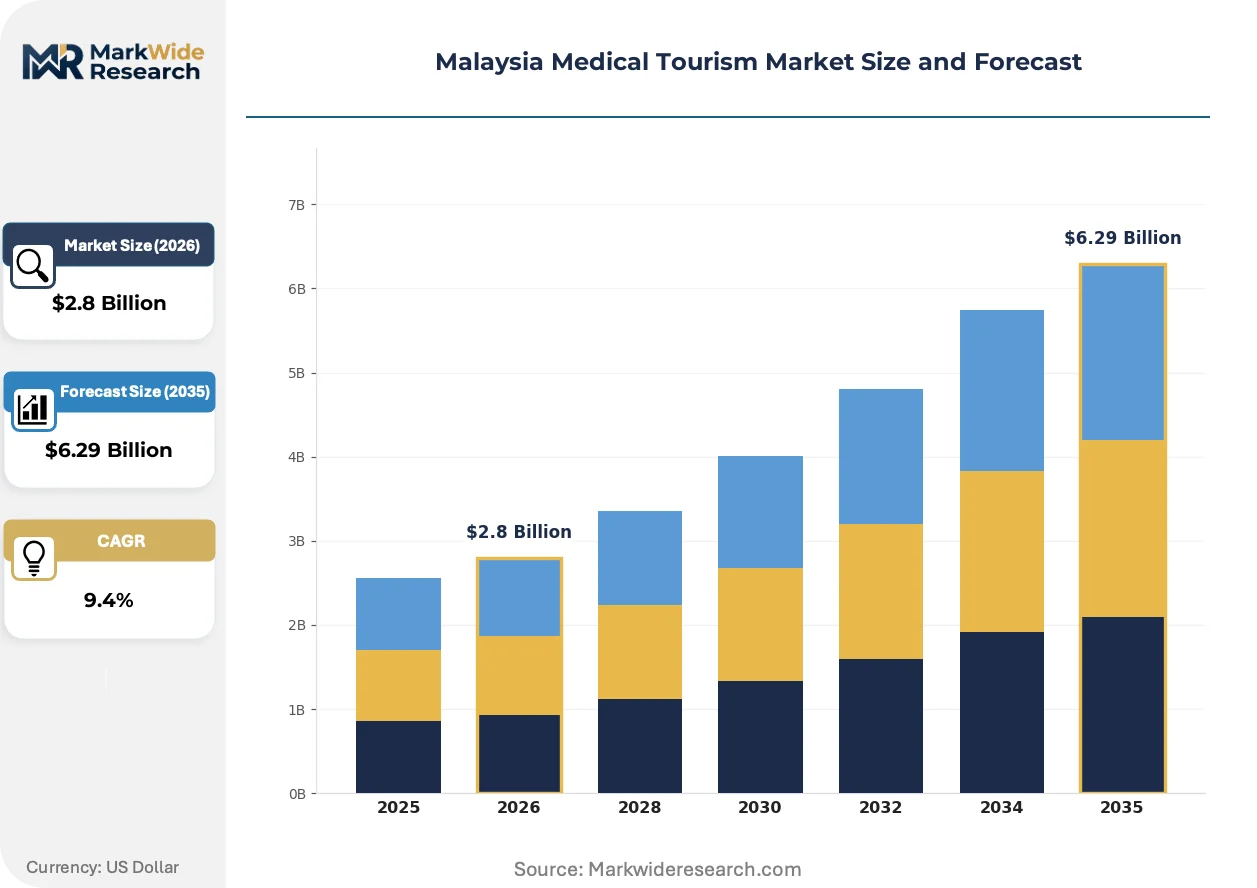
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cardiology, Orthopedics, Cosmetic Surgery, Fertility Treatments Treatment Facility: Private Hospitals, Specialty Clinics, Wellness Centers, Rehabilitation Centers Patient Profile: International Patients, Local Patients, Expatriates, Medical Tourists Payment Model: Insurance Coverage, Out-of-Pocket, Financing Options, Package Deals |
| Companies Covered | Subang Jaya Medical Centre, Sunway Healthcare, Island Hospital Penang, Gleneagles Hospital Malaysia, Malaysia Healthcare Travel Council (MHTC), Institut Jantung Negara (IJN), KPJ Healthcare Berhad, Prince Court Medical Centre, Mahkota Medical Centre, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Medical Tourism Market Strategic Shifts
Digital infrastructure and regulatory harmonization are compressing patient journey friction while reshaping how Malaysian facilities capture and retain cross-border volume.
Robotic surgical platforms are miniaturizing intervention footprints across cardiac and orthopedic service lines. Penang's high-throughput centers are deploying compact systems to sustain dual-specialty scheduling density. This equipment trajectory is miniaturizing capital requirements for mid-tier hospitals seeking foreign patient accreditation.
Malaysia Healthcare Travel Council coordination with Ministry of Health foreign patient quotas is tightening facility eligibility standards. The policy architecture is filtering uncredentialed operators from national promotion channels. Private hospital groups with established MSQH accreditation are consolidating preferred provider status under MHTC campaigns.
Pre-arranged appointment bundling is displacing walk-in international patient models across Kuala Lumpur clusters. Indonesian medical travel agents are negotiating fixed-package cardiac protocols directly with hospital revenue departments. This channel consolidation is most visible in Selangor's integrated campus facilities targeting group scheme referrals.
Malaysia Medical Tourism Market Segmentation
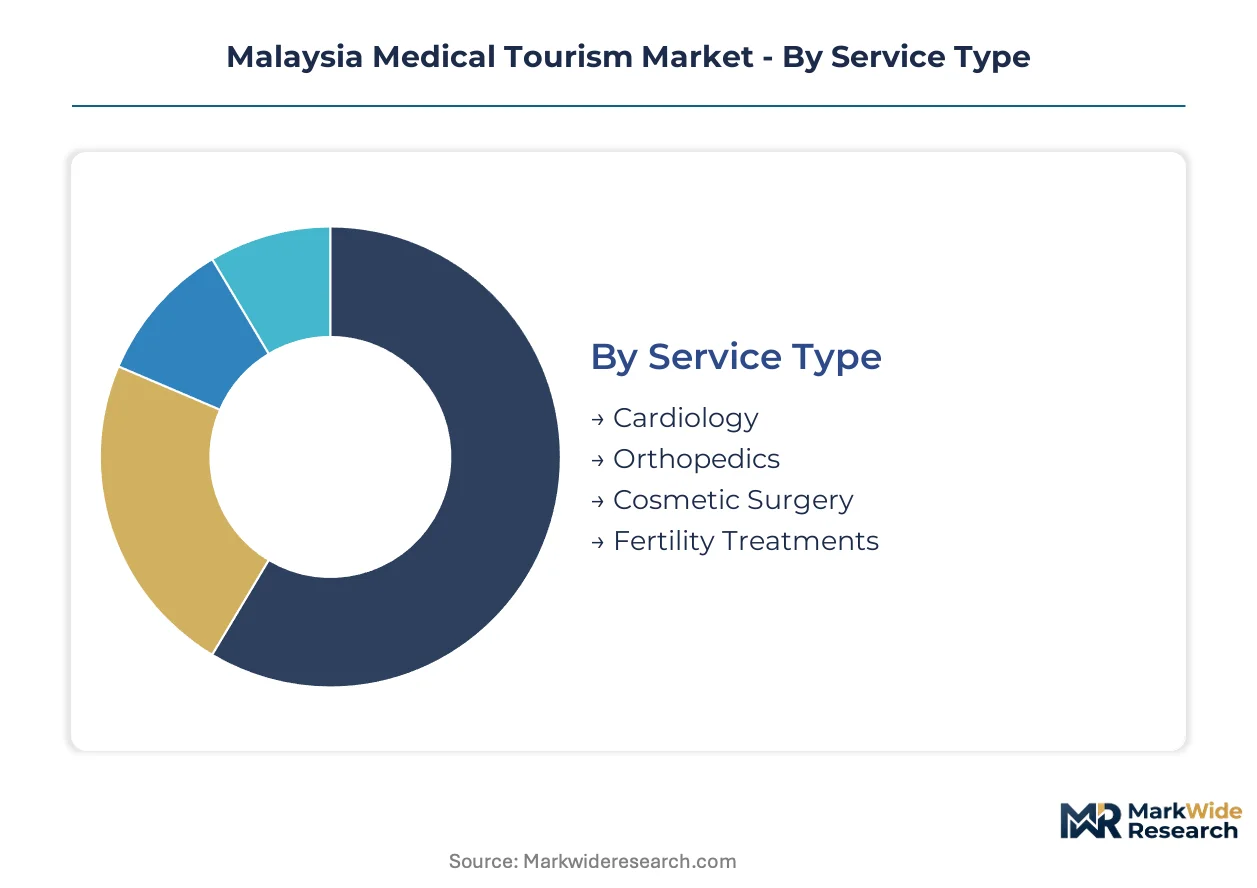
Malaysia's medical tourism segmentation reveals how regulatory licensing, facility accreditation, and patient origin interact to determine revenue capture. Each dimension shapes capital deployment decisions for providers targeting cross-border volume.
Service Type:
Malaysia's Ministry of Health licensing tiers for foreign patient wards create divergent compliance burdens across clinical specialties, directly affecting which service lines hospitals prioritize for international marketing.
- Cardiology:Complex coronary interventions and electrophysiology procedures leverage Malaysia's cost advantage against Singaporean alternatives. Indonesian patients from Sumatra and Java drive demand concentration at Penang's intervention centers, where MSQH-accredited catheterization labs maintain direct referral protocols with Jakarta cardiologists.
- Orthopedics:Joint replacement and spinal surgery command premium scheduling density at Kuala Lumpur's high-throughput campuses. Bangladeshi trauma specialists coordinate discharge planning with Malaysian orthopedic units, establishing predictable referral flows for complex revision cases.
- Cosmetic Surgery:Aesthetic procedures attract regional patients seeking privacy and competitive pricing at Selangor specialty clinics.
- Fertility Treatments:Assisted reproductive technology services concentrate at Kuala Lumpur's integrated fertility centers with dedicated international patient coordinators.
Cardiology handles the majority of throughput; fertility treatments are gaining share fastest among inbound medical travelers.
Treatment Facility:
Capital intensity requirements separate facilities capable of hosting foreign patient wards from those restricted to domestic-only operations under Ministry of Health regulations.
- Private Hospitals:Multi-specialty campuses deploy robotic surgical platforms and advanced imaging suites to sustain dual-specialty scheduling density. MSQH accreditation status determines eligibility for Malaysia Healthcare Travel Council promotion channels, filtering uncredentialed operators from national campaigns.
- Specialty Clinics:Single-discipline centers concentrate on fertility, ophthalmology, or dental services with lower capital barriers to foreign patient ward licensing. These facilities struggle to match private hospital throughput for complex interventions requiring overnight recovery.
- Wellness Centers:Preventive and holistic health services target Australian and Pacific Islander segments at East Malaysian hubs.
- Rehabilitation Centers:Post-surgical recovery facilities coordinate with orthopedic and cardiac discharge planning for extended-stay international patients.
Private hospitals dominate revenue concentration; specialty clinics show the steepest expansion trajectory as regulatory miniaturization reduces accreditation timelines.
Patient Profile:
Origin-based risk assessment and payment reliability shape how Malaysian facilities allocate foreign patient quota capacity across customer types.
- International Patients:Cross-border travelers from Indonesia, Bangladesh, and Vietnam generate the highest per-case revenue at MSQH-accredited institutions. Pre-arranged appointment bundling through medical travel agents is displacing walk-in models across Kuala Lumpur clusters.
- Local Patients:Domestic demand competes for capacity at premium facilities, creating scheduling tension during peak inbound seasons.
- Expatriates:Long-term foreign residents leverage employer-sponsored coverage at private hospital networks with direct billing agreements.
- Medical Tourists:Dedicated wellness and elective procedure travelers combine clinical services with recovery tourism at Penang and Langkawi facilities.
International patients absorb the bulk of foreign patient ward capacity; medical tourists are expanding most quickly as package deal penetration deepens.
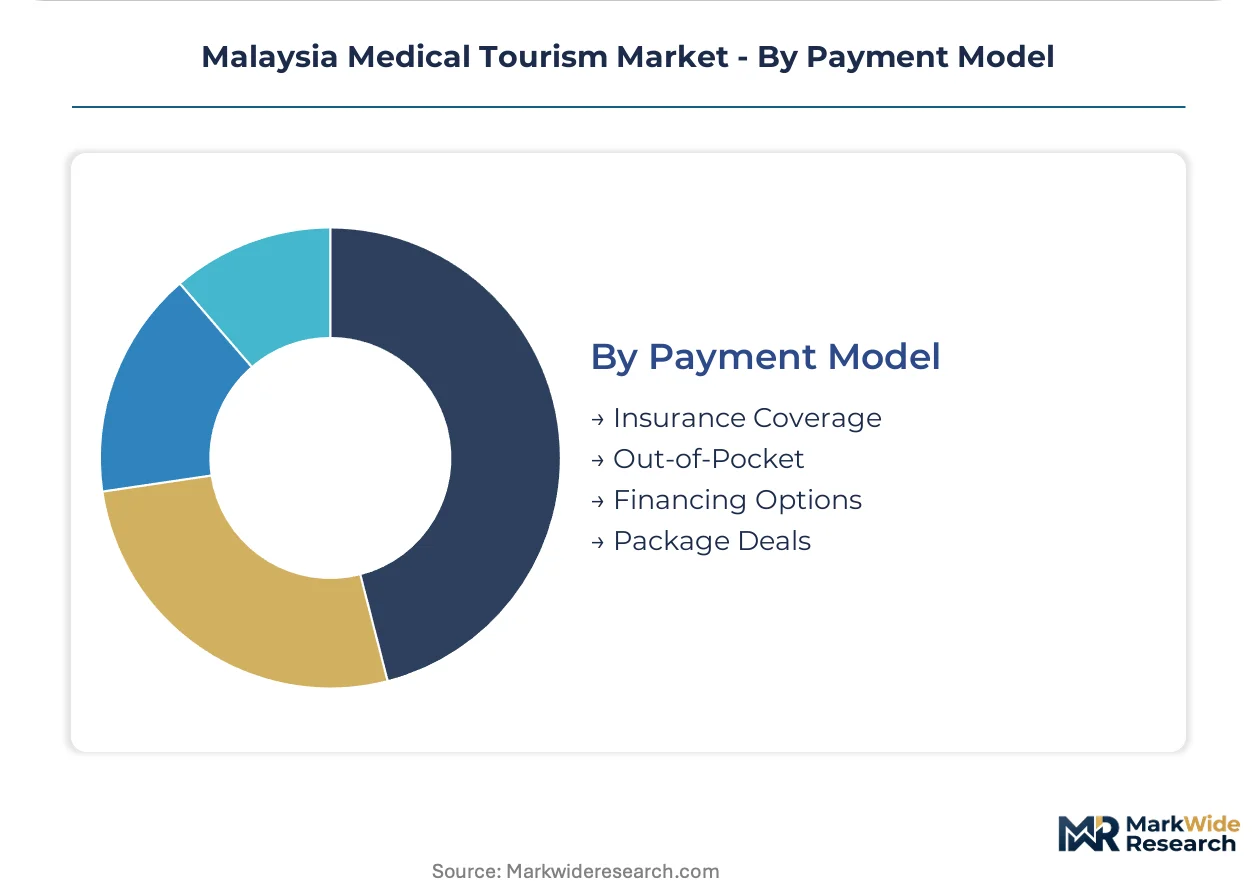
Payment Model:
Bank Negara Malaysia's evolving cross-border payment frameworks are restructuring how transaction flows settle between Indonesian group schemes and Malaysian providers.
- Insurance Coverage:Indonesian corporate health plans and international expatriate policies drive predictable revenue at hospitals with direct billing infrastructure. MHTC coordination with insurers is standardizing pre-authorization protocols for cardiac and orthopedic procedures.
- Out-of-Pocket:Self-pay patients from Bangladesh face exchange rate compression against USD-pegged surgical costs, creating pricing sensitivity at mid-tier facilities.
- Financing Options:Medical installment plans through Malaysian banking partners extend access to elective procedures for regional middle-income segments.
- Package Deals:Fixed-price bundles combining surgery, accommodation, and recovery transport are consolidating channel power with medical travel agents negotiating directly with hospital revenue departments.
Insurance coverage anchors transaction volume; package deals are climbing the fastest as agent channel consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Senai Airport expansion and Penang International Airport cardiac patient corridors anchor Malaysia's medical tourism infrastructure, connecting Indonesian and Bangladeshi demand clusters to treatment hubs.
Penang
Indonesian cardiac referrals from Medan and Aceh drive intervention volume at island hospitals. The Ministry of Health foreign patient ward licensing compresses operational windows for uncredentialed facilities. Georgetown and Bayan Lepas concentration of MSQH-accredited catheterization labs sustains direct discharge protocols with Jakarta cardiologists.
Kuala Lumpur
Bangladeshi orthopedic trauma specialists coordinate revision case flows with Selangor hospitals. Bank Negara Malaysia cross-border payment frameworks enable insurance-covered transactions from Indonesian group schemes. Integrated campus facilities in Petaling Jaya and Subang Jaya deploy robotic surgical platforms for dual-specialty scheduling density.
Johor Bahru
Singaporean day-trip patients seeking cost-differentiated diagnostics and elective procedures generate cross-border volume. Iskandar Malaysia development corridors attract Australian wellness tourism segments. Mid-tier hospitals in the southern corridor face MSQH certification timeline delays freezing capital deployment.
Sabah
Australian and Pacific Islander wellness segments present underdeveloped demand at Kota Kinabalu facilities. East Malaysian expansion strategies target recovery tourism combining clinical services with nature-based recuperation. MHTC coordination channels limited promotional resources toward established Penang and Kuala Lumpur clusters.
Sarawak
Kuching hospitals capture regional Indonesian Borneo referrals for secondary interventions. Telemedicine pre-consultation infrastructure reduces no-show rates for remote patient scheduling. KPJ Healthcare Berhad network presence anchors competitive positioning against Penang-based cardiac diversion.
Malaysia Medical Tourism Market Competitive Environment
Listed leaders compete with private specialists across accreditation status and foreign patient ward licensing tiers. The market concentrates around MSQH-accredited hospital groups with established MHTC promotion channel access. Three archetypes dominate: integrated campus operators with robotic surgical platforms, nationwide network specialists leveraging geographic coverage, and single-site premium facilities targeting high-complexity interventions. Competitive moves center on MSQH certification acquisition and telemedicine pre-consultation infrastructure deployment.
Within the integrated campus tier, Sunway Healthcare exemplifies high-throughput operations across multiple specialties. KPJ Healthcare Berhad represents the nationwide network archetype with specialist hospital coverage spanning major demand clusters. Gleneagles Hospital Malaysia occupies a position in the premium-tier segment targeting Southeast Asian cardiac and oncology referrals.
| Leading Market Players |
|---|
| Subang Jaya Medical Centre |
| Sunway Healthcare |
| Island Hospital Penang |
| Gleneagles Hospital Malaysia |
| Malaysia Healthcare Travel Council (MHTC) |
| Institut Jantung Negara (IJN) |
| KPJ Healthcare Berhad |
| Prince Court Medical Centre |
| Mahkota Medical Centre |
| Others |
Value Chain & Pricing Dynamics
High-throughput cardiac intervention centers in Penang achieve scale economies through dual-specialty scheduling density that compresses per-procedure fixed costs and establishes price floors below Singaporean alternatives. This capacity-utilization advantage concentrates patient flows into MSQH-accredited institutions while marginalizing uncredentialed competitors unable to match capital intensity for robotic surgical platforms.
Pricing Analysis
Volume-discount tiering structures separate MSQH-accredited private hospitals from mid-tier facilities competing on out-of-pocket affordability for Bangladeshi orthopedic patients. Price differentiation centers on accreditation grade and geographic delivery cost, with Penang cardiac centers commanding premiums against Jakarta alternatives while Kuala Lumpur orthopedic units face compression from ringgit volatility against USD-pegged surgical expenses. Pricing pressure stems from Indonesian domestic capacity buildout threatening historical referral flows. Self-pay patients from Bangladesh exhibit highest price sensitivity; insured Indonesian corporate scheme enrollees show lowest.
Supply Chain Analysis
Inventory and lead-time constraints for robotic surgical platforms and advanced imaging equipment tether Malaysian providers to German, Japanese, and US medical device manufacturers. Raw material dependencies span surgical robotics components, diagnostic imaging sensors, and sterile consumables. Supply chain risk concentrates in single-source vulnerability for next-generation catheterization lab equipment. Distribution runs through Malaysia Healthcare Travel Council-coordinated promotion channels filtering uncredentialed operators from national campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's medical tourism market presents a defensive-moat story anchored in regulatory entrenchment: Ministry of Health foreign patient ward licensing creates switching costs that freeze capital deployment at non-accredited facilities while concentrating patient flows into established MSQH-certified networks.
For Market Incumbents: Compound accreditation advantages by extending MSQH certification timelines into telemedicine pre-consultation infrastructure that locks in Indonesian referring cardiologist relationships. Deepen channel control through direct discharge protocol agreements with Bangladeshi trauma specialists, defending against Jakarta's emerging cardiac centers threatening Sumatra referral diversion. Prioritize robotic platform capacity addition in Selangor integrated campuses to sustain dual-specialty scheduling density against Penang throughput bottlenecks.
For New Entrants and Emerging Players: Telemedicine pre-consultation gaps in East Malaysian hubs present white-space opportunities where MHTC promotional resources remain concentrated on Penang and Kuala Lumpur clusters. Target Kota Kinabalu wellness segments for Australian and Pacific Islander recovery tourism combining clinical services with nature-based recuperation. Deploy medical travel agent partnership models bypassing direct hospital revenue department negotiations that dominate Selangor package deal consolidation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated campus operators with established direct billing agreements for Indonesian corporate health plans. Long-term viability across the analysis window favors nationwide network specialists leveraging geographic coverage against single-site premium facilities vulnerable to cardiac referral diversion. Monitor Bank Negara Malaysia cross-border payment framework evolution as inflection indicator for insurance-covered transaction flow expansion from Indonesian group schemes.
| Strategic Initiative | Industry Significance |
|---|---|
| MSQH Accreditation Investment | Ministry of Health licensing tiers filter uncredentialed competitors from MHTC promotion channels. |
| Telemedicine Pre-Consultation Deployment | Remote diagnostic triage reduces Bangladeshi orthopedic no-show rates and locks referral relationships. |
| Robotic Surgical Platform Acquisition | Compact cardiac-orthopedic systems sustain dual-specialty scheduling density at high-throughput campuses. |
| Direct Discharge Protocol Agreements | Jakarta cardiologist and Bangladeshi trauma specialist coordination secures predictable cross-border referral flows. |
| East Malaysian Hub Development | Kota Kinabalu and Kuching facilities capture underdeveloped Australian wellness and Indonesian Borneo segments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of Ministry of Health licensing records, Malaysia Healthcare Travel Council promotional databases, and hospital procurement disclosures. Interviews with hospital international patient coordinators, biomedical engineers, medical travel agents, and GPO contracts managers combined with analysis of MSQH accreditation timelines, Medical Device Authority equipment approvals, and Bank Negara Malaysia cross-border payment frameworks. Bottom-up procedure volume estimates triangulate against top-down market sizing from inbound patient arrival data.
Segmentation dimensions modeled span service type, treatment facility tier, patient origin, and payment model across the projection horizon. Analytical framework incorporates cardiology and orthopedic procedure volumes, foreign patient ward capacity constraints, and regulatory compliance timelines. CAGRs derive from patient flow projections, capacity expansion schedules, and referral relationship stability assumptions. Forecast inputs include Indonesian domestic cardiac center development trajectories and Bangladeshi exchange rate sensitivity patterns.
Forecasts assume regulatory continuity in Ministry of Health foreign patient ward licensing and Medical Device Authority ASEAN Medical Device Directive alignment; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Tourism
France Medical Tourism Market
Medical Tourism
Switzerland Healthcare and Medical Tourism Market
Medical Tourism
Medical Tourism Market
Medical Tourism
Asia-Pacific Medical Tourism Market
Medical Tourism
Spain Medical Tourism Market
Medical Tourism
North America Outbound Medical Tourism Services Market
Medical Tourism
Europe Medical Tourism Market
Medical Tourism
Outbound Medical Tourism Services Market
Medical Tourism
Thailand Medical Tourism Market
Medical Tourism
India Medical Tourism Market
Medical Tourism
Europe Dental Tourism Market
Medical Tourism
UK Medical Tourism Market
Medical Tourism
GCC Countries Medical Tourism Market
Medical Tourism
Fertility Tourism Market
Medical Tourism
South Korea Medical Tourism Market
Medical Tourism
Dental Tourism Market