
 Surgical Glue Market | 2026-2036
Surgical Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Glue Market Intelligence
Manufacturing expansion in China is tilting the supply chain for raw materials and finished products. Johnson & Johnson leverages its extensive hospital distribution network to maintain a dominant position. Medtronic differentiates through specialized applicators designed for minimally invasive surgeries, while B. Braun sustains a strong presence across European hospital systems.
Surgical glues are biocompatible materials used to bond tissues and seal leaks without sutures. These adhesives, often based on fibrin or cyanoacrylate, are engineered for rapid in-vivo polymerization. Fibrin-based products command higher prices and are preferred for internal hemostasis in cardiovascular procedures. In contrast, cyanoacrylate adhesives represent a high-volume segment, primarily used for external wound closure in hospitals and specialty clinics.
Regulatory pathways, such as the FDA's Premarket Approval process in the United States and the EU's MDR, impose stringent requirements for clinical data. These frameworks, enforced by bodies including China's NMPA, dictate product safety standards and market access. Consequently, navigating the evolving biocompatibility standards for synthetic polymers versus natural biologics remains a critical strategic decision for all manufacturers.
Market Dynamics
The surgical glue market is shaped by a fundamental tension between the clinical demand for accelerated wound healing in an aging global population and the increasingly stringent regulatory frameworks governing biocompatible materials, such as the EU's Medical Device Regulation.
Growth Catalysts
- Minimally Invasive Surgery:The expansion of laparoscopic and robotic procedures creates specific demand for adhesives and specialized applicators that can operate in confined spaces, reducing surgical trauma and recovery times.
- Demographic Shifts:Aging populations in developed nations like Germany and Japan are driving a higher volume of cardiovascular and orthopedic surgeries, where fibrin sealants are critical for achieving rapid hemostasis.
- Biomaterial Innovation:Advances in synthetic polymers and recombinant biologics are enabling the development of adhesives with enhanced properties like flexibility, controlled degradation rates, and lower immunogenicity.
Market Restraints
- Reimbursement Policies:In many healthcare systems, reimbursement rates for advanced surgical adhesives do not fully cover their higher cost compared to traditional sutures, limiting adoption in cost-sensitive hospital environments.
- Regulatory Scrutiny:The FDA's Premarket Approval (PMA) process and China's NMPA registration require extensive and costly clinical trials, creating high barriers to entry for new synthetic or biological adhesives.
- Technical Limitations:Current adhesives exhibit performance trade-offs; for instance, cyanoacrylates have high strength but can be cytotoxic, while fibrin sealants are highly biocompatible but have lower mechanical strength.
Strategic Opportunities
- Drug-Eluting Adhesives:Integrating therapeutic agents such as antibiotics, anti-inflammatory drugs, or growth factors into the adhesive matrix offers a pathway to improve patient outcomes and create high-value, differentiated products.
- Emerging Economies:Expanding healthcare infrastructure and rising middle-class incomes in countries like Brazil and India present significant opportunities for market entry, particularly for mid-tier cyanoacrylate-based products.
- Veterinary Medicine:The use of surgical glues in companion animal and livestock surgery is an underpenetrated market segment that offers a separate, less stringent regulatory pathway for product commercialization.
Industry Challenges
- Raw Material Sourcing:Manufacturers of fibrin sealants face the challenge of securing a stable, pathogen-free supply of human or animal-derived plasma components like fibrinogen and thrombin, creating supply chain vulnerabilities.
- Surgeon Training and Technique:Improper application of surgical glue can lead to complications such as poor wound healing, infection, or unintended adhesion. This necessitates standardized training programs for surgical staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Glue Market |
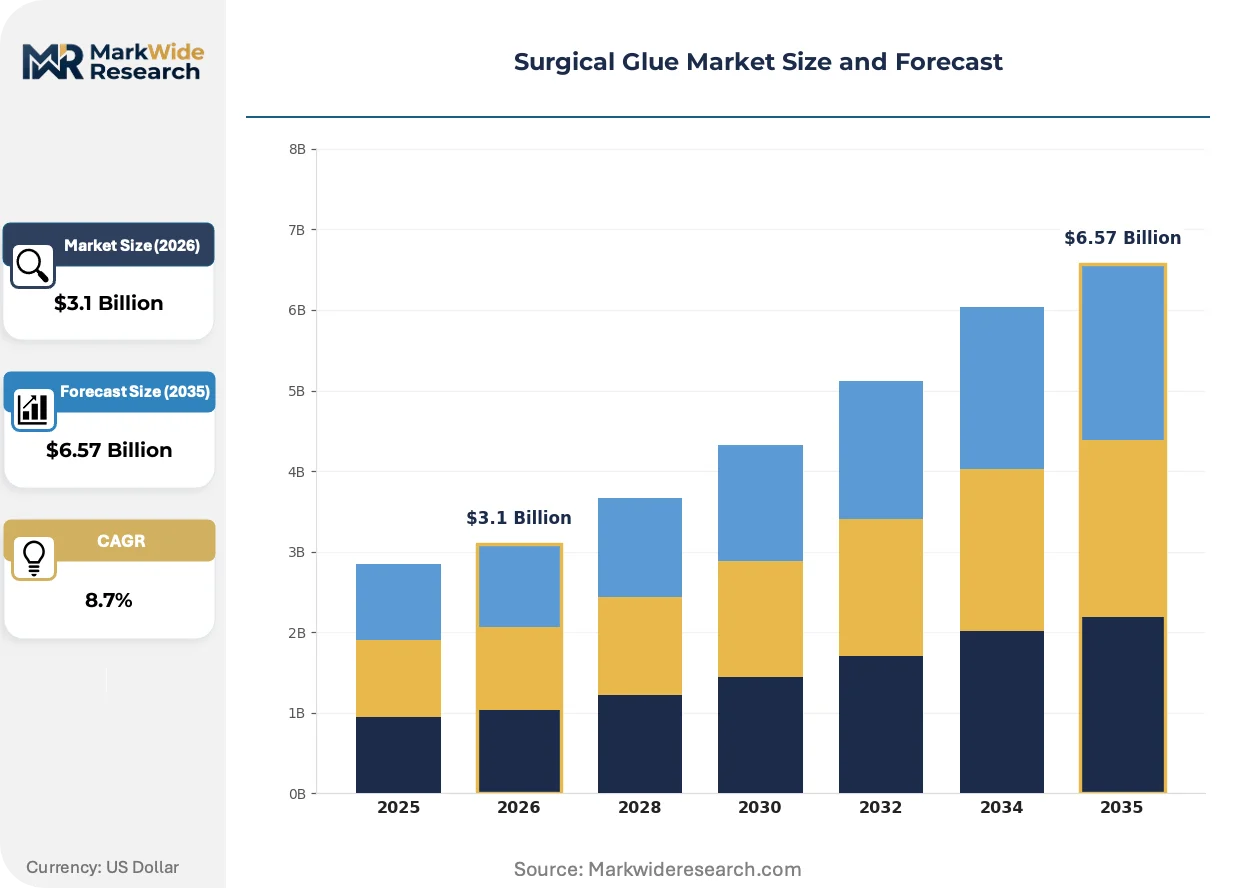
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyanocrylate, Fibrin, Polyurethane, Albumin, Gelatin, Synthetic Polymer Application: Wound Closure, Hemostasis, Tissue Adhesion, Plastic Surgery, Cardiovascular Procedures, Orthopedic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Veterinary Clinics, Research Institutes, Military Medical Units Delivery Mode: Spray, Liquid, Patch, Pre-loaded Applicator, Powder, Film |
| Companies Covered | Johnson & Johnson, Medtronic, B. Braun, Baxter, Artivion, Inc., Integra LifeSciences Corporation, Cardinal Health, Becton Dickinson and Company, Advanced Medical Solutions Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Glue Market Strategic Shifts & Innovations
The market is evolving from passive closure devices to active, functional biomaterials. This transition prioritizes adhesives that not only bond tissue but also participate in the healing process, a shift driven by advances in polymer science and a deeper understanding of tissue biology.
Advanced biomimetic hydrogels are a key area of product development, designed to mimic the properties of the body's natural extracellular matrix. These materials are gaining traction in specialized fields like neurosurgery and ophthalmology for their ability to seal delicate tissues without causing inflammation. This technology is virtualizing the mechanical act of suturing by creating a conformable, in-situ barrier that integrates with the host tissue.
Regulatory frameworks are mandating a life-cycle approach to device safety. The EU's Medical Device Regulation (MDR) imposes stringent post-market surveillance and clinical evidence requirements, raising the compliance burden for all manufacturers. This particularly affects novel synthetic polymers, which now face a level of scrutiny previously reserved for biologics, forcing companies to invest heavily in long-term patient data collection.
A notable shift in hospital purchasing behavior involves the bundling of surgical adhesives with related procedural products. Large hospital networks are moving away from single-item procurement and instead prefer comprehensive kits that include the adhesive, specialized applicators, and even wound dressings from a single supplier. This trend is most visible in integrated health systems in the United States and parts of Western Europe.
Surgical Glue Market Segmentation
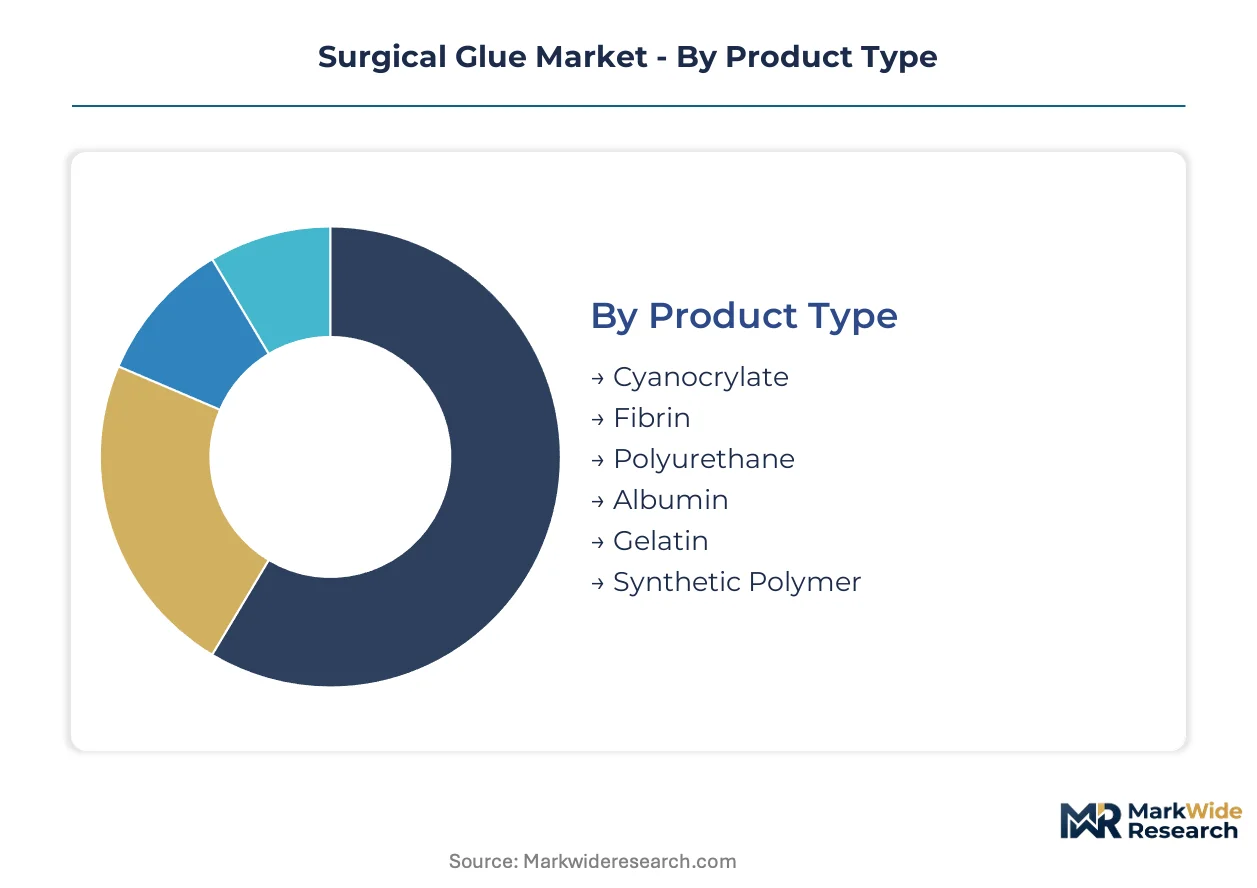
The surgical glue market's segmentation provides a granular view of product innovation, clinical utility, and market access strategies. Understanding these distinct segments is crucial for manufacturers to align product development with specific clinical demands and regulatory pathways. This detailed analysis reveals the nuanced interplay between material science, application technique, and end-user requirements across the healthcare spectrum.
Product Type:
The use-case spectrum for surgical glues dictates material selection, with diverse chemistries addressing specific clinical needs.
- Fibrin:Fibrin-based products consist of human or animal-derived fibrinogen and thrombin, mimicking the body's natural clotting cascade. These biocompatible adhesives are preferred for internal hemostasis in cardiovascular procedures, where rapid blood control is critical.
- Cyanocrylate:Cyanoacrylate adhesives are synthetic monomers that polymerize rapidly on contact with tissue, forming a strong bond for external wound closure. This high-volume segment finds extensive use in hospitals and specialty clinics for superficial cuts and incisions.
- Polyurethane:Polyurethane-based glues offer strong adhesion and flexibility, suitable for various tissue types and internal applications requiring durable bonds.
- Albumin:Albumin-based sealants are biologically derived materials providing tissue adherence and hemostatic properties, often used in conjunction with other agents.
- Gelatin:Gelatin-based adhesives are biodegradable and offer hemostatic capabilities, frequently employed in general surgery for sealing and tissue approximation.
- Synthetic Polymer:This category encompasses a range of engineered polymers designed for specific mechanical properties and degradation profiles in diverse surgical settings.
The dominant share belongs to Fibrin, while Cyanoacrylate is closing the gap fastest.
Application:
Application areas define the surgical glue market's functional requirements, ranging from immediate hemostasis to long-term tissue repair.
- Cardiovascular Procedures:These applications demand highly biocompatible and flexible adhesives capable of withstanding pulsatile pressure and providing rapid hemostasis. Aging populations in Germany and Japan drive the demand for fibrin sealants in complex heart surgeries.
- Wound Closure:Surgical glues in wound closure offer an alternative to sutures, reducing surgical time and improving cosmetic outcomes for patients. Cyanoacrylate adhesives are widely used for external wound sealing in hospitals and outpatient settings.
- Hemostasis:Products for hemostasis focus on rapid blood cessation, critical in emergency and high-bleeding risk surgeries.
- Tissue Adhesion:This segment includes glues designed for bonding delicate tissues, supporting tissue regeneration, and providing structural integrity.
- Plastic Surgery:Adhesives in plastic surgery aim for minimal scarring and precise tissue approximation, enhancing aesthetic outcomes.
- Orthopedic Surgery:Glues in orthopedics support bone and soft tissue repair, particularly in procedures requiring strong, durable bonds.
Cardiovascular Procedures represent the fastest-growing application, driven by an aging population and complex interventions.
End User:
Customer type significantly influences purchasing patterns and product specifications across the surgical glue market.
- Hospitals:Hospitals represent the primary end-users for surgical glues, utilizing a broad spectrum of products across various surgical disciplines from general surgery to orthopedics. Procurement departments often seek comprehensive kits that bundle adhesives with applicators.
- Ambulatory Surgical Centers:These centers focus on minimally invasive procedures, driving demand for specialized adhesives and pre-loaded applicators that streamline operations. Cost-effectiveness and rapid patient turnover are key considerations for ASCs.
- Specialty Clinics:Specialty clinics, such as dermatology or ophthalmology, use surgical glues for specific, often less invasive, procedures.
- Veterinary Clinics:Veterinary medicine presents an underpenetrated market for surgical glues, offering less stringent regulatory pathways for product commercialization.
- Research Institutes:Research institutes utilize surgical glues for experimental models, tissue engineering, and biocompatibility studies.
- Military Medical Units:Military medical units require robust and rapidly deployable surgical glues for field trauma care and emergency interventions.
Hospitals constitute the largest demand segment, though Specialty Clinics demonstrate increasing procedural volume.
Delivery Mode:
Delivery modes for surgical glues are engineered to optimize application precision and efficiency during various surgical interventions.
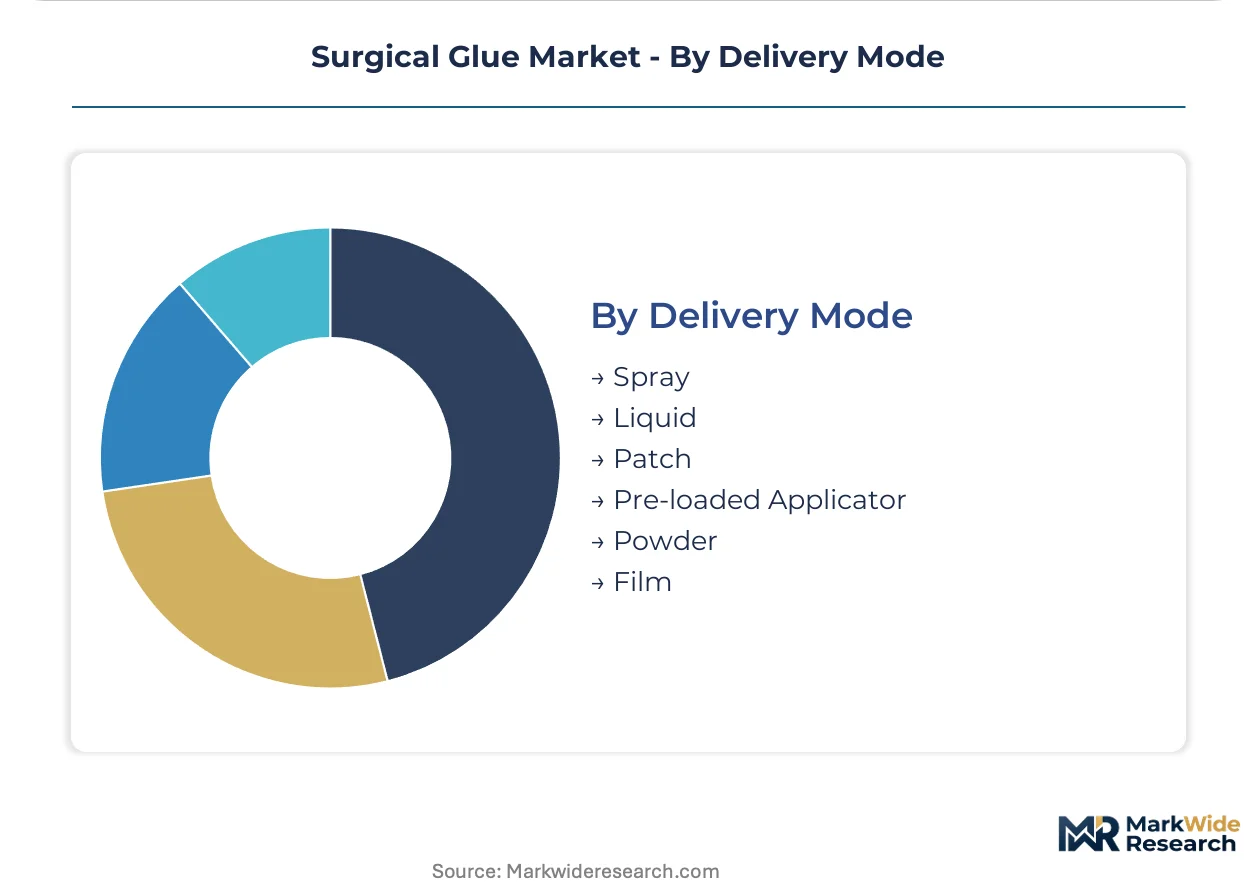
- Pre-loaded Applicator:These devices integrate the adhesive and delivery mechanism, ensuring precise and controlled application, especially in confined surgical spaces. Medtronic differentiates its offerings with specialized applicators designed for minimally invasive surgeries.
- Liquid:Liquid surgical glues offer versatility in application, allowing surgeons to cover irregular surfaces or fill cavities during complex procedures. This traditional format is widely adopted across various surgical specialties due to its adaptability.
- Spray:Spray delivery systems enable broad and even coverage of larger surface areas, often used for hemostasis or sealing diffuse leaks.
- Patch:Patch-based glues provide a localized and sustained release of adhesive, suitable for specific anatomical sites requiring consistent sealing.
- Powder:Powder formulations offer ease of storage and can be mixed on demand, providing flexibility for various clinical scenarios.
- Film:Film delivery systems offer a thin, conformable adhesive layer, particularly useful for delicate tissues or as a barrier.
Pre-loaded Applicators are becoming pivotal for minimally invasive surgeries, streamlining application for surgeons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply chain for surgical glues shows a pronounced concentration in key manufacturing hubs. China's expanding production capabilities are significantly influencing the global availability of raw materials and finished products for this market. This geographic focus impacts pricing and distribution dynamics worldwide.
United States
The United States market exhibits strong demand for advanced surgical glues in high-value cardiovascular and orthopedic interventions. The FDA's Premarket Approval process imposes stringent clinical data requirements for new products. Boston's biotech corridor drives development of novel biomaterials and specialized applicators.
Germany
Germany's aging population fuels consistent demand for fibrin sealants in complex cardiovascular and orthopedic surgeries. The EU's Medical Device Regulation mandates rigorous clinical evidence for all medical devices. Munich's medical technology sector demonstrates significant R&D in advanced biocompatible materials and specialized adhesive applications.
Japan
Japan's rapidly aging demographics contribute to a growing need for surgical glues, especially in minimally invasive procedures and internal hemostasis. The PMDA enforces strict safety and efficacy standards for medical devices, guiding product development. Advanced medical centers in Tokyo are early adopters of novel adhesives and specialized delivery systems.
China
China's expanding manufacturing base is a critical source for raw materials and finished surgical glue products, impacting global supply. The NMPA registration process requires extensive localized clinical data for market approval. The Yangtze River Delta region is a significant hub for medical device production, including various synthetic polymer-based adhesives.
India
Expanding healthcare infrastructure and rising middle-class incomes in India generate substantial demand for cost-effective surgical glues. The CDSCO's regulatory guidelines are evolving, impacting market entry and product commercialization. Bengaluru's medical technology ecosystem fosters innovation in mid-tier cyanoacrylate-based products.
Surgical Glue Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the surgical glue market. This market exhibits a tiered structure, with a few large multinational corporations dominating the premium segment and numerous smaller players specializing in niche products. Strategic archetypes include diversified medical device giants, specialized biomaterial developers, and regional manufacturers focusing on cost-effective solutions. Companies often engage in strategic partnerships and extensive portfolio diversification to maintain their market presence.
Among the diversified medical device giants, Johnson & Johnson, a prominent US-based corporation, leverages its extensive hospital distribution network to maintain a dominant market position. Medtronic, another US-based firm, exemplifies the strategy of differentiation through specialized applicators designed for minimally invasive surgeries. B. Braun, a German-based healthcare company, sustains a strong presence across European hospital systems, representing a regional powerhouse with a broad product portfolio. These firms collectively anchor the premium and high-volume segments of the surgical glue market, influencing product development and market access strategies globally.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| B. Braun |
| Baxter |
| Artivion, Inc. |
| Integra LifeSciences Corporation |
| Cardinal Health |
| Becton Dickinson and Company |
| Advanced Medical Solutions Group |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta region's expanding manufacturing capacity significantly influences the global availability of synthetic polymer-based adhesives. This concentration directly impacts the pricing dynamics for high-volume surgical glues worldwide.
Pricing Analysis
The EU's Medical Device Regulation dictates the pricing tier structure for surgical glues, emphasizing product safety and efficacy. Pricing stratifies across premium, standard, and economy tiers, driven by factors such as the level of clinical evidence and specialized applicator integration. Pricing pressure stems from reimbursement policies, which often do not fully cover the higher cost of advanced adhesives in many healthcare systems. Hospitals exhibit the most price sensitivity, while specialty clinics prioritize specific performance for less invasive procedures.
Supply Chain Analysis
Securing pathogen-free human or animal-derived plasma components like fibrinogen and thrombin represents a critical upstream challenge for fibrin sealant manufacturers. Raw material sourcing centers on countries like China, Germany, and the United States. A structural risk involves the potential for pathogen contamination or supply disruptions for these biologics, impacting global availability. Downstream distribution extends through extensive hospital networks and direct-to-specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical glue market presents a service-attach opportunity, where specialized applicator maintenance and training programs are expanding faster than the core adhesive product sales. This offers a recurring revenue stream alongside product commercialization.
For Market Incumbents:Entrench existing market share by strengthening hospital distribution networks and diversifying product portfolios to include advanced biomimetic hydrogels. Stringent regulatory scrutiny, particularly from the EU's MDR, poses a continuous threat, necessitating ongoing investment in clinical evidence generation. Deepen R&D into drug-eluting adhesives to create high-value, differentiated offerings that improve patient outcomes. Medtronic's focus on specialized applicators for minimally invasive surgery demonstrates this differentiation.
For New Entrants and Emerging Players:Establish a beachhead in emerging economies like India and Brazil, targeting the mid-tier cyanoacrylate-based product segment. Veterinary medicine also presents an underpenetrated market with less stringent regulatory pathways, offering faster commercialization. Focus on cost-effectiveness and ease of use for high-volume external wound closure applications. Localized manufacturing in regions like Bengaluru can support market entry.
For Investors and Strategic Acquirers:Long-term, this sits as an essential medical technology play because of its fundamental role in surgical outcomes and an aging global population. Identify specialized biomaterial developers with strong intellectual property in advanced synthetic polymers or recombinant biologics as key acquisition targets. The signal to watch is the accelerating adoption rate of drug-eluting adhesives in complex cardiovascular procedures, indicating a shift towards functional biomaterials.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Biomaterial R&D | Developing biomimetic hydrogels addresses demand for delicate tissue sealing in neurosurgery and ophthalmology. |
| Strengthen Hospital Distribution | Leveraging extensive networks, like Johnson & Johnson's, secures market dominance across diverse surgical disciplines. |
| Localized Production in Emerging Markets | Expanding manufacturing in regions like India supports cost-effective cyanoacrylate product commercialization. |
| Specialized Applicator Integration | Medtronic's strategy of integrating applicators streamlines use in minimally invasive surgical procedures. |
| Enhanced Clinical Evidence Generation | Meeting stringent FDA PMA and EU MDR requirements is crucial for novel product market access. |
Research Approach
A standing panel of surgeons, hospital procurement managers, regulatory affairs specialists, and biomaterial scientists provided ongoing calibration for market sizing and trend analysis. Primary interviews with these industry stakeholders were triangulated against extensive secondary research, including FDA filings, EU MDR guidance documents, and NMPA registration data. This approach combined bottom-up market intelligence with top-down validation from medical device journals.
Scenario-bracketing defined the forecast framework, modeling market evolution across the analysis window under varying macroeconomic conditions and regulatory shifts. Segmentation dimensions included product type, application, end-user, delivery mode, and specific material chemistry. Compound Annual Growth Rates were derived from historical data extrapolation and projected adoption rates. Aging population demographics and minimally invasive surgery adoption rates served as key forecast inputs.
Sensitivities concentrate around evolving biocompatibility standards and shifts in healthcare reimbursement policies, which could revise market forecasts. Forecasts reflect assumptions regarding technological advancements and regulatory stability over the projection horizon. Cross-checking against national medical device expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Cryoboxes Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Hemostasis Products Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Finger Splint Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Push-In Plug Vials Market