
 Medical Nitrile Gloves Market | 2026-2036
Medical Nitrile Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Nitrile Gloves Market Outlook
REACH is shifting the cost-of-entry calculus for European-bound nitrile glove suppliers, forcing reformulation investments that smaller producers cannot absorb. Top Glove Corporation Bhd leverages integrated latex-to-glove manufacturing across Malaysian facilities to sustain margin control under these compliance burdens. Hartalega Holdings Berhad anchors its position through advanced nitrile formulation R&D, while Ansell Ltd differentiates via specialized surgical-grade portfolios for hospital procurement networks.
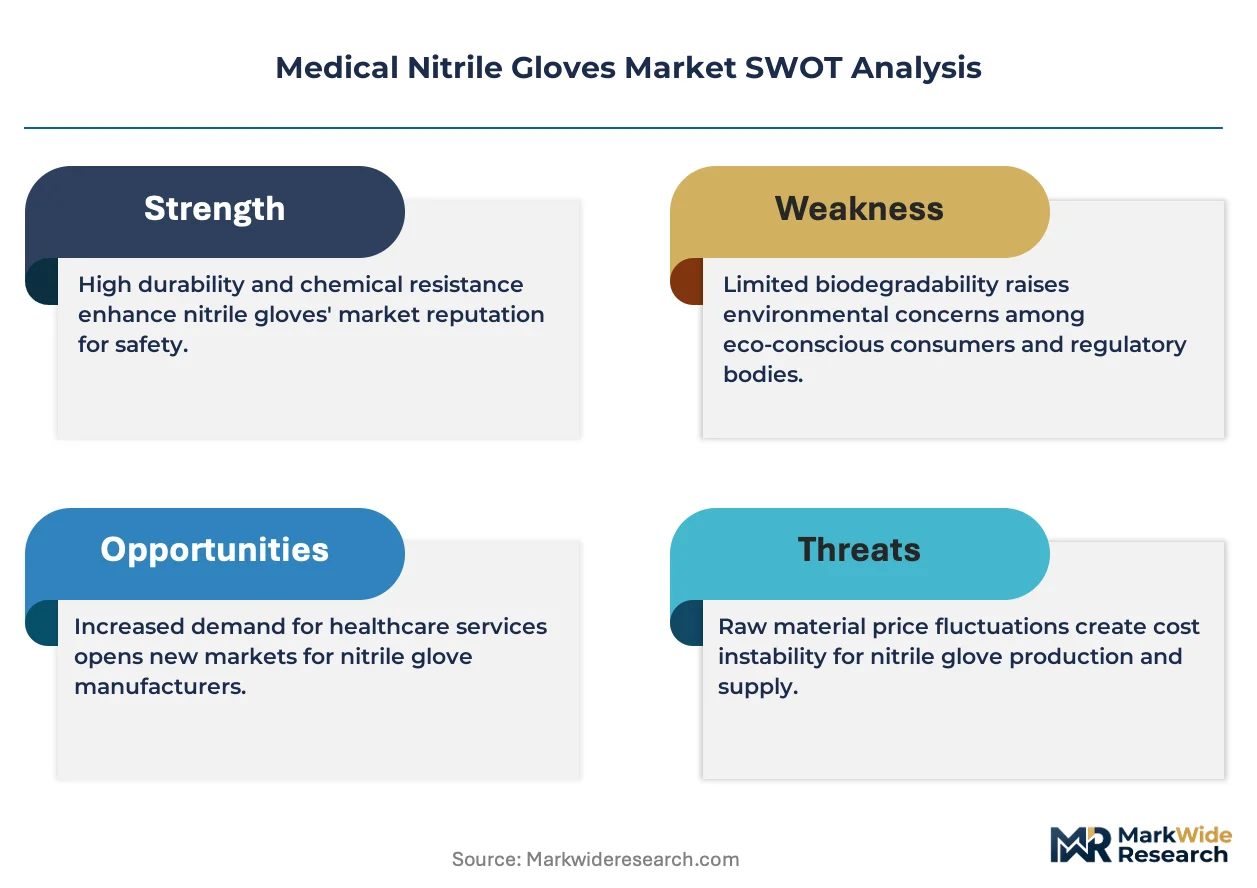
Medical nitrile gloves are synthetic rubber protective barriers manufactured from acrylonitrile-butadiene copolymer, typically ranging from 3 mil to 6 mil in thickness, formed through dipping processes on ceramic hand formers and vulcanized to achieve puncture resistance and chemical impermeability for infection control in clinical settings. Powder-free formulations now dominate hospital procurement due to reduced allergen transmission risk, while AAMI Level certification stratifies pricing across standard examination and high-risk surgical applications. Biodegradable variants represent an emerging segment where margin pools concentrate as sustainability mandates tighten across European and North American healthcare systems.
FDA 510(k) clearance requirements govern US market access for medical-grade nitrile gloves, while CE marking under the EU MDR enforces biocompatibility and performance testing protocols for European distribution. ISO 13485 quality management certification has become a baseline threshold for contract eligibility with major hospital purchasing organizations. Stakeholders must monitor regulatory divergence between FDA and MDR testing standards when configuring multi-region manufacturing and distribution strategies.
Market Dynamics
Malaysia's Klang Valley manufacturing corridor concentrates over 60% of global nitrile glove capacity, creating supply-side leverage that amplifies price volatility during demand surges and forces procurement networks to diversify sourcing strategies.
Growth Catalysts
- FDA 510(k) pathway acceleration:Powder-free device clearances are compressing latex conversion timelines across US hospital systems. Tertiary surgical suites are expanding nitrile procurement volumes as allergen protocols tighten.
- Acrylonitrile-butadiene formulation advances:Thinner 3-mil barriers now match 6-mil puncture resistance, enabling material cost reduction without performance sacrifice. Malaysian producers are capturing margin expansion from these process yields.
- REACH compliance investments:European-bound suppliers absorbing reformulation costs are consolidating market position against smaller competitors. Biodegradable variants are emerging as premium-margin segments under sustainability mandates.
Market Restraints
- Butadiene feedstock volatility:Petrochemical input costs swing with crude oil benchmarks, compressing gross margins during energy price spikes. Producers lack pricing power to pass through full cost fluctuations.
- Single-corridor supply concentration:Malaysia's Klang Valley dominates nitrile glove manufacturing, creating geopolitical and climate-related disruption risks. Buyers face limited alternative sourcing during regional production halts.
- ISO 13485 certification barriers:Quality management system requirements exclude emerging-market entrants from major hospital purchasing organization contracts. Certification timelines stretch 12-18 months.
Strategic Opportunities
- Biodegradable nitrile formulations:European sustainability mandates are creating premium pricing tiers for compostable variants. Producers with enzymatic degradation technology are securing long-term hospital contracts.
- AAMI Level 4 surgical-grade penetration:High-risk surgical applications remain underpenetrated by synthetic alternatives. Specialized barrier certification is opening procurement channels in cardiac and orthopedic suites.
- Direct-to-hospital distribution platforms:E-procurement networks are disintermediating traditional medical supply distributors. Manufacturers with captive logistics are capturing margin previously allocated to channel intermediaries.
Industry Challenges
- Ceramic former engineering talent scarcity:Dipping process optimization requires specialized polymer-ceramic interface expertise. Malaysian technical institutes are struggling to graduate sufficient process engineers.
- EU MDR biocompatibility testing backlogs:European market access timelines have extended as notified body capacity constrains under expanded testing protocols. Manufacturers face revenue recognition delays.
- Legacy latex production line conversion:Retooling chlorination and polymerization equipment for nitrile formulations demands capital deployment without guaranteed offtake volumes. Mid-scale producers face stranded asset risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Nitrile Gloves Market |
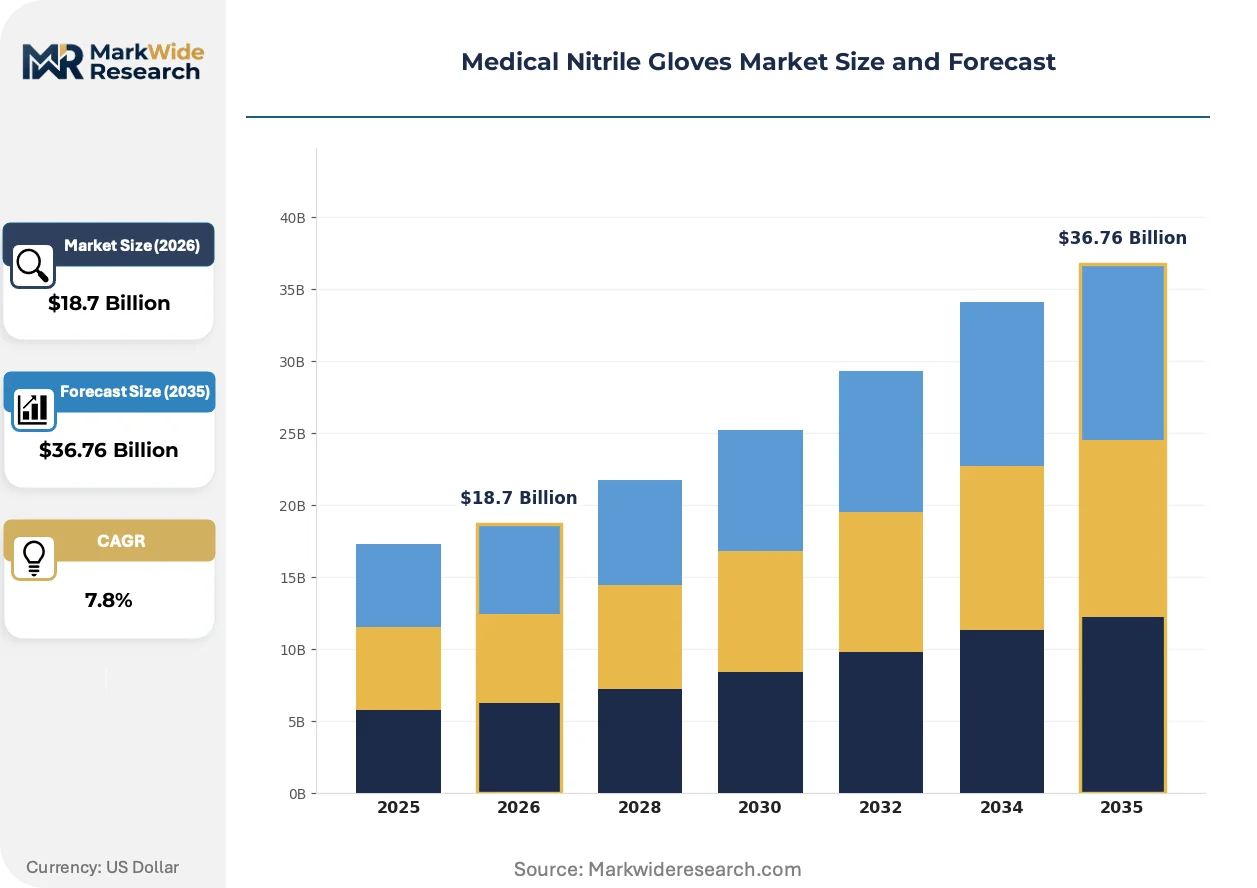
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Powder-Free, Biodegradable, Disposable End User: Hospitals, Clinics, Laboratories, Dental Practices Thickness: 3 Mil, 4 Mil, 5 Mil, 6 Mil Certification: FDA Approved, CE Marked, ISO Certified, AAMI Level |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Kossan Rubber Industries Bhd, Supermax Corporation Berhad, Ansell Ltd, Medline Industries, Inc., Cardinal Health, Semperit AG Holding, INTCO Medical Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Nitrile Gloves Market Strategic Shifts
Advanced nitrile formulation chemistry is compressing thickness-performance tradeoffs while regulatory divergence between FDA and EU MDR standards is fragmenting testing protocols. Procurement networks are consolidating supplier relationships around integrated manufacturers with multi-region certification capabilities.
Next-generation nitrile compounds incorporating graphene oxide additives are unifying electrical conductivity with chemical impermeability for surgical robotics applications. Academic medical centers in Germany and South Korea are piloting these smart-glove variants for haptic feedback integration. The technology is unifying previously separate device categories into single-procedure platforms, compressing procurement SKU complexity.
REACH substance restriction expansions are mandating elimination of specific accelerators and plasticizers from European-bound nitrile formulations. ECHA's updated candidate list is forcing reformulation investments that favor integrated latex-to-glove manufacturers with captive chemical synthesis capabilities. German hospital procurement networks are now requiring full material disclosure documentation as a contract eligibility threshold.
Consolidated purchasing organizations are displacing fragmented departmental buying across US health systems. Group Purchasing Organizations like Premier and Vizient are concentrating contract awards among 3-4 vertically integrated suppliers with domestic inventory buffers. This concentration is most visible in the Southeast US, where hospital system mergers have compressed vendor panels by 40% since 2022.
Medical Nitrile Gloves Market Segmentation
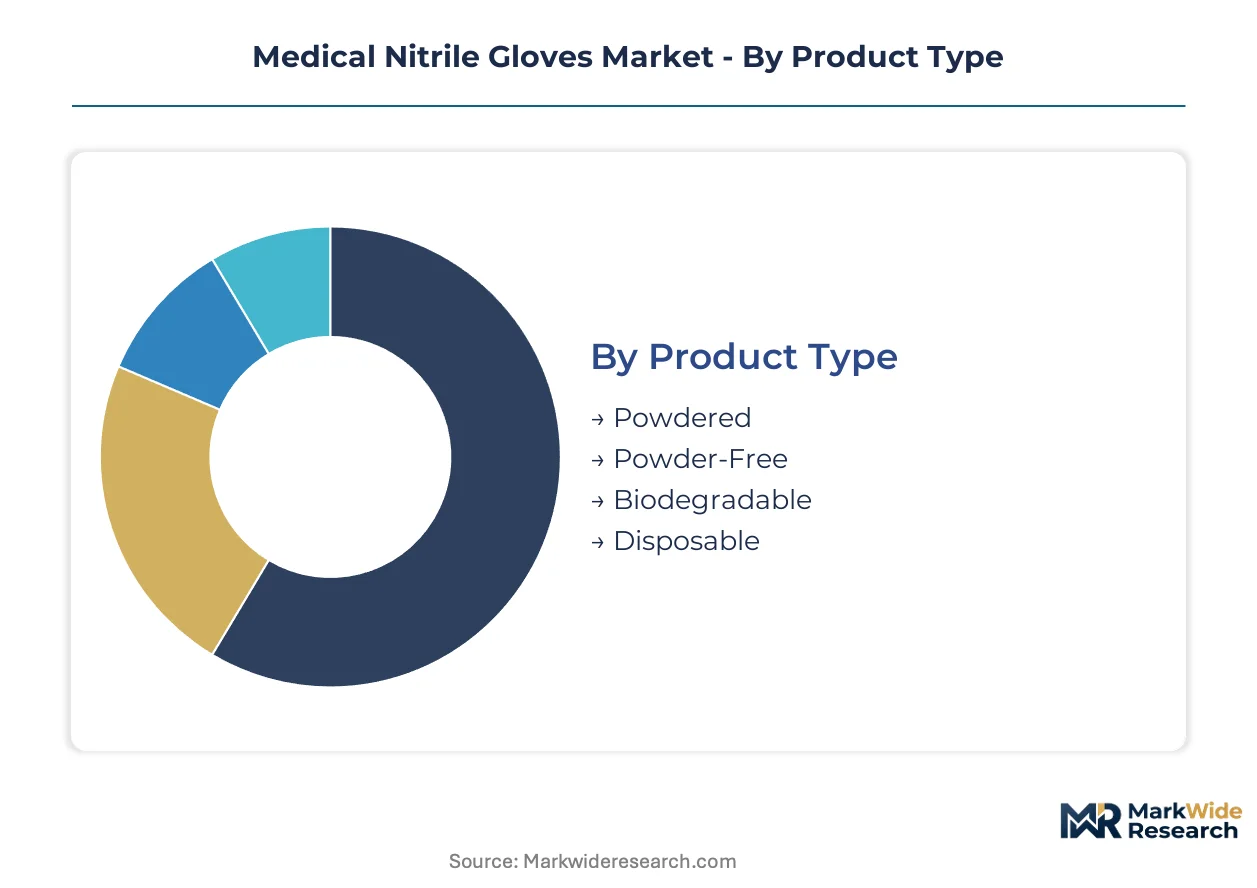
Malaysia's Klang Valley manufacturing corridor shapes how product categories stratify across price and performance tiers. Procurement networks configure sourcing strategies around thickness-certification combinations that match specific clinical risk profiles.
Product Type:
Supply concentration in Malaysian integrated facilities favors producers with captive chlorination and polymerization capabilities.
- Powder-Free:Acrylonitrile-butadiene copolymer barriers undergo chlorination or polymer coating to eliminate surface tack. US tertiary surgical suites are expanding procurement volumes as FDA 510(k) clearances accelerate latex conversion timelines.
- Biodegradable:Enzymatic degradation additives enable compostable end-of-life pathways under European sustainability mandates. German hospital procurement networks now require full material disclosure documentation as contract eligibility thresholds.
- Powdered:Cornstarch or calcium carbonate lubricants ease donning in high-throughput examination settings. Allergen transmission risks have relegated this format to non-clinical applications.
- Disposable:Single-use specifications dominate infection control protocols across clinical environments. Standard examination-grade formulations capture volume in price-sensitive procurement channels.
Today's leader: Powder-Free. Tomorrow's challenger: Biodegradable.
End User:
Cost tier differentiation separates institutional buyers with captive logistics from fragmented departmental purchasing.
- Hospitals:Consolidated purchasing organizations concentrate contract awards among vertically integrated suppliers with domestic inventory buffers. Group Purchasing Organizations in the US Southeast have compressed vendor panels by 40% since 2022.
- Laboratories:Chemical resistance specifications prioritize puncture protection over tactile sensitivity. Research institutions in Germany and South Korea pilot graphene oxide additives for haptic feedback integration.
- Clinics:Outpatient settings balance cost constraints against basic barrier requirements. Smaller procurement volumes limit negotiating leverage with integrated manufacturers.
- Dental Practices:Ergonomic fit and tactile precision dominate selection criteria for extended procedure wear. Specialty distributors maintain relationships with mid-scale formulators.
Volume concentrates in Hospitals. Margin expansion concentrates in Laboratories.
Thickness:
Application-specific risk assessment drives mil selection across standard examination and high-risk surgical contexts.
- 4 Mil:Balanced puncture resistance and tactile sensitivity for general examination and minor procedure applications. Malaysian producers capture margin expansion from advanced formulation yields.
- 6 Mil:Maximum barrier protection for high-risk surgical and chemical handling environments. AAMI Level certification opens procurement channels in cardiac and orthopedic suites.
- 3 Mil:Thinnest commercially viable barrier matching 6-mil puncture resistance through copolymer advances. Material cost reduction without performance sacrifice enables economy-tier positioning.
- 5 Mil:Intermediate specification serving extended-duration procedures requiring enhanced durability. Limited differentiation from adjacent thickness categories constrains dedicated SKU development.
Performance leadership: 6 Mil. Fastest volume gain: 4 Mil.
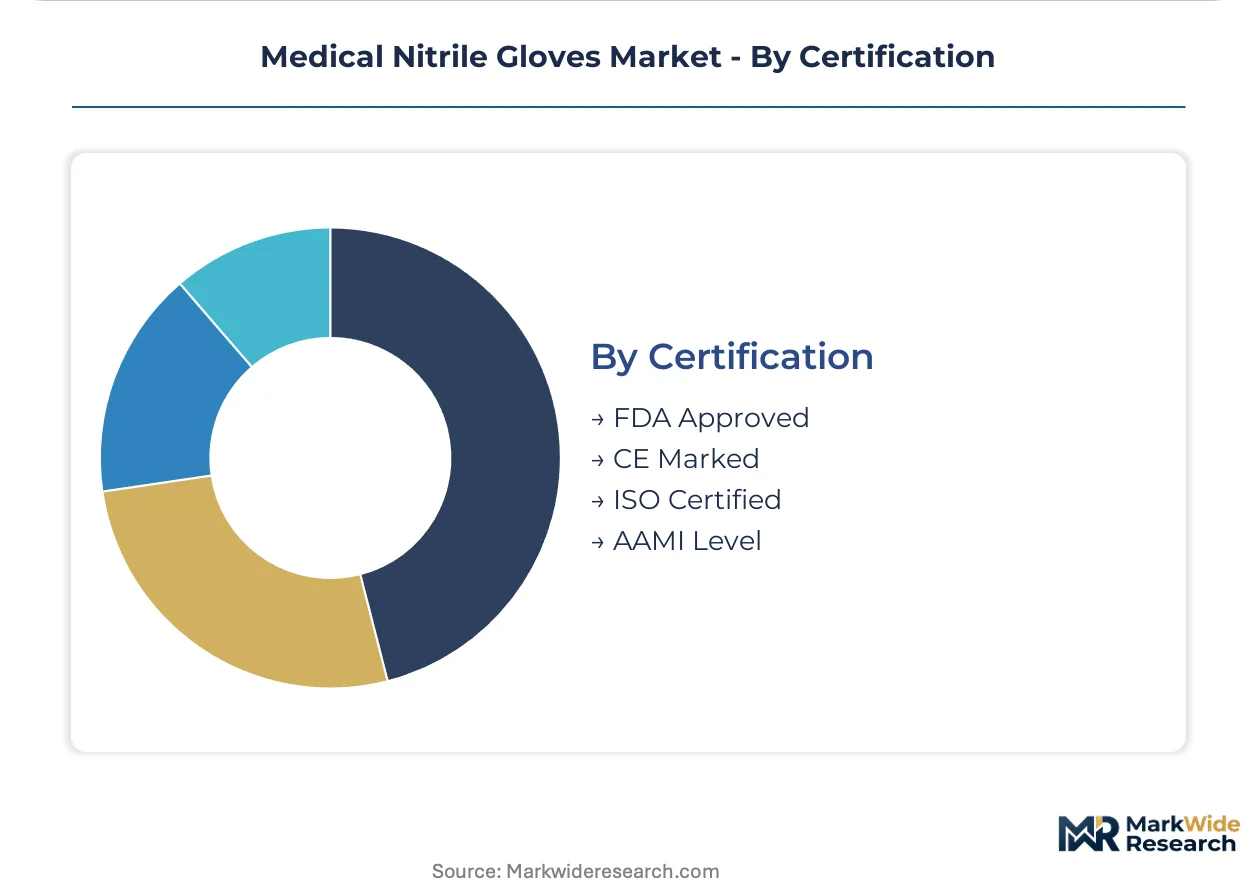
Certification:
Geography determines which regulatory gateway controls market access for multi-region manufacturers.
- FDA Approved:510(k) clearance requirements govern US market entry for medical-grade devices. Powder-free device clearances compress latex conversion timelines across hospital systems.
- CE Marked:EU MDR biocompatibility testing protocols enforce performance standards for European distribution. Notified body capacity constraints extend market access timelines.
- AAMI Level:Barrier performance stratification separates standard examination from high-risk surgical applications. Level 4 certification remains underpenetrated by synthetic alternatives.
- ISO Certified:ISO 13485 quality management certification serves as baseline threshold for contract eligibility with major hospital purchasing organizations. Certification timelines stretch 12-18 months.
Current procurement filter: FDA Approved. Emerging gatekeeper: AAMI Level.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The medical nitrile gloves industry traces its industrial scaling to Malaysia's Klang Valley in the 1990s, where integrated latex-to-glove manufacturing infrastructure first achieved mass production economics. This historical foundation established the supply-side geography that still governs procurement patterns across healthcare systems worldwide.
Malaysia
FDA 510(k) clearances for powder-free devices are accelerating export volumes to US hospital systems. The country's national pharmaceutical regulator enforces GMP standards aligned with US FDA requirements. The Klang Valley corridor concentrates over sixty percent of global nitrile glove capacity, with Shah Alam and Klang facilities expanding chlorination and polymerization lines.
United States
Consolidated purchasing organizations are compressing vendor panels across Southeast hospital systems. FDA maintains stringent 510(k) clearance requirements for medical-grade device entry. Domestic distribution hubs in Memphis and Louisville are building strategic inventory buffers to mitigate single-corridor supply risks.
Germany
REACH substance restrictions are mandating accelerator-free formulations for hospital procurement contracts. ECHA's updated candidate list drives reformulation investments among European-bound suppliers. The Rhine-Ruhr industrial region hosts specialized chemical synthesis facilities serving biodegradable nitrile development programs.
China
Cost-competitive examination-grade production is capturing volume in price-sensitive procurement channels. NMPA medical device registration requirements govern domestic market access standards. The Yangtze River Delta manufacturing belt is expanding nitrile butadiene rubber processing capacity for glove-grade copolymer supply.
Thailand
Emerging production capacity is diversifying buyer sourcing strategies beyond Malaysian concentration. The country's national pharmaceutical regulator maintains alignment with ASEAN harmonized medical device directives. Eastern Economic Corridor industrial zones near Rayong are attracting chlorination equipment investments from regional producers.
Medical Nitrile Gloves Market Competitive Environment
The competitive structure tilts toward integrated Malaysian manufacturers with captive chemical synthesis capabilities. Tiered positioning separates vertically integrated producers controlling latex-to-glove processes from mid-scale formulators dependent on external nitrile butadiene rubber supply. Three archetypes dominate: integrated Malaysian conglomerates with multi-region certification portfolios, specialized surgical-grade specialists, and cost-focused examination-grade producers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term hospital contracts through direct distribution platforms.
Among Malaysian integrated producers, Top Glove Corporation Bhd and Hartalega Holdings Berhad exemplify the scale-driven archetype with backward integration into chemical synthesis. Ansell Ltd occupies a position within the specialized surgical-grade tier, representing differentiation through barrier certification depth. These three anchors illustrate how geographic origin and structural positioning shape competitive strategy in procurement network negotiations.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Kossan Rubber Industries Bhd |
| Supermax Corporation Berhad |
| Ansell Ltd |
| Medline Industries, Inc. |
| Cardinal Health |
| Semperit AG Holding |
| INTCO Medical Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Process engineer scarcity in Malaysia's Klang Valley manufacturing corridor widens labor-cost differentials between integrated producers and mid-scale formulators, compressing margin spreads at the economy tier while premium-grade suppliers capture pricing power through formulation R&D investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AAMI Level 4 surgical-grade portfolios from standard examination formulations and commodity examination volumes. Price differentiation hinges on certification depth and captive chlorination capabilities, with FDA 510(k) clearance timelines extending premium-tier premiums. Cost compression in the economy tier is intensifying because butadiene feedstock volatility erodes producer pricing power. Hospital Group Purchasing Organizations exhibit the lowest price sensitivity, while outpatient clinics face the highest procurement cost pressure.
Supply Chain Analysis
ISO 13485 certification gating excludes emerging-market entrants from major hospital purchasing organization contracts, concentrating qualified supply among Malaysian, Thai, and Chinese producers with established quality management systems. Nitrile butadiene rubber feedstock draws from petrochemical complexes in Northeast Asia and the Middle East. Single-corridor vulnerability in Malaysia's Klang Valley creates geopolitical disruption exposure. Distribution runs through medical supply distributors and emerging direct-to-hospital e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical nitrile gloves represent a late-cycle quality story as US tertiary surgical suites shift procurement specifications toward powder-free, AAMI Level-certified barriers that command sustainable margin premiums over commodity examination grades.
For Market Incumbents: Anticipate REACH substance restriction expansions by accelerating reformulation investments in accelerator-free nitrile compounds before compliance deadlines strand legacy production lines. Secure backward integration into nitrile butadiene rubber synthesis to defend margin position against feedstock volatility. Prioritize multi-region certification portfolios spanning FDA 510(k) and EU MDR pathways to capture consolidated hospital purchasing organization contract awards. For New Entrants and Emerging Players: Enter via biodegradable nitrile formulations targeting German hospital procurement networks where sustainability mandates create premium pricing tiers with limited incumbent competition. Focus white-space penetration on enzymatic degradation technology partnerships with academic medical centers. Leverage direct-to-hospital distribution platforms to disintermediate traditional medical supply channels and capture margin allocation. For Investors and Strategic Acquirers: Hospital Group Purchasing Organizations are the most active strategic consolidators in this space, seeking captive supply security through vertical integration plays. Five-to-ten-year viability favors integrated manufacturers with multi-region certification capabilities and captive chemical synthesis infrastructure. Watch FDA 510(k) clearance backlog duration as the signal indicating inflection in US market access timelines and pricing power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Powder-free device approvals compress latex conversion timelines across US hospital procurement networks. |
| Backward Integration into NBR Synthesis | Captive nitrile butadiene rubber production insulates margin from petrochemical input volatility. |
| Biodegradable Formulation Development | Enzymatic degradation technology secures premium-tier positioning under European REACH mandates. |
| Direct-to-Hospital Distribution Platform | E-procurement networks disintermediate traditional medical supply distributors and capture channel margin. |
| AAMI Level 4 Certification Investment | High-risk surgical barrier approval opens procurement channels in cardiac and orthopedic suites. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down nitrile glove production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee directors, Group Purchasing Organization contracts managers, biomedical engineers, and Malaysian plant operations heads combined with secondary validation from FDA 510(k) filings, EU MDR notified body registries, hospital procurement databases, and customs trade data. Triangulation between demand-side contract awards and supply-side capacity expansions ensures statistical integrity across the analysis window.
Historical trendline analysis of nitrile glove shipment volumes by thickness grade, certification tier, and end-use segment established baseline growth patterns. The projection framework models product type evolution, end-user concentration, and regional regulatory divergence to derive CAGRs. Forecast inputs incorporate butadiene price elasticity, REACH compliance cost absorption rates, and hospital merger-driven procurement consolidation patterns.
Inputs from FDA and EMA regulatory filings were available through the study window; gaps in real-time hospital inventory positioning data introduce uncertainty bands around near-term demand estimates. Deviation in butadiene feedstock pricing or Malaysian production corridor disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Asia-Pacific Syringe Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Medical Clothing Market
Medical Supplies
Middle East and Africa Surgical Sutures Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
Anti Venom Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Global Isothermal Boxes for Vaccines Market
Medical Supplies
North America Medical Clothing Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Amniotic Membrane Market