
 E-Paper Display Market | 2026-2036
E-Paper Display Market Size, Share, and Industry Trends Forecast 2026-2036
E-Paper Display Market Intelligence
The gap between premium flexible displays and commodity monochrome panels is restructuring competitive dynamics across the E-Paper Display landscape. E Ink Holdings leverages captive microcapsule manufacturing to dominate high-margin reflective display supply. Plastic Logic GmbH anchors its position through organic thin-film transistor backplanes for unbreakable wearable form factors. Pervasive Displays specializes in compact segmented modules for industrial instrumentation where extended temperature ranges command price premiums.
E-Paper Display denotes a reflective display technology employing electrically charged pigment particles suspended in fluid microcapsules, typically achieving contrast ratios above 10:1 at sub-10 millisecond refresh rates while consuming power only during image transitions. Electrophoretic technology leads unit shipments due to mature manufacturing and proven bistability in e-reader applications. Flexible displays capture expanding margin pools as retail and transportation sectors adopt curved digital signage and conformable smart labels. Electrowetting variants represent the fastest-growing technology segment for color-capable outdoor signage requiring video-rate switching.
FCC emissions compliance in the United States and REACH substance restrictions in Europe constrain substrate chemistries and manufacturing locations for panel suppliers. China's GB standards for electronic display energy efficiency and the EU's RoHS directives on hazardous substances collectively shape product design cycles and factory certification requirements. Stakeholders must monitor how emerging right-to-repair regulations across multiple jurisdictions alter module replaceability specifications and warranty obligations.
Market Dynamics
The EU Green Deal's circular electronics mandates are compressing design cycles for E-Paper Display manufacturers, forcing substrate chemistry overhauls and recyclability-by-design requirements before panel qualification can proceed.
Growth Catalysts
- Retail digitalization:Supermarket chains in Germany and France are replacing static paper shelf tags with electrophoretic labels that update pricing dynamically. This eliminates manual labor and reduces pricing error disputes at checkout.
- REACH substance restrictions:The European Chemicals Agency's expanded SVHC list is disqualifying legacy display substrates containing heavy metals. Compliant bistable panels gain preferential procurement status in EU public tenders.
- Shenzhen manufacturing cluster:Concentrated electrophoretic panel production in China's Pearl River Delta enables 72-hour sample-to-volume turnaround for e-reader OEMs, compressing competitor lead times.
Market Restraints
- Indium tin oxide supply concentration:Transparent electrode sourcing depends on Chinese rare earth processing facilities, exposing panel makers to export quota volatility and price spikes.
- Refresh rate limitations:Electrophoretic technology cannot achieve video-rate switching below 50 milliseconds, disqualifying E-Paper from interactive digital signage applications requiring motion rendering.
- LCD substitution in budget segments:Liquid crystal display oversupply from Korean and Taiwanese fabs is depressing entry-level pricing for reflective displays in emerging markets.
Strategic Opportunities
- India retail modernization:Reliance Retail and D-Mart are piloting electronic shelf labels in Mumbai and Bangalore stores, creating first-mover advantage for compliant module suppliers.
- Electrowetting color convergence:Combining electrowetting fluid dynamics with electrophoretic backplanes enables outdoor-readable color displays without backlighting power draw.
- EU right-to-repair mandates:The bloc's emerging replaceability requirements favor modular E-Paper designs with standardized connectors over bonded glass assemblies.
Industry Challenges
- Microcapsule formulation expertise:The specialized polymer chemistry workforce required for bistable pigment suspension development concentrates in Taiwan and Japan, creating hiring bottlenecks for new entrants.
- GB standard certification timelines:China's energy efficiency testing protocols for electronic displays require 14-18 week validation cycles, delaying product launches for Western suppliers unfamiliar with documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Paper Display Market |
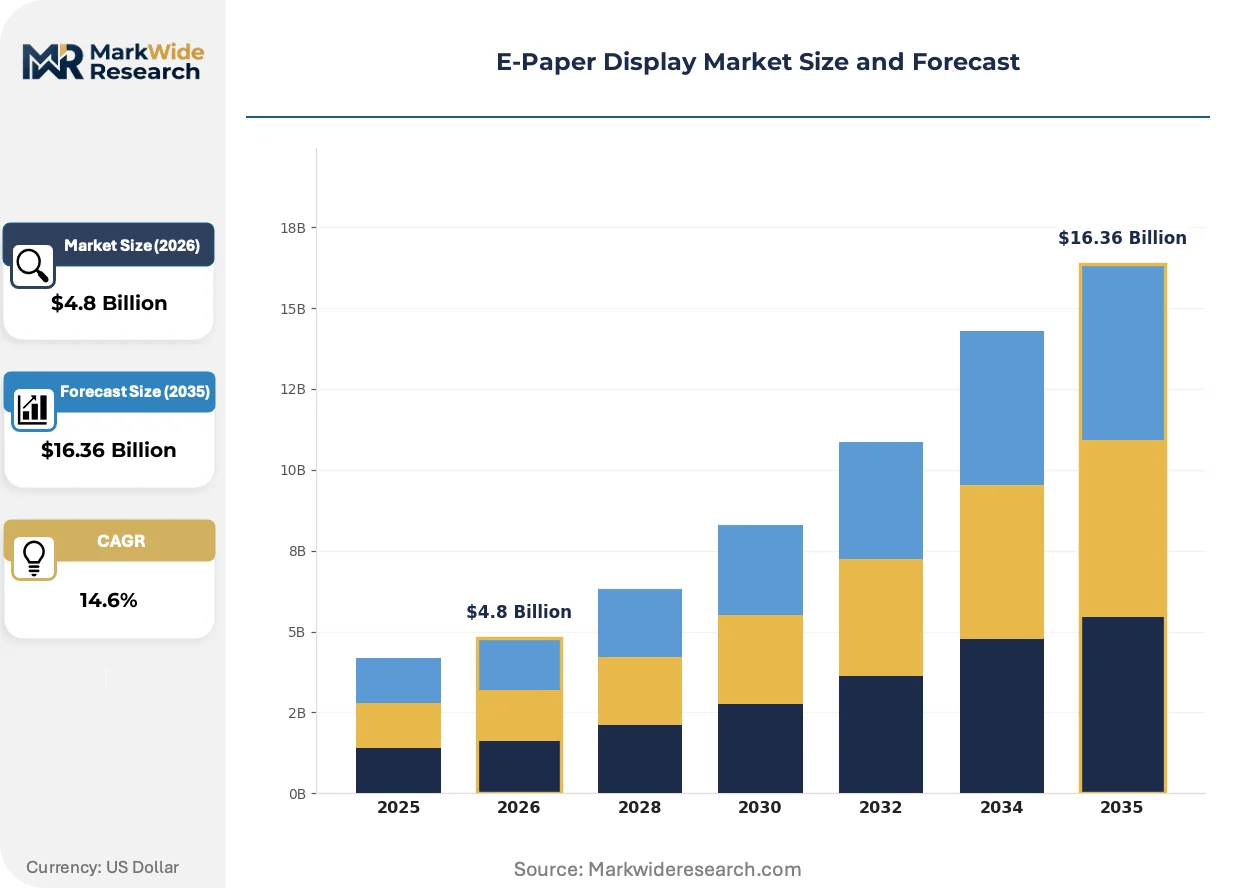
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Segmented Displays, Flexible Displays, Ultra-thin Displays, Monochrome Displays Application: Smart Labels, E-Readers, Digital Signage, Wearable Devices Technology: Electrophoretic, Electrowetting, Cholesteric, Microencapsulated End User: Retail, Education, Transportation, Industrial |
| Companies Covered | E Ink Holdings Inc., Pervasive Displays Inc., Plastic Logic GmbH, Samsung Electronics Co. Ltd., LG Electronics Inc., CLEARink Displays Inc., Toppan Printing Co. Ltd., Solomon Systech Limited, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Paper Display Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory chemistry constraints are converging to redefine what E-Paper Display architectures can achieve in outdoor and wearable environments.
Hybrid electrophoretic-electrowetting architectures are unifying the bistable power efficiency of pigment-based displays with the sub-10 millisecond switching speeds required for color video rendering. Transportation authorities in the Netherlands and Singapore are evaluating these panels for real-time passenger information systems. The technology is unifying previously separate procurement categories for static signage and dynamic displays into single-supplier contracts.
REACH authorization requirements for perfluorinated compounds are forcing reformulation of microcapsule surfactants used in reflective display manufacturing. German chemical suppliers are accelerating bio-based alternatives through ECHA pre-registration. Flexible display segments targeting wearable medical patches face the most stringent substance scrutiny, with notified bodies in France and Germany rejecting legacy formulations.
Buyers in Japanese electronics distribution are consolidating panel procurement through designated trading houses rather than direct manufacturer relationships. Mitsui and Itochu now handle volume contracting for convenience store electronic shelf label deployments across the archipelago. This concentration is visible most acutely in the pharmacy retail vertical, where Matsumoto Kiyoshi and Welcia have standardized on single-source reflective display specifications negotiated through sogo shosha intermediaries.
E-Paper Display Market Segmentation
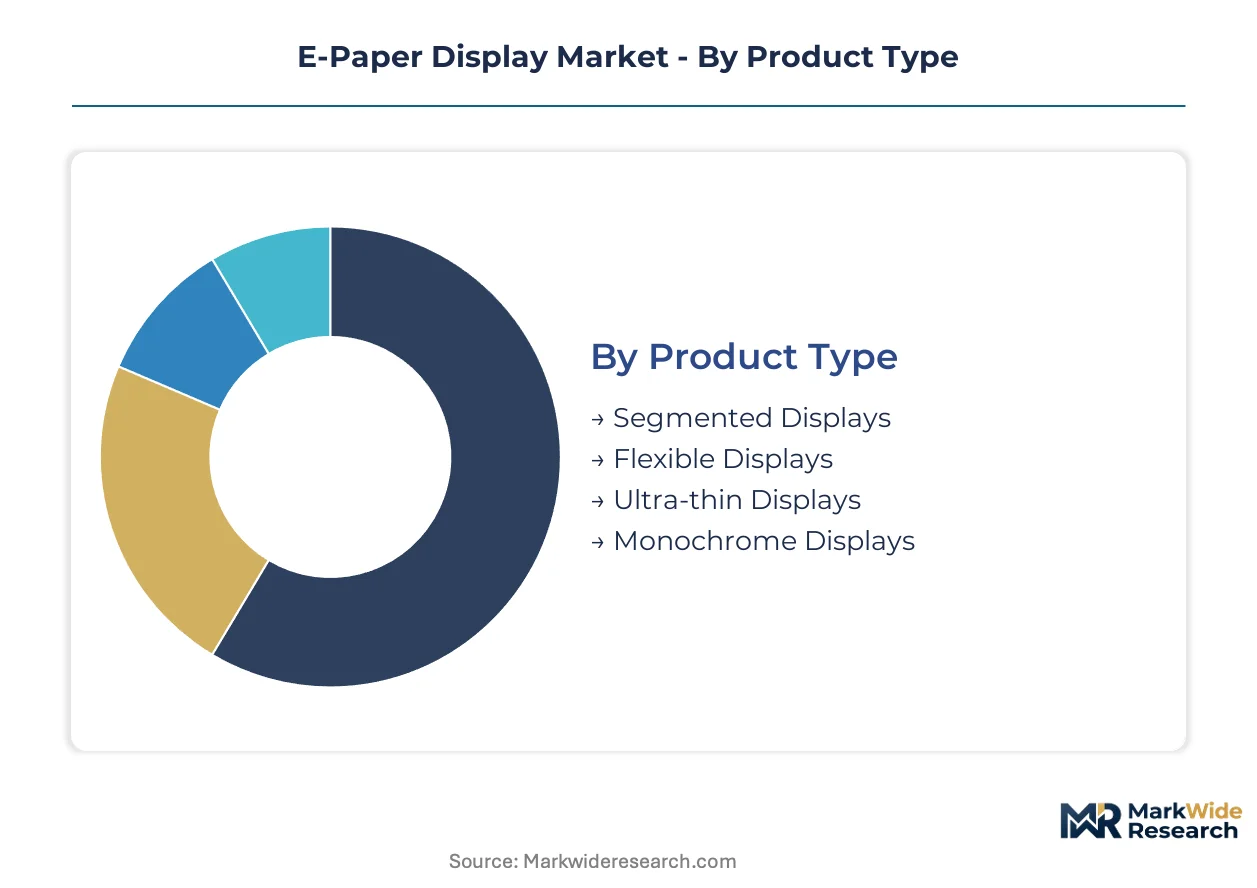
E-Paper Display procurement patterns diverge sharply across buyer archetypes, with retail chains prioritizing total cost of ownership over unit price while industrial operators emphasize operating temperature resilience. Understanding these segment-specific value drivers enables suppliers to align module specifications with actual deployment constraints rather than generic performance benchmarks.
Product Type:
Retail buyers differentiate primarily by installation logistics and mechanical durability requirements, with shelf-edge constraints driving preference for ultra-thin form factors over ruggedized alternatives.
- Segmented Displays:These modules employ discrete electrophoretic cells arranged in fixed patterns for numeric or icon-based readouts, consuming sub-milliwatt power during updates. German supermarket chains source these for basic price displays where network connectivity exceeds graphics requirements. Volume sits with Segmented Displays; growth tilts toward Flexible Displays.
- Flexible Displays:Organic thin-film transistor backplanes enable curvature radii below 10mm without glass substrate fragility. Wearable medical patch manufacturers in Japan specify these for skin-conforming glucose monitors where conformability determines adhesion performance.
- Ultra-thin Displays:Sub-0.3mm total thickness achieved through polymer substrate replacement of glass enables adhesive mounting without structural bezels. Convenience store ESL deployments in France favor these for cramped shelf-edge real estate.
- Monochrome Displays:Single-pigment electrophoretic cells deliver highest contrast ratios and lowest power consumption in bistable operation. E-reader OEMs in China standardize on these for battery life differentiation against LCD tablets.
Procurement weight concentrates in monochrome and segmented variants; flexible architectures are climbing the fastest as wearable form factors proliferate.
Application:
Application selection tracks directly to content refresh frequency requirements, with static information favoring electrophoretic bistability and dynamic content forcing electrowetting trade-offs.
- Smart Labels:Battery-powered electronic shelf labels with wireless pricing updates eliminate manual tag replacement labor. Carrefour and Auchan in France have deployed millions of units across hypermarket networks. Volume sits with Smart Labels; growth tilts toward Digital Signage.
- E-Readers:Dedicated reading devices exploit reflective display daylight readability and paper-like contrast for extended text consumption. Amazon and Kobo maintain procurement volume through annual hardware refresh cycles.
- Digital Signage:Transportation hubs in Singapore and the Netherlands pilot hybrid electrophoretic-electrowetting panels for passenger information requiring both static schedules and emergency video alerts. These deployments represent the steepest expansion trajectory as municipalities consolidate signage procurement.
- Wearable Devices:Smartwatch secondary displays and medical monitoring patches prioritize always-on visibility without battery drain. Japanese electronics trading houses now bundle reflective display procurement with sensor module contracting.
Smart label volumes dominate current shipments; transportation signage applications are gaining share fastest through municipal digital infrastructure budgets.
Technology:
Technology adoption correlates with manufacturing maturity and color capability requirements, with pigment-based approaches dominating unit economics and fluid-dynamic methods capturing premium color specifications.
- Electrophoretic:Microcapsule-encapsulated pigment particles migrate under electric field to form images with sub-500ms update times. Shenzhen manufacturing clusters achieve 72-hour sample turnaround through captive microcapsule production, compressing competitor lead times.
- Electrowetting:Voltage-controlled fluid surface tension manipulates colored oil films for video-rate color switching without backlight power draw. Outdoor signage trials in Dutch transit authorities validate these for direct sunlight readability.
- Cholesteric:Liquid crystal helical structures reflect specific wavelengths without polarizers, enabling brilliant color without filters. Niche medical imaging applications in Germany exploit their archival stability for diagnostic display reference.
- Microencapsulated:Encapsulation chemistry variants optimize particle suspension stability across temperature ranges. Industrial instrumentation buyers in Japan specify these for extended operating envelopes.
Electrophoretic architectures anchor manufacturing scale; electrowetting platforms are expanding most quickly through color video capability.
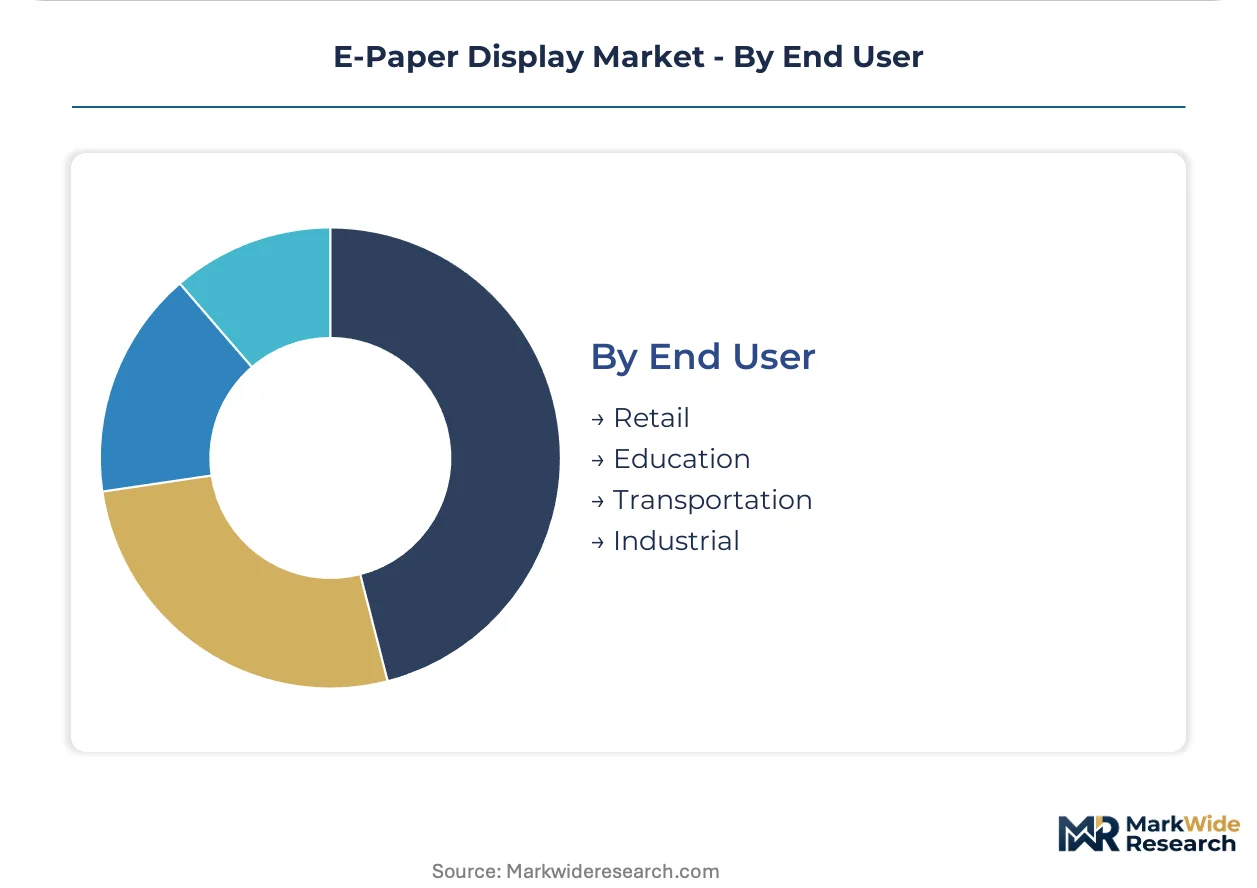
End User:
End-user procurement patterns separate by deployment scale and regulatory exposure, with multinational retail chains demanding REACH-compliant supply chains and industrial operators prioritizing RoHS documentation for factory automation integration.
- Retail:Supermarket and pharmacy chains deploy electronic shelf labels for dynamic pricing and inventory synchronization. Reliance Retail and D-Mart in India are piloting reflective display networks in Mumbai and Bangalore locations.
- Education:E-textbook platforms and digital worksheet systems specify low-power displays for classroom device fleets. Japanese school districts evaluate these for one-to-one computing initiatives.
- Transportation:Rail and aviation operators require sunlight-readable displays with wide viewing angles for passenger information. Dutch and Singaporean transit authorities consolidate static and dynamic signage procurement through hybrid panel specifications.
- Industrial:Factory floor instrumentation and warehouse management systems demand extended temperature operation and shock resistance. German automotive suppliers specify these for production line status displays.
Retail procurement drives current volume concentration; transportation infrastructure budgets are gaining share fastest through municipal digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors electrophoretic panel production through concentrated display fabs and e-reader OEM clusters that compress sample-to-volume turnaround to 72 hours. This Pearl River Delta concentration shapes procurement patterns across three continents.
China
GB standards for electronic display energy efficiency impose 14-18 week certification timelines that delay Western supplier product launches unfamiliar with documentation protocols. Shenzhen and Dongguan manufacturing clusters dominate captive microcapsule production for electrophoretic backplanes. MIIT dual carbon goals pressure fabs to eliminate high-energy curing processes from display substrate manufacturing.
Germany
Carrefour and Auchan hypermarket networks across France source compliant modules through German distribution channels for electronic shelf label deployments. ECHA REACH authorization requirements for perfluorinated compounds force microcapsule surfactant reformulation ahead of panel qualification. Bavarian chemical suppliers accelerate bio-based alternatives through pre-registration workflows.
United States
Amazon and Kobo maintain e-reader procurement volume through annual hardware refresh cycles that standardize on monochrome electrophoretic specifications. FCC emissions compliance constrains substrate chemistries and manufacturing locations for panel suppliers serving North American OEMs. California-based retail technology vendors pilot dynamic pricing networks for supermarket chains.
Japan
Mitsui and Itochu trading houses consolidate convenience store electronic shelf label procurement across pharmacy retail verticals including Matsumoto Kiyoshi and Welcia. METI efficiency standards shape module specifications for wearable medical patch manufacturers in Osaka and Nagoya clusters. Japanese school districts evaluate low-power displays for one-to-one computing initiatives.
Netherlands
Transit authorities in Amsterdam and Rotterdam pilot hybrid electrophoretic-electrowetting panels for passenger information systems requiring both static schedules and emergency video alerts. EU Green Deal circular electronics mandates compress design cycles for substrate chemistry overhauls before panel qualification. Eindhoven-region display integrators serve Belgian and German retail modernization projects.
E-Paper Display Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the E-Paper Display landscape, with captive microcapsule manufacturing conferring cost advantages on integrated players while modular specialists capture niche specifications. The vendor base separates into three strategic archetypes: integrated pigment formulators controlling upstream chemistry, backplane specialists leveraging organic thin-film transistor platforms, and application-focused module integrators. Dominant competitive moves include backward integration into microcapsule production and technology licensing partnerships that expand addressable markets beyond traditional e-reader segments.
Among Taiwan and Japan-based chemistry specialists, E Ink Holdings exemplifies the integrated formulator archetype through captive manufacturing positions. Pervasive Displays occupies a position within the compact module specialist tier, while Plastic Logic GmbH anchors the flexible backplane segment for wearable form factors. These three company structures represent distinct strategic postures: vertically integrated chemistry control, application-specific miniaturization, and conformable substrate engineering.
| Leading Market Players |
|---|
| E Ink Holdings Inc. |
| Pervasive Displays Inc. |
| Plastic Logic GmbH |
| Samsung Electronics Co. Ltd. |
| LG Electronics Inc. |
| CLEARink Displays Inc. |
| Toppan Printing Co. Ltd. |
| Solomon Systech Limited |
| Seiko Epson Corporation |
| Others |
Cost & Logistics Intelligence
EU Green Deal circular electronics mandates are forcing substrate chemistry overhauls that compress supplier margins and accelerate pass-through pricing for REACH-compliant modules. Panel buyers now face stepped cost structures depending on certification status and recyclability-by-design features.
Pricing Analysis
Value-based pricing anchored to total cost of ownership dominates retail chain procurement, with electronic shelf label networks priced on labor savings and pricing error reduction rather than unit hardware costs. Three-tier pricing structure across premium flexible displays, standard monochrome panels, and economy segmented modules separates buyers by application complexity and volume scale. Cost compression in entry-level monochrome segments is intensifying because LCD oversupply from Korean and Taiwanese fabs creates substitution pressure. Industrial instrumentation buyers show lowest price sensitivity, prioritizing extended temperature operation over per-unit cost.
Supply Chain Analysis
GB standard certification timelines and REACH substance restrictions gate qualified supplier access, compressing the vendor pool for Western buyers. Manufacturing concentrates in China, Taiwan, and Japan, with Shenzhen fabs controlling captive microcapsule production for electrophoretic backplanes. Raw material dependencies center on indium tin oxide from Chinese rare earth processing, specialized polymer chemistry feedstocks, and glass or polymer substrates. Single-source vulnerability in transparent electrode sourcing exposes panel makers to export quota volatility. Distribution runs through designated trading houses in Japan and direct manufacturer relationships in European retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The E-Paper Display market sits in a technology-transition phase where hybrid electrophoretic-electrowetting architectures are displacing pure electrophoretic legacy in transportation and outdoor signage applications.
For Market Incumbents: Hedge against LCD substitution in budget segments by accelerating backward integration into microcapsule production and securing captive indium tin oxide supply arrangements. E Ink Holdings and integrated chemistry specialists must defend margin position through proprietary formulation lock-in while expanding electrowetting licensing partnerships to capture color video signage growth. For New Entrants and Emerging Players: The gap between premium flexible displays and commodity monochrome panels creates entry space for mid-tier module integrators targeting India's retail modernization pilots and European right-to-repair compliant designs. Focus white-space capture on pharmacy retail verticals in Japan through trading house partnerships, and on industrial instrumentation segments requiring extended temperature specifications where incumbent capacity is constrained. For Investors and Strategic Acquirers: The window for entry favors organic thin-film transistor backplane specialists and electrowetting technology platforms over commodity electrophoretic assemblers. Long-term viability hinges on color capability and flexible form factor IP. Watch hybrid panel qualification timelines at Dutch and Singaporean transit authorities as the inflection signal for technology convergence adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microcapsule Production | Captive chemistry control locks in margin for E Ink Holdings against Taiwanese competitors. |
| Electrowetting Technology Licensing | CLEARink and fluid-dynamic specialists expand addressable market beyond static e-reader applications. |
| REACH-Compliant Surfactant Reformulation | German chemical suppliers accelerate bio-based alternatives through ECHA pre-registration workflows. |
| Flexible Display Capacity Expansion | Plastic Logic GmbH scales organic thin-film transistor output for wearable medical patch manufacturers. |
| Trading House Distribution Partnerships | Mitsui and Itochu consolidate convenience store procurement across Matsumoto Kiyoshi and Welcia networks. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with display module procurement managers, fab operations directors, retail technology vendors, and ECHA compliance specialists. E Ink Holdings SEC disclosures, MIIT GB standard documentation, Shenzhen customs export records, and EU Green Deal implementation guidance formed the documentary backbone. Bottom-up shipment tallies by application and technology were cross-validated against top-down market sizing from electrophoretic panel capacity estimates.
Granularity-level modeling proceeded at the intersection of product type, application, technology, and end-user dimensions, with separate treatment of flexible versus rigid substrate architectures and color versus monochrome capability tiers. CAGRs were derived from segment-level volume projections reconciled against macroeconomic drivers and regulatory implementation timelines across the analysis window. Forecast inputs incorporated electronic shelf label deployment schedules at Carrefour and Auchan, e-reader OEM refresh cycles at Amazon and Kobo, and hybrid panel pilot timelines at Dutch and Singaporean transit authorities.
Inputs from ECHA pre-registration databases and MIIT certification registries were available through the study window; gaps in real-time trading house contract disclosure introduce uncertainty bands around Japanese procurement volume estimates. Forecasts reflect assumptions on REACH authorization timelines and GB standard documentation familiarity among Western suppliers. A model refresh is warranted upon material change in EU right-to-repair regulatory finalization or indium tin oxide export quota adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Privacy Screens Market
Display Technologies
DLP Projector Market
Display Technologies
Paper-Thin Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Interactive Video Wall Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Commercial Touch Display Market
Display Technologies
OLED Panel Market
Display Technologies
Head Up Display Market
Display Technologies
Projector Screen Market
Display Technologies
Touch Screen Film Market
Display Technologies
Computer Monitor Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Display Control and Management System Market
Display Technologies
Vietnam Digital Signage Market