
 Global Center Stack Display Market | 2026-2036
Global Center Stack Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Center Stack Display Market Intelligence
Modular display bundling is realigning how OEMs procure center stack systems. Continental AG leverages captive touchscreen production to control cost and quality across European programs. Visteon Corporation anchors North American supply through integrated software-hardware modules for domestic automakers. Panasonic Holdings Corporation dominates Japanese OEM relationships with specialized OLED and LCD configurations for hybrid and electric platforms.
Center stack displays are integrated touchscreen or non-touchscreen panels mounted in a vehicle's central console, typically featuring capacitive or projected capacitive sensing layers, anti-glare coatings, and operating temperatures from minus forty to eighty-five degrees Celsius to manage infotainment, climate, and navigation interfaces. Touchscreen displays lead product type revenue due to universal OEM specification for mid-range and premium vehicles, while OLED displays represent the fastest-growing category as automakers adopt flexible, high-contrast panels for differentiated cabin experiences. Capacitive technology occupies the dominant technology position, though projected capacitive variants are gaining share in electric vehicles where multi-touch gesture control is standard.
NHTSA guidelines in the United States and EU General Safety Regulation requirements shape display placement, driver distraction limits, and touch-response latency standards. ECE R79 and ISO 15008 compliance frameworks govern field-of-view positioning and minimum font legibility across European and harmonized markets. Stakeholders must monitor evolving software-defined vehicle architectures that decouple hardware refresh cycles from model-year timelines.
Market Dynamics
Software-defined vehicle architectures are decoupling hardware refresh cycles from model-year timelines, forcing Tier-1 suppliers to restructure development contracts around over-the-air update capabilities rather than fixed physical specifications.
Growth Catalysts
- EU Green Deal electrification mandates:European OEMs must accelerate EV platform rollouts, expanding touchscreen specifications across mass-market lineups to meet interface standardization requirements.
- Projected capacitive sensing:Multi-touch gesture control is becoming standard in electric vehicles, pulling demand for advanced touch layers that support pinch, swipe, and haptic feedback protocols.
- German R&D clusters:Dense supplier concentration around Stuttgart and Munich enables rapid prototyping cycles, compressing time-to-market for new display form factors.
Market Restraints
- Indium tin oxide price volatility:Input cost fluctuations for transparent conductive layers squeeze margins on mid-range touchscreen configurations.
- Single-source OLED substrate supply:Japanese and South Korean material providers control critical flexible substrate capacity, creating geographic concentration risk.
- NHTSA distracted-driving latency caps:Strict touch-response timing requirements limit design freedom and extend validation timelines for new interface concepts.
Strategic Opportunities
- India domestic OEM expansion:Local automakers are upgrading cabin electronics specifications, creating white space for integrated display-module suppliers.
- Head-up display convergence:Center stack systems are merging with windshield projection technologies, enabling new bundled cockpit-electronics offerings.
- EU General Safety Regulation phase-in:Mandated driver-monitoring integration creates demand for camera-embedded display bezels and gaze-tracking compatibility.
Industry Challenges
- Embedded software talent scarcity:Automotive-qualified Linux and hypervisor engineers command premium compensation, constraining supplier scaling.
- ISO 26262 functional safety certification:ASIL-B compliance for display control units demands 18-24 month validation cycles that mismatch consumer-electronics refresh rates.
- Legacy CAN bus integration:New display architectures must bridge to 20-year-old vehicle networks, adding protocol translation complexity and failure-mode analysis burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Center Stack Display Market |
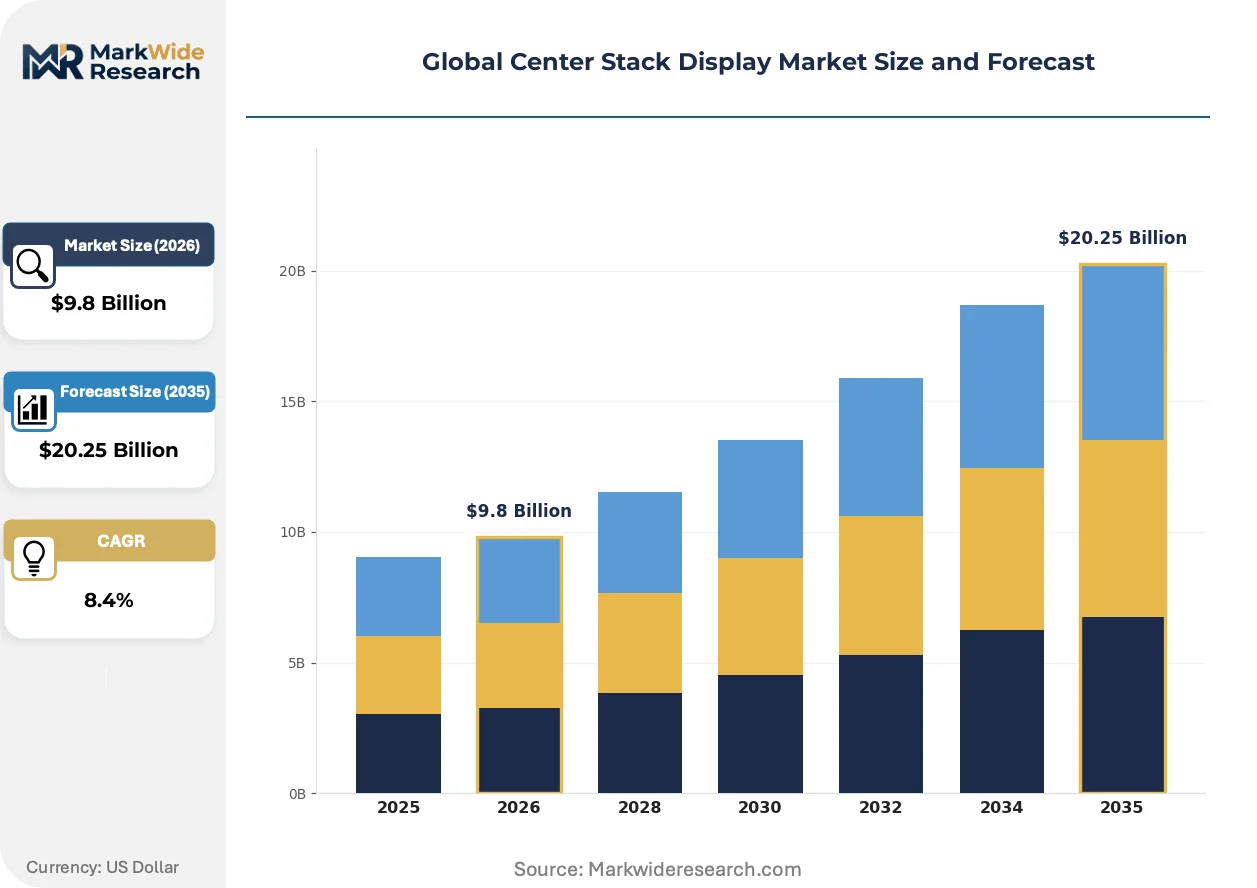
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen Display, Non-Touch Display, Head-Up Display, OLED Display, LCD Display Technology: Resistive, Capacitive, Infrared, Surface Acoustic Wave, Optical, Projected Capacitive Application: Passenger Cars, Commercial Vehicles, Off-Highway Vehicles, Specialty Vehicles, Electric Vehicles End User: OEM Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Fleet Operators |
| Companies Covered | Continental AG, Visteon Corporation, Panasonic Holdings Corporation, Robert Bosch GmbH, Alpine Electronics, Inc., Preh GmbH, Hyundai Mobis, Marelli Corporation, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Center Stack Display Market Strategic Shifts & Innovations
Display technologies are fragmenting across performance tiers as automakers differentiate cabin experiences, while regulatory pressure on driver distraction forces simultaneous innovation in interface safety and visual engagement.
OLED panels with plastic substrates are overtaking glass-based LCD configurations in premium electric vehicle programs. BMW and Mercedes-Benz specification teams have shifted 2026-2028 model year sourcing toward flexible OLED for curved dashboard integration. This technology is overtaking rigid display formats by enabling seamless surface transitions between center stack and instrument cluster zones.
EU General Safety Regulation requirements are mandating direct driver-monitoring integration into display bezels by 2026. Automotive suppliers must now engineer camera-embedded touch modules that meet ECE R79 field-of-view positioning rules while maintaining optical clarity. European premium OEMs are responding with dedicated "driver attention" UX modes that dim non-critical content when gaze tracking detects distraction.
Automotive procurement teams are consolidating vendor relationships around software-hardware bundles rather than discrete component sourcing. Tier-1 suppliers now compete on integrated cockpit domain controller platforms that merge display driving, touch processing, and vehicle network gateways. This pattern is most visible in Germany and Japan, where OEMs have eliminated separate display-controller RFQs in favor of single-source cockpit-electronics contracts.
Global Center Stack Display Market Segmentation
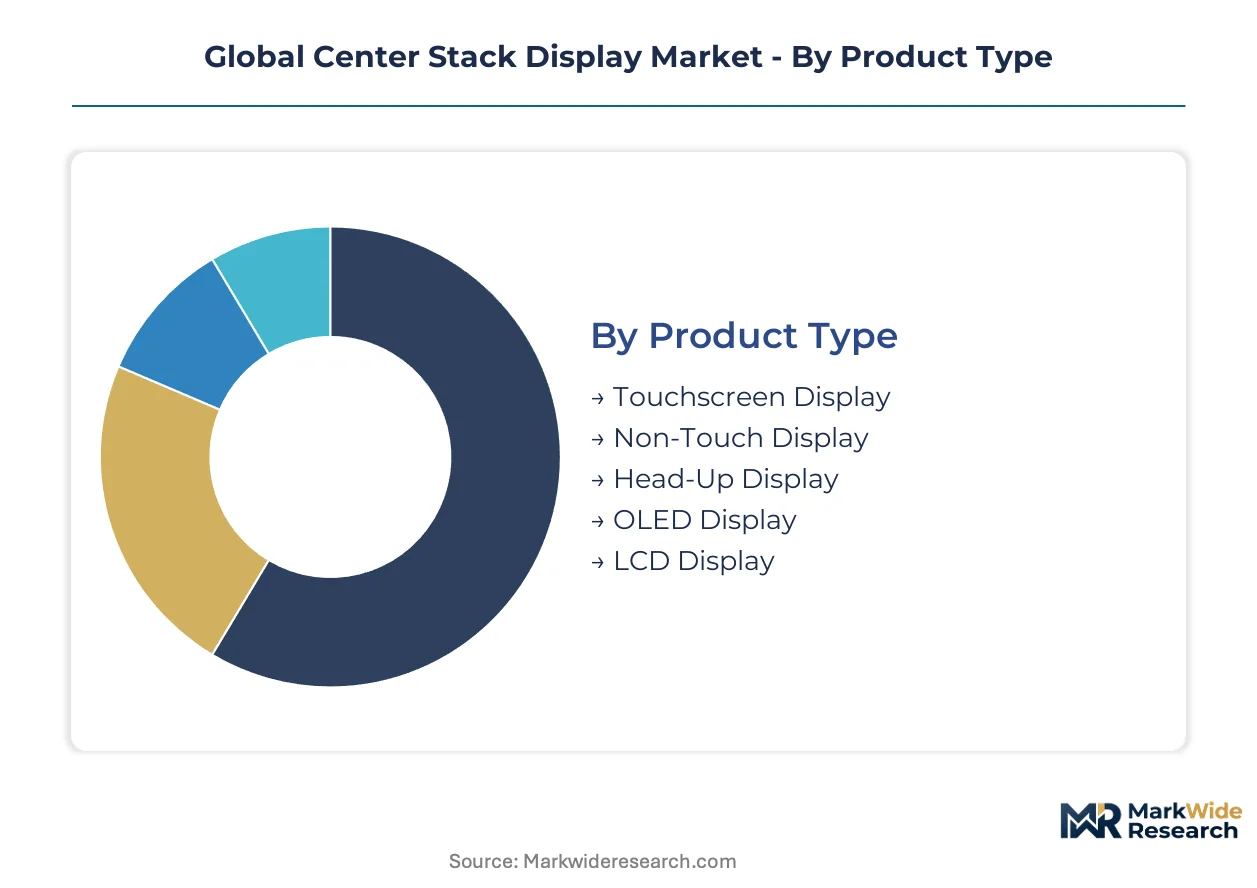
Center stack display procurement varies sharply by integration depth. Standalone modules serve legacy platforms while embedded systems dominate software-defined vehicle architectures. Understanding segment boundaries helps suppliers align R&D investment with OEM sourcing patterns.
Product Type:
Integration depth separates standalone retrofit units from embedded factory-installed systems. Touchscreen and OLED configurations anchor embedded platforms, while non-touch displays persist in commercial vehicle retrofit channels.
- Touchscreen Display:Capacitive sensing layers with anti-glare coatings operate across minus forty to eighty-five degrees Celsius. Passenger car OEMs in Germany and Japan specify these for mid-range and premium lineups under EU Green Deal electrification mandates. NHTSA touch-response latency caps constrain gesture protocol design.
- OLED Display:Plastic substrates enable curved dashboard integration with seamless surface transitions between center stack and instrument cluster zones. BMW and Mercedes-Benz specification teams have shifted sourcing toward flexible OLED for model years through 2028, displacing rigid formats in premium electric vehicle programs.
- Non-Touch Display:Physical button-retained interfaces serve commercial vehicle operators requiring glove-compatible operation in construction and agriculture sectors.
- Head-Up Display:Windshield projection modules are merging with center stack systems for bundled cockpit-electronics offerings.
- LCD Display:Glass-based configurations retain cost advantage in economy passenger car segments and fleet vehicle retrofits.
Touchscreen display leads volumes today; OLED display is gaining share fastest.
Technology:
Cost tier stratification separates mature resistive implementations from premium projected capacitive stacks. Volume concentration in electric vehicles pulls demand toward multi-touch capable layers.
- Capacitive:Dominant technology position across passenger car OEM specifications. Single-touch variants serve economy segments while multi-touch configurations penetrate mass-market electric vehicles.
- Projected Capacitive:Supports pinch, swipe, and haptic feedback protocols becoming standard in electric vehicle platforms. Indium tin oxide price volatility squeezes margins on mid-range configurations using transparent conductive layers.
- Resistive:Pressure-activated layers retain position in commercial vehicle and off-highway equipment where glove operation is mandatory.
- Infrared:Frame-based sensing suits large-format displays in specialty vehicles with bezel width tolerance.
- Surface Acoustic Wave:High clarity performance serves premium applications requiring optical precision.
- Optical:Camera-based touch detection enables unconventional form factors in concept and limited-production vehicles.
Capacitive technology commands the largest installed base; projected capacitive is expanding most quickly.
Application:
Customer type determines specification stringency. Fleet operators prioritize durability and standardization while private passenger demand drives feature differentiation.
- Passenger Cars:Largest addressable volume with tiered specifications across economy, mid-range, and premium segments. EU General Safety Regulation mandates driver-monitoring integration by 2026.
- Electric Vehicles:Fastest-expanding category with standardized multi-touch gesture control and over-the-air update capability requirements.
- Commercial Vehicles:Fleet procurement emphasizes ruggedized housings and CAN bus compatibility with 20-year-old vehicle networks.
- Off-Highway Vehicles:Construction and agriculture equipment demands glove-compatible interfaces and extreme temperature resilience.
- Specialty Vehicles:Ambulance, fire, and military applications require customized bezel configurations and electromagnetic interference shielding.
Passenger cars dominate current procurement volumes; electric vehicles show the steepest expansion trajectory.
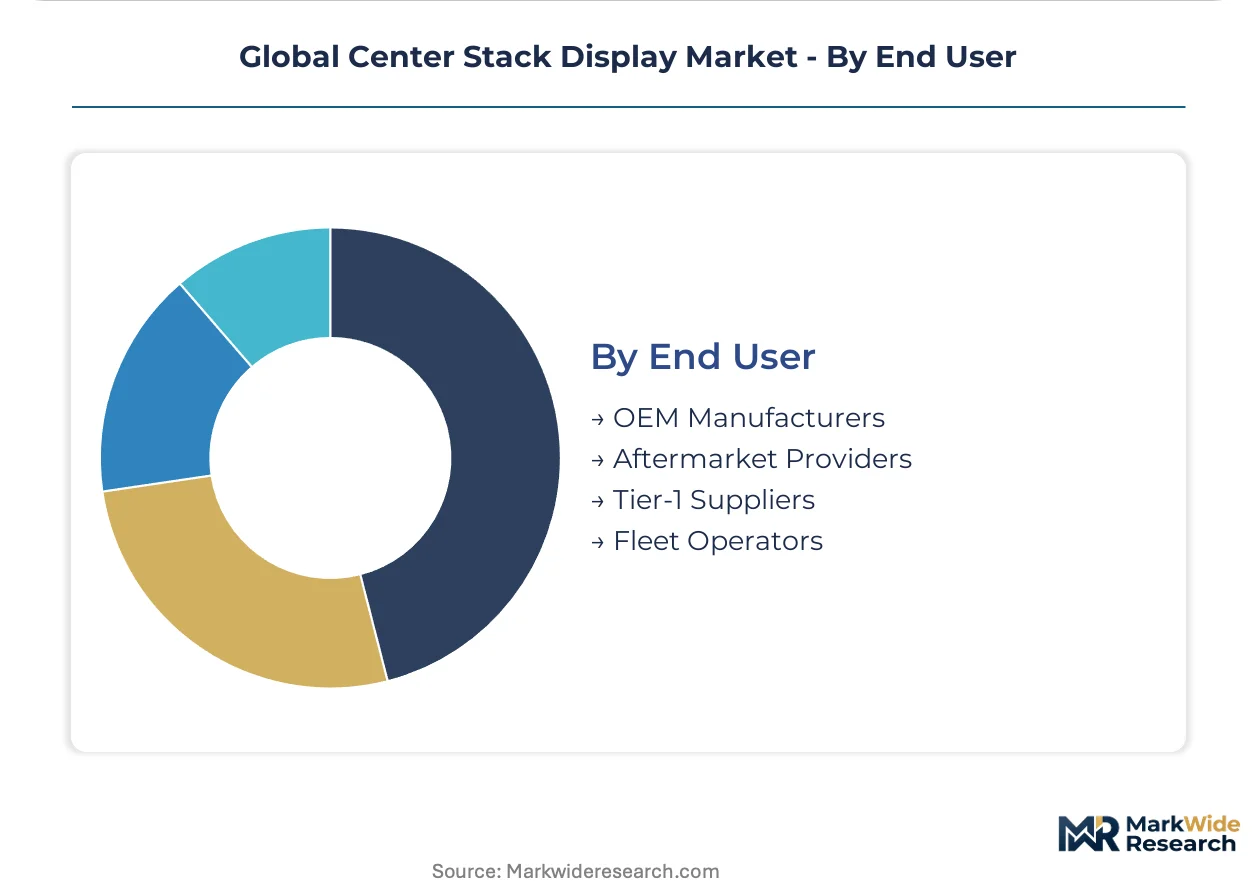
End User:
Supply concentration shapes margin structure. OEM direct sourcing consolidates around integrated software-hardware bundles while aftermarket channels fragment across retrofit specialists.
- OEM Manufacturers:Direct procurement of integrated cockpit domain controller platforms eliminates separate display-controller RFQs in Germany and Japan. Single-source contracts now cover display driving, touch processing, and vehicle network gateways.
- Tier-1 Suppliers:Continental AG, Visteon Corporation, and Panasonic Holdings Corporation compete on bundled module supply with captive touchscreen production or integrated software-hardware configurations.
- Aftermarket Providers:Fragmented channel serving vehicle owners outside warranty periods with standardized fitment kits.
- Fleet Operators:Volume purchasers prioritizing total cost of ownership and standardized maintenance protocols across multi-brand vehicle pools.
OEM manufacturers represent the largest contract value; Tier-1 suppliers are capturing share fastest through bundled platform offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The center stack display industry traces its commercial scale to German automotive electronics engineering in the 1990s, when Stuttgart and Munich suppliers pioneered integrated cockpit modules for European OEM platforms. This heritage established technical standards and supplier relationships that persist across today's electrified vehicle architectures.
Germany
EU Green Deal electrification mandates accelerate EV platform rollouts from Volkswagen, BMW, and Mercedes-Benz, expanding touchscreen specifications across mass-market lineups. ECE R79 and ISO 15008 compliance frameworks govern field-of-view positioning and minimum font legibility requirements. Stuttgart and Munich host dense R&D clusters where Continental AG and Robert Bosch GmbH operate rapid prototyping facilities, compressing time-to-market for curved OLED form factors.
United States
NHTSA distracted-driving guidelines tighten display-interface requirements, capping touch-response latency and constraining gesture protocol design for domestic automakers. The agency's field-of-view placement rules shape center stack positioning across Ford, General Motors, and Tesla programs. Southeast Michigan anchors North American supply chain concentration, where Visteon Corporation maintains integrated software-hardware module production for domestic OEM contracts.
Japan
Japanese OEMs specify specialized OLED and LCD configurations for hybrid and electric platforms, with Toyota, Honda, and Nissan driving procurement volumes. METI industrial policy supports domestic display material supply chains, including critical flexible substrate capacity. The Kanto region around Tokyo and the Chubu industrial corridor near Nagoya concentrate Panasonic Holdings Corporation and Alpine Electronics manufacturing relationships with domestic automakers.
China
Domestic EV manufacturers BYD, NIO, and XPeng specify large-format center stack displays as standard cabin differentiation, pulling demand for projected capacitive multi-touch layers. MIIT vehicle-type approval regulations incorporate display safety requirements aligned with evolving international standards. The Yangtze River Delta and Pearl River Delta manufacturing belts host emerging domestic display module suppliers serving local OEM electrification roadmaps.
South Korea
Hyundai and Kia electrification programs standardize advanced touch interfaces across Genesis premium and mass-market lineups, with Hyundai Mobis anchoring domestic supply. The country's display material providers control critical flexible OLED substrate capacity, creating geographic concentration in upstream supply. Seoul Capital Area and Busan-Ulsan industrial zones concentrate R&D and manufacturing for export-oriented automotive electronics production.
Global Center Stack Display Market Key Industry Players
Premium-margin players sit above commodity-margin players across software-hardware integration depth, with bundled cockpit domain controllers commanding superior contract terms against discrete display component suppliers. The vendor base stratifies into three tiers: integrated platform providers with captive touchscreen production, software-hardware module specialists, and regional component fabricators serving aftermarket channels. Dominant competitive moves include single-source cockpit-electronics contracts replacing separate display-controller RFQs, and backward integration into touch layer manufacturing to control indium tin oxide input costs.
Within the integrated platform tier, Continental AG and Robert Bosch GmbH exemplify European archetypes combining captive production with software stack ownership, while Visteon Corporation occupies a position representing North American bundled module supply. Panasonic Holdings Corporation anchors the Asia-Pacific supplier concentration with specialized display configurations for hybrid and electric platforms. These three entities represent distinct geographic anchoring strategies—European engineering heritage, North American OEM proximity, and Japanese OEM relationship depth—without implying specific market share or technology leadership claims.
| Leading Market Players |
|---|
| Continental AG |
| Visteon Corporation |
| Panasonic Holdings Corporation |
| Robert Bosch GmbH |
| Alpine Electronics, Inc. |
| Preh GmbH |
| Hyundai Mobis |
| Marelli Corporation |
| Magna International Inc. |
| Others |
Cost & Logistics Intelligence
Flexible OLED substrate manufacturing migration from glass to plastic base materials simultaneously compresses production costs and concentrates supplier power among Japanese and South Korean material providers. This dual transformation reshapes procurement economics for Tier-1 display integrators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates center stack display procurement. Price differentiation separates flexible OLED configurations from rigid LCD alternatives based on certification grade and volume scale. Pricing pressure stems from indium tin oxide cost volatility squeezing margins on mid-range touchscreen configurations. Fleet operators exhibit highest price sensitivity, while premium electric vehicle OEMs prioritize performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs mandate multi-supplier qualification for critical touch layer components. Manufacturing concentrates in Germany, Japan, and South Korea for display module assembly and flexible substrate production. Raw material dependencies center on indium tin oxide transparent conductors, polyimide substrates, and specialized optical films. Single-source vulnerability in flexible OLED substrate capacity creates geographic concentration risk. Distribution runs through Tier-1 bundled platform suppliers rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU General Safety Regulation driver-monitoring mandates by 2026 forcing hardware refresh cycles across European OEM programs.
For Market Incumbents: Hedge against indium tin oxide price volatility through backward integration into touch layer manufacturing or captive supply agreements with substrate providers. Defensive consolidation around software-hardware bundles protects margin position as OEMs eliminate separate display-controller RFQs. Capacity addition in Indian manufacturing clusters addresses emerging domestic OEM demand. For New Entrants and Emerging Players: The premium-economy price-point gap in mid-range electric vehicle displays offers accessible entry terrain. White space concentrates in India domestic OEM expansion and aftermarket retrofit channels for commercial vehicle fleets. Go-to-market positioning should emphasize ISO 26262 ASIL-B certification investment to bypass incumbent qualification barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional component fabricators lacking software stack integration. Long-term viability favors acquisition targets with cockpit domain controller platform capabilities and established OEM relationships. The signal to watch is NHTSA distracted-driving guideline tightening on touch-response latency caps, which would accelerate consolidation toward compliant integrated suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Decouples hardware refresh from model-year timelines, enabling over-the-air revenue streams. |
| Backward Integration into Touch Layers | Captive indium tin oxide supply hedges input cost volatility for mid-range configurations. |
| Geographic Manufacturing Footprint | Indian production addresses domestic OEM electrification roadmaps outside established clusters. |
| Platform Standardization | Single-source cockpit-electronics contracts replace discrete component sourcing in Germany and Japan. |
| Charging Infrastructure Partnership | Display-integrated charging status interfaces deepen electric vehicle platform embedding. |
Research Approach
Bottom-up electric vehicle platform modeling reconciled against top-down display module production tracking forms the analytical core of this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures cross-verified demand and supply estimates.
Input-output matrix framing connects propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster dimensions across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs include electric vehicle adoption curves, regulatory compliance timelines, and supplier capacity expansion announcements.
Caveats apply where indium tin oxide price volatility, NHTSA guideline revisions, or EU Green Deal mandate acceleration could materially shift the outlook. Deviation in flexible OLED substrate supply availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Commercial Touch Display Market
Display Technologies
Electroluminescent Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Display Control and Management System Market
Display Technologies
Gaming Monitors Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
3D Display Market
Display Technologies
Phosphor Screen Market
Display Technologies
Touch Screen Module Market
Display Technologies
Global Ferro Liquid Display Market
Display Technologies
Flexible Screens Market
Display Technologies
Global Monochrome Display Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
LCD Panel Market