
 Foldable Screens Market | 2026-2036
Foldable Screens Market Size, Share, and Industry Trends Forecast 2026-2036
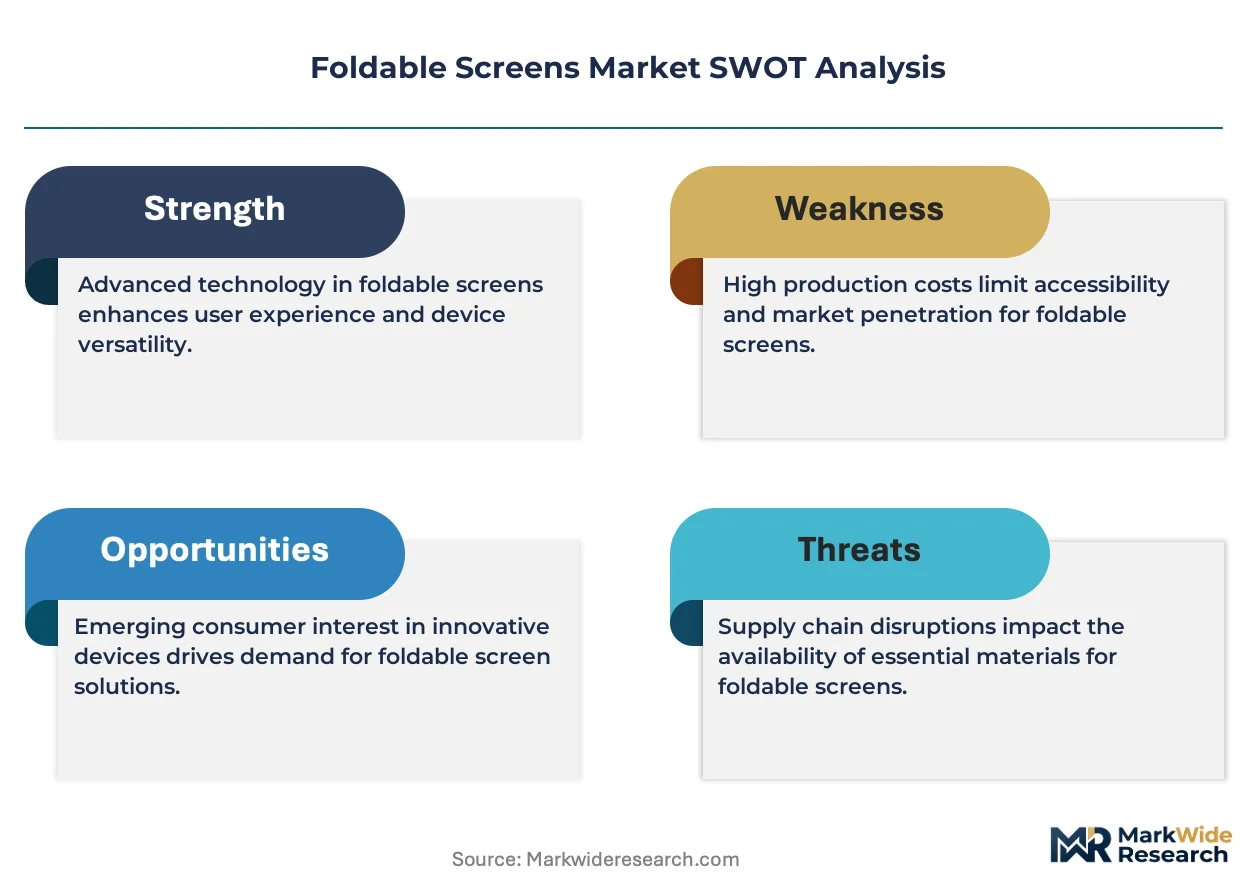
Foldable Screens Market Analysis
Software-defined display calibration is decoupling hardware sales from recurring revenue models. Samsung Electronics Co., Ltd. leverages its captive display supply to control premium smartphone pricing. BOE Technology Group Co., Ltd. competes aggressively on manufacturing scale in flexible OLED substrates. LG Display Co., Ltd. specializes in automotive-grade foldable prototypes for next-generation cockpit interfaces.
Foldable screens are electromechanical display assemblies built on polyimide or ultra-thin glass substrates with hinge-integrated pixel arrays, typically measuring under 100 micrometers in thickness to enable repeated bending cycles without luminance degradation. Their primary commercial purpose is to deliver expanded screen real estate within portable device form factors. Smartphones dominate current shipments, though laptops represent the fastest-growing form factor as Microsoft and PC OEMs validate Windows-on-foldable architectures. OLED technology anchors the value pool due to its self-emissive pixel structure and superior flexibility compared to backlit alternatives.
FCC equipment authorization rules govern electromagnetic emissions from foldable devices sold in the United States, while REACH compliance in Europe restricts hazardous substances in display adhesives and substrate coatings. South Korea's Ministry of Trade, Industry and Energy (METI-aligned standards via KATS) certifies mechanical durability for domestic foldable exports. Stakeholders must monitor how durability testing standards evolve as manufacturers push bend radius specifications below 1 millimeter.
Market Dynamics
Ultra-thin glass substrate breakthroughs from Corning and Schott AG are compressing crease visibility thresholds while extending mechanical fatigue cycles, fundamentally altering how display manufacturers qualify materials for premium tier deployment.
Growth Catalysts
- Self-emissive OLED pixel architectures:Elimination of backlight layers enables sub-100 micrometer thickness profiles essential for sub-1 millimeter bend radii in consumer electronics form factors.
- Windows-on-foldable validation:Microsoft and PC OEMs are certifying operating system adaptations for laptop-class foldable displays, expanding addressable device categories beyond smartphones.
- REACH substance restrictions:European hazardous substance limits in display adhesives and substrate coatings are accelerating migration toward fluorine-free barrier films and solvent-reduced coating processes.
Market Restraints
- Input cost volatility in polyimide substrates:Precursor chemical supply concentrates among Japanese and South Korean specialty polymer suppliers, creating margin pressure during feedstock price spikes.
- Ultra-thin glass yield limitations:Thickness profiles below 30 micrometers exhibit edge chipping rates that disqualify significant production volumes from premium tier qualification.
- Mechanical durability certification timelines:KATS-aligned METI standards require 200,000-cycle bend testing protocols that extend product validation schedules by 8-14 months.
Strategic Opportunities
- Automotive cockpit interface migration:LG Display prototypes for curved and foldable instrument panels target 2027-2028 model year deployments in luxury vehicle segments.
- Software-defined display calibration:Firmware-updateable color management and hinge-angle adaptive refresh rates enable recurring revenue attachment to hardware shipments.
- India PLI scheme incentives:Production-linked incentive frameworks for display manufacturing are attracting module assembly investments targeting domestic consumer electronics brands.
Industry Challenges
- Hinge-integrated pixel array engineering:Active matrix routing through dynamic flex regions requires specialized semiconductor design talent scarce outside South Korea and Taiwan.
- Barrier film deposition capex intensity:Multi-layer thin-film encapsulation systems demand vacuum cluster tools exceeding $40 million per production line.
- FCC equipment authorization complexity:Electromagnetic emissions testing for devices with moving conductive elements adds 6-10 weeks to US market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Screens Market |
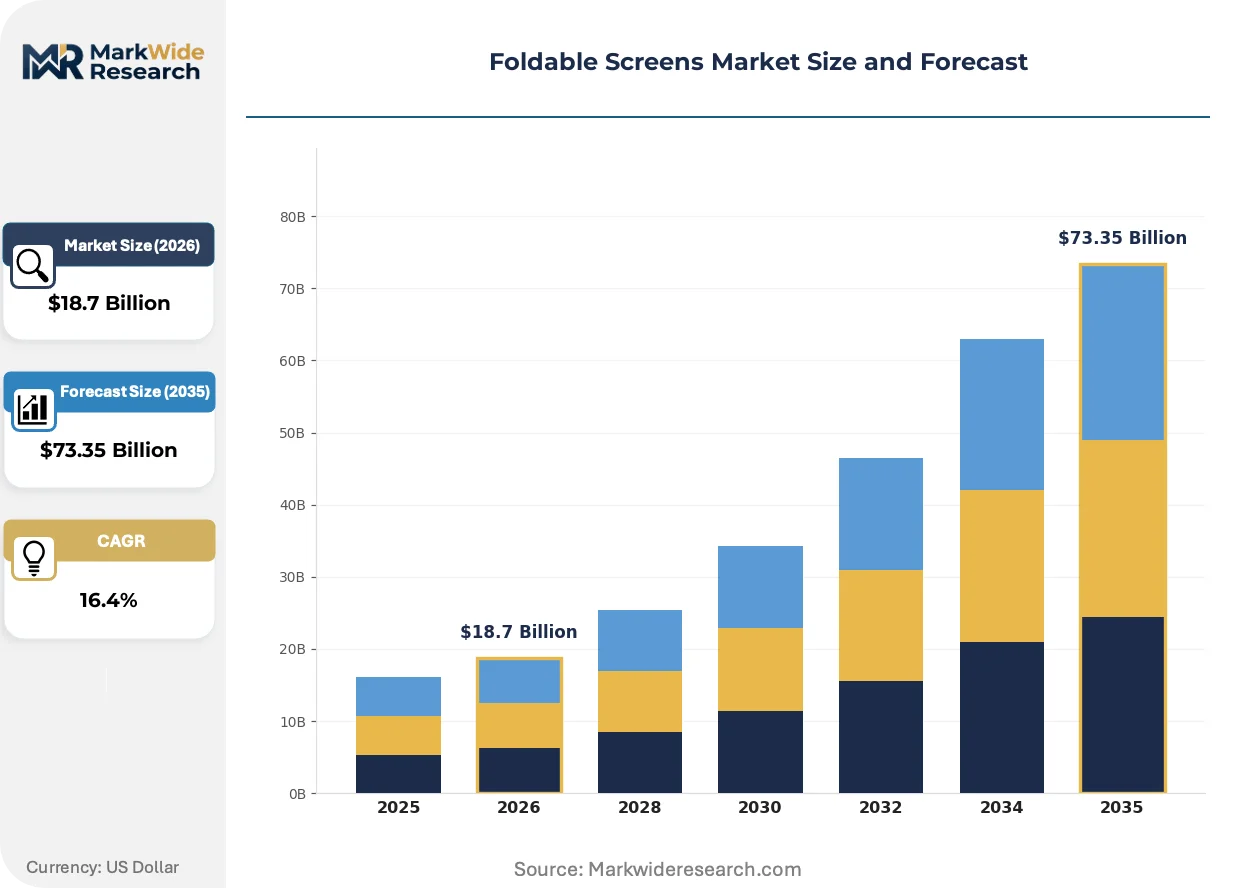
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form Factor: Smartphones, Tablets, Laptops, Wearables Technology: OLED, LCD, E Ink, MicroLED End User: Consumers, Enterprises, Educational Institutions, Designers Application: Entertainment, Education, Business, Design |
| Companies Covered | Samsung Electronics Co., Ltd., BOE Technology Group Co., Ltd., LG Display Co., Ltd., Visionox Technology, Inc., TCL China Star Optoelectronics Co., Ltd., Royole Corporation, AUO Corporation, Innolux Corporation, Tianma Microelectronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Screens Market Emerging Trajectories
Material science advances and regulatory pressure on substance composition are converging to redefine manufacturing process flows and supplier qualification criteria across the foldable display value chain.
Ultra-thin glass with chemically strengthened edges is rewriting durability benchmarks for premium smartphone tiers. Samsung Display and BOE Technology Group are qualifying substrates below 50 micrometers for 2025 device generations. This substrate transition is compressing polyimide-dependent supply relationships and shifting value capture toward glass chemistry specialists.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of barrier film adhesives used in flexible OLED stacks. European display importers must certify fluorine-free alternatives by 2026. Automotive-grade foldable prototypes face the most acute compliance pressure given longer qualification cycles and stricter material documentation requirements.
Enterprise procurement of foldable laptops is concentrating through direct OEM relationships rather than distributor channels. Microsoft Surface and Lenovo ThinkPad commercial divisions are bypassing traditional PC wholesale networks for fleet deployments above 500 units. North American and Western European enterprise segments exhibit the strongest channel compression as IT departments prioritize unified endpoint management integration over hardware sourcing flexibility.
Foldable Screens Market Segmentation
Foldable screen segmentation reveals how substrate thickness and hinge mechanics dictate device category viability. Form factor and technology choices determine whether panels serve standalone consumer products or embedded automotive cockpit systems.
Form Factor:
Integration depth varies sharply across device categories, with smartphones operating as fully standalone systems while laptop displays embed within complex thermal and structural chassis assemblies.
- Smartphones:Clamshell and book-style foldables dominate commercial shipments, leveraging polyimide or ultra-thin glass substrates under 100 micrometers. Samsung Display's dedicated fabrication complex in South Korea anchors supply for premium tier handsets targeting consumer replacement cycles.
- Laptops:Windows-on-foldable validation by Microsoft and PC OEMs is accelerating 13-17 inch panel qualification for enterprise fleet deployments. These panels integrate hinge-angle adaptive refresh rates and require more complex active matrix routing through dynamic flex regions than handheld devices.
- Tablets:Mid-size foldables bridge entertainment consumption and light productivity use cases.
- Wearables:Wrist-worn and head-mounted applications demand the most aggressive bend radius specifications below 1 millimeter.
Volume placements concentrate in smartphones; the faster expansion belongs to laptops.
Technology:
Cost tier stratification separates self-emissive architectures from backlit alternatives, with premium positioning commanding specialized semiconductor design talent and vacuum cluster tool investments exceeding $40 million per production line.
- OLED:Self-emissive pixel structures eliminate backlight layers entirely, enabling sub-100 micrometer thickness profiles essential for sub-1 millimeter bend radii. This technology anchors the value pool due to superior flexibility and luminance stability across repeated bending cycles.
- LCD:Backlight-dependent architectures face inherent thickness constraints that disqualify them from sub-5 millimeter bend radius applications in premium consumer electronics.
- E Ink:Bistable electrophoretic displays serve low-refresh applications where power efficiency outweighs color gamut requirements.
- MicroLED:Chiplet-based architectures promise superior brightness and longevity but await manufacturing scale breakthroughs for flexible substrates.
Margin capture clusters in OLED; E Ink holds the steepest expansion trajectory in specialized industrial wearables.
End User:
Customer type determines procurement channel structure, with enterprise segments bypassing traditional distributor networks for direct OEM relationships above 500-unit fleet thresholds.
- Consumers:Individual purchasers drive replacement-cycle demand through retail and carrier channels, with premium tier qualification standards filtering substrate selection toward ultra-thin glass below 50 micrometers.
- Enterprises:IT departments prioritize unified endpoint management integration, concentrating procurement through Microsoft Surface and Lenovo ThinkPad commercial divisions with compressed wholesale margins.
- Educational Institutions:Budget-constrained volume purchasers favor standard-tier specifications with extended warranty terms.
- Designers:Creative professionals demand color-accurate, large-format foldables for portable studio workflows.
Enterprise direct procurement is gaining share fastest; consumer retail maintains absolute volume dominance.
Application:
Maturity gradients separate entertainment-focused mass market deployment from design applications requiring specialized calibration firmware and professional color management certifications.
- Entertainment:Streaming-optimized displays prioritize HDR luminance and crease minimization for video consumption, with South Korean and Chinese consumer electronics brands driving panel specifications.
- Business:Productivity applications demand multitasking-optimized aspect ratios and stylus compatibility, with enterprise security requirements influencing touch controller selection.
- Education:K-12 and higher education deployments emphasize durability certification and repairability over premium specifications.
- Design:Professional creative workflows require factory-calibrated color accuracy and hinge-angle adaptive refresh rates for stylus input precision.
Entertainment commands current volume; design applications show the steepest specification escalation toward professional-tier pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in South Korea and China, while consumption spreads across North America, Europe, and Asia-Pacific. This geographic split shapes investment flows and regulatory compliance strategies. Display fabricators must navigate multiple certification regimes simultaneously.
South Korea
Samsung Display operates the world's largest dedicated foldable OLED fabrication complex, supplying premium smartphone panels to domestic and international OEMs. The Ministry of Trade, Industry and Energy enforces KATS-aligned METI standards requiring 200,000-cycle bend testing for export certification. Gyeonggi-do province hosts the concentrated supply ecosystem, with component vendors clustering around Samsung's display fabs in Asan and Tangjeong.
China
BOE Technology Group and TCL China Star Optoelectronics drive manufacturing scale in flexible OLED substrates, serving both domestic brands and export markets. MIIT oversees GB standards compliance for electromagnetic emissions and mechanical durability. The Yangtze River Delta and Pearl River Delta contain the principal industrial clusters, with Chengdu and Wuhan emerging as secondary display manufacturing hubs.
United States
Enterprise fleet procurement of foldable laptops concentrates through direct OEM relationships, with IT departments prioritizing unified endpoint management integration. FCC equipment authorization rules govern electromagnetic emissions testing for devices with moving conductive elements. California and Texas host the primary demand centers, with Seattle and Redmond anchoring Microsoft's Windows-on-foldable validation programs.
Germany
Automotive OEMs source foldable cockpit prototypes from Asian suppliers for 2027-2028 luxury vehicle model years. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of barrier film adhesives in imported display stacks. Baden-Württemberg's Stuttgart region and Bavaria's Munich corridor concentrate automotive R&D partnerships between OEMs and display technology providers.
Japan
Precursor chemical suppliers for polyimide substrates concentrate among domestic specialty polymer manufacturers, creating feedstock dependencies for Korean and Chinese display fabricators. METI coordinates industrial policy supporting materials science innovation in flexible electronics. Kyushu and the Kansai region host the principal chemical production facilities supplying foldable display supply chains.
Foldable Screens Market Vendor Landscape
Top-tier vendors anchor premium-tier supply through captive fabrication complexes, while mid-scale specialists compete on manufacturing scale and cost positioning. The market structure consolidates around three to four dominant substrate suppliers with multi-billion dollar production investments. Strategic archetypes include integrated electronics conglomerates with display divisions, independent panel specialists, and emerging Chinese scale players. Capacity expansion and strategic technology licensing represent the dominant competitive moves as firms position for laptop and automotive form factor growth.
Within the integrated conglomerate tier, Samsung Electronics Co., Ltd. and LG Display Co., Ltd. exemplify South Korean market presence through their corporate structures and geographic positioning. BOE Technology Group Co., Ltd. occupies a position representing Chinese manufacturing scale in flexible OLED substrates. These three entities collectively illustrate the competitive tension between captive supply integration and independent panel sourcing strategies that defines current market dynamics.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| LG Display Co., Ltd. |
| Visionox Technology, Inc. |
| TCL China Star Optoelectronics Co., Ltd. |
| Royole Corporation |
| AUO Corporation |
| Innolux Corporation |
| Tianma Microelectronics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Ultra-thin glass substrate migration below 50 micrometers is simultaneously compressing manufacturing yields and concentrating supply relationships around Corning and Schott AG chemistry specialists, reshaping how display fabricators negotiate input costs and qualify alternative suppliers.
Pricing Analysis
Margin tightening in premium smartphone tiers reflects yield disqualification rates for glass substrates below 30 micrometers that fail KATS-aligned mechanical durability certification. Three-tier pricing structure across premium, standard, and economy levels separates ultra-thin glass-qualified panels from polyimide-dependent alternatives from LCD-backlit architectures. Pricing pressure stems from Japanese and South Korean specialty polymer suppliers concentrating precursor chemical feedstock. Educational institutions exhibit highest price sensitivity; enterprise fleet purchasers prioritize unified endpoint management integration over unit cost.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are attracting module assembly investments that reshape sourcing patterns for display stack integration. Manufacturing gravity centers on South Korea, China, and Japan, with Gyeonggi-do province and the Yangtze River Delta hosting concentrated fabrication ecosystems. Raw material dependencies include polyimide precursor chemicals, ultra-thin glass substrates, and multi-layer thin-film encapsulation barrier films. Single-source vulnerability concentrates in Japanese specialty polymer suppliers feeding Korean and Chinese fabricators. Distribution runs through direct OEM relationships for enterprise laptop fleets above 500 units, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII fluorine-free reformulation deadlines erect a cost-of-compliance barrier that advantages incumbents with validated alternative adhesive chemistries and multi-year automotive qualification cycles already underway.
For Market Incumbents: To counter BOE Technology Group's manufacturing scale aggression in flexible OLED substrates, Samsung Display should deepen captive supply integration through in-house production of chemically strengthened edge treatment systems. Certification investment in KATS-aligned 200,000-cycle bend testing protocols extends validation moats against emerging Chinese scale players seeking automotive cockpit entry. For New Entrants and Emerging Players: Mid-tier educational procurement represents the most penetrable buyer archetype given budget-constrained volume purchasing patterns and extended warranty prioritization over premium specifications. White-space targets include India PLI scheme module assembly for domestic consumer electronics brands and fluorine-free barrier film adhesive formulation for European REACH compliance. Go-to-market positioning should emphasize repairability certification and standard-tier durability at compressed wholesale margins. For Investors and Strategic Acquirers: Re-rating potential sits with automotive-grade foldable specialists given LG Display's 2027-2028 luxury vehicle cockpit prototype timeline and longer qualification cycle lock-in effects. Long-term viability framing favors firms with demonstrated hinge-integrated pixel array engineering talent and vacuum cluster tool deployment exceeding $40 million per production line. Signal to watch: Windows-on-foldable enterprise fleet deployment acceleration above 500-unit direct procurement thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-thin Glass Qualification | Corning and Schott AG chemistry partnerships displace polyimide-dependent supply relationships in premium tiers. |
| Fluorine-free Adhesive Reformulation | REACH Annex XVII compliance secures European automotive import certification ahead of 2026 deadlines. |
| Hinge-angle Adaptive Refresh Firmware | Software-defined calibration enables recurring revenue attachment to laptop-class hardware shipments. |
| Automotive Cockpit Prototype Development | LG Display's curved instrument panel validation targets luxury OEM 2027-2028 model year deployment slots. |
| India PLI Module Assembly Investment | Production-linked incentives attract display stack integration for domestic consumer electronics brand supply. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with display fabrication engineers, automotive Tier 1 procurement leads, enterprise IT fleet managers, and semiconductor design specialists. Secondary sources included FCC equipment authorization databases, KATS certification registries, REACH Annex XVII substance restriction notices, and MIIT GB standards documentation. Bottom-up panel shipment triangulation against top-down consumer electronics brand revenue attribution validated market sizing.
Data-stream reconciliation across form factor, technology architecture, and end-user procurement channel dimensions shaped the analytical framework over the projection horizon. Modeled segmentation spanned substrate material, hinge mechanism complexity, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted replacement cycle assumptions and enterprise fleet penetration scenarios. Industry-specific forecast inputs included Windows-on-foldable validation timelines and automotive cockpit prototype qualification schedules.
Revisions become necessary when KATS durability testing protocols extend cycle requirements, REACH substance restrictions expand to additional fluorinated compounds, or polyimide precursor supply disruptions alter feedstock economics. Forecasts reflect documented assumptions regarding yield improvement trajectories for sub-50 micrometer glass substrates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Collaboration Display Market
Display Technologies
Global Portable Monitor Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
Touch Screen Film Market
Display Technologies
3D Holographic Display Market
Display Technologies
Dot Matrix Display Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Europe Transparent Conductive Films Market
Display Technologies
Holographic Display Market
Display Technologies
MEMS Microdisplay Market
Display Technologies
Smartphone Display Market
Display Technologies
Tablets and Notebook Display Market
Display Technologies
Vietnam Displays Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Surface-Conduction Electron-Emitter Display (SED) Market
Display Technologies
Touch Screen Module Market