
 Disaster Recovery As a Service (Draas) Market | 2026-2036
Disaster Recovery As a Service (Draas) Market Size, Share, and Industry Trends Forecast 2026-2036
Disaster Recovery As a Service (Draas) Market Intelligence
The unbundling of comprehensive DRaaS suites into modular, pay-as-you-go offerings for backup and replication is repositioning buyer choice away from monolithic contracts. Amazon Web Services leverages its vast infrastructure to provide granular, scalable recovery services. Microsoft Corporation integrates its Azure Site Recovery solution directly into its broader cloud ecosystem. Veeam Software Inc. specializes in backup and replication, competing through partnerships with multiple cloud providers.
Disaster Recovery as a Service (DRaaS) involves the replication and hosting of an organization's computing infrastructure in a secure, third-party data center. The service ensures business continuity by orchestrating failover to meet predefined Recovery Time Objectives (RTOs) and Recovery Point Objectives (RPOs). Cloud-based deployment models represent the largest share, offering scalability and reduced capital expenditure for users. Small and Medium Enterprises constitute the fastest-growing end-user segment, attracted by the operational expense model of DRaaS.
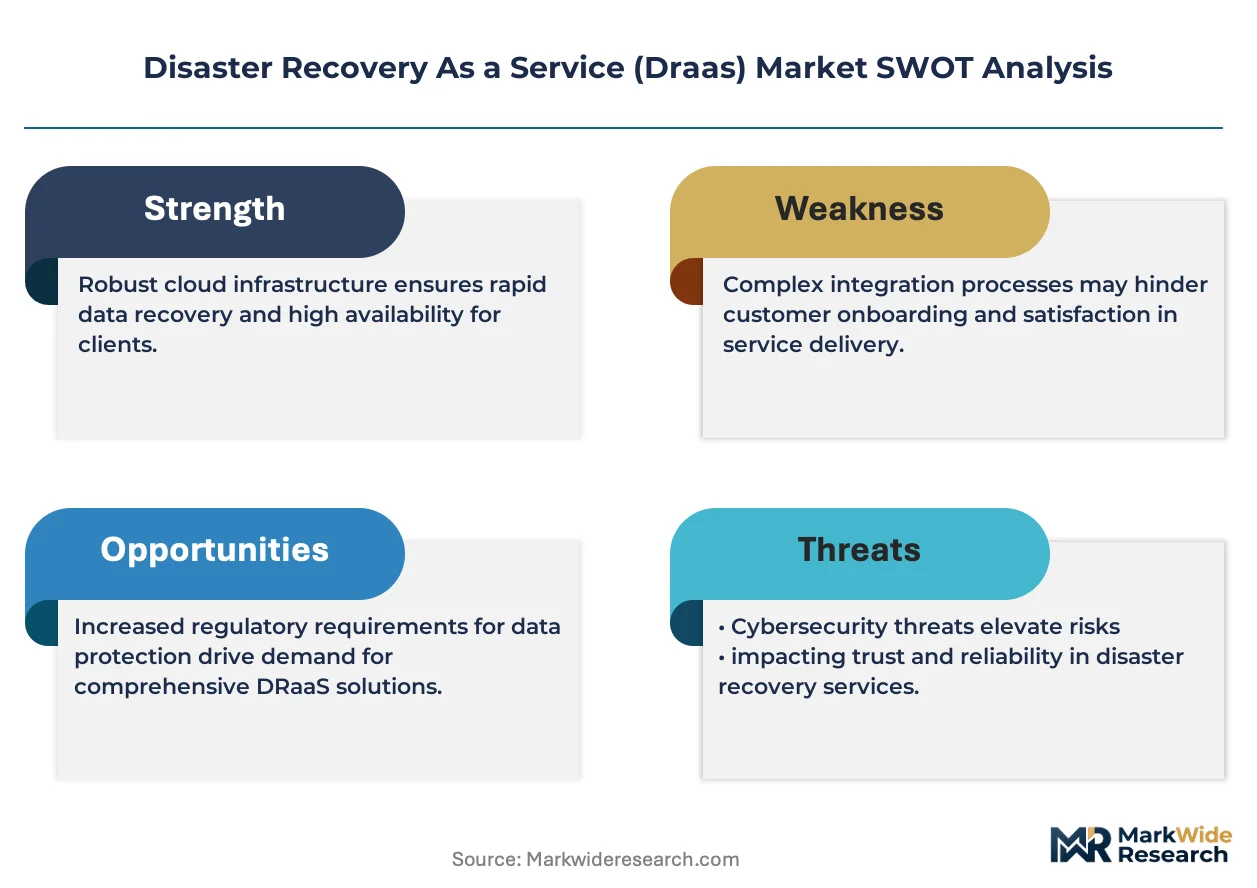
Data protection mandates like Europe's GDPR and the US HIPAA directly compel organizations to implement verifiable data recovery plans. Data sovereignty requirements enforced by regulators in countries like China and India also influence the geographic placement of recovery infrastructure. Stakeholders must now balance the need for low-latency recovery with the complexities of multi-cloud architectures and evolving compliance landscapes.
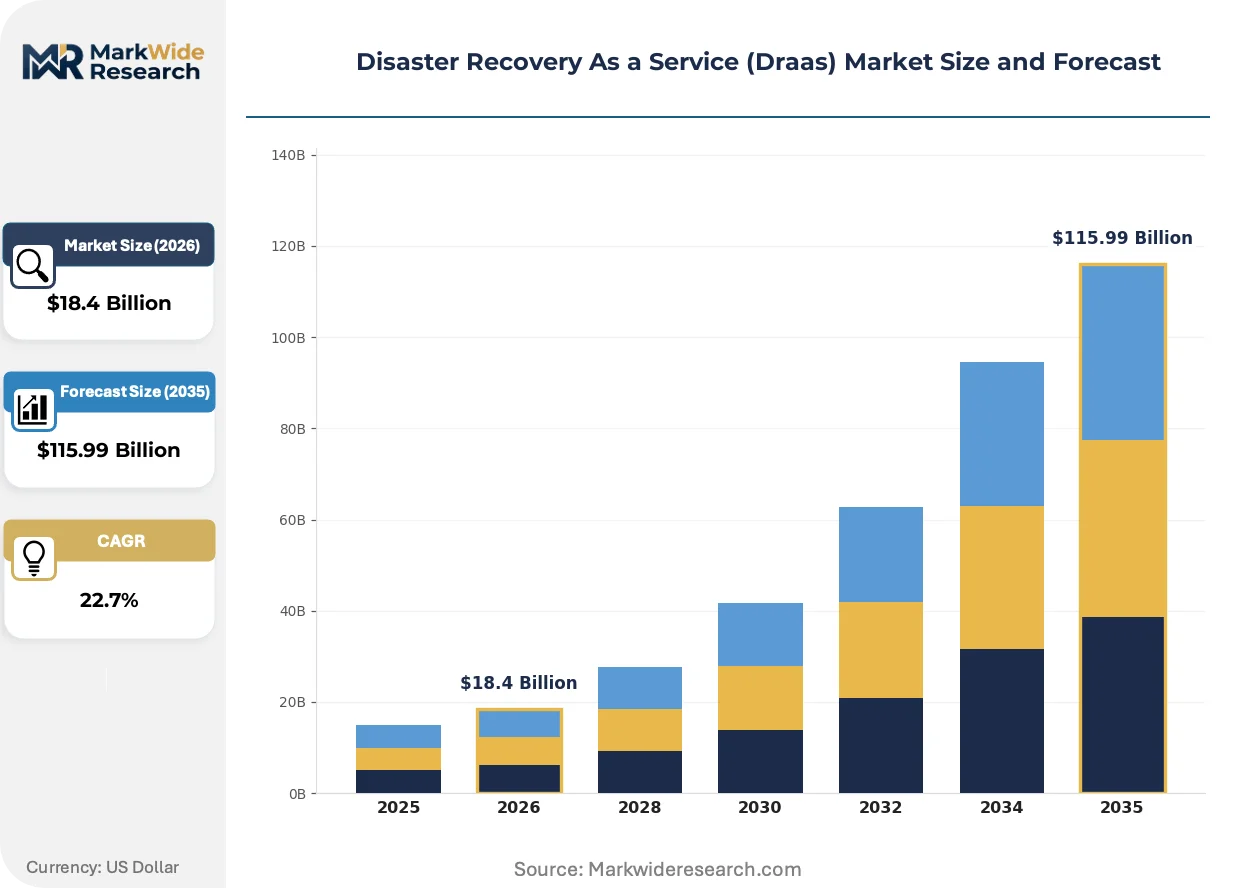
Market Dynamics
The fundamental tension between stringent, geographically specific data protection mandates and the architectural shift toward modular, cloud-native services defines the DRaaS market. This dynamic forces providers to balance standardized, scalable offerings with the need for customized compliance and data sovereignty solutions.
Growth Catalysts
- Regulatory Mandates:Data protection regulations like Europe's GDPR and the US HIPAA compel organizations to implement and test verifiable disaster recovery plans, directly driving demand for compliant DRaaS solutions.
- Financial Services Adoption:The highly regulated financial services sector requires resilient data handling and minimal downtime, making it a primary adopter of DRaaS to meet stringent business continuity and regulatory requirements.
- SME Accessibility:The operational expense model of cloud-based DRaaS lowers the barrier to entry for Small and Medium Enterprises, which previously could not afford the capital expenditure of traditional disaster recovery sites.
Market Restraints
- Multi-Cloud Complexity:Orchestrating failover and ensuring consistent Recovery Point Objectives across disparate public and private cloud environments introduces significant technical complexity and management overhead for users.
- Data Sovereignty Laws:Regulations in countries like China and India requiring data to be stored and processed within national borders complicate DRaaS architecture for multinational corporations and increase operational costs.
- Cost Predictability:While pay-as-you-go models are attractive, the potential for high, unpredictable data egress and compute costs during a large-scale disaster event or extensive testing presents a budget risk.
Strategic Opportunities
- Workload-Specific DR:Developing specialized DRaaS offerings tailored for modern application architectures, such as Kubernetes clusters and serverless computing, addresses an emerging and underserved market segment.
- Integrated Cyber Resilience:Combining DRaaS with ransomware detection and automated recovery capabilities creates a high-value service that addresses both data availability and security threats in a unified platform.
- Geographic Expansion:Targeting underpenetrated markets in Southeast Asia and Latin America, where cloud adoption is accelerating but mature DRaaS solutions are less common, offers significant growth potential for providers.
Industry Challenges
- Talent Scarcity:A persistent shortage of IT professionals with the combined expertise in cloud architecture, networking, and disaster recovery orchestration hinders adoption and effective management of sophisticated DRaaS solutions.
- Legacy System Integration:Connecting modern cloud-based recovery platforms with aging on-premise mainframe or AS/400 systems poses a significant technical and operational challenge for established enterprises in their modernization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disaster Recovery As a Service (Draas) Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $115.99 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Private Cloud, Managed Recovery Solution Offering: Backup and Restore, Replication, Continuous Data Protection, Data Archiving, Failover Management Application: Financial Services, Manufacturing, Telecommunication, Government Agencies, Education End User: Small and Medium Enterprises, Large Enterprises, Managed Service Providers, System Integrators |
| Companies Covered | Microsoft Corporation, IBM Corporation, Amazon Web Services, VMware Inc., Hewlett Packard Enterprise, Recovery Point Systems, Acronis International GmbH, Cisco Systems Inc, Veeam Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disaster Recovery As a Service (Draas) Market Strategic Shifts & Innovations
The industrialization of recovery services is transforming the market. A move away from bespoke, project-based disaster recovery toward automated, productized, and consumption-based models is lowering costs and expanding access to enterprise-grade resilience for a wider range of organizations.
Automated Orchestration Platforms
Automation and orchestration software provides the central nervous system for modern DRaaS. Small and Medium Enterprises and large enterprises alike are adopting these platforms to reduce manual intervention and guarantee adherence to Recovery Time Objectives. This technology is consolidating previously siloed backup, replication, and failover management tools into a unified, software-defined control plane.
Data Sovereignty and In-Country Clouds
Data localization requirements, such as those enforced by regulators in India, are a powerful force. This directly compels DRaaS providers and their hyperscale partners to invest in building in-country data center infrastructure to offer compliant services. Multinational clients operating in these jurisdictions must adapt their global DR strategies to accommodate these local data residency rules.
Unbundling of DR Services
A clear shift is occurring from all-inclusive DRaaS suites toward the consumption of discrete, modular services. This unbundling of offerings allows customers to abandon monolithic contracts in favor of assembling best-of-breed solutions for backup, replication, and failover from different vendors. The trend is most pronounced in the SME segment, which prioritizes the flexibility and lower initial investment of this pay-as-you-go approach.
Disaster Recovery As a Service (Draas) Market Segmentation
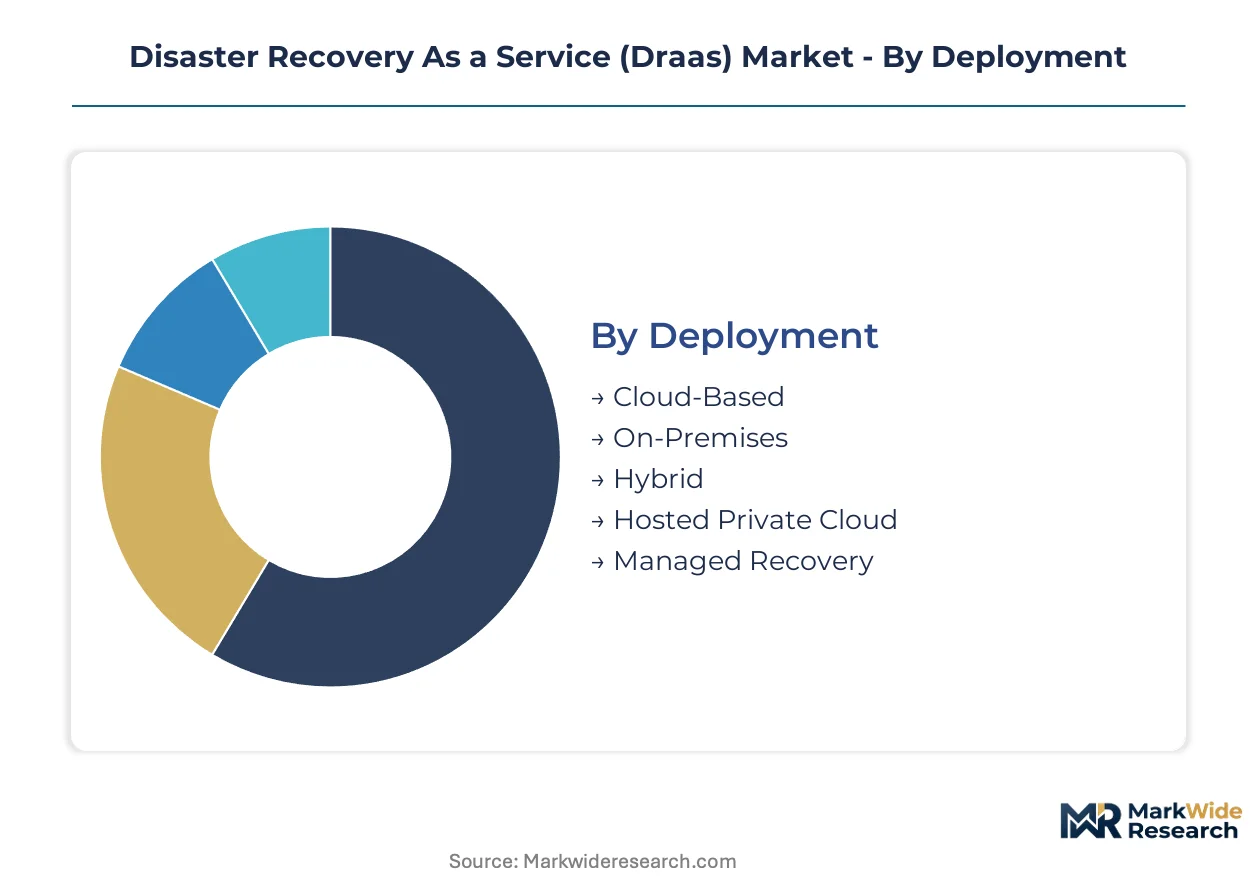
The Disaster Recovery as a Service (DRaaS) market segments across key operational dimensions, reflecting diverse deployment models, solution capabilities, application requirements, and end-user profiles. Understanding these distinctions clarifies how providers deliver resilient data handling and business continuity solutions to a varied customer base.
Deployment:
Supply concentration in DRaaS deployment models increasingly favors cloud-native and hybrid approaches, driven by scalability and cost-efficiency considerations.
- Cloud-Based:This model leverages public cloud infrastructure for replication, storage, and recovery, offering on-demand scalability and reduced capital expenditure. Demand is concentrating in the United States, driven by hyperscale provider investments and robust regulatory frameworks like HIPAA.
- Hybrid:Combining on-premise infrastructure with cloud resources, this model provides flexibility for organizations managing sensitive data or legacy systems. Demand is concentrating in Europe, where data sovereignty concerns influence the blend of local and cloud-based recovery sites.
- On-Premises:Organizations maintain their own recovery infrastructure within their physical facilities, offering maximum control and security.
- Hosted Private Cloud:A third-party provider manages dedicated cloud infrastructure for a single organization, offering enhanced isolation and performance.
- Managed Recovery:A provider fully manages the DRaaS solution, including planning, implementation, testing, and failover orchestration.
Today's leader: Cloud-Based. Tomorrow's challenger: Hybrid.
Solution Offering:
The range of DRaaS solution offerings addresses specific aspects of data protection and business continuity, catering to varied recovery objectives across different application types.
- Replication:This core capability involves continuously copying data and virtual machines from primary to secondary locations, ensuring minimal data loss during outages. Demand is concentrating in the financial services sector, where stringent RPO targets necessitate near real-time data synchronization.
- Failover Management:This service orchestrates the automated or semi-automated transfer of operations to the recovery site during a disaster, ensuring adherence to RTOs. Demand is concentrating among large enterprises seeking to reduce manual intervention and human error in complex recovery scenarios.
- Backup and Restore:This foundational offering creates copies of data at regular intervals, enabling recovery from data loss events.
- Continuous Data Protection:This advanced method captures every change to data, allowing recovery to any point in time.
- Data Archiving:Long-term storage of historical data for compliance, legal, or analytical purposes, often with lower access frequency.
The most critical offering is Replication, forming the bedrock of rapid recovery strategies.
Application:
Distinct application segments drive specific DRaaS requirements, with each industry vertical demanding tailored recovery capabilities aligned with its operational and regulatory landscape.
- Financial Services:This highly regulated sector requires robust, verifiable disaster recovery plans to maintain transactional integrity and meet stringent compliance mandates like GDPR. Demand is concentrating in major financial hubs like New York and London, driven by the need for continuous service availability.
- Telecommunication:Critical infrastructure and continuous service delivery necessitate advanced DRaaS solutions for network stability and customer connectivity. Demand is concentrating in countries with rapidly expanding digital economies, such as India, where network uptime is paramount.
- Manufacturing:Operational technology (OT) and enterprise resource planning (ERP) systems require protection to prevent production downtime and supply chain disruptions.
- Government Agencies:Public sector entities require secure and compliant DRaaS to protect citizen data and ensure continuity of essential services.
- Education:Institutions utilize DRaaS to protect student records, research data, and learning platforms from outages.
Financial Services remains the segment with the most stringent recovery demands.
End User:
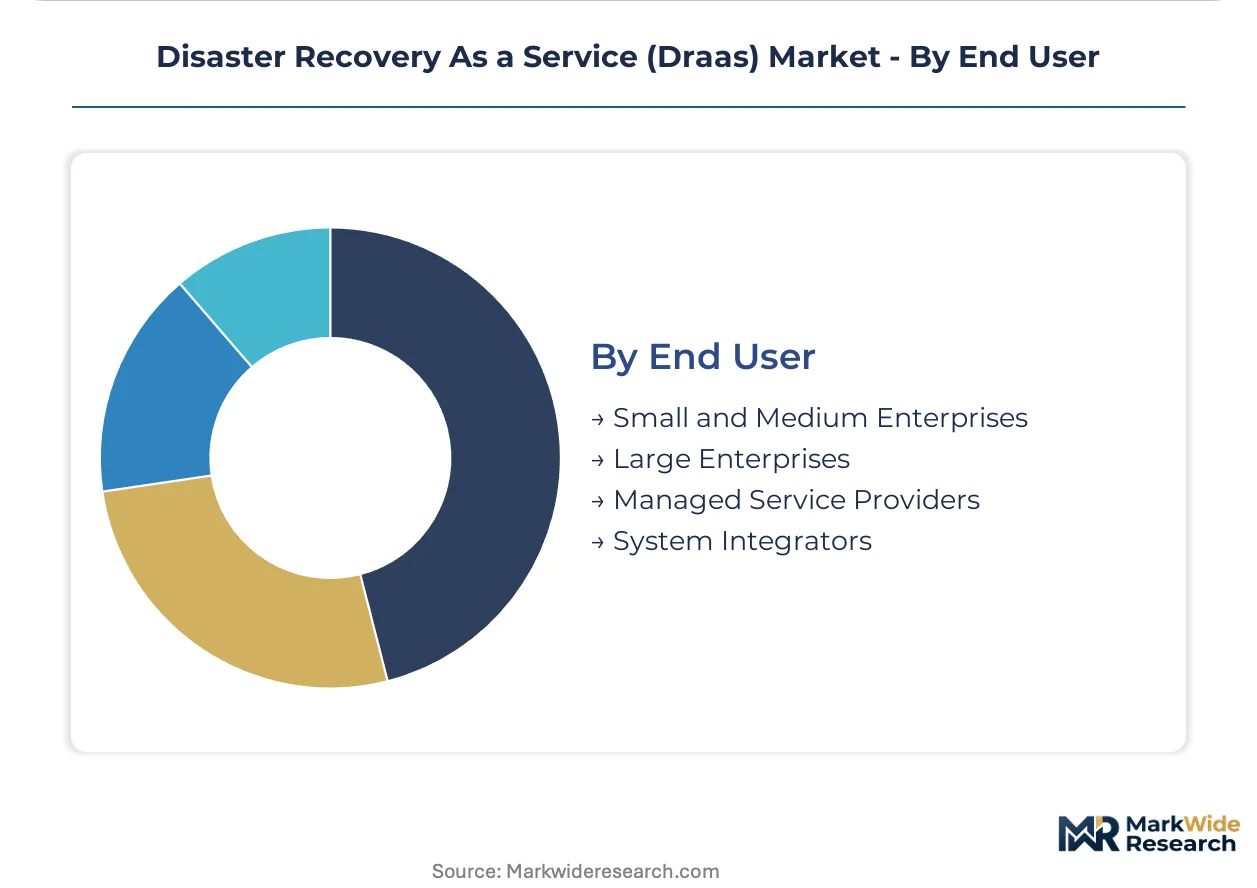
DRaaS end-user segments exhibit varying needs regarding cost structures, management complexity, and required service levels, influencing provider engagement models.
- Small and Medium Enterprises:Attracted by the operational expense model and reduced capital outlay, SMEs increasingly adopt DRaaS for enterprise-grade resilience. This segment represents the fastest-growing trajectory, driven by the accessibility of cloud-based solutions.
- Large Enterprises:These organizations require complex, scalable DRaaS solutions to protect vast, distributed IT environments and integrate with legacy systems. Demand is concentrating among multinational corporations balancing global operations with data sovereignty requirements.
- Managed Service Providers:MSPs leverage DRaaS to offer enhanced data protection and business continuity services to their own client base.
- System Integrators:SIs incorporate DRaaS into broader IT infrastructure projects, providing comprehensive solutions to their enterprise customers.
SMEs are rapidly expanding their adoption of DRaaS solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Disaster Recovery as a Service market's foundational growth began in the United States, driven by early cloud adoption and stringent regulatory environments. This market has since expanded globally, with diverse regional demands influenced by local data protection laws and the pace of digital transformation. Providers now balance standardized offerings with specific in-country compliance requirements.
United States
Demand for DRaaS in the United States is propelled by the rapid adoption of cloud infrastructure and the critical need for business continuity across all sectors. Federal regulations like HIPAA and the financial sector's FINRA rules compel organizations to implement robust data recovery plans. Key data center clusters in states like Virginia, Texas, and California concentrate DRaaS deployments, serving a vast enterprise and SME customer base.
Germany
Germany's DRaaS market is shaped by strong data privacy concerns and the country's highly regulated financial and industrial sectors. Regulations such as GDPR and national data protection laws mandate secure and localized data handling. Major economic centers like Frankfurt and Munich see significant investment in hybrid cloud DRaaS solutions, catering to enterprises balancing cloud flexibility with local compliance.
India
India represents a rapidly expanding market for DRaaS, fueled by its burgeoning digital economy and increasing cloud adoption across enterprises and SMEs. Data sovereignty laws, including those from the Reserve Bank of India, require data to be stored and processed within national borders. Technology hubs in Bangalore, Hyderabad, and Pune are witnessing substantial growth in local cloud infrastructure to support compliant DRaaS offerings.
Canada
Canada's DRaaS market benefits from its close economic ties to the United States and a growing focus on data resilience in critical infrastructure sectors. Provincial and federal privacy laws, such as PIPEDA, influence the design and deployment of recovery solutions. Major metropolitan areas like Toronto, Montreal, and Vancouver serve as key nodes for DRaaS provision, particularly for organizations seeking secure, in-country data replication.
United Kingdom
The United Kingdom's DRaaS market is characterized by a mature financial services sector and a strong emphasis on regulatory compliance post-Brexit. GDPR and sector-specific mandates from the Financial Conduct Authority (FCA) drive demand for verifiable recovery capabilities. London remains a critical hub for DRaaS providers, supporting financial institutions and other large enterprises with low-latency recovery solutions.
Disaster Recovery As a Service (Draas) Market Key Industry Players
Premium-margin players sit above commodity-margin players across service complexity and regulatory adherence within the DRaaS market. This tiered structure includes hyperscale cloud providers offering foundational infrastructure, specialized software vendors delivering backup and replication tools, and managed service providers offering end-to-end solutions. Strategic partnerships between these archetypes and continuous portfolio diversification represent dominant competitive moves.
Hyperscale cloud providers like Amazon Web Services and Microsoft Corporation exemplify the infrastructure-as-a-service model, leveraging their vast global networks for scalable recovery options. Veeam Software Inc. occupies a position as a specialized software vendor, focusing on backup and replication solutions that integrate with various cloud platforms. These companies represent distinct approaches to delivering disaster recovery capabilities, from broad cloud ecosystems to focused data protection software.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| VMware Inc. |
| Hewlett Packard Enterprise |
| Recovery Point Systems |
| Acronis International GmbH |
| Cisco Systems Inc |
| Veeam Software Inc. |
| Others |
Cost & Logistics Intelligence
Captive data center infrastructure, often managed in-house or by a dedicated provider, anchors both the supply position for disaster recovery services and the pricing power for specialized solutions. This integration choice allows organizations to maintain control over sensitive data and ensure compliance with stringent regulatory frameworks like GDPR.
Pricing Analysis
Consumption-based pricing models dominate the DRaaS market, allowing customers to pay for resources used, including storage, compute, and data transfer. Price differentiation stems from the level of automation and the guaranteed Recovery Time Objective (RTO), with faster RTOs commanding premium rates. Pricing pressure stems from hyperscale cloud providers offering foundational infrastructure at competitive rates. Small and Medium Enterprises (SMEs) exhibit the highest price sensitivity, preferring flexible, pay-as-you-go options to avoid large capital outlays.
Supply Chain Analysis
Data localization mandates, such as those enforced by India's Reserve Bank of India, significantly reshape sourcing strategies for DRaaS providers. Geographic supply concentration centers on key data center clusters within the United States, Germany, and India. The market relies on robust fiber optic networks and high-availability server hardware as critical component dependencies. A structural supply chain risk involves single-source vulnerability for specialized hardware or software components. Distribution runs through direct sales teams and a robust network of Managed Service Providers (MSPs) and System Integrators (SIs).
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DRaaS market offers a geographic-arbitrage play, as providers can leverage lower operational costs in some regions to offer competitive services while meeting stringent data sovereignty requirements in others.
For Market Incumbents: Anticipate continued demand for hybrid cloud solutions as enterprises balance legacy systems with cloud adoption. Consolidate market share through strategic acquisitions of specialized software vendors offering advanced replication and orchestration capabilities. Address the talent scarcity threat by investing in comprehensive training programs for cloud and DRaaS professionals. Leverage existing customer relationships to cross-sell integrated cyber resilience platforms.
For New Entrants and Emerging Players: Launch via strategic partnerships with regional Managed Service Providers to access established customer bases in underpenetrated markets like Southeast Asia. Target workload-specific DRaaS offerings for modern application architectures, such as Kubernetes clusters, which represent a significant white-space opportunity. Focus on the Small and Medium Enterprise segment in emerging economies, offering simplified, cost-effective, and automated recovery solutions with clear pricing structures. Emphasize ease of deployment and management as a key go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized DRaaS software providers because the market is experiencing unbundling of services, creating opportunities for consolidation of best-of-breed solutions. The long-term viability of the DRaaS market remains strong, driven by persistent regulatory mandates and the increasing cost of downtime. Focus on acquisition targets with strong intellectual property in automated orchestration platforms or integrated cyber resilience capabilities. The signal to watch for accelerated M&A activity is a further tightening of data sovereignty regulations across multiple key geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Cyber Resilience | Expands revenue streams by addressing both data availability and security threats for enterprise clients. |
| Geographic Expansion into Southeast Asia | Captures new customer segments in rapidly digitizing economies with growing cloud adoption. |
| Development of Workload-Specific DRaaS | Addresses the specialized recovery needs of modern cloud-native applications like Kubernetes. |
| Strategic Partnerships with Hyperscalers | Leverages vast infrastructure and market reach of major cloud providers for broader service delivery. |
| Investment in Automated Orchestration R&D | Reduces manual intervention and improves Recovery Time Objectives for all customer segments. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the DRaaS market. Primary research included in-depth discussions with CTOs, IT procurement officers, cloud architects, and regulatory compliance specialists. This primary data was validated against secondary sources, including SEC filings, industry association reports, and official government technology mandates, ensuring robust bottom-up and top-down triangulation.
The comparable-period framing anchored the forecast window to established historical reference periods, allowing for consistent trend analysis and projection. The analytical framework modeled key segmentation dimensions, including deployment model, solution offering, application, end-user, and regional regulatory compliance frameworks. Compound Annual Growth Rates (CAGRs) were derived through a proprietary regression analysis, integrating factors like cloud infrastructure investment and data center capacity expansion as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unforeseen global economic shifts or rapid technological disruption. The forecasts reflect assumptions regarding sustained regulatory pressure and continued cloud adoption across enterprises. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Change Management Software Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Event Apps Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Demand Signal Repository Solutions Market
Digital Solutions
Germany Smart Office Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market