
 Data Classification Tool Market | 2026-2036
Data Classification Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Data Classification Tool Market Insights
The divergence between premium enterprise suites and commodity open-source classification libraries is realigning procurement patterns across the data classification tool landscape. Microsoft Corporation leverages its cloud ecosystem to anchor high-availability deployments in regulated industries. IBM Corporation differentiates through AI-powered semantic tagging that sustains premium positioning against modular competitors.
A data classification tool is software that applies metadata labels to structured and unstructured information based on content sensitivity, regulatory jurisdiction, and business criticality, typically processing files at throughput rates exceeding 10,000 documents per hour for enterprise deployments. Cloud-based software is capturing the fastest expansion as organizations retire on-premise data centers, while hybrid software occupies the margin-rich middle ground for firms operating under data residency mandates. Compliance management applications are leading revenue contribution among end-use cases, though data governance is gaining traction as CISOs consolidate tool stacks.
The EU AI Act, GDPR, and HIPAA collectively shape product roadmaps by mandating explainable classification logic and audit-ready lineage documentation. The Federal Trade Commission and Securities and Exchange Commission in the United States are intensifying scrutiny of automated data handling, forcing vendors to embed policy enforcement directly within classification engines. Stakeholders must monitor whether regulatory fragmentation between jurisdictions forces platform specialization or accelerates consolidation toward unified global standards.
Market Dynamics
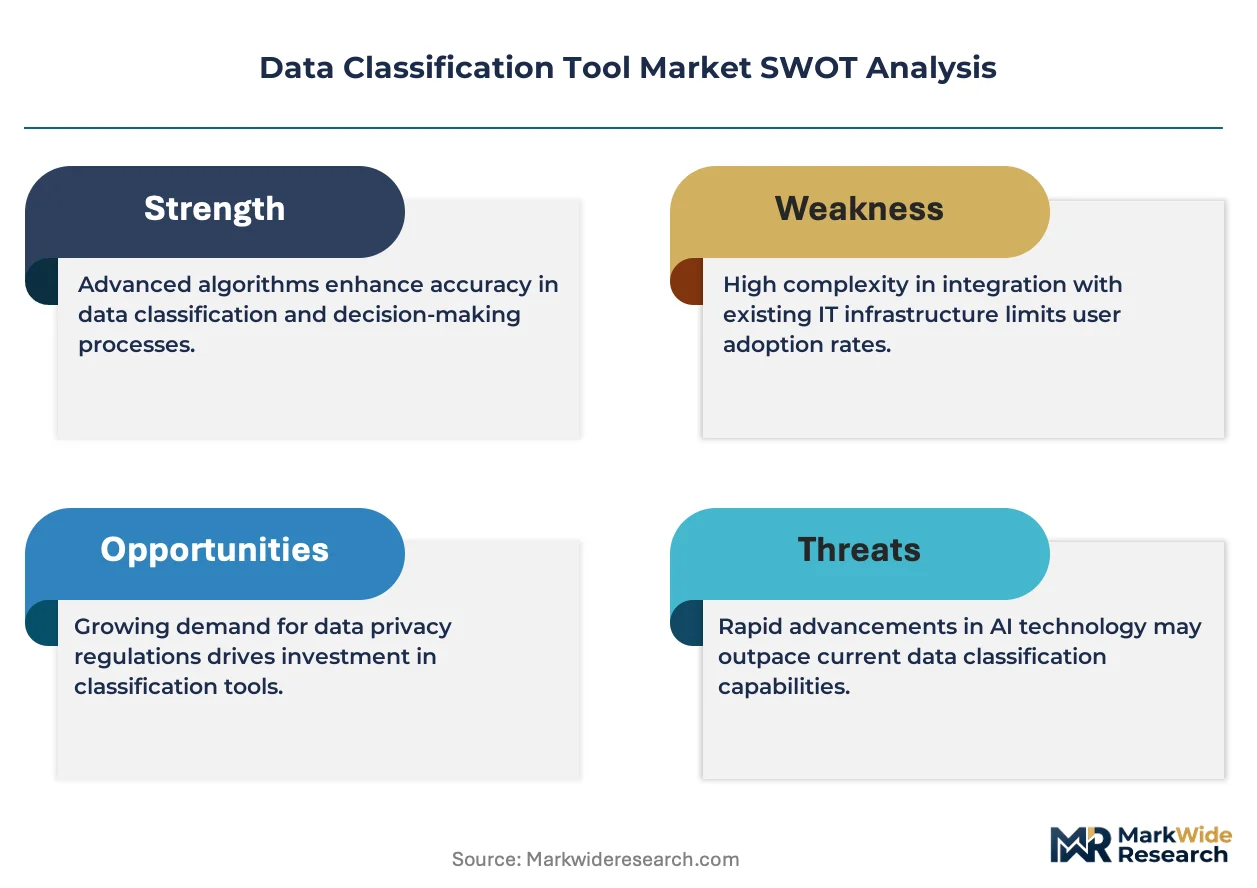
Cloud migration mandates from financial services and healthcare providers are compressing deployment cycles for automated classification engines, forcing vendors to embed policy enforcement directly within processing pipelines rather than bolt-on compliance layers.
Growth Catalysts
- EU AI Act explainability mandates:Automated classification systems must now generate audit-ready lineage documentation, expanding procurement of enterprise-grade semantic tagging platforms across Frankfurt and Paris banking clusters.
- Healthcare data volume acceleration:HIPAA-covered entities are retiring manual classification workflows as patient record digitization exceeds 10,000 documents per hour processing thresholds in US hospital networks.
- Hybrid cloud architectures:German and Japanese enterprises operating under data residency requirements are driving margin-rich deployments that span on-premise and sovereign cloud environments simultaneously.
Market Restraints
- GPU compute cost volatility:AI-powered classification training runs depend on NVIDIA H100 availability, with spot pricing fluctuations compressing vendor margins on mid-market SaaS tiers.
- Open-source library substitution:Apache Tika and Presidio offer baseline entity recognition without licensing fees, anchoring price ceilings for commodity classification workloads.
- Cross-border data friction:China's Personal Information Protection Law and Russia's data localization requirements fragment cloud deployment architectures, forcing redundant infrastructure investment.
Strategic Opportunities
- India's digital public infrastructure:The country's Account Aggregator framework and Data Empowerment and Protection Architecture create greenfield demand for consent-aware classification in fintech and healthtech stacks.
- Edge computing convergence:Classification engines compressed for IoT gateways are opening manufacturing and autonomous vehicle telemetry markets previously blocked by latency constraints.
- CSRD sustainability reporting:The EU Corporate Sustainability Reporting Directive mandates structured ESG data classification, creating specialized vertical demand distinct from general-purpose tools.
Industry Challenges
- MLops talent scarcity:Enterprises struggle to hire engineers capable of tuning transformer-based classification models while maintaining sub-second inference latency at enterprise scale.
- Legacy system integration friction:Mainframe-era data repositories in insurance and government sectors resist API-native classification, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Classification Tool Market |
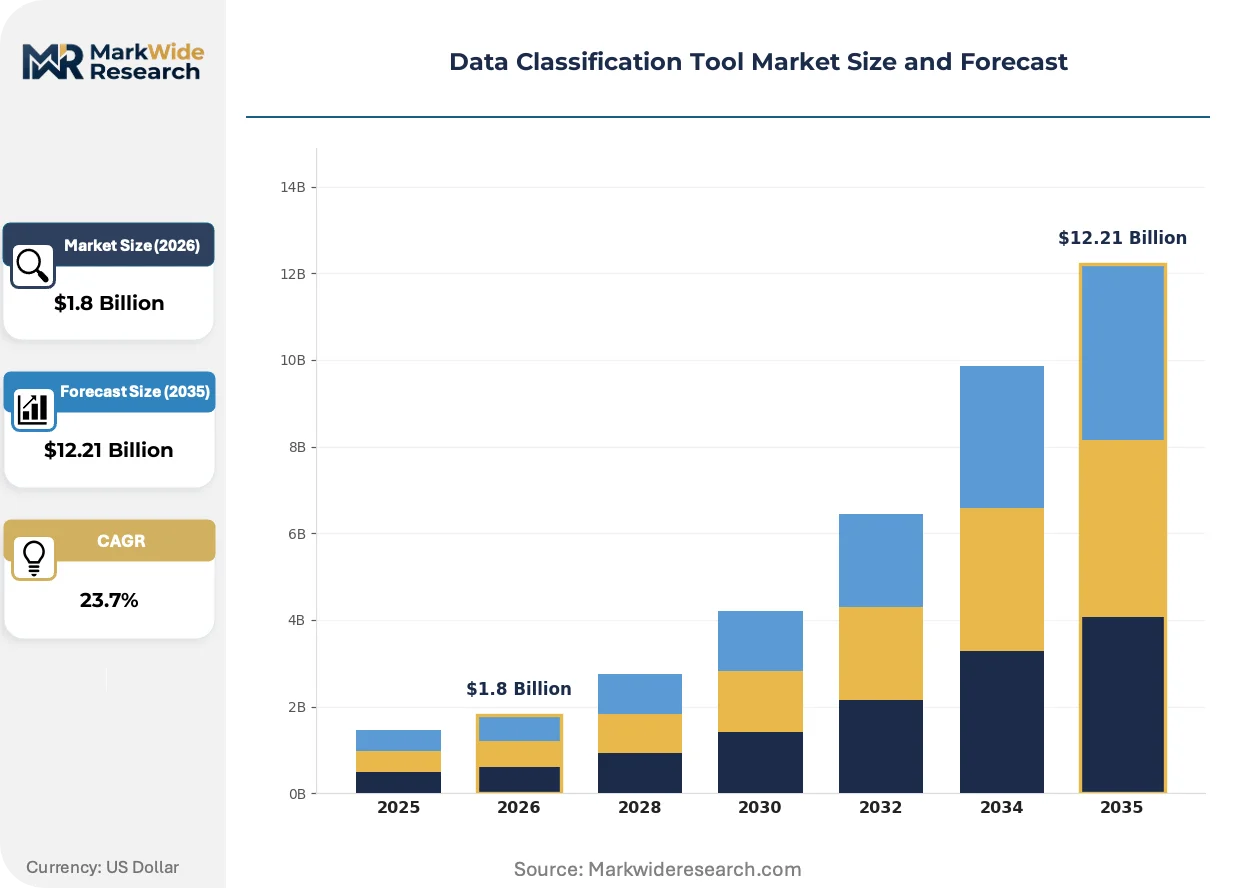
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $12.21 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Premise Software, Cloud-Based Software, Hybrid Software, Open Source Tools Deployment Model: Public Cloud, Private Cloud, Community Cloud, Hybrid Cloud End User: Healthcare Providers, Financial Institutions, Retail Businesses, Educational Institutions Application: Data Security, Compliance Management, Data Governance, Information Lifecycle Management |
| Companies Covered | Microsoft Corporation, IBM Corporation, Amazon Web Services, Varonis Systems, Forcepoint, BigID Inc., Fortra, Broadcom, Google LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Classification Tool Market Trends and Innovations
Foundation model architectures are compressing the feature gap between bespoke enterprise classification systems and commodity alternatives, reshaping vendor investment priorities toward fine-tuning infrastructure rather than core algorithm development.
Transformer-based semantic classification is overtaking rules-engine approaches in regulated industries. Large language models trained on domain-specific corpora now extract sensitivity labels from unstructured contracts and medical records with contextual accuracy that static regex patterns cannot match. Financial institutions in London and Singapore are deploying these systems for real-time transaction monitoring, compressing the competitive moat between premium suites and open-source alternatives.
The EU AI Act's risk-tier framework is forcing classification vendors to document decision logic for high-stakes automated processing. Systems handling biometric or credit-scoring data must now expose confidence thresholds and training data provenance to national regulators. This documentation burden favors established vendors with dedicated compliance engineering teams over leaner competitors, concentrating procurement toward vendors with Brussels and Berlin regulatory affairs presence.
Buyers are unbundling classification from monolithic data governance suites, selecting best-of-breed engines via API subscription rather than enterprise license agreements. Mid-market technology firms in Austin and Tel Aviv now procure classification as metered cloud service, paying per million documents processed rather than annual seat commitments. This consumption shift pressures legacy vendors to expose granular pricing and usage analytics previously reserved for negotiated contracts.
Data Classification Tool Market Segmentation
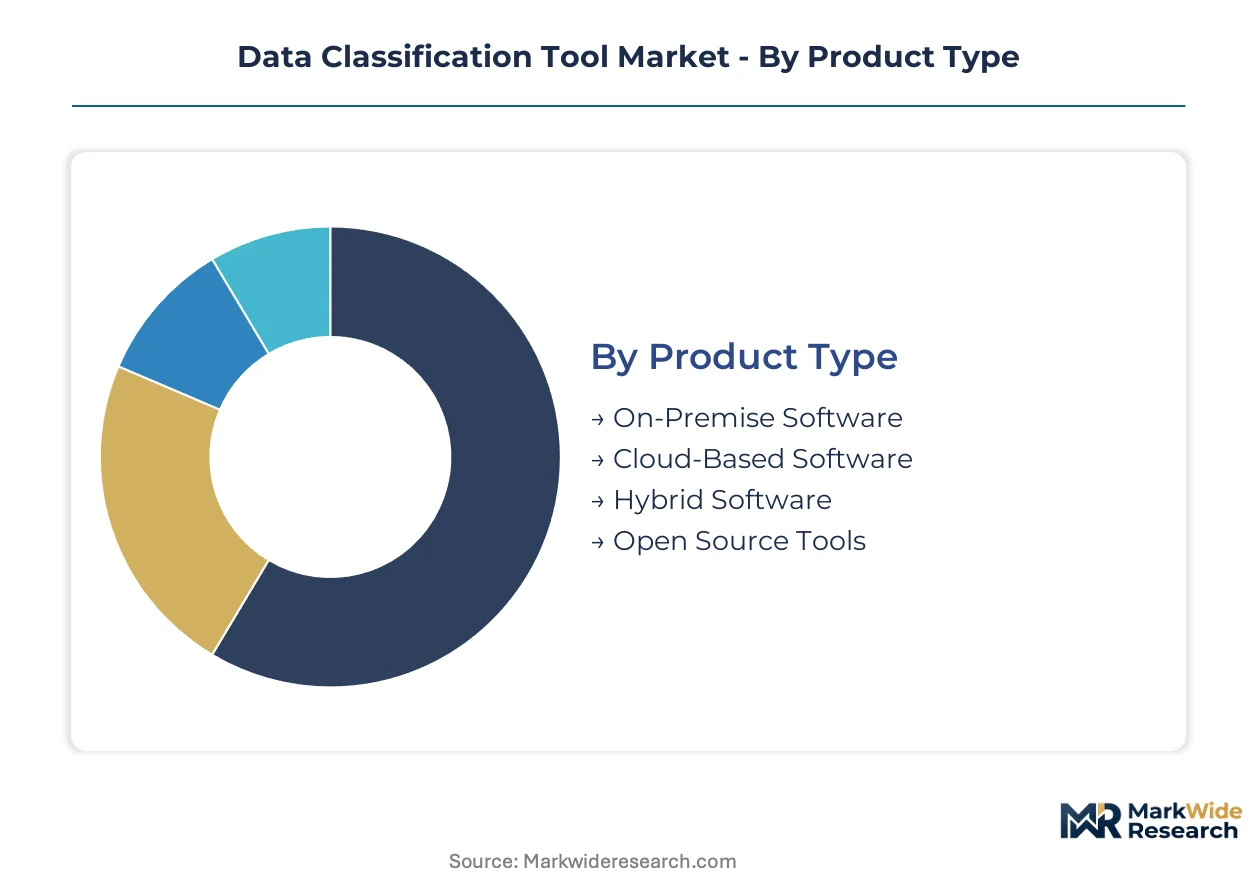
Segmentation in the data classification tool market reveals how deployment architecture, regulatory jurisdiction, and end-use sensitivity reshape procurement patterns. Buyers select configurations based on data residency mandates, processing volume requirements, and the specific compliance frameworks governing their operations.
Product Type:
EU AI Act explainability requirements and GDPR certification burdens fall heaviest on cloud-based and hybrid deployments, while on-premise installations face divergent national data localization statutes.
- Cloud-Based Software:Multi-tenant architectures with auto-scaling compute pools process unstructured data streams exceeding enterprise throughput thresholds. Frankfurt and Singapore banking clusters drive demand as GDPR and MAS Technology Risk Management Guidelines mandate sovereign cloud processing for customer financial records.
- Hybrid Software:Split-processing engines maintain sensitive data on-premise while pushing anonymized analytics to public cloud tiers. German automotive manufacturers and Japanese pharmaceutical firms operating under METI data governance circulars anchor procurement for this margin-rich configuration.
- On-Premise Software:Air-gapped deployments satisfy Russian data localization requirements and Chinese cybersecurity law mandates for critical information infrastructure operators.
- Open Source Tools:Apache Tika and Presidio libraries anchor price ceilings for baseline entity recognition workloads without licensing overhead.
Cloud-based software sits at the top of the volume ranking, with hybrid software climbing the fastest as data residency mandates proliferate across jurisdictions.
Deployment Model:
Cost tier separation runs deepest between reserved private cloud instances and metered public consumption, with community cloud occupying a narrowing middle band for sector-specific consortiums.
- Public Cloud:Shared infrastructure with consumption-based billing compresses entry costs for mid-market technology firms in Austin and Tel Aviv. AWS, Azure, and GCP availability zones in Ireland and Virginia handle the bulk of HIPAA and GDPR-aligned processing workloads.
- Private Cloud:Dedicated single-tenant stacks command premium positioning for credit-scoring and biometric data processing under EU AI Act high-risk system classifications. Swiss banking secrecy law and Singapore MAS requirements sustain demand in Zurich and Marina Bay deployments.
- Community Cloud:Sector-specific infrastructure shared among NHS trusts or German Sparkassen networks achieves compliance economies unavailable to individual operators.
- Hybrid Cloud:Policy-orchestrated workload placement spans on-premise, sovereign cloud, and hyperscaler environments simultaneously.
Public cloud holds the volume lead, though private cloud gains share fastest as high-risk AI system designations expand.
End User:
Application complexity and audit frequency separate healthcare and financial procurement from retail and education deployments, with the former demanding embedded policy enforcement and real-time lineage documentation.
- Financial Institutions:Real-time transaction monitoring systems in London and New York deploy transformer-based semantic classification for AML and sanctions screening. SEC and FCA scrutiny of algorithmic decision-making sustains investment in explainable tagging platforms.
- Healthcare Providers:HIPAA-covered entities process patient records at throughput rates exceeding manual classification capacity, with US hospital networks retiring legacy workflows. FDA guidance on clinical decision support software shapes procurement specifications for diagnostic data handling.
- Retail Businesses:Customer preference and transaction data classification supports personalization engines while navigating state-level privacy statutes in California and Virginia.
- Educational Institutions:Student information system integration drives demand for FERPA-compliant metadata handling in US public university systems.
Financial institutions dominate current volume, with healthcare providers expanding most quickly as patient record digitization accelerates.
Application:
Maturity curves diverge sharply: compliance management commands established budgets while data governance emerges as CISOs consolidate fragmented tool stacks.
- Compliance Management:Automated audit trail generation and regulatory report packaging anchor enterprise procurement decisions. GDPR Article 30 record-keeping and EU AI Act conformity documentation requirements sustain premium pricing for integrated classification-to-reporting workflows.
- Data Security:Sensitivity-based access control and encryption key management integration protect against insider threat and external breach scenarios. Financial institutions in London and Singapore prioritize this application for payment card data environments.
- Data Governance:Unified metadata catalogs and lineage visualization support enterprise data mesh architectures. CSRD sustainability reporting mandates in the European Union create specialized vertical demand for ESG data classification distinct from general-purpose deployments.
- Information Lifecycle Management:Retention schedule enforcement and defensible disposition automation reduce storage liability for long-tail document repositories.
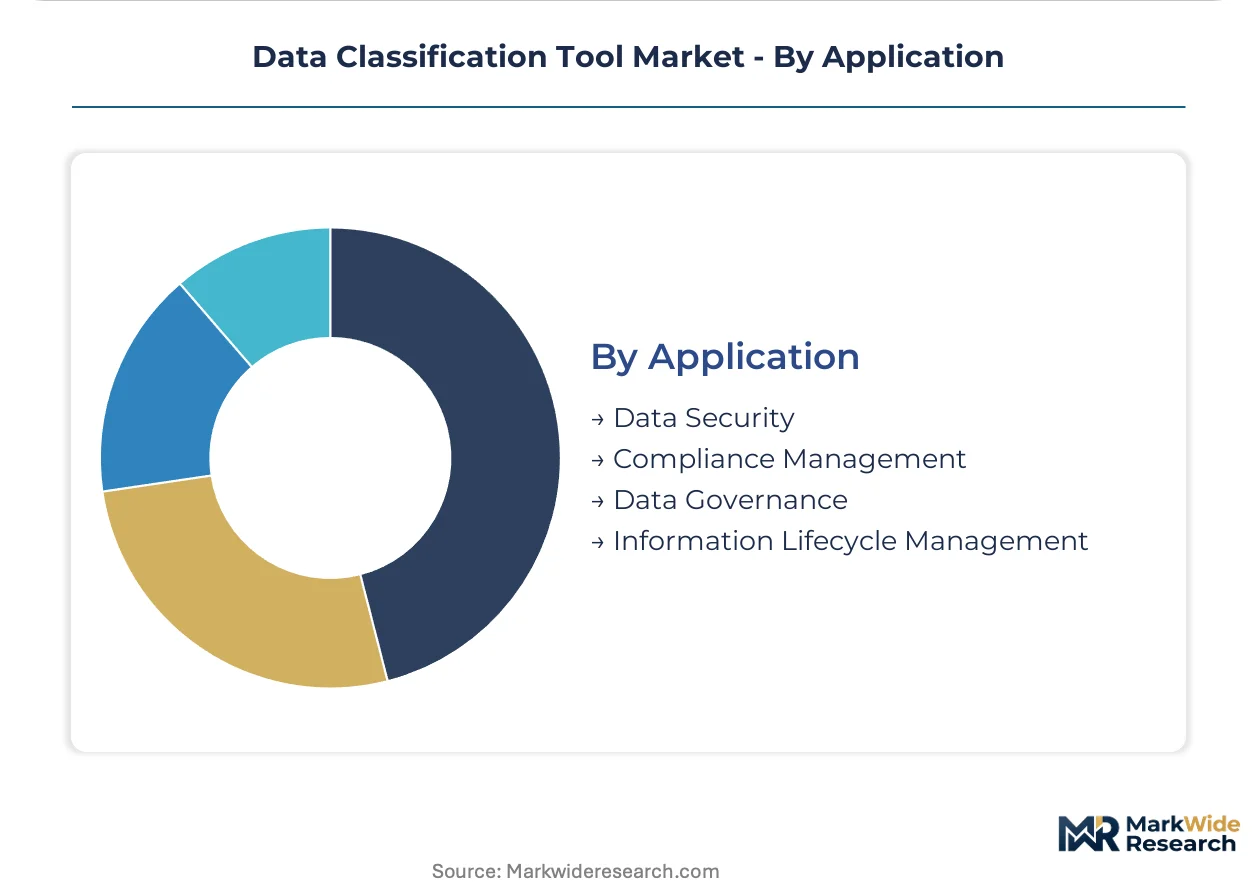
Compliance management leads by volume, with data governance gaining share fastest as chief data officers centralize architecture authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and pharmaceutical clusters generate stricter data residency demand than France's banking consolidation, while Japan's METI circulars create hybrid-deployment premiums unmatched elsewhere in Asia-Pacific.
United States
HIPAA-covered hospital networks and SEC-regulated asset managers drive automated classification procurement at scale. The FTC intensifies scrutiny of algorithmic data handling, forcing explainable tagging into vendor roadmaps. New York and Chicago financial clusters deploy real-time semantic classification for transaction monitoring pipelines.
Germany
Automotive manufacturers and Sparkassen banking networks anchor hybrid software demand under GDPR and EU AI Act mandates. The country's data governance circulars from METI-equivalent regulators enforce sovereign cloud processing. Frankfurt's banking cluster generates audit-ready lineage documentation requirements that shape vendor certification standards.
Japan
Pharmaceutical firms and electronics manufacturers operate under METI data governance guidelines that mandate on-premise retention for sensitive R&D data. The country's cybersecurity framework pushes classification engines into hybrid architectures. Tokyo and Osaka industrial corridors sustain premium pricing for split-processing deployments spanning sovereign and public cloud tiers.
India
Fintech stacks and healthtech platforms exploit the Account Aggregator framework and DEPA infrastructure for consent-aware classification. RBI guidelines on data localization shape procurement specifications for payment data. Mumbai and Bengaluru clusters drive greenfield demand as digital public infrastructure matures.
United Kingdom
FCA-regulated insurers and asset managers deploy transformer-based classification for AML and sanctions screening workflows. Post-Brexit data adequacy negotiations with the EU reshape cloud deployment architectures. London's financial services concentration sustains investment in real-time semantic tagging platforms with embedded policy enforcement.
Data Classification Tool Market Competitive Landscape
Top-tier vendors anchor enterprise-grade semantic tagging, while modular API providers and open-source libraries compress mid-market pricing. The structure concentrates around hyperscaler-integrated suites, best-of-breed specialists, and compliance-heavy legacy platforms. Dominant competitive moves include M&A to acquire fine-tuning infrastructure and strategic partnerships with sovereign cloud providers to satisfy data residency mandates.
Within the hyperscaler-integrated tier, Microsoft Corporation and Amazon Web Services exemplify cloud-native deployment architectures that embed classification within broader data governance ecosystems. IBM Corporation occupies a distinct position among AI-powered semantic specialists, sustaining premium positioning through transformer-based contextual accuracy that static pattern-matching alternatives cannot replicate. These three entities represent the dominant archetypes reshaping procurement patterns as buyers unbundle monolithic suites in favor of metered, API-accessible engines.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services |
| Varonis Systems |
| Forcepoint |
| BigID Inc. |
| Fortra |
| Broadcom |
| Google LLC |
| Others |
Pricing and Supply Chain Analysis
EU AI Act explainability mandates are compressing procurement cycles for audit-ready classification engines, forcing vendors to embed compliance documentation directly into product architecture and compress margins on mid-market SaaS tiers that lack dedicated regulatory engineering teams.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for cloud-based classification services as hyperscaler availability zones expand. Three-tier pricing structure across premium semantic tagging, standard pattern-matching, and economy open-source alternatives dominates procurement decisions. Price differentiation hinges on GDPR certification tier and transformer-based contextual accuracy. Cost compression in the standard tier is intensifying because Apache Tika and Presidio libraries anchor zero-license alternatives. Mid-market technology firms in Austin and Tel Aviv exhibit highest price sensitivity, while Frankfurt banking clusters show least sensitivity due to EU AI Act high-risk system mandates.
Supply Chain Analysis
Freight cost volatility for GPU hardware shipments from Taiwan and South Korea is feeding into deployment pricing for AI-powered classification engines. Software supply concentrates in the United States, Germany, and Japan for enterprise-grade semantic tagging platforms. Raw material dependencies include NVIDIA H100 accelerators, high-bandwidth memory modules, and sovereign cloud infrastructure. Single-source vulnerability around NVIDIA GPU availability creates procurement risk for vendors training transformer-based models. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with metered API consumption models displacing annual license agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in data classification tools rests on the shift from seat-based licensing to consumption-metered API services, compressing customer acquisition costs while capturing premium pricing for high-throughput enterprise deployments.
For Market Incumbents: Lock in regulatory certification moats by embedding EU AI Act conformity documentation directly into processing pipelines rather than bolt-on compliance layers. Invest in sovereign cloud partnerships across Frankfurt, Singapore, and Tokyo to defend against emerging modular API competitors. Capacity additions in India's digital public infrastructure represent a priority geography for preemptive channel control.
For New Entrants and Emerging Players: API-first distribution routes through hyperscaler marketplaces offer the lowest-friction customer acquisition path for transformer-based semantic tagging specialists. India's Account Aggregator framework and DEPA infrastructure present the most penetrable white-space for consent-aware classification engines. Target healthtech stacks in Mumbai and Bengaluru with fine-tuned models for clinical document sensitivity labeling.
For Investors and Strategic Acquirers: Asymmetric upside sits with best-of-breed semantic tagging specialists possessing dedicated Brussels regulatory affairs presence and transformer fine-tuning infrastructure. Long-term viability favors vendors capable of spanning both GDPR-certified enterprise deployments and metered mid-market API consumption. Watch for inflection signals around EU AI Act high-risk system designations expanding beyond biometric and credit-scoring data.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding classification engines within Microsoft Azure and AWS data governance ecosystems captures enterprise procurement decisions. |
| Acquisition of Specialist Firm | Buying transformer fine-tuning startups with healthcare or financial domain expertise accelerates contextual accuracy differentiation. |
| Strategic Partnership | Alliances with sovereign cloud providers in Germany and Japan satisfy data residency mandates under METI and GDPR frameworks. |
| Product Launch | Edge-compressed classification engines for IoT gateways unlock manufacturing and autonomous vehicle telemetry markets. |
| Geographic Expansion | Establishing regulatory affairs presence in Brussels and Berlin secures EU AI Act certification advantages over leaner competitors. |
Research Methodology
Direct dialogue with CISOs, data governance officers, platform engineers, and hyperscaler partnership leads grounded the qualitative foundation of this study. Secondary validation drew from SEC filings of publicly traded software vendors, hyperscaler capex disclosures, EU regulatory filings under GDPR and AI Act frameworks, and healthcare procurement databases tracking HIPAA-covered entity technology spend. Bottom-up and top-down triangulation cross-validated segment-level demand estimates against aggregate market sizing.
Bottom-up modeling of deployment volumes by organization size and vertical combined with top-down macroeconomic adjustment for cloud migration spend produced value estimates across the projection horizon. Segmentation dimensions included deployment architecture, end-user industry, application use case, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement cycle compression and pricing model shifts. Industry-specific forecast inputs encompassed GPU availability constraints and EU AI Act implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for edge-compressed transformer inference would alter the outlook for IoT and manufacturing segment penetration. Forecasts reflect assumptions around hyperscaler marketplace distribution dominance and regulatory certification consolidation toward vendors with dedicated compliance engineering teams. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Construction Design App Market
Digital Solutions
Japan Online Gambling Market
Digital Solutions
Smart Card in Government Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Global Application Container Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Digital Signage Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
OTA Transmission Platform Market
Digital Solutions
Social Computing Market
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Serverless Architecture Market