
 Enterprise Drone Analytics Software Market | 2026-2036
Enterprise Drone Analytics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Drone Analytics Software Market Insights
FAA Part 107 evolution is shifting the cost-of-entry calculus for commercial drone operations, forcing software vendors to embed airspace compliance modules as baseline features. DroneDeploy leverages its cloud-native architecture to sustain multi-tenant scalability across construction and energy verticals. Pix4D anchors European demand through photogrammetry specialization that dominates precision surveying workflows.
Enterprise drone analytics software encompasses platforms that ingest telemetry, imagery, and sensor data from unmanned aerial systems to generate actionable intelligence through computer vision algorithms and geospatial processing pipelines. These systems typically process RGB, multispectral, and LiDAR outputs at sub-centimeter resolution to automate asset inspection, volumetric measurement, and change detection across industrial sites. Cloud-Based deployment leads current adoption due to elastic compute requirements for photogrammetric reconstruction, while Edge Computing represents the fastest-expanding segment as latency-sensitive applications such as security surveillance and disaster response demand real-time onboard analytics. Image Processing commands the largest solution type share, though Predictive Maintenance is capturing disproportionate margin pools as energy utilities integrate drone-derived thermal data into asset health monitoring systems.
FAA regulations govern commercial flight operations and pilot certification in the United States, while EASA's U-space framework standardizes unmanned traffic management across European airspace, and ISO 21384-3 establishes operational safety protocols that shape insurance and liability structures for enterprise deployments. Regulatory fragmentation between jurisdictions forces software vendors to maintain modular compliance engines that adapt to divergent airspace classification and data sovereignty requirements. Stakeholders must monitor the trajectory of beyond-visual-line-of-sight rulemakings and their cascading implications for fleet management software architectures.
Market Dynamics
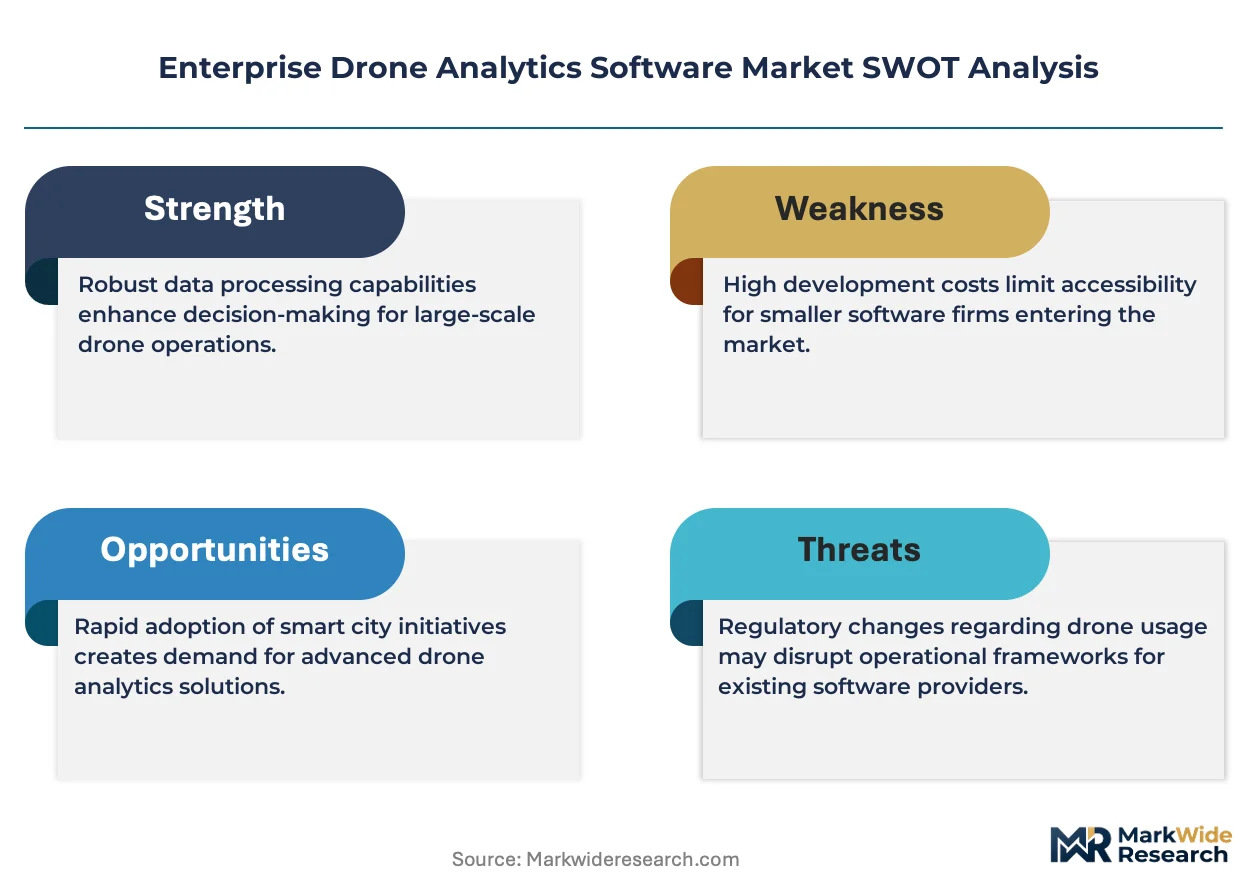
Beyond-visual-line-of-sight rulemakings are compressing deployment timelines for commercial drone fleets while forcing software architectures toward modular compliance engines. This regulatory momentum is redistributing competitive advantage toward vendors with embedded airspace management capabilities.
Growth Catalysts
- FAA Part 107 Expansion:The FAA's beyond-visual-line-of-sight framework is unlocking long-range infrastructure inspection contracts for utility operators. Automated waiver processing is accelerating fleet deployment timelines.
- Precision Agriculture Telemetry:Multispectral sensor integration is automating crop health assessments for large-scale farm operations. Sub-centimeter resolution requirements are expanding analytics software procurement budgets.
- Edge Computing Convergence:Latency-sensitive security surveillance and disaster response applications are demanding real-time onboard processing. Hardware-software co-design is creating new platform subscription tiers.
Market Restraints
- Photogrammetric Compute Costs:Elastic cloud requirements for sub-centimeter reconstruction create volatile operational expenditure profiles for mid-sized operators. GPU scarcity is amplifying processing queue bottlenecks.
- Data Sovereignty Fragmentation:Divergent cross-border data localization mandates are forcing redundant infrastructure deployment. EASA's U-space framework and FAA airspace classifications create incompatible compliance modules.
- LiDAR Sensor Supply Concentration:Specialized hardware sourcing depends on concentrated Asian manufacturing clusters. Geopolitical friction is extending procurement lead times for high-resolution surveying equipment.
Strategic Opportunities
- Predictive Maintenance Integration:Energy utilities are embedding drone-derived thermal data into asset health monitoring systems. Software vendors can capture recurring revenue through API-based enterprise system integration.
- ISO 21384-3 Certification Services:Operational safety protocol standardization is creating adjacent consulting and insurance validation revenue streams. Compliance-as-a-service modules address liability structure uncertainties.
- Construction Volumetric Analytics:Earthworks contractors are adopting automated cut-and-fill measurement for progress billing verification. Cloud-native platforms with multi-tenant scalability can penetrate this underdigitized vertical.
Industry Challenges
- Computer Vision Talent Scarcity:Geospatial algorithm development requires specialized expertise spanning photogrammetry and machine learning. Compensation inflation is compressing vendor margin structures.
- Legacy System Integration Complexity:Enterprise asset management platforms operate on divergent data schemas. Custom middleware development extends implementation timelines and strains professional services capacity.
- Cross-Jurisdictional Certification Timelines:Type certification for new sensor payloads varies across national aviation authorities. Parallel approval processes delay product launch velocity in fragmented regulatory environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Drone Analytics Software Market |
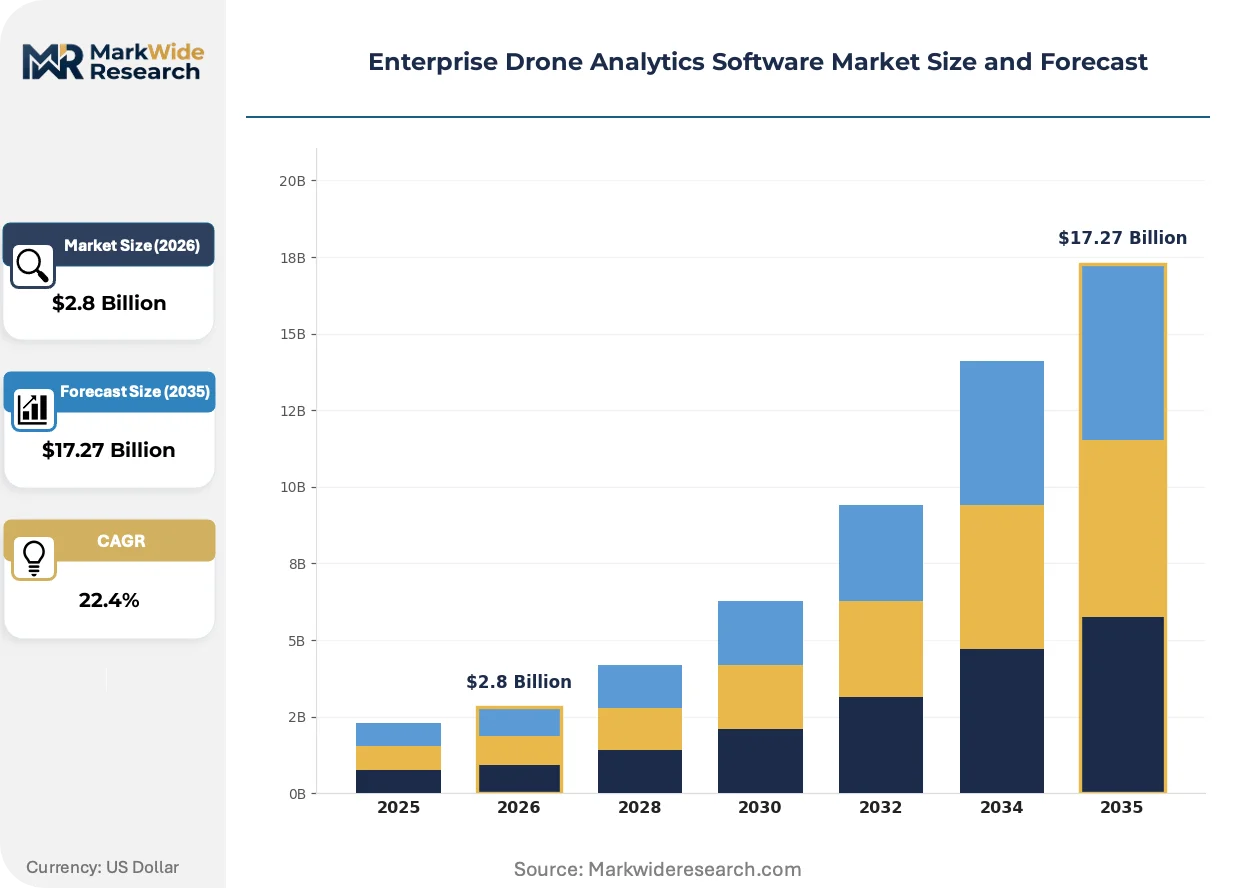
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.27 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Type: Image Processing, Flight Data Analysis, Predictive Maintenance, Regulatory Compliance, Mapping & Surveying Use Case: Precision Agriculture, Infrastructure Inspection, Security Surveillance, Environmental Monitoring, Disaster Management End User Industry: Agribusiness, Energy & Utilities, Transportation, Public Safety, Mining |
| Companies Covered | DroneDeploy, PrecisionHawk, Pix4D, Esri, Kespry, Skydio, Skycatch, DELAIR, AgEagle Aerial Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Drone Analytics Software Market Trends and Innovations
Computer vision architectures are converging with edge hardware to enable real-time analytics without cloud dependency. This shift is redistributing value capture between software licensing and integrated platform sales.
Neural network inference optimization is consolidating disparate image processing pipelines into unified detection frameworks. Agricultural cooperatives and energy utilities are adopting these compressed models for immediate field decision-making. The technology is consolidating vendor competitive positions around proprietary training datasets and domain-specific accuracy benchmarks.
EASA's U-space framework is mandating standardized unmanned traffic management interfaces across European airspace. Software vendors must embed conformant telemetry protocols to maintain market access. Commercial operators in Germany and France are prioritizing platforms with pre-certified compliance modules to accelerate operational authorization.
Subscription-based platform access is displacing perpetual license models across construction and surveying verticals. Equipment dealers are transforming into recurring revenue channels through white-labeled software distribution. This pattern is most visible in the United States, where national rental fleets bundle analytics access with hardware utilization contracts.
Enterprise Drone Analytics Software Market Segmentation
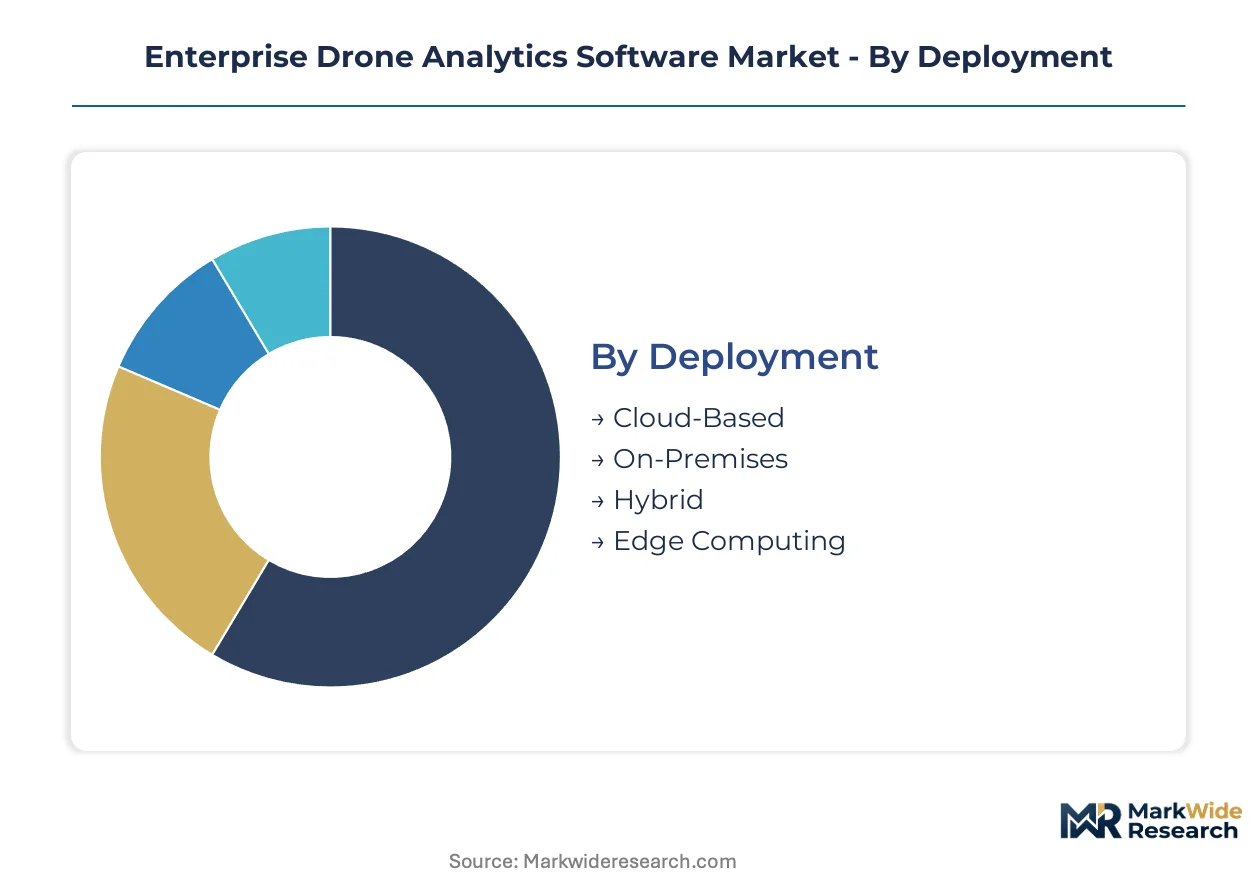
Segmentation reveals divergent capital requirements and margin profiles across deployment architectures and solution types. Enterprise procurement patterns cluster around compute-intensive workflows versus latency-sensitive applications, with each configuration demanding distinct infrastructure investments and vendor capabilities.
Deployment:
Capital-intensity varies sharply across deployment modes, with elastic compute requirements and hardware-software co-design investments creating tiered entry barriers for operators and vendors alike.
- Cloud-Based:Elastic compute clusters handle photogrammetric reconstruction for sub-centimeter resolution outputs. Energy utilities in the United States dominate procurement, driven by thermal data integration into asset health monitoring systems. Most installed capacity flows through Cloud-Based architectures. Expansion is steepest in Edge Computing.
- Edge Computing:Real-time onboard processing enables immediate field decision-making for security surveillance and disaster response applications. Hardware-software co-design creates premium subscription tiers as latency-sensitive deployments concentrate in public safety and critical infrastructure sectors.
- On-Premises:Sovereign data requirements and air-gapped security protocols drive adoption among defense contractors and classified infrastructure operators.
- Hybrid:Split workflows process raw imagery at the edge while delegating reconstruction to cloud clusters, balancing latency against compute economics for mid-sized surveying firms.
Cloud deployments absorb the majority of current analytics workload volume, though edge-native architectures are climbing the fastest as silicon efficiency improves.
Solution Type:
Application complexity and integration depth determine which solution types command premium pricing versus commoditized competition.
- Image Processing:RGB, multispectral, and LiDAR pipelines automate asset inspection and volumetric measurement through computer vision algorithms. Construction contractors in Germany and France prioritize platforms with pre-certified EASA U-space compliance modules to accelerate operational authorization.
- Predictive Maintenance:Thermal anomaly detection and trend analysis integrate drone-derived data into enterprise asset management systems. Energy utilities capture disproportionate margin pools through API-based recurring revenue arrangements with specialized vendors.
- Flight Data Analysis:Telemetry processing and flight path optimization support fleet efficiency and pilot performance benchmarking for commercial operators.
- Regulatory Compliance:Modular airspace management engines adapt to FAA Part 107 waivers and divergent national aviation authority requirements, reducing certification friction for cross-border deployments.
- Mapping & Surveying:Photogrammetry specialization dominates precision workflows with sub-centimeter accuracy requirements for cadastral and engineering applications.
Image Processing retains the largest installed base. Predictive Maintenance is gaining share fastest as utilities deepen thermal monitoring integration.
Use Case:
Operational tempo and data refresh frequency differentiate use cases requiring continuous monitoring from project-based deployments.
- Precision Agriculture:Multispectral sensor integration automates crop health assessments across large-scale farm operations. Agribusiness cooperatives in the United States are expanding analytics procurement budgets as automated yield prediction becomes standard practice.
- Infrastructure Inspection:Beyond-visual-line-of-sight frameworks unlock long-range utility contracts with automated waiver processing accelerating fleet deployment timelines for transmission line and pipeline operators.
- Security Surveillance:Perimeter monitoring and event detection demand real-time analytics with minimal latency, favoring edge-native platform architectures.
- Environmental Monitoring:Vegetation encroachment, erosion tracking, and watershed analysis support regulatory compliance and conservation planning for government agencies.
- Disaster Management:Rapid damage assessment and search-and-rescue coordination require portable, rapidly deployable systems with offline processing capabilities.
Infrastructure Inspection commands the largest contract values. Precision Agriculture shows the steepest budget expansion as farm consolidation accelerates.
End User Industry:
Industry-specific regulatory exposure and asset criticality shape procurement authority and software customization requirements.
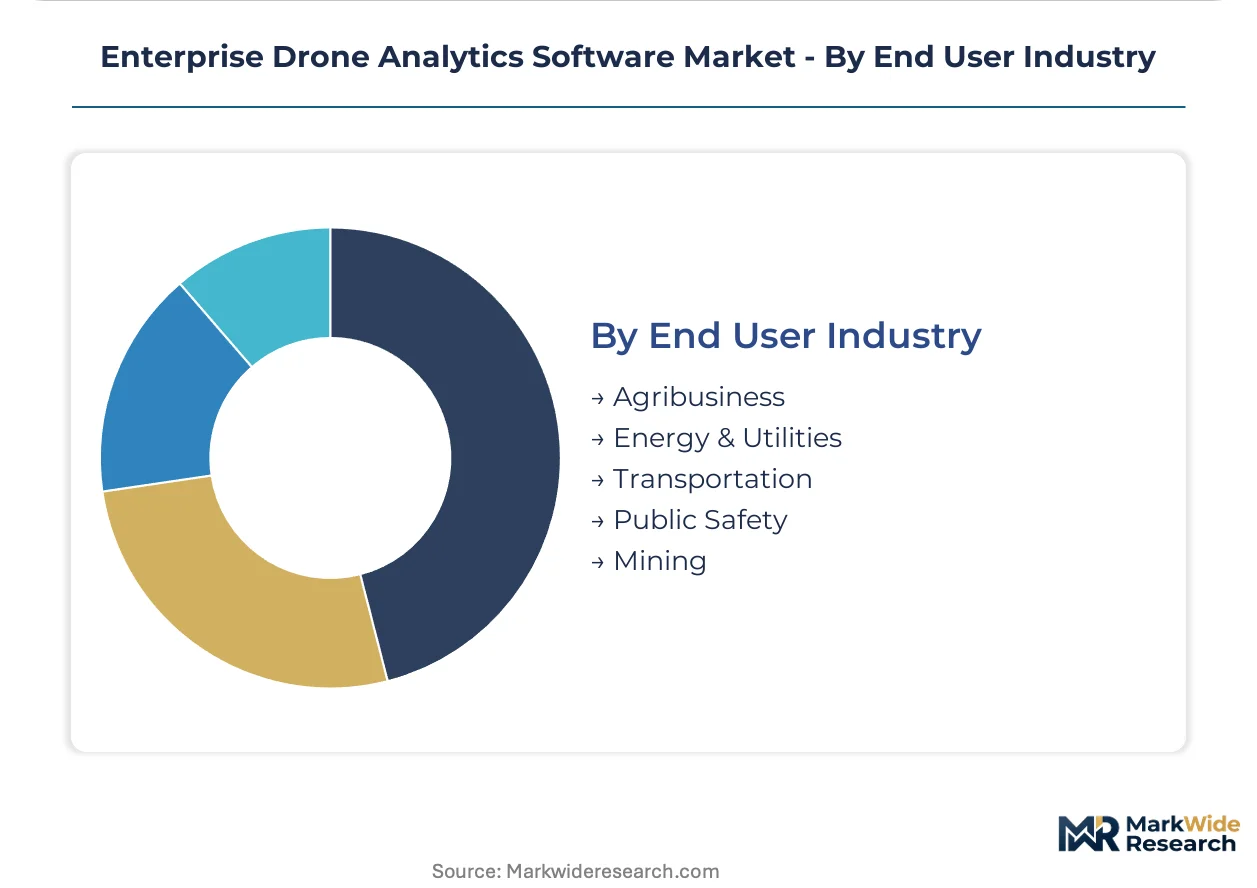
- Energy & Utilities:Transmission, distribution, and generation asset inspection drives thermal analytics adoption with integration into SCADA and enterprise asset management platforms. FAA Part 107 expansion is reshaping operational permissions for commercial fleets serving this vertical.
- Agribusiness:Farm management platforms are embedding drone analytics as standard features, with equipment dealers transforming into recurring revenue channels through white-labeled software distribution.
- Transportation:Bridge, rail, and port infrastructure inspection programs are standardizing drone-based condition assessment protocols.
- Public Safety:Police and fire departments deploy for search operations, accident reconstruction, and situational awareness with strict chain-of-custody requirements for evidentiary imagery.
- Mining:Pit volumetrics, stockpile measurement, and tailings monitoring support production planning and regulatory reporting for open-pit operations.
Energy & Utilities anchor current procurement volume. Agribusiness is expanding most quickly as precision agriculture becomes table stakes for competitive farm operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized computer vision engineers cluster in technology corridors across the United States, Germany, and China, anchoring regional software development capabilities for enterprise drone analytics platforms.
United States
Utility infrastructure inspection contracts drive enterprise software procurement as transmission operators automate thermal monitoring of generation assets. FAA Part 107 expansion for beyond-visual-line-of-sight flights compresses deployment timelines for commercial fleets. The Greater Boston corridor hosts concentrated photogrammetry algorithm development for sub-centimeter reconstruction pipelines.
Germany
Construction contractors prioritize platforms with pre-certified EASA U-space compliance modules to accelerate operational authorization across European airspace. The country's national aviation authority maintains rigorous type certification standards for sensor payload integration. Bavaria's industrial automation cluster supports edge computing hardware-software co-design for real-time field analytics.
China
Domestic drone manufacturers integrate proprietary analytics stacks as standard equipment offerings to agribusiness cooperatives. The Ministry of Industry and Information Technology governs unmanned aerial system certification and data localization requirements. Shenzhen's electronics manufacturing ecosystem supplies concentrated LiDAR sensor production for high-resolution surveying equipment.
France
Energy utilities embed drone-derived thermal data into asset health monitoring systems through API-based enterprise integration. EASA's U-space framework mandates standardized unmanned traffic management interfaces across national airspace. The Paris-Saclay research cluster advances neural network inference optimization for compressed detection models.
Australia
Mining operations deploy automated volumetric measurement for pit surveying and stockpile monitoring supporting production planning. The country's national aviation regulator administers beyond-visual-line-of-sight operational certificates for remote infrastructure inspection. Western Australia's Pilbara region concentrates open-pit automation demand for real-time onboard analytics.
Enterprise Drone Analytics Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architectures and vertical applications. The vendor base organizes around cloud-native platform scalability, photogrammetry specialization, and integrated hardware-software bundles. Three archetypes dominate: vertical-agnostic SaaS providers, domain-specific analytics engines, and equipment-integrated solution stacks. Competitive positioning hardens through strategic partnerships with sensor manufacturers and API-based enterprise system integration.
Within the cloud-native platform tier, DroneDeploy and Skycatch exemplify multi-tenant architectures serving construction and energy verticals. Pix4D occupies a position as a European specialist anchoring photogrammetry workflows through precision surveying capabilities. PrecisionHawk represents the integrated hardware-software archetype with equipment bundled analytics access.
| Leading Market Players |
|---|
| DroneDeploy |
| PrecisionHawk |
| Pix4D |
| Esri |
| Kespry |
| Skydio |
| Skycatch |
| DELAIR |
| AgEagle Aerial Systems |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in cloud-native software platforms exercise disciplined pricing power through subscription bundling while sourcing compute infrastructure from concentrated hyperscaler regions. Their ownership structure rewards recurring revenue maximization over transactional margin capture, tightening vendor economics for mid-sized operators dependent on elastic photogrammetric processing.
Pricing Analysis
Bundled hardware-software service packages dominate enterprise procurement, separating equipment-integrated analytics access from pure SaaS licensing tiers. Price differentiation rests on certification grade—ISO 21384-3 compliance modules command premium positioning—and vertical integration depth, with full-stack vendors capturing margin pools unavailable to point-solution providers. Cost compression in mid-market cloud processing tiers intensifies as GPU scarcity amplifies queue bottlenecks. Equipment dealers bundling white-labeled platform access show lowest price sensitivity; mid-sized surveying firms operating on project-based workflows exhibit highest elasticity.
Supply Chain Analysis
LiDAR sensor supply rests on concentrated manufacturing clusters in China, Japan, and South Korea, with Shenzhen's electronics ecosystem anchoring high-resolution surveying component production. Specialized photogrammetric compute hardware draws from Taiwanese semiconductor foundries and Korean memory fabricators. Geopolitical friction across Taiwan Strait shipping lanes presents single-source vulnerability for edge-native processing silicon. Distribution runs through national equipment rental fleets and direct enterprise sales channels, with dealer networks transforming into recurring revenue conduits through subscription bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Enterprise Drone Analytics Software Market compounds steadily as regulatory tailwinds from FAA Part 107 expansion and EASA U-space mandates institutionalize fleet deployment across critical infrastructure verticals.
For Market Incumbents: Acquire specialized computer vision engineering teams to consolidate scarce photogrammetry and machine learning expertise before compensation inflation erodes margin structures. Defend position by embedding modular airspace compliance engines that adapt to divergent FAA and EASA regulatory trajectories, reducing certification friction for cross-border enterprise deployments. Prioritize API-based integration depth with SCADA and enterprise asset management platforms to lock in utility sector recurring revenue. For New Entrants and Emerging Players: The premium-to-economy pricing gap in edge-native security surveillance platforms offers white-space entry for hardware-software co-design specialists. Target construction volumetric analytics in Germany and France, where EASA U-space pre-certification requirements have slowed incumbent platform adaptation. Penetrate through white-label partnerships with national equipment rental fleets seeking analytics bundling capabilities without proprietary development investment. For Investors and Strategic Acquirers: Valuations sit cheapest among domain-specific photogrammetry engines with concentrated European surveying market share but limited vertical expansion. Long-term viability hinges on sustained regulatory momentum for beyond-visual-line-of-sight operations across energy and utility infrastructure inspection. Watch FAA waiver processing velocity as the inflection signal—accelerated automated approvals would compress deployment timelines and amplify platform revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Consolidates scarce computer vision talent before compensation inflation compresses margins. |
| Platform Integration | API-based SCADA connectivity locks energy utilities into recurring thermal monitoring revenue streams. |
| Geographic Expansion | EASA U-space pre-certification accelerates operational authorization across German and French airspace. |
| Strategic Partnership | Equipment dealer white-labeling transforms hardware vendors into recurring analytics distribution channels. |
| Product Launch | Edge-native security surveillance platforms capture latency-sensitive public safety procurement budgets. |
Research Methodology
Direct dialogue with fleet operations managers at transmission utilities, precision agriculture directors at agribusiness cooperatives, and software procurement leads at construction firms grounded qualitative findings in operational reality. Secondary validation drew from FAA Part 107 waiver databases, EASA U-space regulatory filings, utility infrastructure inspection contract announcements, and hyperscaler capex disclosures for elastic compute infrastructure. Bottom-up triangulation across deployment architecture adoption curves and top-down reconciliation against vertical software spending patterns ensured cross-verified demand estimates.
Bottom-up modeling segmented the market across cloud-based, edge computing, on-premises, and hybrid deployment modes, with solution type granularity spanning image processing, predictive maintenance, and regulatory compliance modules. CAGRs were derived from segment-level growth rate reconciliation against aggregate vertical software procurement trends. Forecast inputs incorporated FAA beyond-visual-line-of-sight rulemaking trajectory and LiDAR sensor supply lead time dynamics across the projection horizon.
Caveats apply where FAA waiver automation delays or EASA U-space implementation friction could materially shift the outlook for fleet deployment velocity. Forecasts reflect assumptions around sustained hyperscaler compute cost trajectories and stable geopolitical conditions for Asian sensor sourcing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
North America Crowd Analytics Market
Analytics
US Video Analytics Market
Analytics
Asia-Pacific HR Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Global Retail Analytics Software and Services Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Europe Crowd Analytics Market
Analytics
Attribution Software Market
Analytics
Construction Data Analytics Software Market
Analytics
Predictive and Prescriptive Analytics Market
Analytics
Sweden ICT Market
Analytics
Content Analytics Discovery and Cognitive Software Market
Analytics
Investigative Analytics Market
Analytics
APAC Location Analytics Market
Analytics
Brazil Geospatial Analytics Market