
 Latin America Digital Signage Market | 2026-2036
Latin America Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Digital Signage Market Foresight
Multi-source procurement for display panels and media players is expanding as systems integrators diversify beyond Korean and Japanese suppliers. Samsung Electronics Co. Ltd anchors high-brightness outdoor installations through its direct sales infrastructure across São Paulo and Mexico City. NEC Corporation competes in transportation hubs with specialized narrow-bezel video wall configurations. LG Display Co. Ltd leverages its OLED manufacturing scale to target premium retail flagships seeking curved and transparent screen formats.
Latin America digital signage encompasses networked electronic display systems comprising LED and LCD panels, media players, content management software, and connectivity infrastructure designed for remote scheduling and real-time audience analytics. These systems operate through cloud-based or on-premise architectures to deliver advertising, wayfinding, and operational messaging in public and commercial environments. LED Displays dominate transportation and stadium deployments due to superior luminance and durability in tropical climates. Cloud-Based Solutions sustain the fastest expansion trajectory as Brazilian and Colombian retailers adopt subscription content management to reduce capital outlays. Interactive Displays occupy emerging margin pools in healthcare and education segments where touch-enabled wayfinding and patient engagement applications multiply.
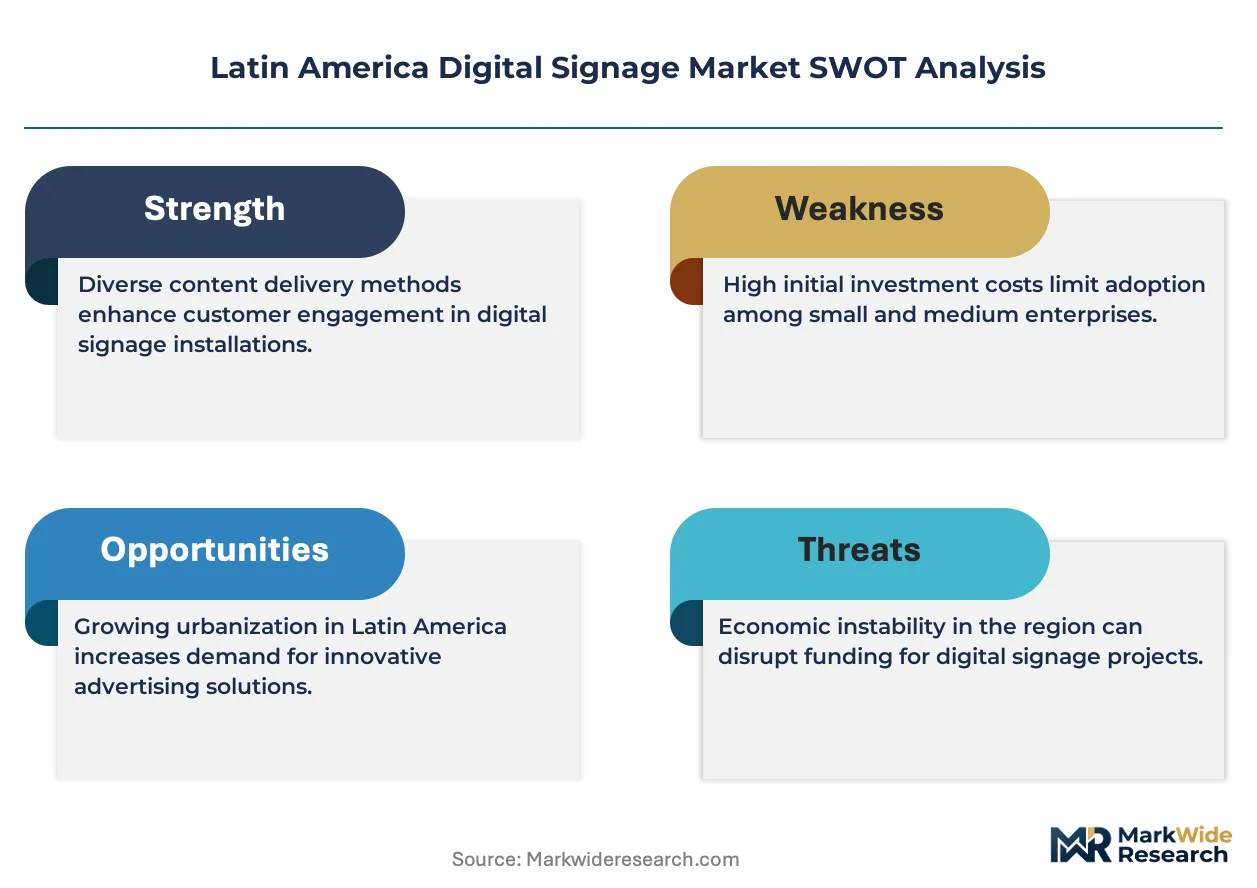
ANATEL in Brazil mandates electromagnetic compatibility and radio frequency certifications that extend hardware import lead times for non-local assemblers. Mexico's Federal Telecommunications Institute imposes analogous equipment approval protocols that shape supplier registration strategies. Energy efficiency benchmarks under local utility programs in Chile and Colombia increasingly filter procurement specifications for large-format screen networks. Stakeholders must weigh certification pathway investments against the acceleration of localized assembly partnerships that compress regulatory timelines.
Market Dynamics
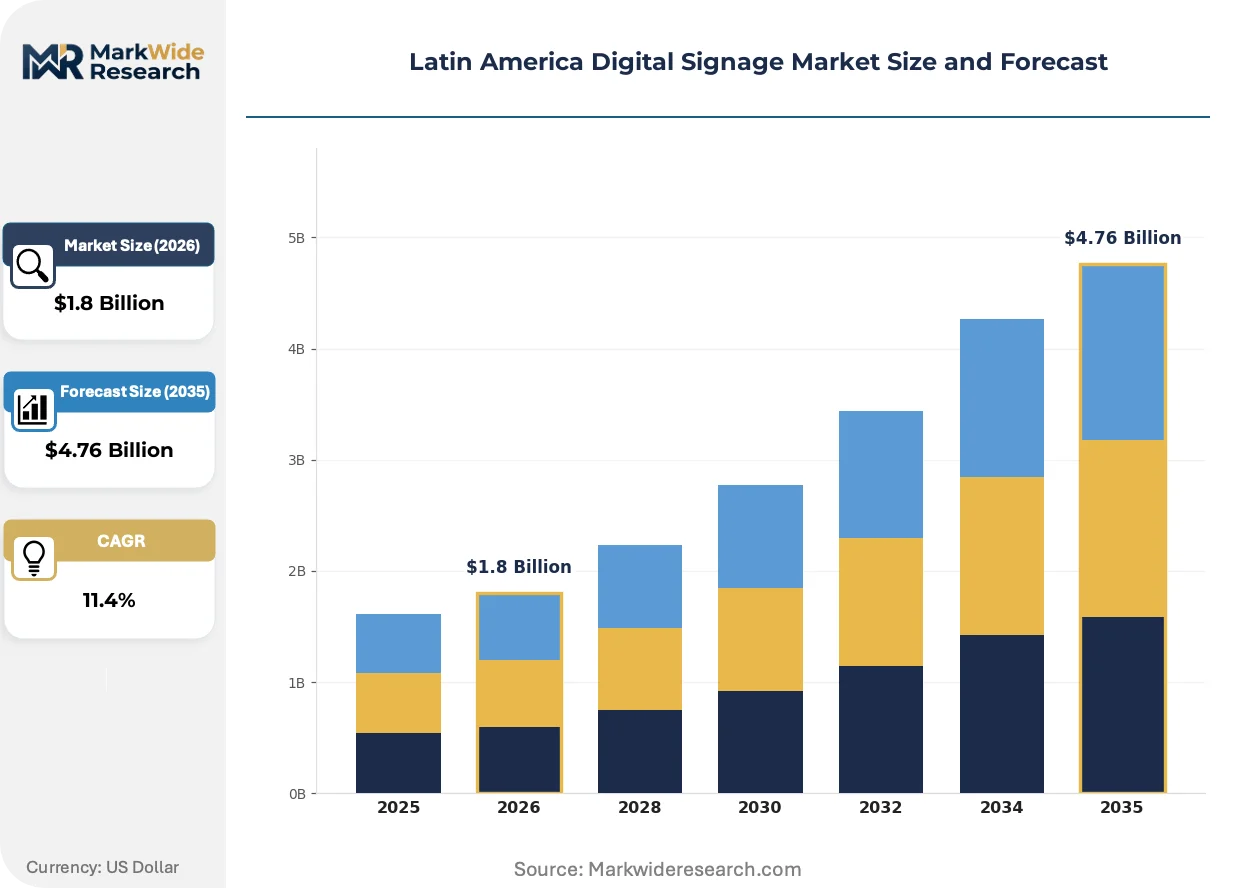
Cloud-based content management systems are compressing deployment timelines across Brazilian retail networks, while ANATEL certification bottlenecks for non-local hardware extend procurement cycles and reshape supplier localization strategies.
Growth Catalysts
- Transit Authority Digitization:São Paulo and Rio de Janeiro metropolitan transit authorities are issuing bundled screen tenders for wayfinding and advertising revenue generation.
- ANATEL's Local Assembly Incentives:Brazil's electromagnetic compatibility certification pathway rewards localized assembly partnerships with compressed approval timelines.
- LED Luminance Advantages:Transportation and stadium deployments favor LED displays for tropical climate durability and superior brightness performance.
Market Restraints
- Panel Supply Concentration:Display panel sourcing concentrates among Korean and Japanese suppliers, exposing integrators to single-geography disruption risk.
- Certification Timeline Friction:ANATEL and Mexico's Federal Telecommunications Institute protocols extend hardware import lead times for non-registered vendors.
- Capital Intensity Barriers:Large-format screen networks require substantial upfront investment in connectivity infrastructure and content management platforms.
Strategic Opportunities
- Colombian Retail Subscription Adoption:Colombian retailers are pivoting toward subscription-based content management to eliminate capital outlay barriers.
- Healthcare Touch Applications:Interactive displays for patient wayfinding and engagement remain underpenetrated across Brazilian hospital networks.
- Chilean Energy Efficiency Mandates:Local utility programs in Chile are creating procurement preference filters for certified efficient screen networks.
Industry Challenges
- Integration Complexity:Legacy point-of-sale and inventory systems in Mexican retail chains resist seamless API connectivity with dynamic pricing displays.
- Certification Skill Scarcity:Systems integrators face talent gaps in navigating ANATEL electromagnetic compatibility documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Digital Signage Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
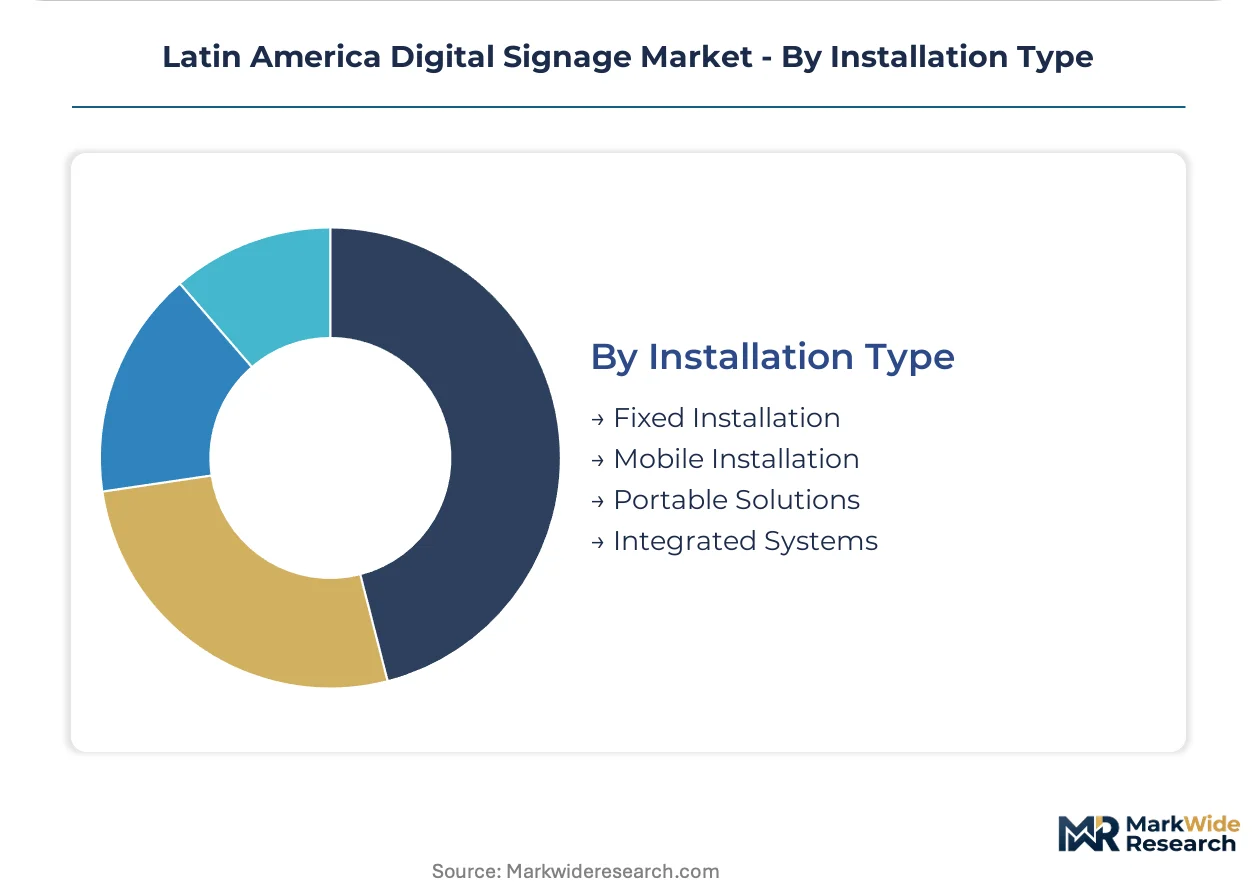
| Segmentation | Product Type: LED Displays, LCD Displays, Projectors, OLED Screens End User: Retail, Transportation, Education, Healthcare Technology: Cloud-Based Solutions, On-Premise Solutions, Interactive Displays, Digital Posters Installation Type: Fixed Installation, Mobile Installation, Portable Solutions, Integrated Systems |
| Companies Covered | Sony Corporation, NEC Corporation, Samsung Electronics Co. Ltd, 3M Corporation, Cisco Systems Inc, LG Display Co. Ltd, Sharp Corporation, Scala Inc, Panasonic Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Digital Signage Market Shifts & Advancements
Display hardware architecture and procurement contracting models are diverging simultaneously, with modular assembly methods colliding against subscription-based service structures across the region's deployment base.
Micro-LED packaging technology is modularizing outdoor display construction for Brazilian stadium and transit applications. Systems integrators in São Paulo are adopting field-replaceable cabinet designs to reduce maintenance downtime. This modularity is compressing total cost-of-ownership calculations for high-brightness installations.
Energy efficiency benchmarks under Chilean utility programs are filtering into procurement specifications for large-format networks. Retail landlords in Santiago now require efficiency certification as a lease condition for screen deployments. Shopping mall renovation tenders increasingly specify compliant hardware categories.
Subscription content management is displacing perpetual-license purchasing among mid-market Brazilian retailers. São Paulo-based retail chains are unbundling hardware ownership from software access to preserve working capital. This preference shift is most visible in fashion and grocery verticals with thin margin profiles.
Latin America Digital Signage Market Segmentation
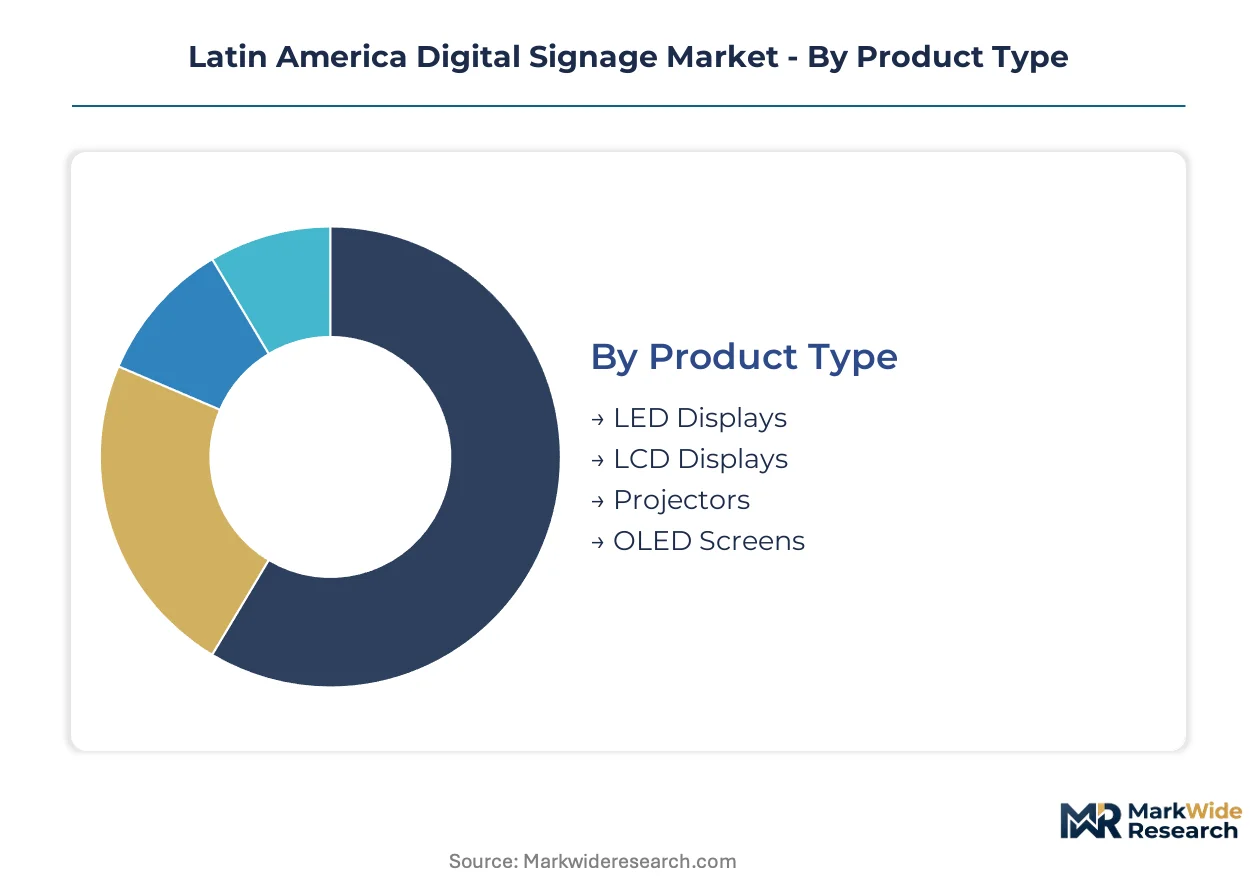
Digital signage segmentation in Latin America reflects divergent procurement priorities across tropical climate durability, electromagnetic certification pathways, and capital deployment preferences. Each axis shapes supplier positioning and margin capture differently across Brazilian, Mexican, and Colombian deployment clusters.
Product Type:
Display technology selection hinges on luminance requirements, thermal management, and field serviceability in high-humidity environments.
- LED Displays:Direct-view LED cabinets with IP65-rated enclosures withstand tropical precipitation and temperature cycling. São Paulo metro tenders and Rio de Janeiro stadium renovations specify LED for 10,000+ nit brightness and modular field replacement. ANATEL certification timelines favor locally assembled LED cabinets over fully imported alternatives.
- LCD Displays:High-brightness LCD panels with optical bonding dominate indoor retail and corporate deployments where resolution-per-inch drives content fidelity. Mexican shopping mall renovations in Mexico City and Guadalajara specify 4K LCD for luxury brand flagships. Supply concentrates among Korean and Japanese panel makers, exposing integrators to currency fluctuation risk.
- Projectors:Laser phosphor projectors serve temporary event installations and heritage building restrictions where permanent screen mounting is prohibited.
- OLED Screens:Self-emissive OLED panels enable transparent and curved form factors for premium retail experiences in São Paulo's luxury corridors.
LED Displays lead on scale; OLED Screens lead on momentum.
End User:
Demand concentration varies by sector-specific procurement authority and revenue-model sophistication.
- Retail:Brazilian fashion and grocery chains deploy networked screens for dynamic pricing synchronization with inventory systems. Colombian retailers favor subscription-based content management to eliminate capital barriers. Integration complexity with legacy POS systems remains the primary deployment friction.
- Transportation:Transit authorities in São Paulo and Rio de Janeiro bundle wayfinding and advertising concession rights in single tenders. LED durability in open-air platforms and station environments drives specification preferences. Revenue-sharing models with advertising operators offset capital requirements.
- Education:Touch-enabled interactive displays penetrate Brazilian university campuses for wayfinding and digital bulletin board replacement.
- Healthcare:Patient engagement screens and touch-enabled directory systems remain underpenetrated across Brazilian hospital networks, presenting greenfield opportunity.
Transportation commands the largest tender values; Healthcare climbs the fastest.
Technology:
Architecture decisions determine upfront capital intensity versus recurring operational expenditure profiles.
- Cloud-Based Solutions:Browser-based content management platforms enable remote scheduling and real-time analytics without on-site server infrastructure. Colombian and Brazilian mid-market retailers adopt subscription pricing to preserve working capital. São Paulo-based fashion chains unbundle hardware ownership from software access.
- On-Premise Solutions:Local server deployments persist in financial services and government installations where data sovereignty requirements prohibit cloud connectivity. Higher upfront capital requirements limit adoption among margin-constrained verticals.
- Interactive Displays:Touch-enabled screens multiply in healthcare wayfinding and educational campus navigation applications.
- Digital Posters:Standalone non-networked displays serve cost-constrained small retail and quick-service restaurant applications.
Cloud-Based Solutions expand most quickly; On-Premise Solutions retain highest contract values.
Installation Type:
Mounting and mobility specifications reflect deployment duration, structural constraints, and maintenance access requirements.
- Fixed Installation:Permanent wall-mounted and ceiling-suspended configurations dominate transportation and retail deployments. Brazilian stadium projects specify fixed LED cabinets with rear-service access for tropical climate resilience. Structural engineering certification adds timeline and cost layers to high-brightness outdoor implementations.
- Mobile Installation:Wheeled cart-based systems serve event marketing and temporary retail activations where location flexibility outweighs permanence.
- Portable Solutions:Battery-powered and rapid-deploy units address trade show and field marketing applications with minimal infrastructure requirements.
- Integrated Systems:Custom architectural integration conceals display elements within building finishes for premium hospitality and corporate lobby environments.
Fixed Installation dominates revenue; Integrated Systems capture highest margin per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing assembly activity across Latin America as certification cost differentials between locally integrated and direct-import hardware reshape supplier footprints. Brazilian ANATEL electromagnetic compliance timelines favor domestic partnerships, while Mexican and Colombian procurement clusters exploit adjacent trade frameworks to compress equipment lead times.
Brazil
São Paulo metro tenders and Rio de Janeiro stadium renovations drive LED display procurement for transit wayfinding and outdoor advertising concessions. ANATEL certification requirements for electromagnetic compatibility extend import timelines for non-local hardware, incentivizing localized assembly partnerships. Brazilian systems integrators cluster around São Paulo's industrial corridor to exploit compressed approval pathways for domestically assembled cabinets.
Mexico
Mexico City shopping mall renovations and Guadalajara luxury retail flagships specify high-brightness LCD panels for premium brand experiences. The Federal Telecommunications Institute imposes equipment approval protocols that shape supplier registration strategies for cross-border hardware flows. Northern border states leverage proximity to US distribution networks to accelerate media player and display panel procurement cycles.
Colombia
Bogotá and Medellín retail chains pivot toward subscription-based content management to eliminate capital outlay barriers in fashion and grocery verticals. Colombian utility efficiency benchmarks increasingly filter procurement specifications for large-format screen networks. Systems integrators concentrate in Bogotá's commercial district to serve mid-market retailers adopting cloud-based scheduling platforms.
Chile
Santiago retail landlords now require energy efficiency certification as a lease condition for screen deployments in shopping mall renovation tenders. Local utility programs create procurement preference filters for certified efficient hardware categories. Chilean systems integrators target corporate lobby and hospitality segments with integrated architectural display solutions.
Argentina
Buenos Aires transit authorities evaluate bundled screen tenders for subway station wayfinding and advertising revenue generation. Argentine procurement remains constrained by currency fluctuation exposure on imported Korean and Japanese display panels. Local integrators exploit Mercosur trade preferences to source Brazilian-assembled LED cabinets with reduced tariff friction.
Latin America Digital Signage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native software and specialized vertical applications. The vendor base stratifies across three tiers: Korean and Japanese display manufacturers anchor hardware supply; systems integrators bridge installation and certification complexity; software specialists unbundle content management from hardware ownership. Competitive positioning hinges on electromagnetic certification navigation, localized assembly partnerships, and subscription pricing model adoption.
Within the display manufacturing tier, Samsung Electronics Co. Ltd and LG Display Co. Ltd represent the Korean-origin archetype with manufacturing scale advantages, while NEC Corporation exemplifies the Japanese specialist positioning in narrow-bezel transportation applications. Sony Corporation and Panasonic Corporation occupy diversified electronics conglomerate positions spanning multiple display technologies. These named entities anchor hardware supply concentration without constituting exclusive market control.
| Leading Market Players |
|---|
| Sony Corporation |
| NEC Corporation |
| Samsung Electronics Co. Ltd |
| 3M Corporation |
| Cisco Systems Inc |
| LG Display Co. Ltd |
| Sharp Corporation |
| Scala Inc |
| Panasonic Corporation |
| Others |
Supply & Pricing Matrix
Display panel import duties from Korean and Japanese suppliers cascade through three distinct pricing tiers for Brazilian systems integrators, with ANATEL-certified local assembly commanding premium positioning against direct-import alternatives facing extended compliance timelines.
Pricing Analysis
Input-cost pass-through from display panel sourcing concentrates pricing power among Korean and Japanese manufacturers, with currency fluctuation exposure amplifying volatility for Brazilian and Mexican integrators. Pricing stratifies across ANATEL-certified premium tiers, standard direct-import configurations, and economy-grade domestic assembly options. Cost compression in the standard tier intensifies as Colombian retailers accelerate subscription-based content management adoption. Healthcare and education segments demonstrate highest price sensitivity due to thin capital budgets, while transportation authorities with advertising revenue-sharing models absorb premium pricing for LED durability specifications.
Supply Chain Analysis
Warehouse-distribution layers concentrate in São Paulo's industrial corridor for Brazilian market coverage, with northern Mexican border states leveraging US distribution networks for accelerated media player procurement. Display panel supply anchors in South Korea and Japan, with LED chip and driver component dependencies drawing from Taiwanese and Chinese semiconductor foundries. Single-source vulnerability from Korean panel concentration exposes integrators to disruption risk from trade policy shifts or shipping chokepoints. Distribution runs through systems integrator-led hub-and-spoke patterns reaching retail chains in Bogotá, Mexico City, and Santiago.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANATEL certification timelines create geographic-arbitrage value for locally assembled hardware against Mexican and Colombian procurement clusters exploiting adjacent trade frameworks with compressed equipment lead times.
For Market Incumbents: Lock in localized assembly partnerships across São Paulo's industrial corridor to compress ANATEL electromagnetic compatibility approval pathways against emerging cloud-native software competitors. Defend margin position by securing exclusive distribution rights with Brazilian transit authorities bundling wayfinding and advertising concession tenders. Prioritize certification documentation expertise as a talent moat against integrators facing skill scarcity in electromagnetic compatibility navigation. For New Entrants and Emerging Players: Launch via subscription-based content management platforms targeting Colombian mid-market fashion and grocery retailers eliminating capital outlay barriers. Exploit underpenetrated Brazilian hospital networks for touch-enabled patient engagement and wayfinding applications where incumbent hardware specialists lack software integration capabilities. Pursue white-label partnerships with Chilean systems integrators serving energy efficiency-mandated retail landlord specifications in Santiago mall renovations. For Investors and Strategic Acquirers: Consolidation pressure builds where cloud-native software specialists unbundle content management from hardware ownership, fragmenting value capture across the vendor base. Long-term viability favors vertically integrated players controlling both ANATEL certification pathways and localized LED cabinet assembly. Target acquisition profiles include São Paulo-based integrators with established electromagnetic compliance expertise and Bogotá-focused subscription platform operators. Watch Colombian utility efficiency benchmark adoption rates as inflection indicators for hardware procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Investment | Compressed approval timelines reward domestic assembly partnerships against direct-import competitors. |
| Cloud-Native Platform Launch | Subscription pricing models displace perpetual licenses among Colombian and Brazilian mid-market retailers. |
| Healthcare Vertical Penetration | Touch-enabled wayfinding applications remain underpenetrated across Brazilian hospital networks. |
| Energy Efficiency Certification | Chilean utility mandates filter procurement specifications for Santiago shopping mall renovations. |
| Micro-LED Modular Assembly | Field-replaceable cabinet designs reduce maintenance downtime for Brazilian stadium and transit deployments. |
Research Methodology
Multiple input streams — primary interviews with systems integrators and transit authority procurement officers, secondary validation through ANATEL certification databases and Brazilian customs records, and trade flow analysis from Korean and Japanese export statistics — were reconciled to construct market estimates. Bottom-up segmentation modeling across LED, LCD, and OLED product categories was cross-checked against top-down macroeconomic indicators for digital infrastructure investment across the analysis window.
Historical deployment data from São Paulo metro tenders and Rio de Janeiro stadium renovations were cross-referenced against panel input from Colombian retail chain technology officers and Chilean utility program administrators. Segmentation dimensions modeled include display technology type, deployment architecture, end-use vertical, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for certification timeline friction and subscription pricing adoption curves, with LED luminance specifications and cloud-based solution penetration serving as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANATEL regulatory revision scenarios or abrupt currency fluctuation in Korean won and Japanese yen exchange rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Latin America and Europe Digital Signature Market
Digital Solutions
Global Data Historian Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Data Monetization Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Graph Technology Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Construction Design App Market
Digital Solutions
Digital Notepad Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Weather App Market