
 UK B2B Fixed Connectivity Market | 2026-2036
UK B2B Fixed Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
UK B2B Fixed Connectivity Market Insights
Mid-market enterprises are unwinding legacy copper dependency as cloud-first architectures reshape procurement priorities. BT Group leverages its Openreach infrastructure control to sustain wholesale dominance across Ethernet provisioning. CityFibre competes through pure-fiber overbuilds in regional cities, while Vodafone Limited anchors multinational accounts with MPLS-to-SD-WAN migration pathways.
UK B2B Fixed Connectivity encompasses dedicated, symmetric bandwidth services delivered over fiber, copper, or wireless last-mile infrastructure with service level agreements guaranteeing uptime thresholds. These circuits enable mission-critical data transmission between corporate sites, data centers, and cloud service endpoints with latency and jitter specifications tailored to sector requirements. Dedicated Internet Access commands premium pricing in financial services verticals where sub-millisecond latency thresholds justify fiber deployment, while Ethernet segments extend fastest across manufacturing estates requiring scalable bandwidth increments. Leased Line services retain structural importance in healthcare provider networks where resilience mandates dual-path routing, though MPLS faces displacement pressure from software-defined alternatives.
Ofcom's wholesale fixed telecoms market review governs Openreach pricing transparency and physical infrastructure access obligations, directly conditioning competitor entry economics in regional markets. The UK's Building Digital UK program and Project Gigabit subsidy frameworks accelerate full-fiber availability timelines, compressing DSL residual value and redirecting vendor capital toward fiber-to-the-premises overbuilds. Stakeholders must weigh regulatory commitment to infrastructure competition against consolidation incentives as altnet funding costs tighten and wholesale margin structures face downward pressure from standardized access pricing.
Market Dynamics
Ofcom's wholesale fixed telecoms market review is compressing Openreach's pricing power while altnet fiber overbuilds fragment supply-side concentration across UK regional markets.
Growth Catalysts
- Project Gigabit subsidy frameworks:Government funding accelerates full-fiber deployment timelines in underserved counties. Public capital de-risks infrastructure investment for challenger network operators.
- Real-time payment infrastructure mandates:Financial institutions require dedicated low-latency circuits for instant settlement systems. This drives symmetric fiber procurement in London and Manchester financial clusters.
- Cloud-first architecture migration:Mid-market enterprises abandon legacy copper for scalable Ethernet services. Bandwidth procurement shifts from capped commitments to elastic consumption models.
Market Restraints
- Altnet funding cost volatility:Rising debt servicing expenses constrain pure-fiber overbuild economics. Smaller network operators face refinancing pressure against Openreach's incumbent scale.
- Wayleave access friction:Property owner consent delays street-level fiber deployment. Physical infrastructure access obligations under Ofcom rules do not guarantee timely commercial agreements.
- SD-WAN substitution threat:Software-defined wide area networking displaces traditional MPLS private circuits. Enterprise buyers prioritize application-aware routing over dedicated leased line guarantees.
Strategic Opportunities
- Regional city tech corridor expansion:Manchester, Leeds, and Birmingham enterprise zones lack fiber density of London. Altnets can establish wholesale dominance before Openreach completes overbuilds.
- Healthcare network resilience mandates:NHS trusts require dual-path routing for patient data systems. Leased line providers capture structural demand from clinical system digitization.
- Smart manufacturing estate connectivity:Industrial IoT sensors and automated production lines demand scalable symmetric bandwidth. Manufacturing verticals represent underpenetrated demand relative to financial services saturation.
Industry Challenges
- Fiber splicing technician scarcity:Skilled field engineering capacity constrains deployment velocity. Training pipeline gaps delay customer activation timelines against competitive pressure.
- Legacy copper estate remediation costs:Network operators face stranded asset write-downs as DSL subscriber bases erode. Balance sheet pressure compounds against fiber capex intensity requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK B2B Fixed Connectivity Market |
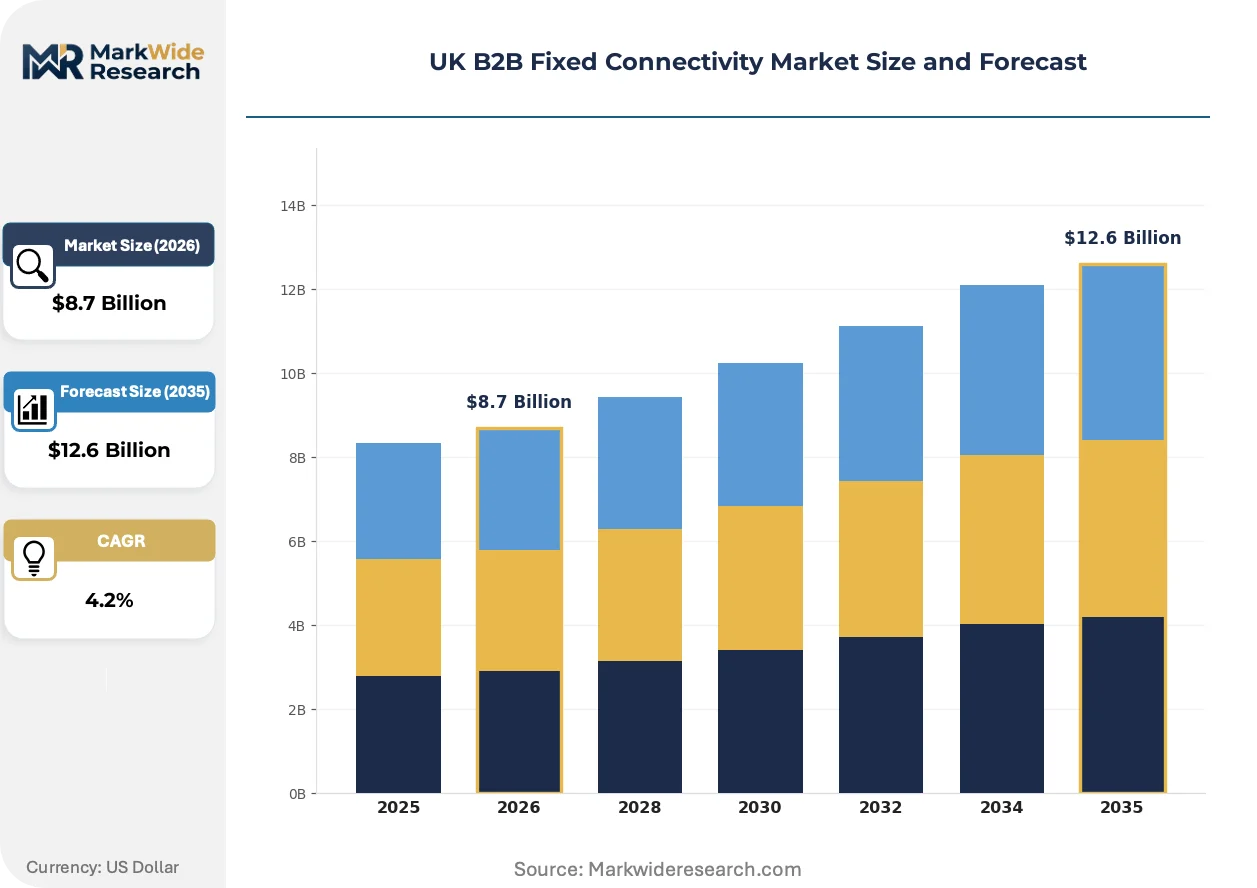
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Internet Access, MPLS, Leased Line, Ethernet End User: Manufacturers, Retail Chains, Financial Institutions, Healthcare Providers Technology: Fiber Optic, DSL, Satellite, Fixed Wireless Deployment: On-premise, Hybrid, Cloud-based, Managed |
| Companies Covered | BT Group, Vodafone Limited, Virgin Media Business Ltd, Sky UK Limited, Openreach, CityFibre, KCOM Group Limited, XLN Telecom Ltd, TalkTalk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK B2B Fixed Connectivity Market Trends and Innovations
Network function virtualization and software-defined architectures are dismantling traditional hardware-centric service delivery models across UK enterprise connectivity procurement.
SD-WAN edge appliances are decomposing branch-office MPLS dependency by abstracting transport from application policy enforcement. Mid-market retailers and logistics operators adopt hybrid connectivity models within compressed procurement cycles. This technology shift is collapsing the premium pricing power that dedicated private circuits previously commanded in multi-site deployments.
Ofcom's physical infrastructure access regulations now mandate dark fiber and duct sharing at cost-oriented prices. Challenger operators leverage Openreach's passive infrastructure to accelerate regional city overbuilds without full civil engineering replication. Wholesale margin structures face sustained compression as standardized access pricing removes historical incumbent differentiation.
Enterprise procurement teams now unbundle connectivity from managed service wrappers previously sold as integrated packages. Direct cloud interconnection and API-driven bandwidth scaling replace long-term contractual commitments with consumption-based alternatives. This pattern concentrates among technology and professional services verticals in London and Manchester where internal network engineering capabilities are strongest.
UK B2B Fixed Connectivity Market Segmentation
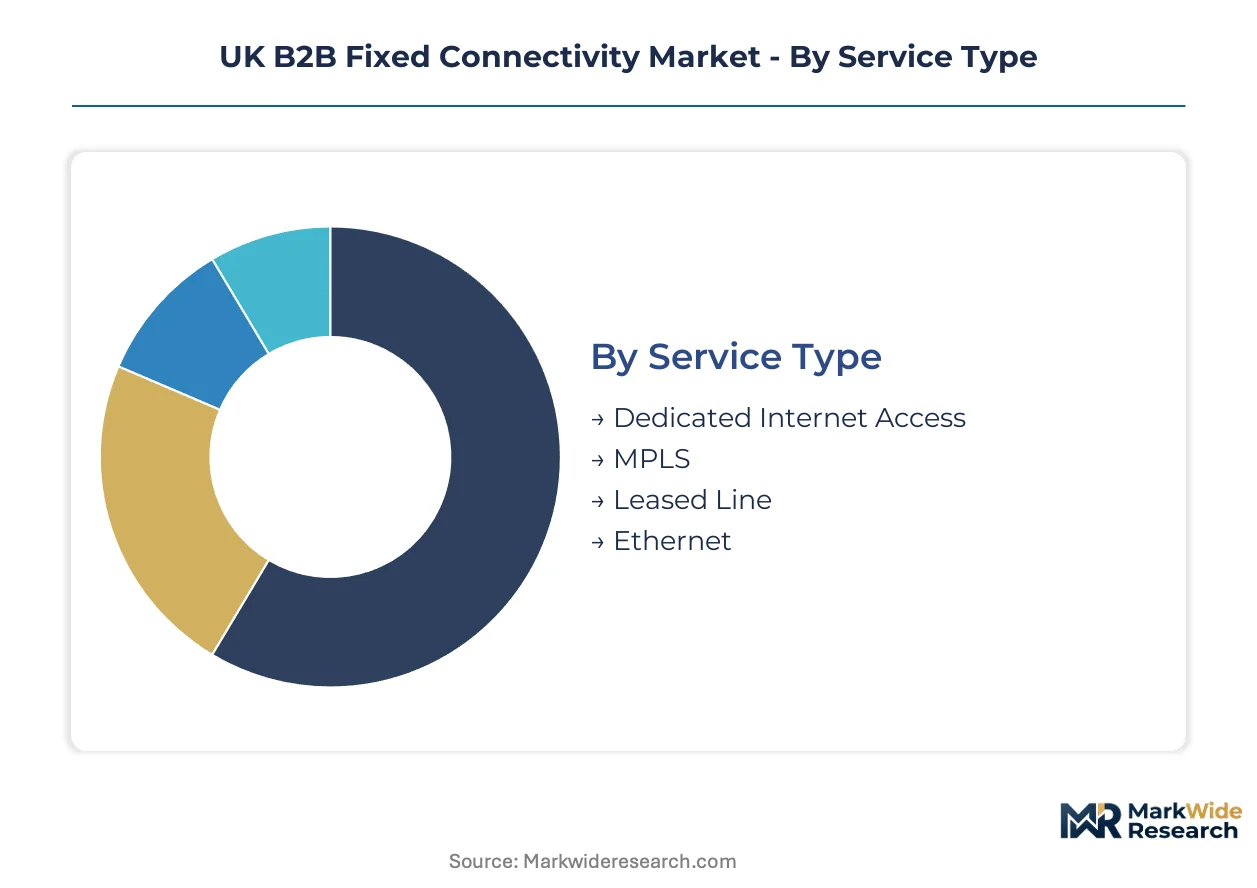
Enterprise procurement teams segment UK B2B fixed connectivity by technical specifications, operational requirements, and consumption models. Each dimension carries distinct margin profiles and competitive intensity that reshape vendor positioning across London's financial district and regional industrial clusters.
Service Type:
SD-WAN substitution pressure weighs heaviest on legacy MPLS circuits as enterprises renegotiate multi-site contracts.
- Dedicated Internet Access:Symmetric fiber-delivered circuits with committed bandwidth guarantees and sub-millisecond latency specifications. Financial institutions in London's Square Mile procure these for real-time payment infrastructure where jitter tolerance approaches zero.
- Ethernet:Scalable point-to-point or multipoint services enabling bandwidth increments from 10Mbps to 10Gbps. Manufacturing estates in the West Midlands deploy Ethernet for automated production line connectivity requiring predictable throughput.
- Leased Line:Contention-free private circuits with dual-path routing options for resilience mandates. NHS trusts specify these for patient data transmission between hospitals and primary care networks.
- MPLS:Label-switched private networks with quality-of-service prioritization. Retail chains maintain MPLS for legacy point-of-sale systems though migration timelines accelerate toward software-defined alternatives.
Dedicated Internet Access retains volume leadership; Ethernet holds the steepest expansion curve.
End User:
Procurement sophistication varies sharply across verticals, with financial services demanding bespoke SLA terms unavailable to mid-market buyers.
- Financial Institutions:Investment banks and clearing houses require symmetric fiber with 99.999% uptime guarantees and sub-millisecond latency to trading venues. Ofcom's wholesale pricing review directly conditions their leased line expenditure.
- Healthcare Providers:NHS trusts and private hospital networks mandate dual-path routing for clinical system resilience. Patient data digitization drives leased line procurement despite budget constraints from NHS England capital allocations.
- Manufacturers:Industrial IoT sensor networks and automated quality control systems consume scalable symmetric bandwidth. Automotive suppliers in the Midlands represent underpenetrated demand relative to financial services saturation.
- Retail Chains:Multi-site operators balance MPLS legacy dependencies against SD-WAN migration economics. Warehouse robotics and inventory management systems shift procurement toward Ethernet over DSL alternatives.
Financial Institutions command premium pricing tiers; Manufacturers present the widest whitespace opportunity.
Technology:
Last-mile infrastructure economics concentrate vendor investment toward fiber overbuilds as DSL residual value collapses.
- Fiber Optic:Full-fiber-to-the-premises deployment with GPON or dedicated point-to-point architectures. Project Gigabit subsidies accelerate availability timelines in underserved counties across England and Wales.
- Fixed Wireless:Microwave and millimeter-wave point-to-point links bypassing street-level civil engineering. Industrial estates with wayleave access friction deploy these for rapid activation against fiber construction delays.
- DSL:Copper-pair based asymmetric services with declining procurement relevance. Legacy estates face stranded asset pressure as enterprises abandon sub-100Mbps options for cloud-first architectures.
- Satellite:Geostationary and low-earth-orbit constellations serving rural enterprise locations beyond fiber economic reach. Scottish Highlands and Welsh border enterprises represent primary addressable demand.
Fiber Optic dominates new contract value; Fixed Wireless captures the most rapid deployment velocity.
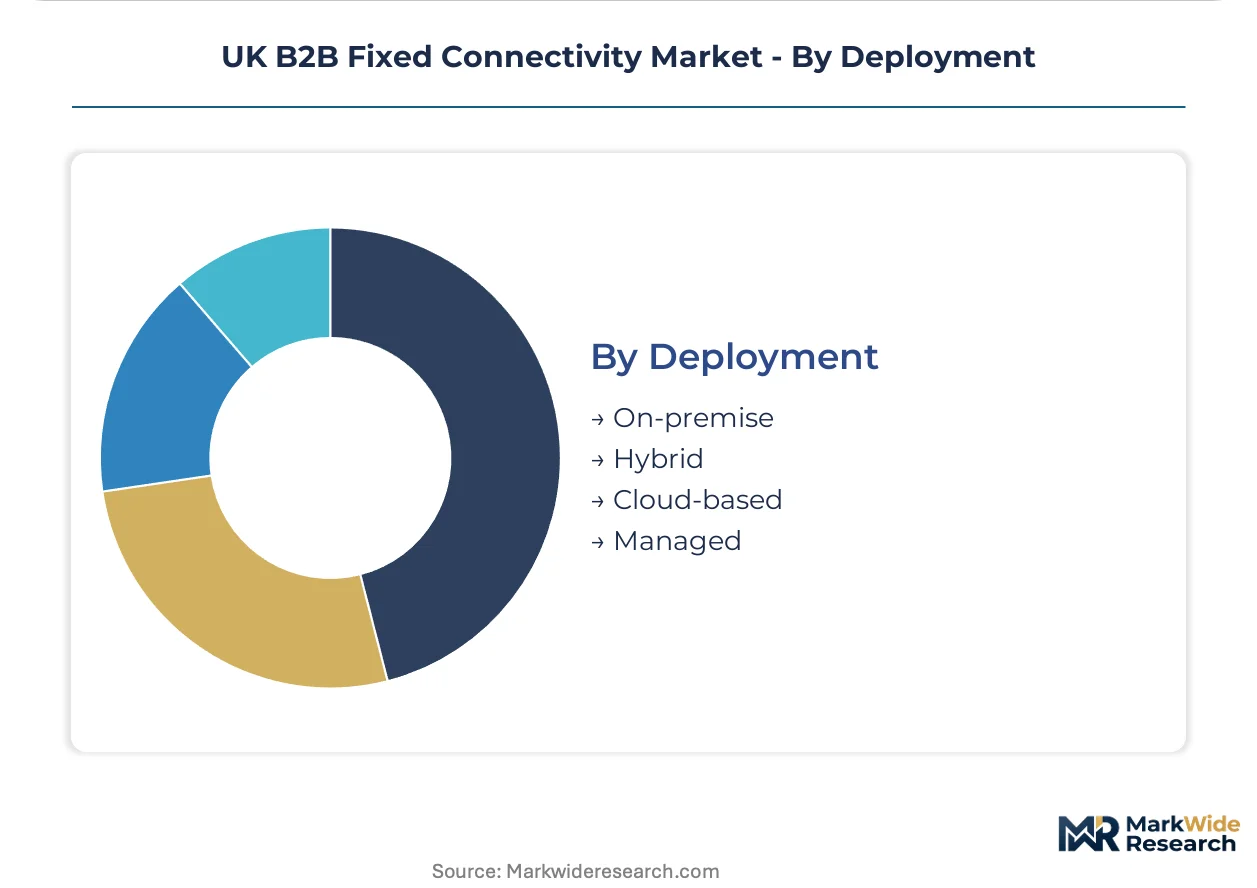
Deployment:
Enterprise IT capabilities determine unbundling preferences between raw connectivity and managed service integration.
- Managed:Fully outsourced network operations including monitoring, maintenance, and SLA enforcement. Mid-market retailers lacking internal engineering capacity procure these bundled packages.
- Cloud-based:API-driven bandwidth scaling with direct cloud interconnection to AWS, Azure, and GCP. Technology verticals in Manchester's tech corridor favor consumption-based alternatives to long-term commitments.
- Hybrid:Combined on-premise and cloud connectivity with SD-WAN orchestration across transport types. Logistics operators deploy these for application-aware routing between warehouses and cloud ERP systems.
- On-premise:Customer-operated CPE with dedicated physical infrastructure. Defense contractors and government agencies mandate these for security classification requirements.
Managed services retain contract volume leadership; Cloud-based deployment exhibits the sharpest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UK connectivity infrastructure exports asymmetrically to EU financial centers seeking low-latency London access. Cross-border circuit demand concentrates between London's Square Mile and Frankfurt's banking district.
London and the Southeast
Financial institutions in the Square Mile and Canary Wharf drive symmetric fiber procurement for real-time payment infrastructure. Ofcom's wholesale pricing review directly conditions leased line expenditure across the capital. Tech corridor expansion in Reading and Slough absorbs excess fiber capacity from London core builds.
Midlands
Automotive suppliers and advanced manufacturing estates in the West Midlands consume scalable Ethernet for industrial IoT sensor networks. Project Gigabit subsidies accelerate full-fiber deployment timelines across Staffordshire and Warwickshire. Birmingham's enterprise zone attracts altnet overbuilds ahead of Openreach completion schedules.
North England
Manchester's emerging tech corridor concentrates fintech and media enterprise demand for cloud-first connectivity. CityFibre and altnets establish wholesale dominance before incumbent overbuilds finalize. Leeds and Liverpool healthcare trusts mandate dual-path leased lines for NHS digitization programs.
Scotland
Edinburgh's asset management sector and Glasgow's public sector networks drive divergent procurement patterns across the central belt. Building Digital UK program funding extends full-fiber timelines to Aberdeen's energy sector and Dundee's life sciences cluster. Scottish Highlands enterprises rely on satellite and fixed wireless where fiber economics fail.
Wales
Cardiff's public sector and Swansea's manufacturing bases anchor demand within constrained infrastructure budgets. Project Gigabit subsidies target underserved counties in North Wales and rural Powys. Welsh border enterprises face satellite dependency where altnet overbuilds remain uneconomic.
UK B2B Fixed Connectivity Market Competitive Landscape
Listed leaders compete with private specialists across infrastructure ownership models. BT Group and Vodafone operate as publicly traded entities with wholesale and retail divisions, while CityFibre and altnets function as private infrastructure investors. The market structures around three archetypes: incumbent integrated operators with passive infrastructure control, altnet pure-play fiber builders, and mobile-centric carriers with fixed-line extensions. Competitive moves concentrate on fiber overbuild velocity in regional cities and strategic partnerships for SD-WAN service packaging.
Within the incumbent tier, BT Group and Vodafone occupy positions shaped by legacy infrastructure access and multinational account relationships. Virgin Media Business exemplifies cable-based competition through hybrid fiber-coaxial coverage density. Among altnet specialists, CityFibre represents the pure-fiber overbuild model targeting regional city wholesale dominance. KCOM Group anchors the geographic specialist archetype with historical concentration in Hull and surrounding regions.
| Leading Market Players |
|---|
| BT Group |
| Vodafone Limited |
| Virgin Media Business Ltd |
| Sky UK Limited |
| Openreach |
| CityFibre |
| KCOM Group Limited |
| XLN Telecom Ltd |
| TalkTalk |
| Others |
Pricing and Supply Chain Analysis
Ninety-day fiber installation lead times concentrate pricing power with Openreach and CityFibre in dense metropolitan corridors, while sparse regional coverage forces buyers toward premium fixed-wireless alternatives. This supply asymmetry stratifies contract values across London's financial district and peripheral manufacturing estates.
Pricing Analysis
Fiber-to-the-premises deployment commands a three-to-one premium over legacy copper DSL, with symmetric dedicated internet access separating financial institutions from price-sensitive mid-market retailers. Pricing stratifies across premium, standard, and economy tiers based on latency guarantees and SLA uptime thresholds. Cost compression in Ethernet segments intensifies as CityFibre and altnets undercut Openreach wholesale rates. Retail chains exhibit highest price sensitivity, while investment banks absorb premium fiber pricing for sub-millisecond trading venue connectivity.
Supply Chain Analysis
Just-in-time fiber deployment dominates in London and Manchester where duct access permits rapid customer activation, while strategic civil engineering stockpiles anchor regional city overbuilds ahead of demand confirmation. Optical fiber and GPON equipment draw from China, USA, and Japan. Supply chain vulnerability centers on single-source dependency for specialized splicing equipment. Distribution runs through wholesale fiber exchanges and direct enterprise sales teams with managed service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement fragmentation creates specialist opportunities as SD-WAN unbundling dismantles integrated connectivity packages. Mid-market buyers now separate raw bandwidth from managed service wrappers.
For Market Incumbents: Secure wholesale fiber dominance through accelerated regional city overbuilds ahead of altnet completion schedules. Defend MPLS revenue streams by embedding SD-WAN orchestration into legacy contract renewals before software-defined substitution accelerates. Vertical integration into passive infrastructure through duct and dark fiber ownership anchors margin defense against Ofcom's standardized access pricing. For New Entrants and Emerging Players: Managed SD-WAN service gaps in Manchester and Birmingham tech corridors expose incumbent under-service of mid-market enterprises lacking internal network engineering capacity. Target healthcare trusts in Leeds and Liverpool requiring dual-path leased line resilience for NHS digitization programs. Lead with API-driven bandwidth scaling and direct cloud interconnection to differentiate from incumbent managed service bundles. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because fiber assets generate contracted revenue streams with regulatory-supported returns. Acquisition candidates include altnet specialists with concentrated regional city wholesale positions and strategic duct holdings. Watch CityFibre's wholesale partnership traction with mobile operators as signal of sustainable competitive positioning against Openreach scale.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Overbuild Acceleration | CityFibre and altnets establish wholesale dominance before Openreach completes regional deployments. |
| SD-WAN Service Packaging | Managed service bundling captures mid-market buyers abandoning legacy MPLS private circuits. |
| Cloud Interconnection Partnership | Direct AWS, Azure, and GCP peering addresses enterprise cloud-first architecture migration requirements. |
| Healthcare Network Resilience Contracting | NHS trust dual-path mandates create structural demand for leased line providers with clinical system expertise. |
| Fixed Wireless Rapid Deployment | Microwave and millimeter-wave links bypass wayleave friction for industrial estates facing fiber construction delays. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Ofcom regulatory filings, Openreach wholesale price controls, and Project Gigabit subsidy disclosures. Network operator executives, enterprise IT procurement officers, and fiber infrastructure engineers provided qualitative input. Data triangulates bottom-up contract value analysis with top-down market sizing across service type, end user vertical, and technology deployment dimensions.
Segmentation dimensions modeled encompass service type, end user industry, last-mile technology, and deployment architecture across the projection horizon. CAGRs derive from installed base migration curves, replacement cycle timing, and elasticity responses to wholesale pricing shifts. Forecast inputs incorporate fiber penetration trajectories in regional cities and SD-WAN substitution rates in multi-site enterprise accounts.
Forecasts assume regulatory continuity in Ofcom's wholesale fixed telecoms market review and Building Digital UK program commitments; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as altnet funding costs and wayleave access friction evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Network Management Solutions Market
Network Technology
Wimax Solutions Market
Network Technology
Network Performance Monitoring Market
Network Technology
Fiber to the Premises Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Cloud Managed Access Points Market
Network Technology
Application Delivery Controller (ADC) Market
Network Technology
Wi-Fi 6E Router Market
Network Technology
Global Network Probe Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Europe Private 5G Network Market
Network Technology
Digital Repeater Market
Network Technology
CPE Router Market
Network Technology
Wireless Infrastructure Monitoring Market
Network Technology
Global Active Network Management Market