
 Asia-Pacific Digital Marketing Software Market | 2026-2036
Asia-Pacific Digital Marketing Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Marketing Software Market Analytics
Mid-market retailers and direct-to-consumer brands is rotating toward integrated campaign management suites as enterprise buyers extend contract cycles. Salesforce.com Inc anchors its position through deep CRM-to-advertising workflow integration across Southeast Asian markets. HubSpot Inc competes by sustaining product-led growth motion with freemium tiers calibrated for APAC price sensitivity. Adobe Inc dominates creative-to-analytics pipelines, leveraging its content production heritage to extend into performance marketing orchestration.
Asia-Pacific digital marketing software encompasses cloud-native and on-premises platforms that automate audience segmentation, campaign execution, and attribution measurement through API-connected data pipelines and machine learning-driven personalization engines. These systems process real-time behavioral signals to optimize media spend and customer lifetime value for brands operating across fragmented channel ecosystems. CRM Software and Analytics Tools command the deepest margin pools, as buyers prioritize unified customer data layers over point solutions. Cloud-Based deployment leads volume uptake, though Hybrid Solutions gain traction among financial services and healthcare entities navigating China's data-localization mandates and India's cross-border data flow restrictions.
China's Personal Information Protection Law, India's Digital Personal Data Protection Act, and Japan's Act on Protection of Personal Information collectively reshape product architecture, forcing vendors to engineer region-specific data residency modules and consent-management frameworks. TRAI's spam-monitoring directives and Australia's Spam Act further constrain outbound marketing automation, elevating demand for compliant deliverability infrastructure. Stakeholders must weigh localization investment against platform standardization as regulatory fragmentation deepens across the region.
Market Dynamics
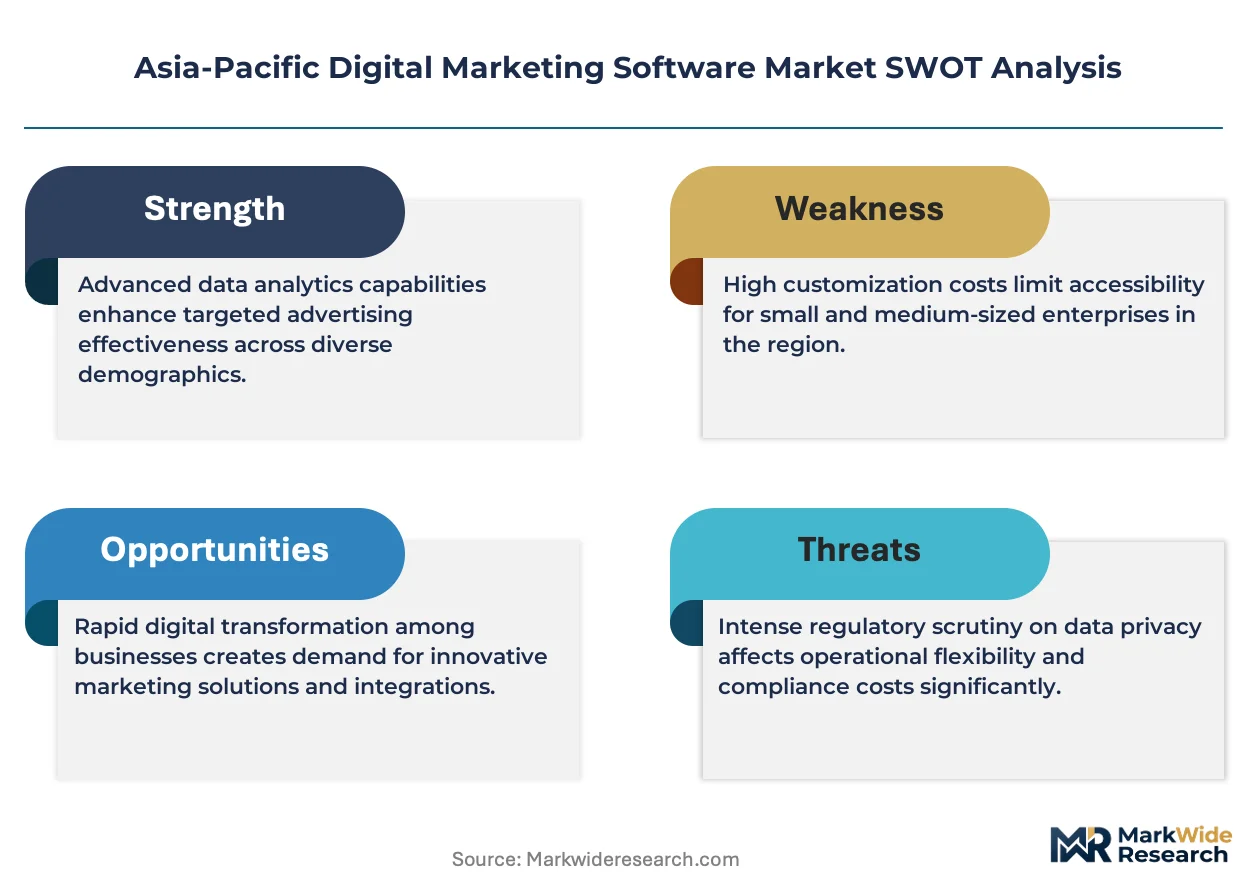
Consent-management infrastructure is fragmenting platform architectures across Asia-Pacific as China's Personal Information Protection Law and India's Digital Personal Data Protection Act force vendors to engineer jurisdiction-specific data residency modules rather than unified regional stacks.
Growth Catalysts
- SME Digitalization Programs:India's government-backed technology adoption initiatives are accelerating procurement cycles among mid-market retailers seeking integrated campaign management suites.
- Cross-Border E-Commerce Expansion:Direct-to-consumer brands across Southeast Asia are consolidating point solutions into cloud-native orchestration platforms to manage fragmented channel ecosystems.
- API-Connected Data Pipelines:Machine learning-driven personalization engines are automating real-time behavioral signal processing for brands optimizing media spend across multiple touchpoints.
Market Restraints
- Data Localization Mandates:China's cross-border data flow restrictions and India's storage requirements are inflating infrastructure costs for vendors maintaining hybrid deployment architectures.
- Consent Framework Fragmentation:Japan's Act on Protection of Personal Information diverges from PIPL and DPDPA compliance protocols, forcing redundant engineering investment.
- Deliverability Infrastructure Constraints:TRAI's spam-monitoring directives and Australia's Spam Act are compressing outbound marketing automation capabilities for financial services and healthcare entities.
Strategic Opportunities
- Underpenetrated Indonesian Market:Mid-market retailers in Indonesia remain underserved by integrated CRM-to-advertising workflow solutions, creating whitespace for localized platform entry.
- Healthcare Compliance Tailwinds:India's Digital Personal Data Protection Act is elevating demand for consent-management frameworks specifically engineered for patient data marketing use cases.
- Creative-to-Analytics Convergence:Content production heritage platforms are extending into performance marketing orchestration by unifying creative asset management with attribution measurement.
Industry Challenges
- Machine Learning Engineering Talent Scarcity:Vendors face acute shortages of data scientists capable of building region-specific personalization engines compliant with divergent privacy regimes.
- Legacy CRM Integration Complexity:Enterprise buyers extending contract cycles are demanding seamless API connectivity with entrenched on-premises customer databases, stretching implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Marketing Software Market |
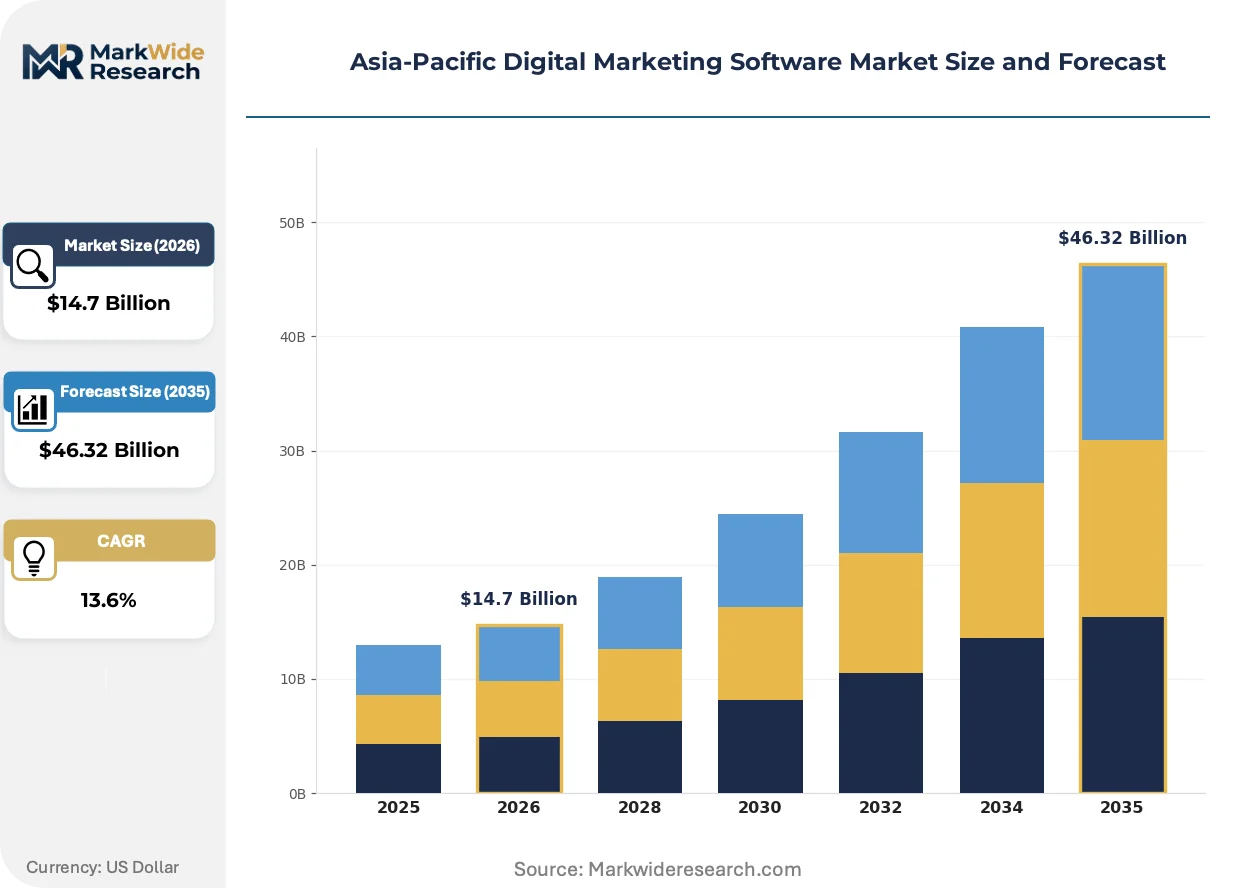
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $46.32 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytics Tools, CRM Software, Content Management Systems, Email Marketing Software Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Managed Services End User: SMEs, Large Enterprises, Marketing Agencies, E-Commerce Service Type: Consulting, Integration, Support & Maintenance, Training |
| Companies Covered | Adobe Inc, Google LLC, HubSpot Inc, Oracle Corporation, IBM Corporation, Microsoft Corporation, Salesforce.com Inc, SAS Institute Inc, Marketo Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Marketing Software Market Evolving Landscape
Composable architecture is displacing monolithic platform suites as Asia-Pacific buyers prioritize modular API connectivity over end-to-end vendor lock-in. This shift is compressing traditional software procurement cycles and elevating integration specialists.
Composable customer data platforms are decomposing legacy marketing cloud architectures by enabling brands to assemble best-of-breed segmentation, execution, and attribution components through standardized APIs. Mid-market retailers in India and Southeast Asia are adopting this approach fastest, driven by price sensitivity and the need to swap vendors as regulatory requirements evolve. The structural consequence is margin compression for full-stack incumbents as integration layers capture value previously monopolized by suite vendors.
China's Personal Information Protection Law is mandating granular consent collection and purpose limitation for all behavioral data processing, forcing vendors to rebuild data pipelines with audit-ready lineage tracking. Industrial consequence includes delayed product launches as engineering teams localize core infrastructure. Financial services entities in Shanghai and Shenzhen are most affected, responding by procuring region-specific instances rather than global platform subscriptions.
Mid-market buyers are consolidating vendor relationships from an average of twelve point solutions to four integrated platforms, prioritizing unified customer data layers over specialized functionality. This concentration is displacing niche attribution and email service providers in favor of CRM-anchored suites. The pattern is most visible among direct-to-consumer brands in India, where procurement teams negotiate enterprise-grade contracts previously reserved for multinational corporations.
Asia-Pacific Digital Marketing Software Market Segmentation
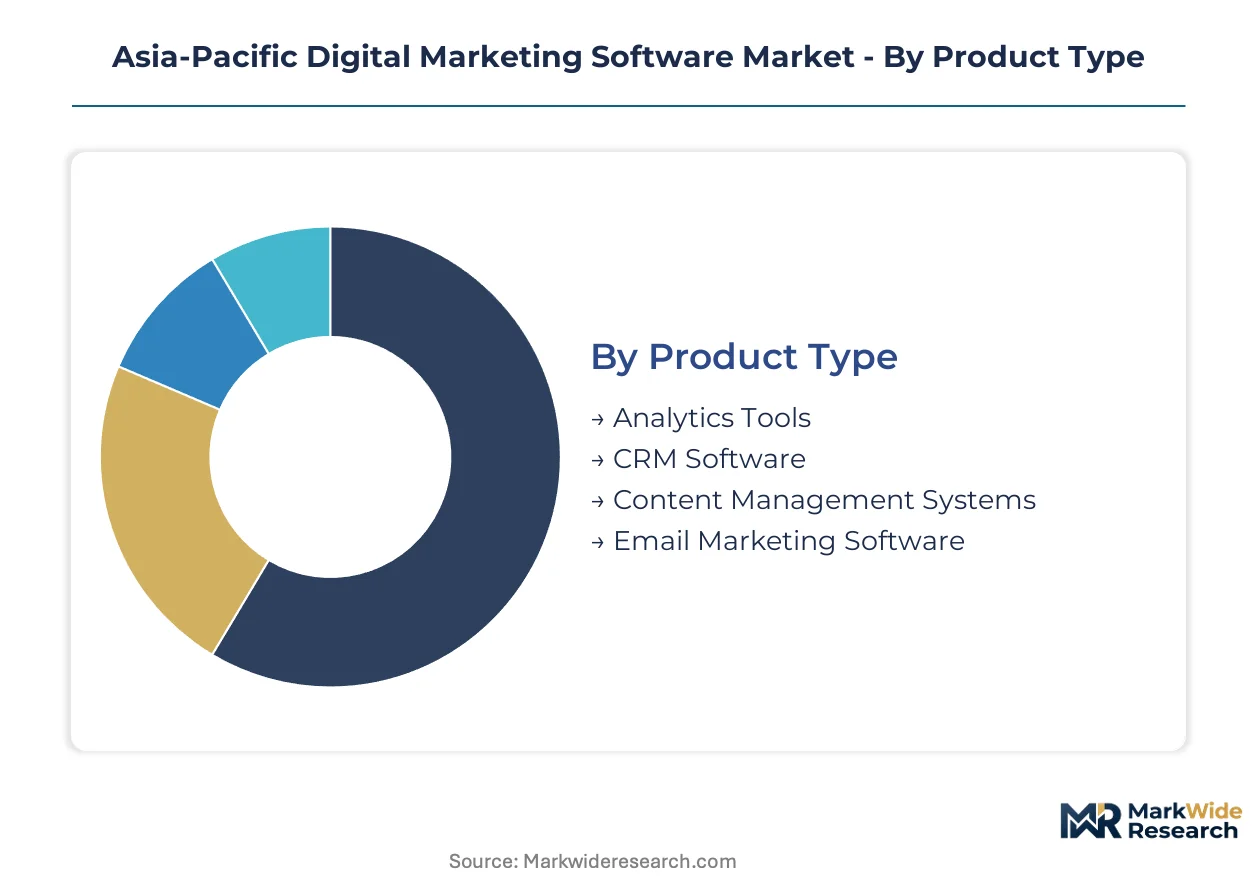
Asia-Pacific digital marketing software procurement patterns diverge sharply across buyer sophistication tiers and regulatory exposure levels. Segmentation reveals how China's data-localization mandates and India's consent frameworks reshape deployment preferences and service bundling across the region.
Product Type:
Regulatory differentiation across China's PIPL, India's DPDPA, and Japan's APPI fragments data-processing capabilities required in each segment, forcing vendors to engineer jurisdiction-specific modules rather than unified regional architectures.
- Analytics Tools:Machine learning-driven attribution engines process real-time behavioral signals across fragmented channel ecosystems. Financial services entities in Shanghai and Mumbai prioritize these for media spend optimization while navigating divergent cross-border data flow restrictions.
- CRM Software:Unified customer data layers anchor enterprise procurement decisions, with API-connected pipelines enabling segmentation across touchpoints. India's SME digitalization programs and government-backed technology adoption initiatives accelerate mid-market procurement cycles for integrated suites.
- Content Management Systems:Creative asset repositories with localized deployment options serve brands managing China's storage requirements.
- Email Marketing Software:Compliant deliverability infrastructure addresses TRAI spam-monitoring directives and Australia's Spam Act constraints.
CRM Software handles the majority of throughput; Analytics Tools is the fastest mover on share.
Deployment:
Cost tier stratification separates volume uptake from margin concentration, with cloud-native architectures dominating mid-market budgets while hybrid configurations command premium pricing from regulated sectors.
- Cloud-Based:API-native orchestration platforms enable modular best-of-breed assembly through standardized interfaces. Mid-market retailers in India and Southeast Asia adopt this approach fastest, driven by price sensitivity and vendor swap flexibility as regulatory requirements evolve.
- Hybrid Solutions:Split architectures separate customer data residency from processing layers to satisfy China's cross-border restrictions and India's storage mandates. Financial services and healthcare entities in Shanghai, Shenzhen, and Mumbai procure these configurations despite inflated infrastructure costs.
- On-Premises:Entrenched legacy databases at enterprise buyers demand seamless API connectivity, stretching implementation timelines.
- Managed Services:Outsourced compliance management addresses consent-framework fragmentation across Japan, China, and India.
Cloud-Based deployment captures the volume base; Hybrid Solutions commands the steepest expansion trajectory among regulated verticals.
End User:
Customer type determines integration complexity tolerance, with enterprise buyers extending contract cycles while SMEs consolidate vendor relationships from twelve point solutions toward four integrated platforms.
- SMEs:Procurement teams negotiate enterprise-grade contracts previously reserved for multinational corporations, prioritizing unified customer data layers over specialized functionality. India's government-backed initiatives accelerate this concentration pattern among direct-to-consumer brands.
- Large Enterprises:Extended contract cycles demand seamless API connectivity with entrenched on-premises customer databases, stretching implementation timelines and favoring CRM-anchored suites over niche providers.
- Marketing Agencies:Multi-tenant platform requirements drive demand for composable architectures with modular vendor swapping capability.
- E-Commerce:Cross-border expansion across Southeast Asia consolidates point solutions into orchestration platforms managing fragmented channel ecosystems.
SMEs are expanding most quickly on platform adoption; Large Enterprises retains the deepest contract values.
Service Type:
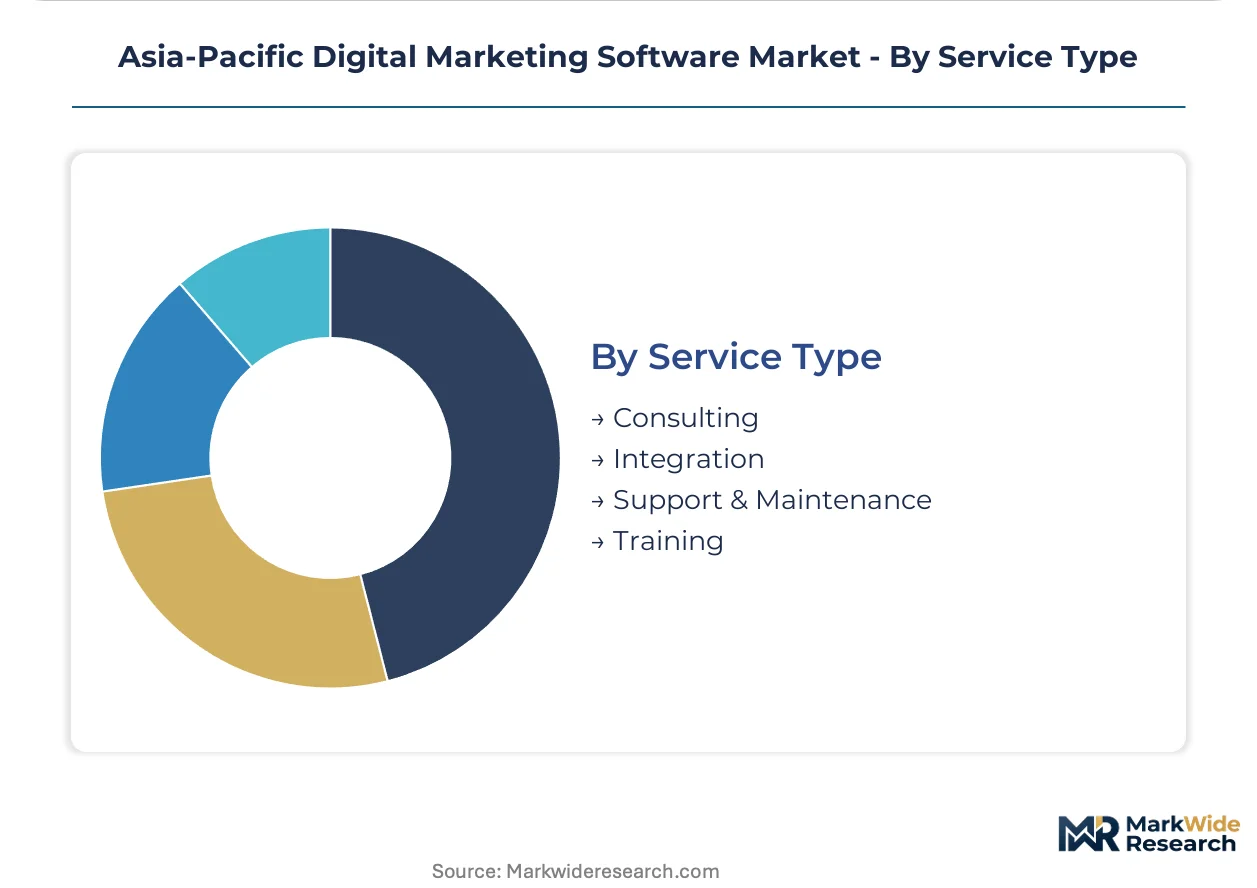
Supply concentration among integration specialists elevates value capture for technical implementation services as composable architectures displace monolithic suites.
- Integration:API connectivity engineering captures value previously monopolized by full-stack vendors, with specialists commanding premium positioning as mid-market buyers prioritize modular assembly over end-to-end lock-in.
- Consulting:Jurisdiction-specific compliance strategy addresses PIPL, DPDPA, and APPI divergence, requiring region-specific data residency and consent-management framework design.
- Support & Maintenance:Audit-ready lineage tracking mandates ongoing infrastructure oversight for behavioral data processing compliance.
- Training:Machine learning engineering talent scarcity elevates demand for data scientist capability building in region-specific personalization engine development.
Integration services command the strongest margin expansion; Consulting is climbing the fastest on regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports digital marketing infrastructure services to Southeast Asian e-commerce platforms, while India supplies SaaS talent and implementation capacity to Australian and Singaporean enterprise buyers.
China
Shanghai and Shenzhen financial services entities drive demand for consent-management frameworks compliant with the Personal Information Protection Law. MIIT data-localization mandates force vendors to maintain region-specific instances rather than global platform subscriptions. Shenzhen-based fintech clusters procure hybrid deployment architectures to satisfy cross-border data flow restrictions.
India
Mid-market retailers in Mumbai and Bangalore accelerate procurement through government-backed SME digitalization programs. TRAI spam-monitoring directives elevate demand for compliant deliverability infrastructure among outbound marketing automation users. Bangalore's technology corridor concentrates vendor engineering centers building region-specific personalization engines.
Japan
Tokyo-based direct-to-consumer brands consolidate point solutions into orchestration platforms managing fragmented channel ecosystems. METI-aligned Act on Protection of Personal Information diverges from PIPL and DPDPA protocols, forcing redundant consent-framework engineering. Osaka's industrial marketing clusters favor CRM-anchored suites with API connectivity to entrenched legacy databases.
Australia
Sydney and Melbourne marketing agencies adopt composable architectures enabling modular vendor swapping as regulatory requirements evolve. The Spam Act constrains outbound automation capabilities, compressing deliverability infrastructure options. Sydney's financial services precinct procures cloud-native orchestration platforms with audit-ready lineage tracking.
Indonesia
Jakarta mid-market retailers remain underserved by integrated CRM-to-advertising workflow solutions, creating whitespace for localized platform entry. The national data protection framework under development elevates demand for jurisdiction-specific data residency modules. Surabaya's emerging e-commerce clusters consolidate vendor relationships from multiple point solutions toward unified customer data layers.
Asia-Pacific Digital Marketing Software Market Competitive Landscape
Listed leaders compete with private specialists across cloud-native deployment and hybrid infrastructure dimensions. Market structure tilts toward consolidated suites at the enterprise tier and fragmented point solutions among mid-market buyers. Three archetypes dominate: full-stack incumbents with creative-to-analytics pipelines, CRM-anchored workflow integrators, and composable platform specialists. Competitive moves concentrate on M&A to absorb consent-management capabilities and strategic partnerships to localize data residency modules.
Among United States-based technology conglomerates, Adobe Inc and Salesforce.com Inc exemplify divergent positioning archetypes. Adobe occupies a position representing creative-to-analytics convergence, while Salesforce anchors the CRM-to-advertising workflow integration tier. HubSpot Inc exemplifies the product-led growth motion calibrated for APAC price sensitivity.
| Leading Market Players |
|---|
| Adobe Inc |
| Google LLC |
| HubSpot Inc |
| Oracle Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Salesforce.com Inc |
| SAS Institute Inc |
| Marketo Inc |
| Others |
Value Network & Pricing Analysis
Cloud-native infrastructure scale economies in India and Southeast Asia compress unit economics for API-connected data pipelines while simultaneously elevating price floors for hybrid deployment architectures serving China's MIIT data-localization mandates. This bifurcation concentrates margin capture among vendors maintaining jurisdiction-specific instances rather than unified regional stacks.
Pricing Analysis
Current-generation cloud-native orchestration platforms command premium positioning against prior-generation on-premises suites and emerging next-gen composable architectures still in beta deployment. Three-tier pricing structure across enterprise-grade integrated suites, mid-market SaaS tiers, and freemium entry points dominates procurement patterns, with certification level for PIPL and DPDPA compliance emerging as the primary price differentiation driver. Pricing pressure stems from mid-market retailers consolidating twelve point solutions toward four integrated platforms, squeezing niche attribution vendors. SMEs exhibit acute price sensitivity, while large enterprises in Shanghai and Mumbai absorb premium hybrid-configuration costs.
Supply Chain Analysis
Inbound logistics costs through Singapore and Hong Kong container hubs constrain hardware-dependent edge-deployment infrastructure for financial services entities requiring localized data residency. Engineering talent concentrates in India, China, and Singapore, with Bangalore and Shenzhen anchoring machine-learning personalization engine development. Raw material dependencies span GPU compute clusters, API middleware licenses, and consent-management framework modules. Single-source vulnerability sits with NVIDIA-dominated AI training hardware for behavioral signal processing. Distribution runs through direct enterprise sales teams in Mumbai and Tokyo alongside cloud marketplace channels for mid-market self-service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific digital marketing software represents a high-growth disruption propelled by India's SME digitalization programs intersecting with China's PIPL-mandated infrastructure rebuilds. Regulatory fragmentation across PIPL, DPDPA, and APPI creates permanent product-architecture complexity that rewards localized engineering investment.
For Market Incumbents: Shield CRM-anchored workflow integration against composable platform displacement by accelerating jurisdiction-specific data residency module deployment ahead of DPDPA enforcement timelines. Deepen API connectivity engineering capabilities to capture integration-layer value previously monopolized by full-stack positioning. Prioritize Bangalore and Shenzhen engineering center expansion to address machine-learning talent scarcity constraining competitor personalization engine development. For New Entrants and Emerging Players: Lead with compliant deliverability infrastructure targeting Jakarta mid-market retailers underserved by integrated CRM-to-advertising workflow solutions. Indonesia's national data protection framework under development creates whitespace for localized platform entry ahead of incumbent localization investment. Pursue product-led growth motion with freemium tiers calibrated for APAC price sensitivity, mirroring HubSpot's regional penetration strategy. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among consent-management framework specialists serving healthcare and financial services verticals navigating India's DPDPA patient-data marketing requirements. Long-term viability over a five-to-ten year window favors vendors with established China-region-specific instances rather than global platform subscriptions vulnerable to MIIT cross-border data flow restrictions. Monitor TRAI spam-monitoring directive enforcement intensity as a signal for outbound marketing automation capability compression and compliant infrastructure demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Consent-Management Framework Acquisition | Absorbs specialized PIPL and DPDPA compliance capabilities ahead of regulatory enforcement timelines. |
| Hybrid Deployment Architecture Launch | Captures premium pricing from Shanghai and Mumbai financial services entities navigating data-localization mandates. |
| API-Native Platform Integration | Enables modular best-of-breed assembly for price-sensitive mid-market retailers consolidating vendor relationships. |
| Indonesia Market Entry Partnership | Establishes localized presence in Jakarta ahead of national data protection framework formalization. |
| Machine-Learning Engineering Center Expansion | Addresses acute data scientist scarcity constraining region-specific personalization engine development. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs at direct-to-consumer brands, IT procurement officers at Mumbai financial services entities, platform engineers building consent-management frameworks, and integration specialists serving Southeast Asian e-commerce platforms. Secondary validation drew from MIIT data-localization filings, TRAI spam-monitoring directives, SEC 10-K disclosures from listed software vendors, and hyperscaler capex allocation reports. Bottom-up sizing of deployment-model segments triangulated against top-down regional IT spend aggregates.
Across the analysis window, the forecasting framework modeled product-type segmentation spanning CRM software, analytics tools, content management systems, and email marketing platforms alongside deployment-model dimensions of cloud-native, hybrid, on-premises, and managed services. CAGRs were derived from regression analysis of historical procurement velocity against regulatory inflection timing. Industry-specific inputs included SME digitalization program budget allocations and cross-border e-commerce expansion rates across Southeast Asian markets.
The analysis sits within stated boundaries; outcomes outside sustained government technology adoption funding or accelerated PIPL enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding machine-learning engineering talent availability and container-hub logistics stability. Model outputs assume no fundamental relaxation of China's cross-border data flow restrictions or India's storage mandates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Game Engines Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Farm Management Software Market
Digital Solutions
Data Converter Market
Digital Solutions
Construction Design App Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Smart Government Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Enterprise Content Management (ECM) Market