
 Change Management Software Market | 2026-2036
Change Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Change Management Software Market Intelligence
North American enterprise software vendors is broadening the functional scope of change management platforms to encompass IT service operations, digital adoption, and workforce analytics. ServiceNow leverages deep IT workflow integration to anchor large-enterprise deployments across regulated industries. BMC Helix ITSM competes through specialized service-desk capabilities that sustain multi-cloud infrastructure transitions. Whatfix differentiates via in-application guidance layers that reduce training friction during software rollouts.
Change management software constitutes a category of enterprise applications designed to plan, execute, and monitor organizational transitions through structured workflows, risk scoring algorithms, and real-time stakeholder communication protocols. These systems integrate with HR information systems, project management tools, and compliance databases to maintain audit trails and measure adoption velocity. Cloud-based deployment leads solution delivery due to faster implementation cycles and lower total cost of ownership for mid-market buyers. Workflow automation within solution offerings captures concentrated margin pools because recurring licensing attaches to quantifiable efficiency gains. Employee engagement as an end-user segment shows accelerating traction as hybrid work models require persistent pulse-checking and feedback loops.
ISO 31000 risk management standards and the EU AI Act shape product development by mandating documented decision pathways for algorithmic and structural changes. HIPAA in the United States drives healthcare-specific demand for access-controlled change logs and breach-notification workflows. Stakeholders must evaluate how impending SEC climate disclosure rules will expand the scope of transformation tracking beyond operational efficiency into sustainability reporting integration.
Market Dynamics
Workflow automation engines are compressing implementation timelines from quarters to weeks, forcing incumbent vendors to re-architect deployment methodologies or surrender mid-market contracts to cloud-native challengers.
Growth Catalysts
- EU AI Act documentation mandates:European enterprises must maintain algorithmic decision audit trails, creating mandatory procurement of change-tracking platforms with embedded compliance modules.
- Healthcare workforce digitization:HIPAA-covered entities in the United States are deploying access-controlled change logs to satisfy breach-notification workflow requirements during EHR transitions.
- Automotive sector restructuring:German industrial conglomerates are standardizing workforce transition protocols as electrification programs displace traditional manufacturing roles at scale.
Market Restraints
- Cloud infrastructure concentration:Three hyperscale providers control critical hosting capacity, exposing buyers to service-continuity risks during platform migrations.
- ISO 31000 certification complexity:Documented risk-pathway requirements extend sales cycles by requiring specialized consultant involvement before procurement approval.
- Legacy ERP integration friction:On-premise SAP and Oracle installations resist API connectivity, forcing expensive middleware development for unified change visibility.
Strategic Opportunities
- SEC climate disclosure alignment:Pending sustainability reporting rules will expand transformation-tracking scope beyond operational efficiency into emissions-reduction workflow integration.
- Hybrid work pulse-checking:Persistent employee engagement monitoring represents underpenetrated functionality as distributed teams require asynchronous feedback mechanisms.
- AI-native workflow convergence:Natural-language change-request processing combined with predictive risk scoring creates differentiated positioning against rules-based incumbent systems.
Industry Challenges
- Change-management certification scarcity:Organizations lack sufficient Prosci or CCMP-credentialed practitioners to configure platform workflows effectively, delaying value realization.
- Multi-cloud orchestration complexity:Buyers operating across AWS, Azure, and Google Cloud environments struggle to maintain consistent change governance across divergent infrastructure APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Change Management Software Market |
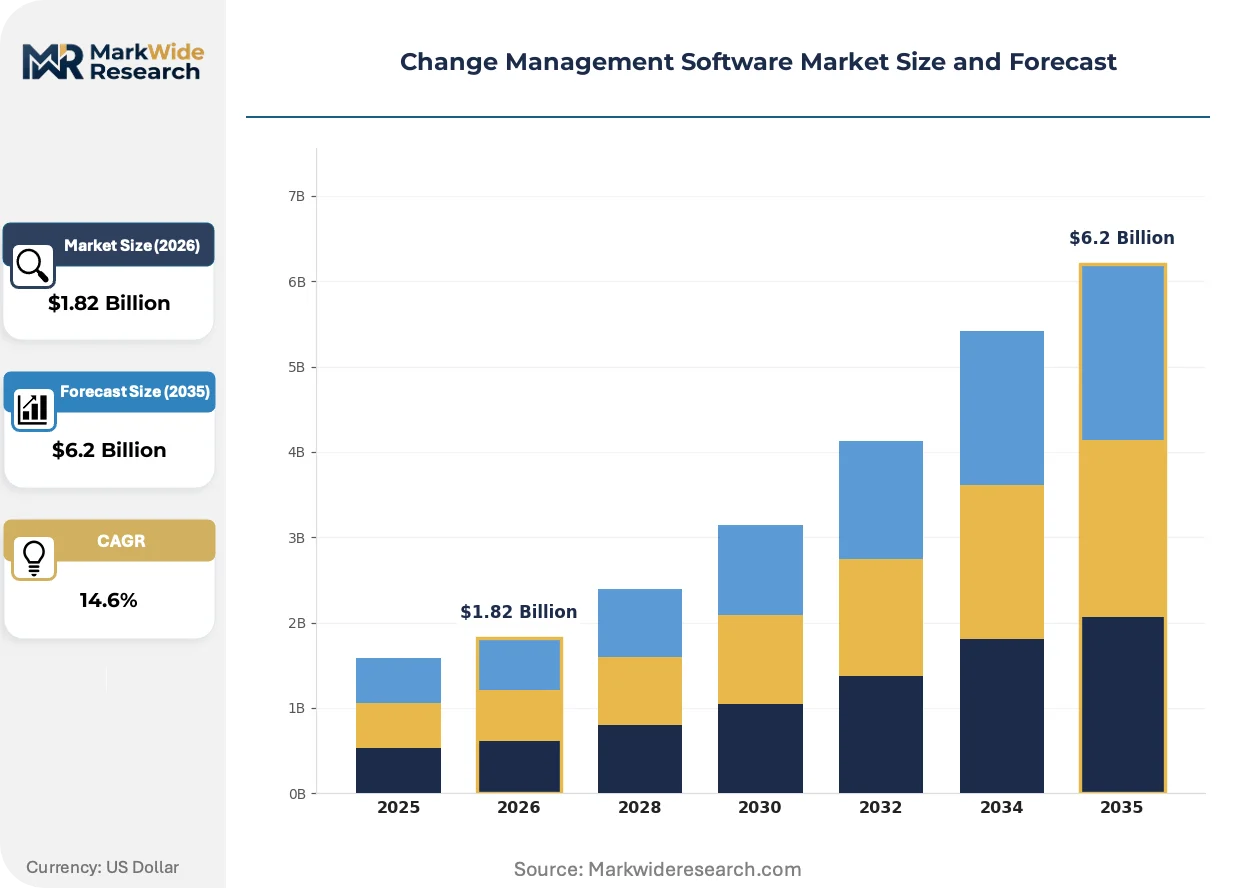
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $6.2 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Solution Offering: Workflow Automation, Risk Assessment, Training Management, Communication Tools, Reporting & Analytics Application: Organizational Transformation, Project Management, Compliance Management, Performance Improvement, Employee Engagement End User: IT Departments, Human Resources, Consulting Firms, Financial Institutions, Educational Institutions |
| Companies Covered | ServiceNow, Jira Service Management, Freshservice, BMC Helix ITSM, Whatfix, WalkMe, Prosci ADKAR Platform, ManageEngine ServiceDesk Plus, Wrike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Change Management Software Market Strategic Shifts & Innovations
Generative interfaces are compressing the distance between change intent and execution, eliminating traditional form-based request workflows in favor of conversational orchestration layers.
Embedded in-application guidance layers are rewriting how enterprises deploy software updates. These systems intercept user workflows at moment-of-need, delivering contextual instruction without disrupting productivity. Financial services and healthcare organizations with strict compliance requirements are adopting these tools fastest. The technology is rewriting training economics by collapsing onboarding from multi-week programs into hours of guided exploration.
The EU AI Act's risk-classification framework is mandating documented human oversight for high-stakes algorithmic changes. Organizations deploying machine-learning models in credit scoring, hiring, or medical diagnostics must now maintain immutable decision logs with explainable audit trails. German automotive manufacturers and French healthcare networks are investing most heavily in compliant workflow infrastructure to preempt enforcement action.
Subscription-based pricing for change-management capabilities is displacing perpetual-license models as buyers prioritize operational flexibility over capital ownership. Mid-market technology firms and professional services organizations are driving this transition, demanding consumption-aligned cost structures. The shift is most visible in North American and Nordic markets where SaaS penetration already exceeds legacy deployment rates.
Change Management Software Market Segmentation
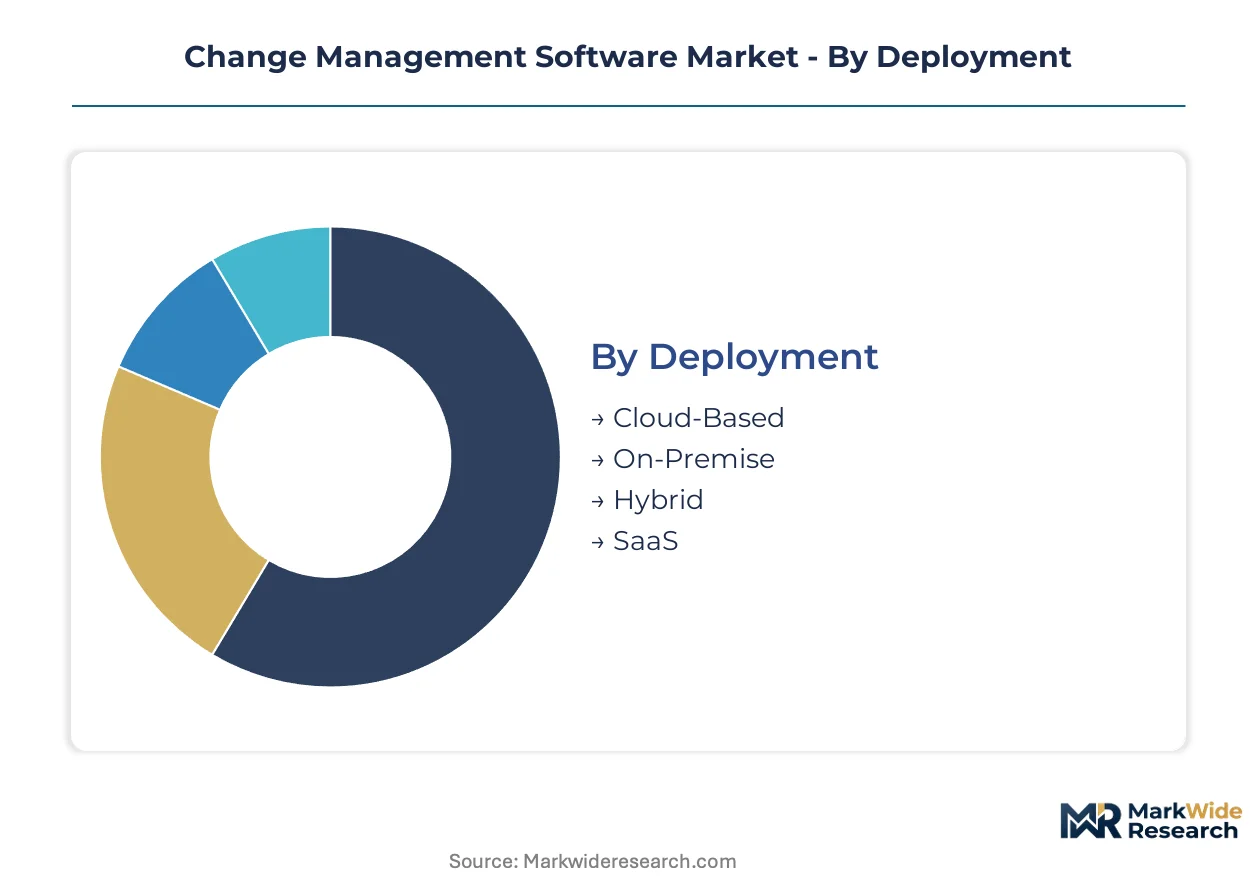
Change management software procurement hinges on matching deployment flexibility to organizational IT maturity, solution depth to transformation complexity, and end-user workflows to functional accountability. Buyers evaluate segments through the lens of implementation speed, compliance burden, and workforce scale rather than feature checklists alone.
Deployment:
Procurement teams weigh total cost of ownership against data sovereignty requirements when selecting hosting architecture.
- Cloud-Based:Multi-tenant architectures deliver sub-week deployment cycles through browser-accessible interfaces. Healthcare networks in the United States prioritize these configurations to satisfy HIPAA audit-trail mandates without capital infrastructure commitments.
- On-Premise:Dedicated hardware installations maintain air-gapped environments for classified or critical-infrastructure operations. German automotive manufacturers deploy these behind firewall perimeters to satisfy Works Council consultation requirements during workforce restructuring.
- Hybrid:Split architectures partition sensitive workflows on-premise while pushing collaboration layers to cloud nodes.
- SaaS:Subscription-native delivery eliminates version-control fragmentation through continuous deployment pipelines.
Cloud-Based leads on scale; SaaS leads on momentum.
Solution Offering:
Margin capture concentrates where software replaces consultant-delivered services with algorithmic execution.
- Workflow Automation:Rules engines orchestrate approval chains, notification triggers, and escalation protocols without manual intervention. Financial institutions in France deploy these to compress regulatory filing preparation from weeks to days under EU AI Act documentation mandates.
- Risk Assessment:Quantitative scoring models evaluate transformation probability, impact severity, and mitigation readiness. Consulting firms embed these modules to standardize client deliverables across ISO 31000 certification engagements.
- Training Management:Curriculum sequencing tools align skill-building milestones with rollout phases.
- Communication Tools:Stakeholder mapping engines route targeted messaging across hierarchical and functional boundaries.
- Reporting & Analytics:Dashboard aggregators synthesize adoption velocity, resistance indicators, and compliance status.
Workflow Automation leads on scale; Risk Assessment leads on momentum.
Application:
Use-case prioritization follows regulatory pressure intensity and workforce disruption magnitude.
- Organizational Transformation:Enterprise-wide restructuring protocols address M&A integration, culture change, and operating model redesign. German industrial conglomerates activate these suites at scale as electrification programs displace traditional manufacturing roles.
- Compliance Management:Structured audit trails, evidence repositories, and control testing satisfy external examiner scrutiny. Healthcare systems in the United States deploy access-controlled change logs to meet HIPAA breach-notification workflow requirements during EHR transitions.
- Project Management:Initiative-specific change workstreams integrate with PPM tools for milestone synchronization.
- Performance Improvement:Continuous optimization loops connect operational metrics to behavioral intervention triggers.
- Employee Engagement:Persistent pulse-checking mechanisms capture sentiment across distributed teams.
Organizational Transformation leads on scale; Employee Engagement leads on momentum.
End User:
Functional ownership determines integration depth and customization requirements.
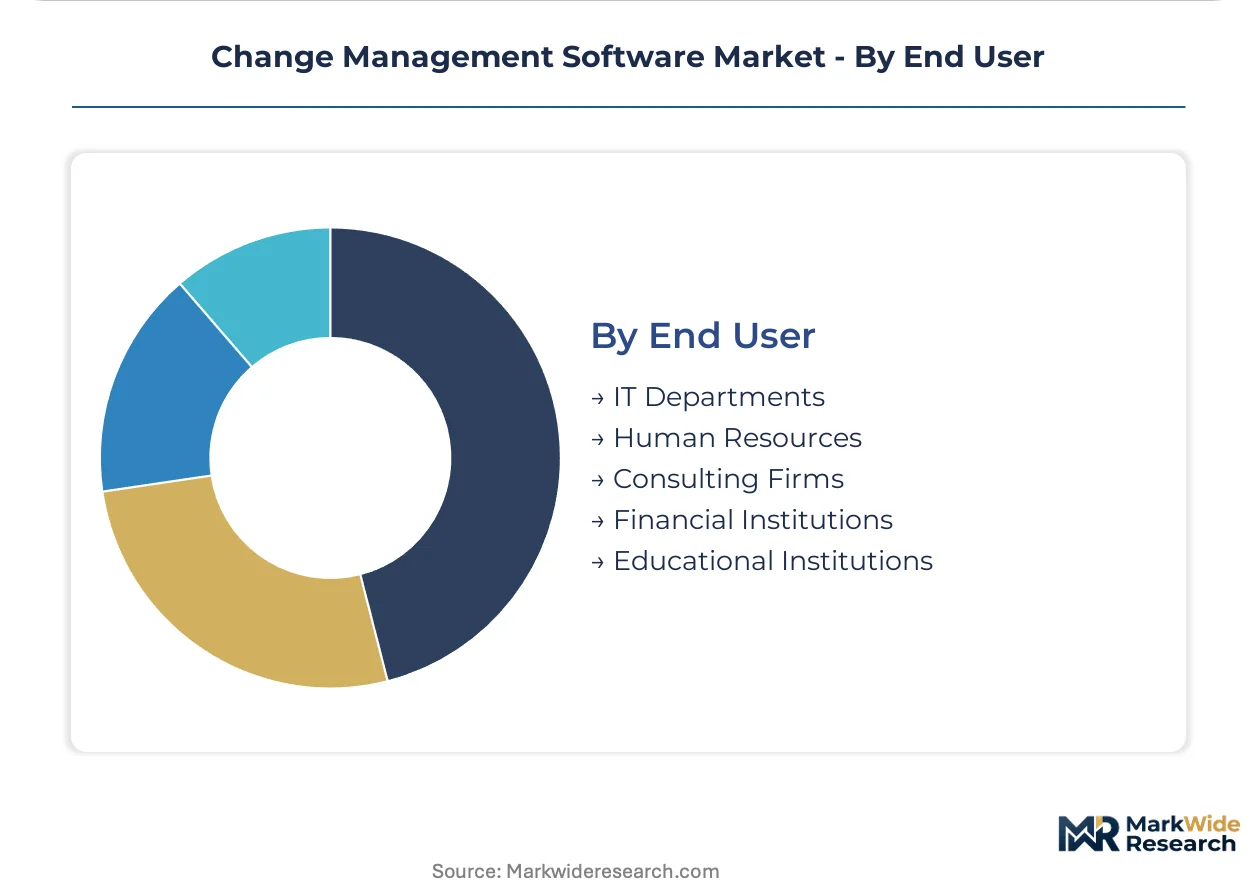
- IT Departments:Technical change control covers infrastructure provisioning, security policy updates, and service-desk reconfiguration. These buyers demand API richness for ServiceNow, BMC Helix, and multi-cloud orchestration compatibility.
- Human Resources:Workforce transition management spans hiring freezes, redeployment protocols, and separation processing. HR buyers prioritize in-application guidance layers that collapse onboarding from multi-week programs into hours of guided exploration.
- Consulting Firms:Client-facing methodology standardization requires white-label configurability and cross-tenant data isolation.
- Financial Institutions:Regulatory change management aligns policy updates with examiner examination cycles.
- Educational Institutions:Semester-aligned rollout schedules accommodate academic calendar constraints.
IT Departments lead on scale; Human Resources leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as enterprises migrate toward jurisdictions offering clearer compliance-cost visibility. Germany and the United States absorb disproportionate platform investment due to mature audit-trail requirements, while India and Brazil emerge as cost-optimized deployment hubs for mid-market buyers seeking SaaS flexibility without European compliance overhead.
United States
HIPAA-covered healthcare networks and SEC-registered financial institutions drive concentrated demand for access-controlled change logs. The SEC's pending climate disclosure rules are expanding transformation-tracking scope into emissions-reduction workflow integration. Boston and New York Metro clusters host dense concentrations of biotech and fintech firms digitizing workforce transition protocols at scale.
Germany
Automotive electrification programs and industrial conglomerate restructuring sustain the largest European procurement volume for workforce transition platforms. The EU AI Act's documentation mandates and Works Council consultation requirements under the Betriebsrätegesetz create dual compliance pressure. Bavaria and Baden-Württemberg anchor deployment concentration as Volkswagen, BMW, and supplier networks standardize change protocols.
United Kingdom
Financial services regulatory change management and post-Brexit operational restructuring sustain platform demand across London and Edinburgh clusters. The Financial Conduct Authority's operational resilience requirements intersect with GDPR audit-trail obligations to create layered procurement criteria. The Southeast and Midlands host the densest vendor-customer ecosystems as consulting firms standardize client methodologies.
India
IT services exporters and mid-market technology firms are accelerating SaaS adoption to compress implementation timelines from quarters to weeks. The RBI's cybersecurity framework for banks and SEBI's disclosure mandates create compliance-driven procurement among financial institutions. Bengaluru and Hyderabad clusters concentrate deployment as hybrid work models require persistent pulse-checking infrastructure.
France
Healthcare network digitization and automotive supplier restructuring sustain demand for risk-scoring and workforce analytics modules. The CNIL's GDPR enforcement posture and EU AI Act risk-classification requirements mandate documented human oversight for algorithmic changes. The Île-de-France and Auvergne-Rhône-Alpes regions concentrate deployment as Sanofi, Renault, and hospital networks invest in compliant workflow infrastructure.
Change Management Software Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI-native workflow convergence and embedded in-application guidance layers. The vendor base organizes around three strategic archetypes: IT workflow integrators anchoring large-enterprise deployments, digital adoption specialists reducing training friction, and methodology platforms standardizing consulting firm deliverables. Dominant competitive moves include M&A to absorb adjacent functionality and strategic partnerships with hyperscale cloud providers to secure hosting capacity.
Among North American platform vendors, ServiceNow and BMC Helix ITSM exemplify the IT workflow integration archetype through deep service-desk and multi-cloud orchestration capabilities. Whatfix occupies a position within the digital adoption specialist tier, representing the in-application guidance layer approach that collapses onboarding timelines. These three anchors illustrate how functional differentiation—IT operations depth versus workforce experience optimization—structures competitive positioning without requiring undifferentiated feature parity.
| Leading Market Players |
|---|
| ServiceNow |
| Jira Service Management |
| Freshservice |
| BMC Helix ITSM |
| Whatfix |
| WalkMe |
| Prosci ADKAR Platform |
| ManageEngine ServiceDesk Plus |
| Wrike |
| Others |
Cost & Logistics Intelligence
Certification-tier divergence between ISO 31000-compliant enterprise suites and unvalidated mid-market tools manifests in both pricing premiums of 40-60% and supply chain configurations that route high-assurance modules through audited development pipelines in Germany and the United States while commodity feature sets deploy from distributed cloud nodes.
Pricing Analysis
Direct-to-enterprise discounts compress distributor margins to 12-18% for cloud-native vendors while legacy on-premise channels retain 25-30% markups. Subscription-SaaS tiering dominates, with pricing stratifying across enterprise-grade compliance bundles, standard workflow automation, and economy self-service tiers. Price differentiation hinges on audit-trail depth and EU AI Act documentation readiness. Cost compression in the economy tier intensifies as open-source workflow engines erode entry-level pricing. Mid-market healthcare buyers exhibit highest price sensitivity; regulated financial institutions demonstrate lowest.
Supply Chain Analysis
Cross-border data residency requirements inflate freight-equivalent latency costs for cloud workload migration between the United States, Germany, and India. Software development concentrates in the United States, Germany, and India, with specialized compliance engineering anchored in France and the United Kingdom. Cloud infrastructure draws from hyperscale capacity in the United States, Ireland, and Singapore. Single-source vulnerability persists where EU AI Act documentation modules rely on boutique German consultancies for certification validation. Distribution runs through direct vendor sales for enterprise accounts and cloud marketplaces for mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The change management software market compounds steadily as regulatory documentation mandates harden into permanent procurement criteria across healthcare, automotive, and financial services verticals.
For Market Incumbents: Anchor defensible positioning through backward integration into compliance consulting capabilities, preempting cloud-native challengers from capturing ISO 31000 certification workflows. Deepen API richness for multi-cloud orchestration to lock in IT department buyers before BMC Helix and ServiceNow extend into workforce analytics. Prioritize EU AI Act module pre-certification to maintain pricing power as documentation requirements tighten. For New Entrants and Emerging Players: Capture white-space in hybrid work pulse-checking functionality, where persistent employee engagement monitoring remains underpenetrated relative to workflow automation saturation. Target mid-market professional services organizations in India and Brazil seeking SaaS flexibility without European compliance overhead. Lead with AI-native natural-language change request processing to differentiate against rules-based incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented digital adoption specialists lack standalone platform depth to compete against IT workflow integrators. Long-term viability favors vendors with embedded compliance modules and recurring revenue concentration above 80%. Acquisition target archetype: AI-native workflow engines with healthcare or automotive vertical penetration. Signal to watch: SEC climate disclosure rule finalization expanding transformation-tracking scope into emissions-reduction workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ServiceNow and BMC Helix connectivity anchors large-enterprise IT department procurement decisions. |
| Acquisition of Specialist Firm | Absorbing digital adoption layers collapses onboarding timelines and captures HR buyer budgets. |
| Strategic Partnership | Hyperscale cloud alliances secure hosting capacity and accelerate sub-week deployment cycles. |
| Geographic Expansion | India and Brazil hubs serve cost-optimized mid-market buyers avoiding European compliance overhead. |
| Product Launch | EU AI Act-compliant documentation modules preempt enforcement action in German automotive networks. |
Research Approach
Multiple input streams — primary interviews with CTOs and IT procurement officers, platform engineer consultations, and channel partner discussions — were reconciled against secondary validation from SEC filings, hyperscaler capex disclosures, and EU regulatory documentation databases. Bottom-up deployment estimates across cloud, on-premise, and hybrid configurations were triangulated with top-down market sizing from vendor revenue disclosures and enterprise software spending patterns.
Data-stream reconciliation anchored analytical frameworks across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions. CAGRs were derived from segmented growth rate modeling applied to baseline penetration estimates. Forecast inputs incorporated EU AI Act implementation timelines and healthcare EHR transition velocity assumptions.
Regulatory enforcement delays, hyperscale capacity constraints, and change-management certification scarcity are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Global Digital Workplace Software Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
European Digital Transaction Management Software Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Crop Management Software Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Email Marketing Market
Digital Solutions
Global Workflow Orchestration Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Global Capacity Management Market