
 Global Integration Platform As a Service (IPAAS) Market | 2026-2036
Global Integration Platform As a Service (IPAAS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Integration Platform As a Service (IPAAS) Market Foresight
Subscription-based consumption models and usage-tiered leasing structures is reconfiguring competitive entry barriers, allowing mid-scale vendors to challenge legacy incumbents without heavy capex commitments. Boomi leverages its cloud-native architecture to anchor SME adoption across distributed deployment environments. Oracle sustains competitive pressure through deep database-to-application connectivity and enterprise-grade governance tooling. Microsoft dominates the productivity-integrated workflow segment by embedding connectivity layers within its broader cloud ecosystem.
An Integration Platform as a Service (IPAAS) is a cloud-hosted middleware environment that provides pre-built connectors, API orchestration engines, and data transformation protocols to link disparate software applications, databases, and services across heterogeneous IT estates. The platform operates through event-driven architectures and RESTful API frameworks to enable real-time bidirectional data synchronization between on-premises legacy systems and cloud-native workloads. Hybrid Cloud deployments are capturing disproportionate strategic attention as enterprises pursue phased migration strategies that preserve operational continuity. API Management solutions concentrate margin pools through recurring developer-portal licensing and governance-tier upsells. Process Automation segments within the solution offering layer are expanding fastest where robotic process automation engines converge with IPAAS orchestration logic.
FCC guidelines on telecommunications data integrity, EU GDPR cross-border transfer mechanisms, and Japan METI cloud security standards collectively shape product certification requirements and customer procurement criteria across major demand centers. The EU AI Act introduces additional algorithmic transparency obligations for automated decision flows routed through integration platforms, forcing vendors to embed audit-trail capabilities at the connector level. Stakeholders must monitor how divergent national cloud sovereignty frameworks reshape data residency requirements and partner ecosystem qualification standards.
Market Dynamics
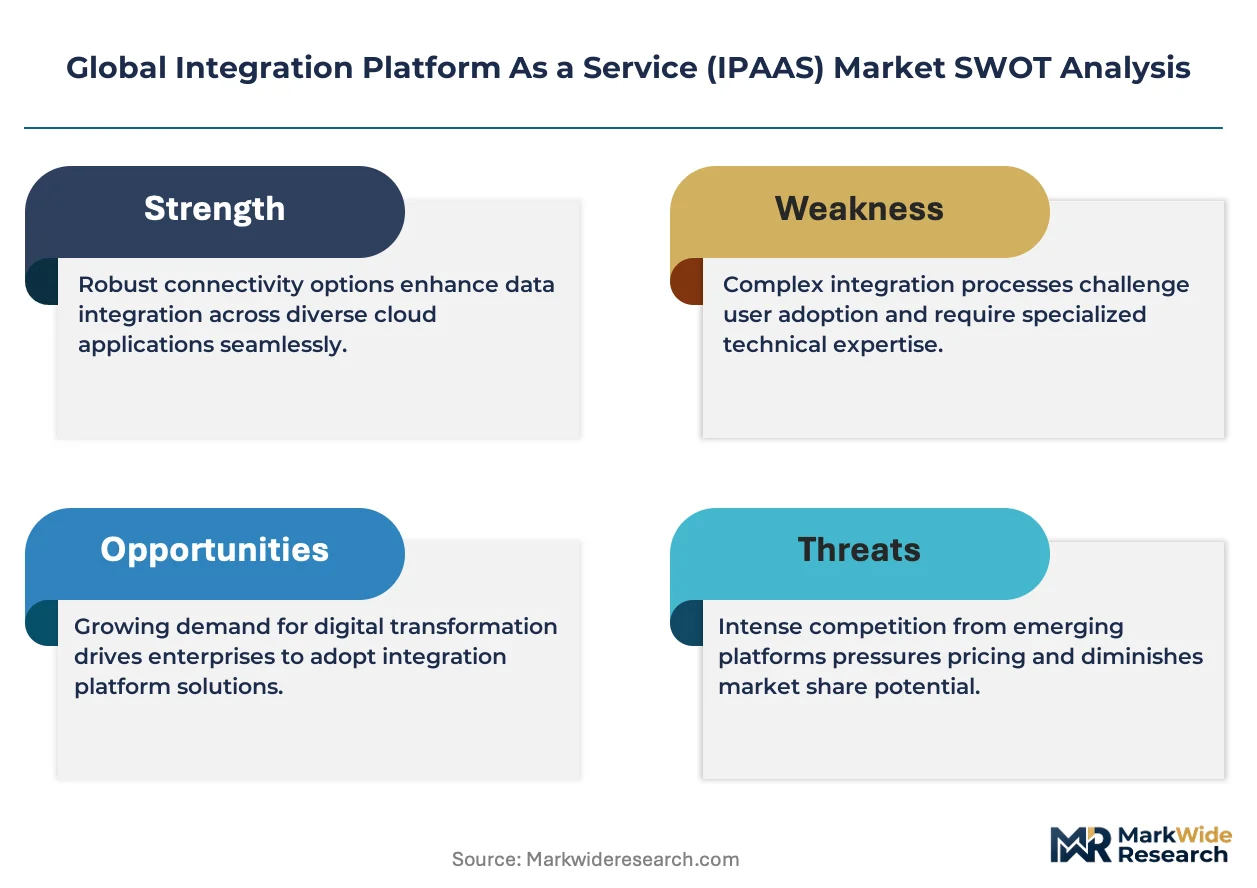
Cloud-native middleware architectures are displacing legacy enterprise service buses as enterprises pursue API-first integration strategies that demand real-time data synchronization across distributed environments.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated decision flows are forcing enterprises to deploy audit-capable integration layers, expanding the addressable market for governance-embedded IPAAS solutions.
- Automotive sector multi-cloud orchestration:German industrial manufacturers are driving demand for hybrid connectivity platforms that synchronize production data across edge devices, private clouds, and supplier networks.
- Event-driven architecture adoption:RESTful API frameworks and asynchronous messaging protocols are enabling real-time bidirectional synchronization that legacy batch-processing middleware cannot support.
Market Restraints
- Cross-border data transfer friction:EU GDPR adequacy decisions and Schrems II rulings are fragmenting cloud deployment patterns, forcing vendors to maintain redundant regional infrastructure.
- Specialized integration talent scarcity:Shortages of API architects and cloud-native DevOps engineers are extending implementation timelines and inflating professional services costs.
- Legacy system entrenchment:Decades-old on-premises ERP investments in financial services and healthcare create switching costs that delay cloud-migration decisions.
Strategic Opportunities
- Process automation convergence:Robotic process automation engines merging with IPAAS orchestration logic are creating new revenue pools in insurance claims processing and supply chain exception handling.
- Japan METI cloud security certification:Compliance with Japanese industrial cybersecurity standards opens procurement channels among precision manufacturing and semiconductor equipment suppliers.
- Edge-to-cloud integration white space:Industrial IoT deployments in oil and gas extraction and smart grid infrastructure require low-latency connectivity that centralized cloud brokers cannot deliver.
Industry Challenges
- Connector maintenance burden:SaaS application versioning cycles force continuous updates to pre-built adapters, straining vendor R&D resources and customer upgrade budgets.
- API security credential management:OAuth token lifecycle governance and secrets rotation across hundreds of endpoints introduce operational failure modes that erode platform reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Integration Platform As a Service (IPAAS) Market |
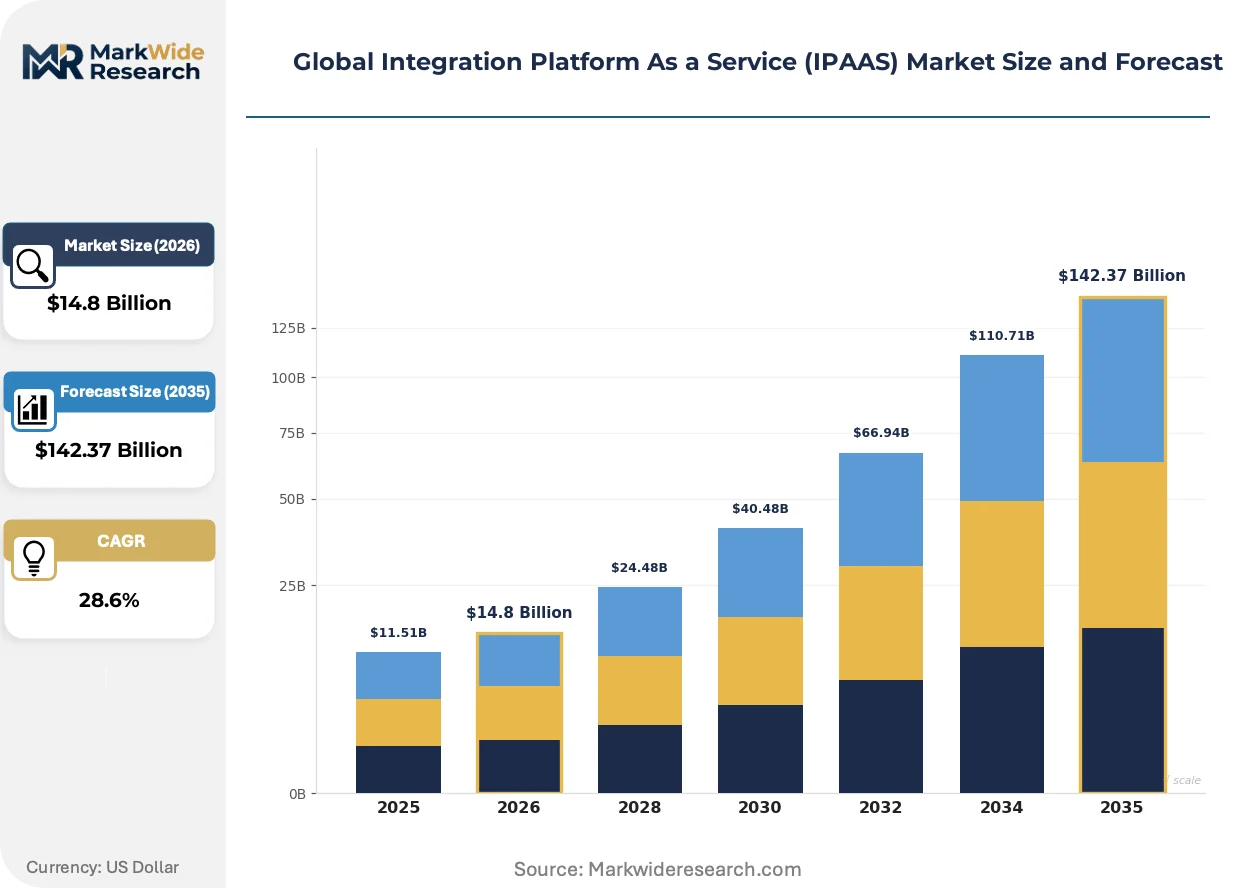
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $142.37 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
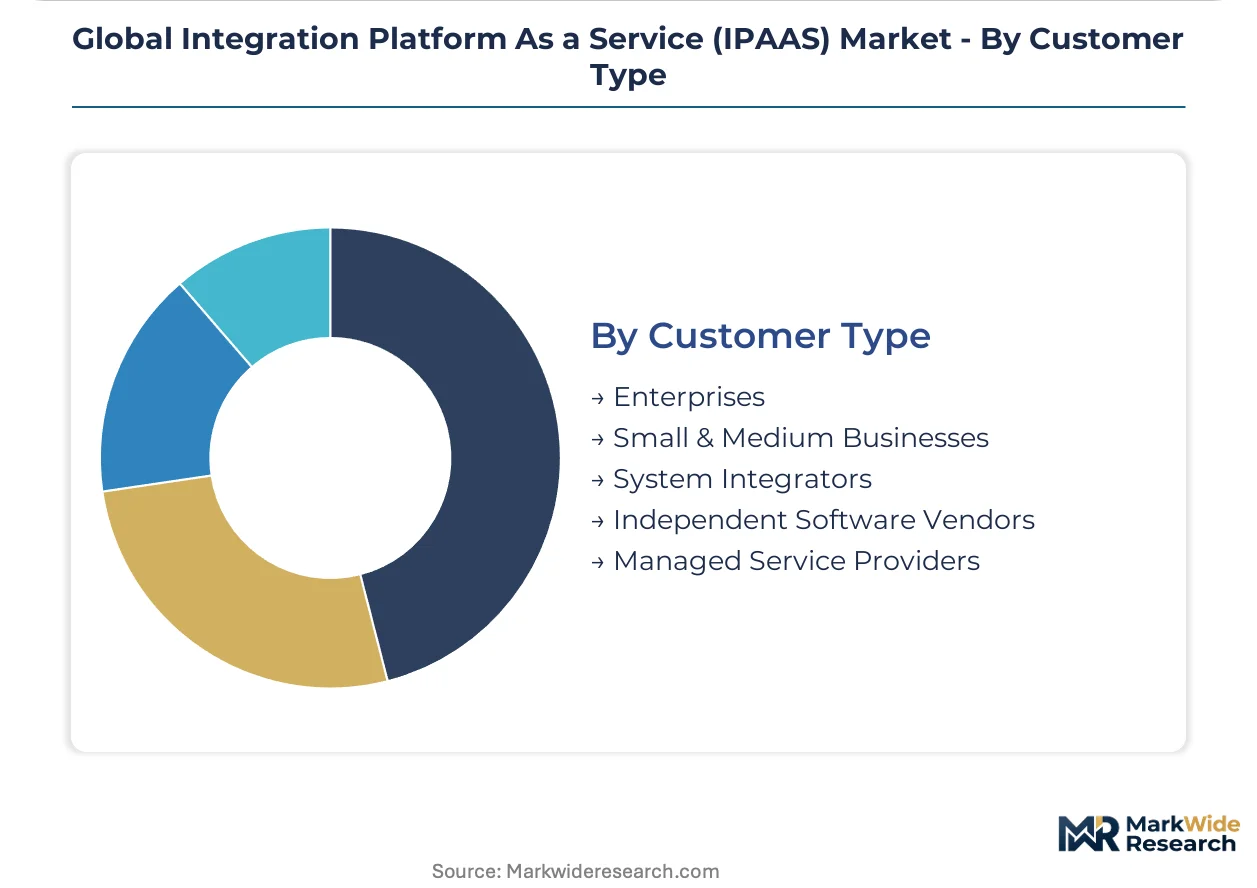
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Solution Offering: Data Integration, Application Integration, Process Automation, API Management, Security & Governance Use Case: Real-Time Data Processing, B2B Data Exchange, Cloud Migration, Legacy System Integration, Business Analytics Customer Type: Enterprises, Small & Medium Businesses, System Integrators, Independent Software Vendors, Managed Service Providers |
| Companies Covered | Boomi, Informatica, MuleSoft, Oracle, IBM, SAP, Microsoft, SnapLogic, Workato, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Integration Platform As a Service (IPAAS) Market Shifts & Advancements
Containerized integration runtimes and declarative API specifications are compressing deployment cycles and enabling infrastructure-as-code practices that treat connectivity as a software-defined layer rather than hardware-provisioned middleware.
Event mesh architectures built on Apache Kafka and cloud-native streaming platforms are virtualizing the traditional hub-and-spoke integration topology. Financial services institutions in London and Singapore are deploying these fabrics to decouple payment processing from core banking systems. The shift is virtualizing the need for centralized message brokers and enabling geographic distribution of integration logic.
The EU AI Act's algorithmic transparency obligations are forcing vendors to embed immutable audit trails at the connector level. Industrial manufacturers routing automated quality-control decisions through IPAAS layers must now maintain decision provenance records. German automotive suppliers are qualifying platforms based on native compliance tooling rather than post-hoc audit capabilities.
Consumption-based pricing models are displacing perpetual licensing for enterprise integration middleware. Mid-market technology companies in the Netherlands and Sweden are favoring usage-tiered subscriptions that align costs with transaction volumes. The shift is most visible among SaaS-native enterprises that lack capital reserves for upfront platform investments.
Global Integration Platform As a Service (IPAAS) Market Segmentation
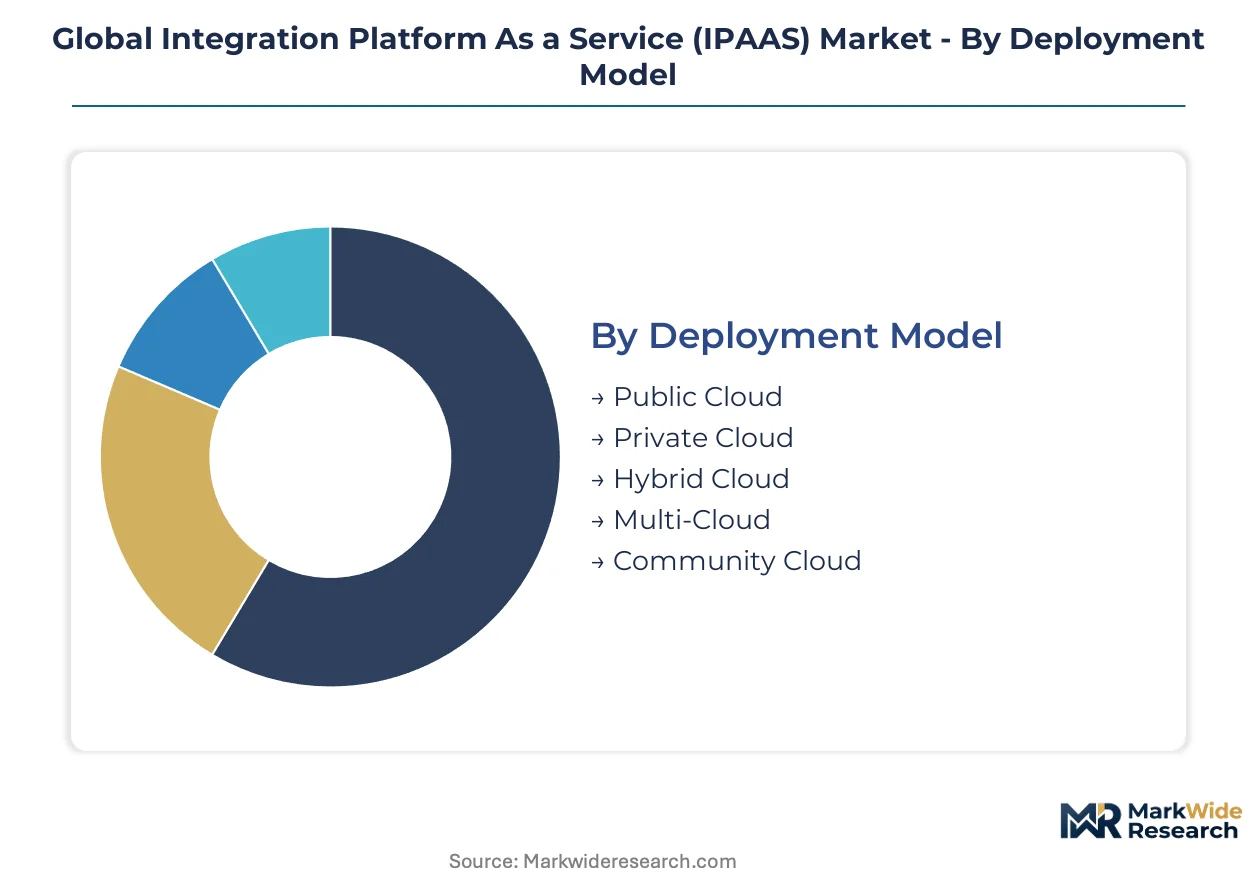
IPAAS procurement patterns diverge sharply across deployment topologies, solution layers, and buyer sophistication. Vendors must align engineering roadmaps with the specific connectivity architectures and governance requirements that dominate each segment cluster.
Deployment Model:
Use-case spectrum spans lightweight SaaS connectivity for digital-native startups through sovereign infrastructure mandates for defense contractors and regulated financial institutions.
- Hybrid Cloud:Combines on-premises runtime engines with cloud-native orchestration planes to support phased ERP migrations. German automotive suppliers are standardizing on hybrid stacks to synchronize production data across edge devices and SAP S/4HANA cloud instances while maintaining local failover.
- Multi-Cloud:Abstracts connectivity across AWS, Azure, and GCP environments through unified control planes and cross-cloud API gateways. Japanese precision manufacturers are deploying multi-cloud fabrics to avoid vendor lock-in while meeting METI cloud security certification requirements.
- Public Cloud:Delivers fully managed integration runtimes with consumption-based pricing and zero infrastructure maintenance overhead.
- Private Cloud:Deploys dedicated integration infrastructure within customer-controlled data centers for regulated workloads.
- Community Cloud:Serves sector-specific consortia with shared governance frameworks and pre-certified connector libraries.
The dominant share belongs to Hybrid Cloud, while Multi-Cloud is closing the gap fastest.
Solution Offering:
Margin concentration tracks developer adoption depth, with API Management capturing premium pricing through governance-tier upsells and developer portal subscriptions.
- API Management:Encompasses lifecycle governance, developer portals, and traffic analytics for externalized service interfaces. London-based fintechs are deploying these layers to decouple open banking APIs from core legacy systems while maintaining PSD2 compliance audit trails.
- Process Automation:Merges robotic process automation engines with IPAAS orchestration logic for exception handling workflows. Insurance claims processors in the Netherlands are automating document ingestion and adjudication routing through converged platforms.
- Data Integration:Provides batch and real-time ETL/ELT pipelines with schema transformation and data quality enforcement.
- Application Integration:Delivers pre-built connectors and protocol adapters for SaaS-to-SaaS and SaaS-to-on-premises linkage.
- Security & Governance:Embeds OAuth credential lifecycle management, encryption policies, and EU AI Act algorithmic transparency tooling.
API Management commands the highest recurring revenue per seat, though Process Automation is expanding most quickly through RPA convergence.
Use Case:
Technical complexity escalates from straightforward data replication through bidirectional synchronization of semantically mismatched legacy systems.
- Legacy System Integration:Bridges decades-old mainframe and ERP investments with modern cloud-native applications through protocol translation and data format mediation. US healthcare providers are extending Epic and Cerner deployments with patient-facing mobile apps via HL7 FHIR-compliant integration layers.
- Real-Time Data Processing:Enables sub-second event streaming and immediate trigger-response workflows across distributed environments. Singaporean trading venues are deploying Kafka-backed event meshes to decouple market data distribution from core matching engines.
- B2B Data Exchange:Standardizes partner onboarding through EDI, AS2, and modern API protocols with contractual SLA enforcement.
- Cloud Migration:Orchestrates phased workload relocation with rollback capabilities and data consistency verification.
- Business Analytics:Consolidates operational data into warehouse and lakehouse destinations for BI and ML pipeline consumption.
Legacy System Integration absorbs the largest professional services attach rate, while Real-Time Data Processing is gaining share fastest through event-driven architecture adoption.
Customer Type:
Buying center composition shifts from centralized IT procurement through line-of-business shadow IT and external service provider intermediation.
- Enterprises:Demand enterprise-grade governance, dedicated support tiers, and custom connector development for proprietary systems. French energy utilities are mandating ISO 27001-certified platforms with sovereign data residency guarantees.
- Managed Service Providers:White-label IPAAS capabilities to deliver multi-tenant integration services across client portfolios with unified billing and monitoring.
- Small & Medium Businesses:Prioritize low-code configuration, pre-built templates, and subscription pricing without upfront platform fees.
- System Integrators:Embed IPAAS into broader digital transformation engagements with custom implementation and training services.
- Independent Software Vendors:Bundle connectivity capabilities into vertical applications to reduce customer integration burden.
Enterprises contribute the highest absolute contract values, though Managed Service Providers are scaling fastest through multi-tenant service aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's automotive corridor, where multi-cloud orchestration commands premium deployment fees, while Indian SaaS vendors compete on usage-tiered subscriptions that compress margins across Asia-Pacific.
United States
FCC guidelines on telecommunications data integrity and HIPAA compliance requirements drive demand for audit-capable integration layers among healthcare providers. Financial services institutions in New York deploy event mesh architectures to decouple payment processing from core banking systems. Silicon Valley cloud-native enterprises favor consumption-based pricing models that align costs with transaction volumes.
Germany
Automotive suppliers standardize on hybrid cloud stacks to synchronize production data across edge devices and SAP S/4HANA cloud instances. EU AI Act algorithmic transparency obligations force vendors to embed immutable audit trails at the connector level. Industrial manufacturing clusters in Baden-Württemberg and Bavaria qualify platforms based on native compliance tooling rather than post-hoc audit capabilities.
United Kingdom
London-based fintechs deploy API management layers to decouple open banking APIs from core legacy systems while maintaining PSD2 compliance audit trails. GDPR cross-border transfer mechanisms and Schrems II rulings fragment cloud deployment patterns, forcing redundant regional infrastructure. Insurance claims processors in the Netherlands automate document ingestion through converged IPAAS-RPA platforms.
Japan
METI cloud security certification requirements open procurement channels among precision manufacturing and semiconductor equipment suppliers. Japanese precision manufacturers deploy multi-cloud fabrics to avoid vendor lock-in while meeting sovereign cybersecurity standards. Industrial IoT deployments in Nagoya's automotive belt require low-latency edge-to-cloud connectivity that centralized brokers cannot deliver.
Singapore
Trading venues deploy Kafka-backed event meshes to decouple market data distribution from core matching engines. ASEAN financial institutions route automated decision flows through integration platforms that satisfy emerging algorithmic transparency obligations. Smart grid infrastructure projects across Southeast Asia demand sub-second event streaming that legacy batch-processing middleware cannot support.
Global Integration Platform As a Service (IPAAS) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with pre-built connectors and protocol adapters. The vendor base stratifies across three tiers: hyperscale cloud providers with embedded connectivity layers, independent pure-play IPAAS vendors with cloud-native architectures, and legacy enterprise software houses extending database-to-application linkages. Consolidation pressure intensifies as subscription pricing models erode perpetual license revenue pools. Dominant competitive moves include M&A to acquire API management capabilities and strategic partnerships to embed integration runtimes within vertical SaaS applications.
Within the pure-play tier, Boomi and Workato occupy positions as cloud-native challengers, while Oracle exemplifies the legacy incumbent archetype extending deep database connectivity into orchestration services. Boomi anchors SME adoption across distributed deployment environments through low-code configuration interfaces. Workato sits within the mid-market segment favored by SaaS-native enterprises lacking capital reserves for upfront platform investments. Oracle sustains competitive pressure through enterprise-grade governance tooling that appeals to regulated financial services and healthcare buyers. These three companies collectively represent the strategic positioning spectrum—from born-in-cloud agility to incumbent infrastructure leverage—that defines current competitive dynamics.
| Leading Market Players |
|---|
| Boomi |
| Informatica |
| MuleSoft |
| Oracle |
| IBM |
| SAP |
| Microsoft |
| SnapLogic |
| Workato |
| Others |
Supply & Pricing Matrix
US-based hyperscaler infrastructure providers anchor upstream compute and storage provisioning, concentrating margin capture in the orchestration layer where API management and governance tooling command recurring subscription premiums. This supply concentration downstream into software-defined connectivity layers shapes how vendors structure consumption-based pricing tiers and professional services attach rates.
Pricing Analysis
Configured-to-order enterprise deployments carry customization premiums of 40-60% above standard SaaS-tiered subscriptions. The dominant pricing structure runs through usage-tiered subscriptions with developer-seat minimums, where price differentiation hinges on governance certification grade and dedicated support tier. Cost compression in the mid-market segment is intensifying because Indian SaaS vendors compete on transaction-volume pricing. Small and medium businesses exhibit highest price sensitivity, while German automotive buyers prioritize native EU AI Act compliance tooling over unit economics.
Supply Chain Analysis
US export-control restrictions on advanced semiconductor manufacturing equipment limit domestic cloud infrastructure expansion, forcing European and Asian vendors to source from alternative hardware supply chains. IPAAS platform development draws from US hyperscaler compute infrastructure, Irish and Singaporean data center operations, and Indian engineering talent pools. Single-source vulnerability concentrates in NVIDIA GPU provisioning for AI-enabled integration workloads. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in this market hinge on API ecosystem density, where vendor lock-in strengthens as developer portal adoption crosses critical mass and connector libraries deepen.
For Market Incumbents: Entrench position by embedding integration runtimes within vertical SaaS applications through strategic partnerships, and accelerate certification investment for EU AI Act algorithmic transparency tooling. Cloud-native challengers threaten margin pools in the SME segment with consumption-based pricing that undercuts enterprise-grade governance bundles. For New Entrants and Emerging Players: Edge-to-cloud integration for industrial IoT deployments in Japanese precision manufacturing represents the most penetrable entry point, with METI cloud security certification serving as the qualifying threshold. Target insurance claims processing workflows in the Netherlands through converged IPAAS-RPA platform offerings. A channel-centric go-to-market through systems integrators accelerates enterprise credibility without direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play API management specialists with developer portal traction and recurring revenue concentration above 80%. Long-term viability in this market rests on ecosystem density and connector library depth rather than feature velocity alone. The signal to watch is hyperscaler marketplace transaction volume share as an indicator of distribution control shifting toward cloud-native channels.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding orchestration runtimes within SAP S/4HANA cloud instances deepens automotive customer retention. |
| Strategic Partnership | Collaboration with London fintechs on PSD2-compliant open banking APIs accelerates financial services penetration. |
| Acquisition of Specialist Firm | Absorbing RPA engine capabilities enables converged IPAAS-automation offerings for insurance claims processing. |
| Geographic Expansion | METI cloud security certification unlocks procurement channels among Nagoya automotive belt precision manufacturers. |
| Product Launch | Immutable audit-trail connectors address EU AI Act algorithmic transparency mandates for German industrial buyers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory submissions to establish baseline market sizing. CTOs, IT procurement officers, platform engineers, and integration specialists at enterprises across German automotive, US healthcare, and Singaporean financial services provided qualitative inputs on deployment patterns and vendor selection criteria. Bottom-up triangulation against top-down macroeconomic indicators validates segment-level projections.
Forecast inputs include deployment model adoption curves, solution offering margin trajectories, and customer type procurement velocity across the projection horizon. The analytical framework models hybrid cloud, multi-cloud, public cloud, private cloud, and community cloud deployment patterns alongside API management, process automation, data integration, application integration, and security governance solution layers. CAGRs derive from regression analysis against cloud infrastructure spending correlations and enterprise software substitution elasticities.
Macroeconomic conditions sit as an overlay; deviation in central bank rate policy, cross-border data transfer regulatory rulings, or hyperscaler pricing power would shift the trajectory. Forecasts reflect documented assumptions regarding EU AI Act implementation timelines and automotive sector cloud migration cadence. Cross-checking against Gartner and IDC enterprise software spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
France Digital Twin Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Smart Card Reader Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Global Product Lifecycle Management Market
Digital Solutions
UK Route Optimization Software Market
Digital Solutions
Human Resource (HR) Technology Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Global Mobile Content Management Market