
 Event Apps Market | 2026-2036
Event Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Event Apps Market Foresight
Corporate event portfolios is rebalancing toward immersive hybrid experiences, pulling software spend away from pure in-person tooling. Cvent dominates the large-enterprise segment with extensive venue and attendee management modules. Whova differentiates through AI-powered networking recommendations that sustain engagement rates. Eventbase specializes in white-label mobile experiences for major trade show operators.
Event apps constitute software platforms that coordinate registration, scheduling, real-time communication, and post-event analytics through native iOS and Android binaries or responsive web layers, typically integrating with CRM and marketing automation stacks via REST APIs. Cloud-based deployment leads absolute spend as organizers prioritize elastic infrastructure for unpredictable attendance spikes. Mobile applications capture the fastest expansion as attendees expect offline-capable, beacon-enabled navigation and personalized agenda building. Hybrid solutions occupy the premium tier where enterprises demand unified virtual and on-site orchestration.
FDA oversight applies where event apps collect biometric or health data from wearables at wellness conferences, while GDPR mandates explicit consent flows for European attendee data. The EU AI Act imposes risk-classification requirements on automated matchmaking and recommendation engines. Stakeholders must monitor evolving cross-border data localization rules that determine where attendee records must reside.
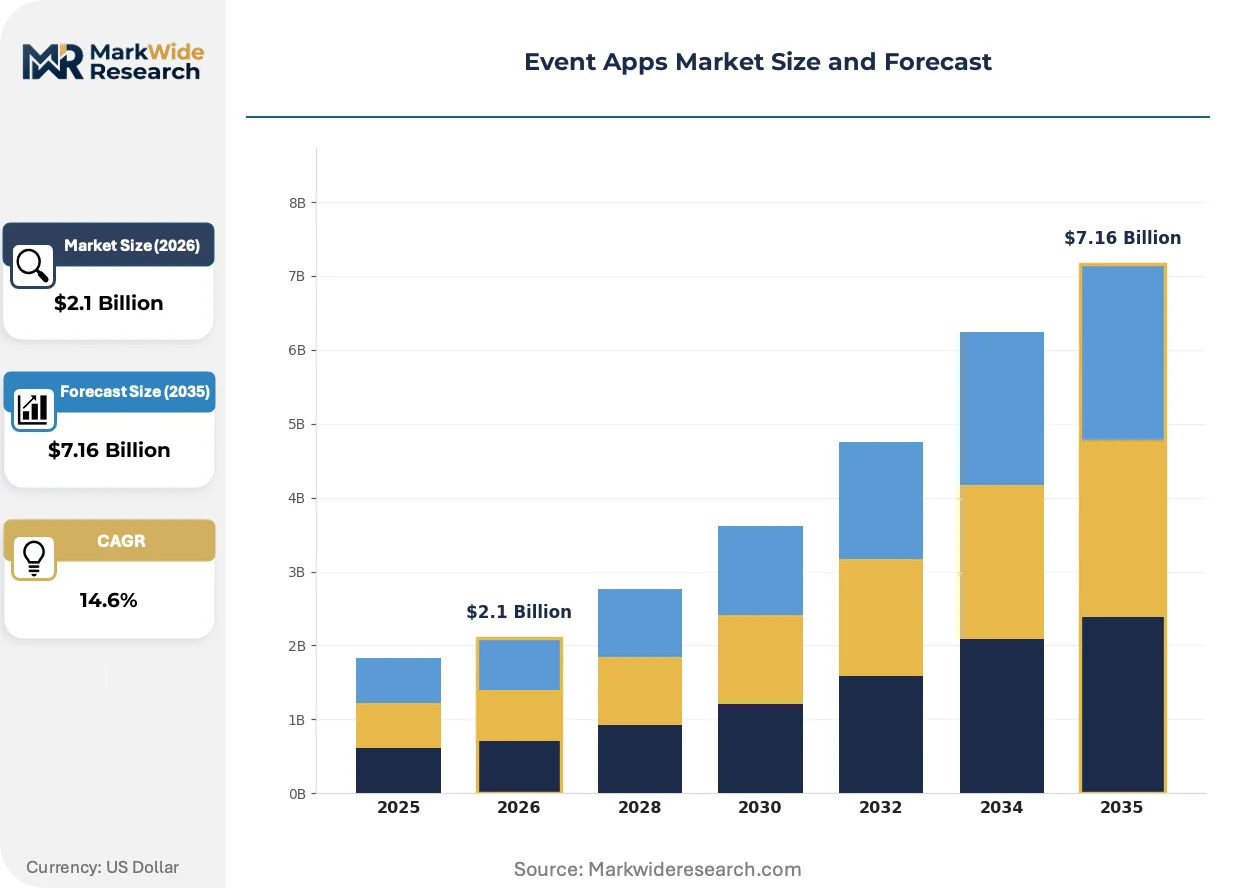
Market Dynamics
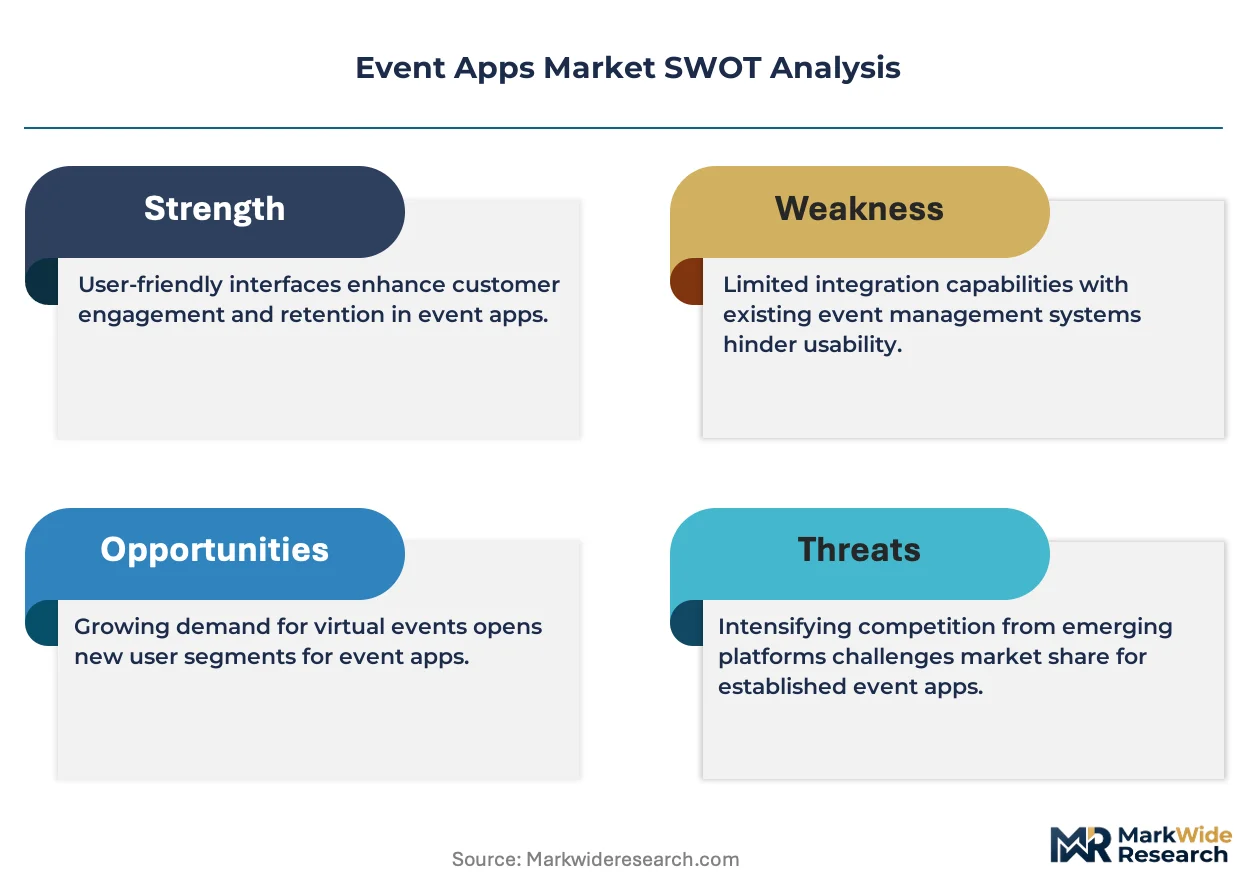
Enterprise event portfolios are rebalancing toward immersive hybrid experiences, pulling software spend away from pure in-person tooling and forcing platforms to unify virtual and on-site orchestration capabilities.
Growth Catalysts
- GDPR Consent Frameworks:European data protection mandates are compelling platform operators to invest in transparent attendee data flows, creating competitive differentiation for compliant vendors.
- Biometric Wearables:Wellness conferences are integrating health-monitoring devices that feed real-time analytics into event apps, expanding addressable use cases.
- United States Enterprise Budgets:Corporate technology allocations for employee engagement platforms sustain premium-tier investments in unified event suites.
Market Restraints
- Cloud Infrastructure Concentration:Reliance on hyperscale providers in limited geographic zones creates latency and resilience vulnerabilities for real-time event operations.
- EU AI Act Classification:Automated matchmaking engines face risk-tier compliance burdens that extend development timelines and legal review costs.
- Technical Fragmentation:Legacy venue management systems resist API standardization, forcing costly middleware development for integration.
Strategic Opportunities
- India PLI Incentives:Domestic electronics manufacturing subsidies could localize hardware-software bundles for Asia-Pacific event deployments.
- Beacon-Navigation Convergence:Bluetooth Low Energy mesh networks combined with augmented reality overlays enable premium indoor positioning services for trade show operators.
- White-Label Channel Expansion:Major exhibition organizers seek branded mobile experiences, opening direct licensing revenue streams independent of per-seat SaaS models.
Industry Challenges
- Cross-Border Data Localization:Divergent national requirements on where attendee records must reside complicate multi-continental event deployments.
- AI Ethics Review Cycles:Recommendation engine training data audits consume engineering resources and delay feature releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Event Apps Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Web-Based Platforms, Desktop Software, Hybrid Solutions End User: Event Organizers, Corporate Clients, Educational Institutions, Nonprofits Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Feature: Networking Tools, Ticketing Systems, Analytics Dashboards, Feedback Collection |
| Companies Covered | Eventdex, Whova, Bizzabo, Eventbase, ExpoPlatform, Cvent, Accelevents, RainFocus, vFairs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Event Apps Market Shifts & Advancements
Event technology stacks are absorbing ambient computing layers that anticipate attendee needs before explicit queries, compressing the gap between physical presence and digital service delivery.
Edge computing architectures are absorbing session-matching workloads that previously routed through centralized cloud nodes. Large trade show operators in Germany and the United States are deploying on-premise inference clusters to reduce latency for real-time networking suggestions. This distributed processing model is absorbing the cost premiums that once justified pure-cloud SaaS pricing, pressuring vendors to unbundle infrastructure fees.
GDPR and the EU AI Act are jointly mandating algorithmic transparency for automated attendee recommendations. Platform operators must now document decision logic and maintain human-in-the-loop override capabilities. European enterprise clients are demanding these compliance features as standard procurement criteria, forcing product roadmap prioritization away from pure performance optimization.
Subscription fatigue among corporate procurement teams is compressing event technology buying cycles toward modular, usage-based arrangements. Marketing departments in the United Kingdom and Netherlands are unbundling registration, networking, and analytics into separate vendor relationships. This fragmentation is absorbing the account control that integrated suites previously enjoyed, elevating API interoperability to a primary selection factor.
Event Apps Market Segmentation
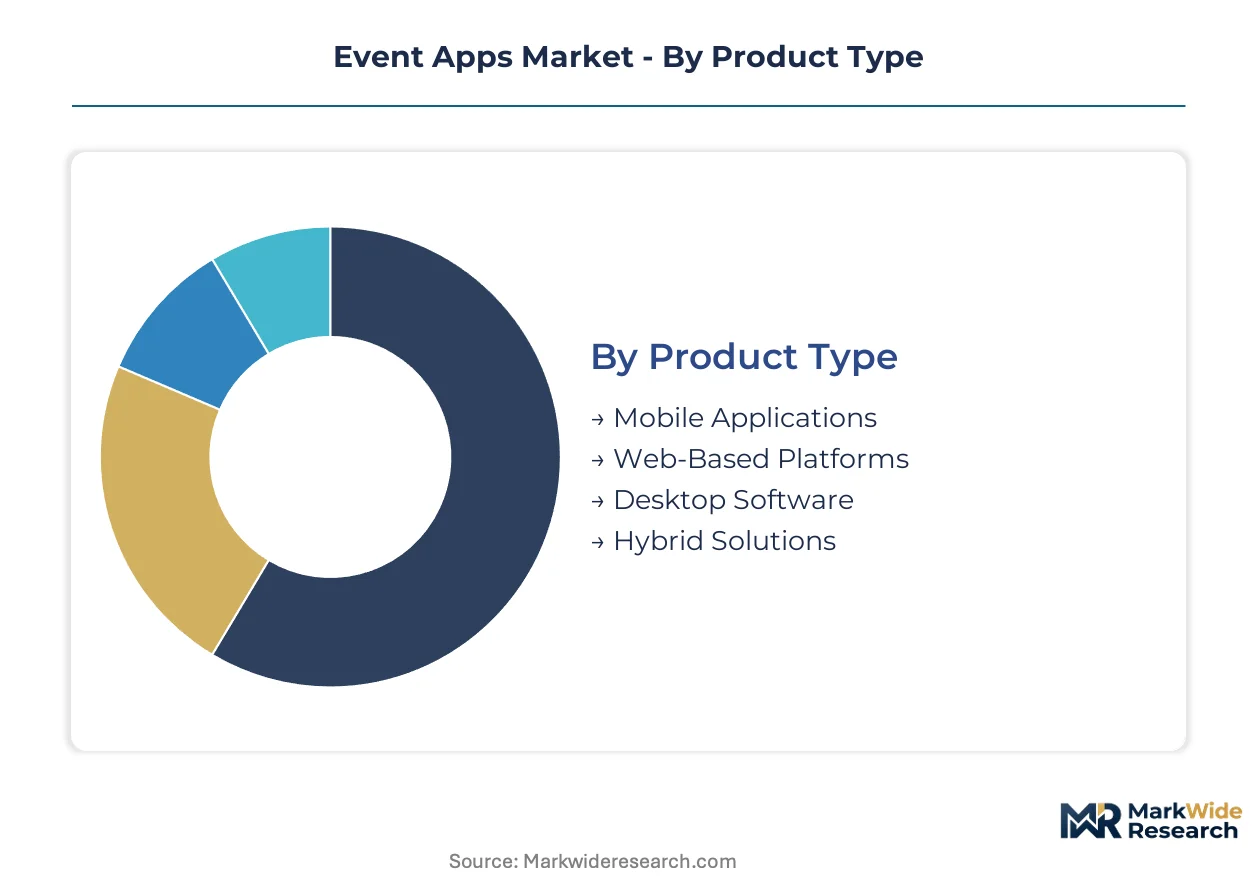
Event apps fragment across four structural dimensions that determine integration complexity and procurement patterns. Product type and deployment mode dictate whether platforms operate as embedded enterprise systems or standalone tools. End user concentration and feature packaging shape pricing elasticity and renewal rates across customer tiers.
Product Type:
Integration depth varies sharply: mobile and web layers embed into broader marketing stacks, while desktop tools often persist as standalone legacy installations.
- Mobile Applications:Native iOS and Android binaries with offline capability, beacon integration, and push notification orchestration. Demand concentrates among United States trade show operators requiring real-time indoor navigation for sprawling convention centers, constrained by app store approval cycles that delay feature releases.
- Web-Based Platforms:Responsive browser layers built on JavaScript frameworks with REST API connectivity to CRM systems. European corporate procurement teams favor these for GDPR-compliant data residency controls that simplify cross-border attendee management.
- Desktop Software:Legacy Windows and macOS installations for venue AV control and on-site registration kiosks.
- Hybrid Solutions:Unified orchestration layers spanning virtual and physical event experiences, commanding premium pricing from enterprise clients.
Mobile Applications lead volumes today; Hybrid Solutions are gaining share fastest.
End User:
Customer type determines feature bundling intensity and sales cycle length, with corporate procurement demanding modular contracts versus institutional preference for integrated suites.
- Corporate Clients:Enterprise technology and pharmaceutical sectors purchasing unified event suites for employee engagement and regulatory compliance. United States headquarters drive standardization across regional subsidiaries, absorbing per-seat SaaS premiums for centralized analytics.
- Event Organizers:Independent planners and agency operators selecting best-of-breed tools per engagement. Budget constraints in the United Kingdom and Netherlands fragment procurement across separate registration, networking, and analytics vendors.
- Educational Institutions:Universities and business schools deploying white-label campus event apps for alumni and admissions programming.
- Nonprofits:Association and charity operators prioritizing donation-integrated ticketing and volunteer coordination features.
Corporate Clients dominate revenue concentration; Educational Institutions are expanding most quickly.
Deployment:
Infrastructure location shapes latency performance, data sovereignty compliance, and total cost of ownership across customer segments.
- Cloud-Based:Elastic AWS, Azure, or Google Cloud deployments scaling automatically for unpredictable attendance spikes. GDPR-mandated EU data residency requirements are forcing hyperscale providers to expand Frankfurt and Dublin region capacity.
- SaaS:Multi-tenant architectures with standardized feature releases and usage-based pricing. United States mid-market event organizers favor these for predictable operational expenditure without capital infrastructure commitments.
- On-Premise:Dedicated server installations for defense sector and government events with classified attendee requirements.
- Hybrid:Split architectures keeping sensitive registration data on-premise while routing public content delivery through cloud edge nodes.
Cloud-Based deployments anchor current infrastructure spend; Hybrid configurations are climbing the fastest as data localization rules multiply.
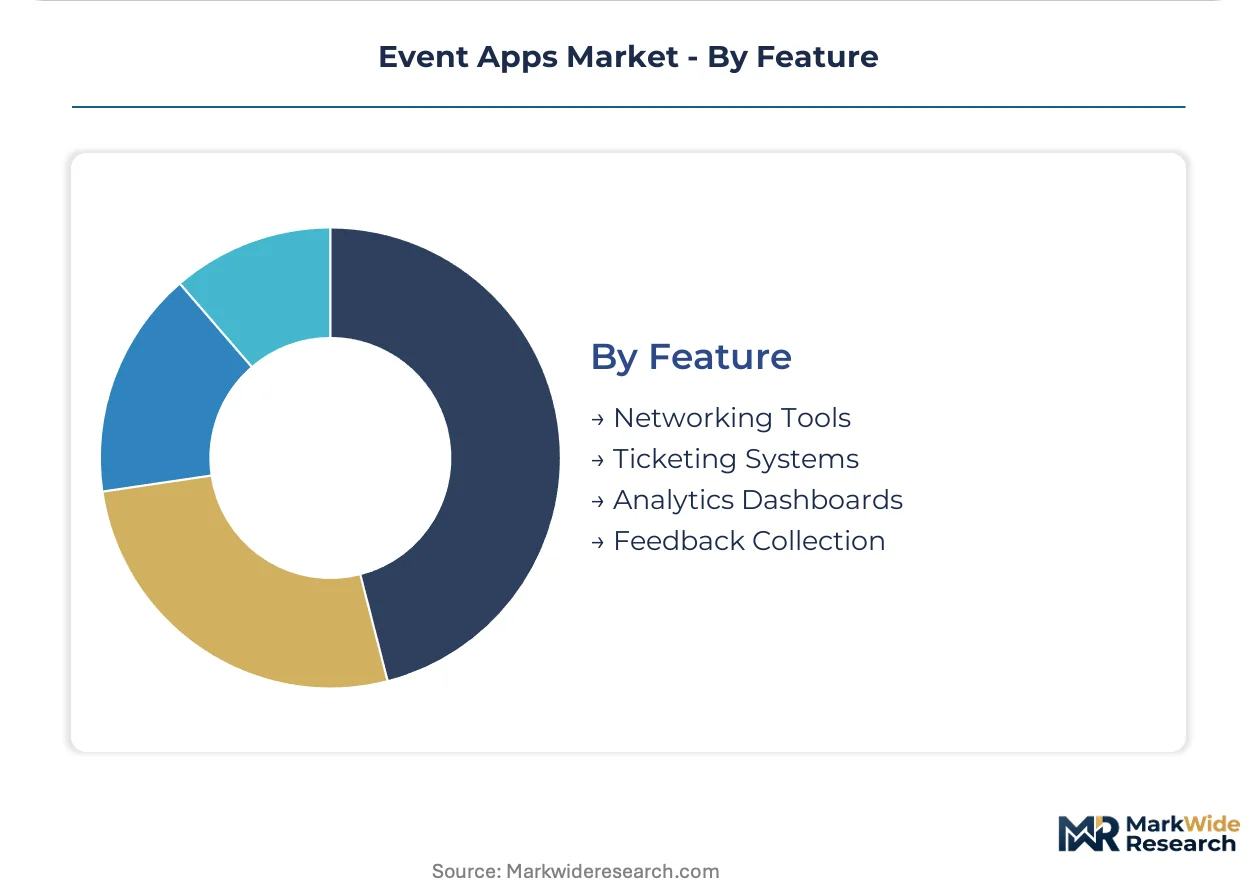
Feature:
Capability modularization is accelerating as procurement teams unbundle integrated suites into separate vendor relationships.
- Networking Tools:AI-powered attendee matching, meeting scheduling, and messaging systems. The EU AI Act's risk classification requirements for automated recommendation engines are extending legal review timelines for European deployments.
- Analytics Dashboards:Real-time attendance tracking, session engagement scoring, and post-event ROI measurement. United States enterprise marketing departments demand these for justifying technology spend to procurement committees.
- Ticketing Systems:Registration workflows, payment processing, and access credential generation with fraud prevention.
- Feedback Collection:Survey deployment, sentiment analysis, and Net Promoter Score calculation for speaker and venue evaluation.
Networking Tools command the highest feature premiums; Analytics Dashboards are seeing steepest demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between the United States and European Union is creating compliance-cost arbitrage that shapes where event technology vendors prioritize platform development. GDPR and the EU AI Act impose heavier engineering burdens than US counterparts, concentrating investment decisions around data residency requirements.
United States
Enterprise technology budgets and hybrid work normalization sustain premium platform investments. HIPAA governs health data collection at medical conferences, while the FDA asserts oversight where biometric wearables feed into event analytics. San Francisco and New York clusters host the dominant SaaS infrastructure providers serving Fortune 500 event portfolios.
Germany
Industrial trade show operators demand white-label mobile experiences for sprawling Messe complexes. The EU AI Act's risk classification requirements extend legal review timelines for automated networking engines. Frankfurt's data center concentration anchors GDPR-compliant cloud deployments for European enterprise clients.
United Kingdom
Marketing procurement teams fragment event technology buying across modular vendor relationships. Subscription fatigue compresses contract cycles toward usage-based arrangements. London's financial services sector drives demand for compliant attendee management at regulatory-heavy conferences and shareholder meetings.
India
Domestic electronics manufacturing subsidies under the PLI scheme could localize hardware-software bundles for Asia-Pacific deployments. BIS standards govern device certification where beacon-enabled navigation hardware integrates with event platforms. Bengaluru's SaaS ecosystem incubates mid-market event technology startups targeting Southeast Asian expansion.
Japan
Corporate hospitality traditions sustain investment in premium hybrid orchestration capabilities. METI guidelines shape data handling practices for international conference operators. Tokyo's exhibition district concentrates demand for real-time multilingual networking tools serving cross-border business events.
Event Apps Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated suites commanding enterprise accounts and point solutions capturing fragmented agency spend. The vendor base concentrates around three tiers: full-stack orchestration platforms, modular feature specialists, and white-label infrastructure providers. Dominant competitive moves include API interoperability investments that ease procurement fragmentation, and edge computing deployments that reduce latency for real-time networking workloads.
Within the full-stack tier, Cvent and Bizzabo exemplify the scale-driven archetype that absorbs enterprise SaaS premiums for centralized analytics. Whova occupies a specialist position where AI-powered recommendation engines differentiate engagement retention. Among white-label providers, Eventbase anchors the premium mobile experience segment for major trade show operators seeking branded deployments independent of per-seat pricing models.
| Leading Market Players |
|---|
| Eventdex |
| Whova |
| Bizzabo |
| Eventbase |
| ExpoPlatform |
| Cvent |
| Accelevents |
| RainFocus |
| vFairs |
| Others |
Supply & Pricing Matrix
Cloud-native engineering talent concentration in Bengaluru and San Francisco establishes labor-cost differentials that separate premium-tier hybrid orchestration platforms from commoditized registration-only tools. GDPR-mandated compliance engineering in Frankfurt and Dublin adds fixed cost layers that vendors recover through higher SaaS pricing for European enterprise deployments.
Pricing Analysis
Distributor margins for white-label mobile deployments absorb 15-25 points before reaching exhibition organizers, compressing vendor net pricing versus direct SaaS sales. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth: API-unbundled modules sit at economy tiers, while unified hybrid suites with edge computing nodes command premium positioning. Price differentiation hinges on GDPR certification tier and real-time networking latency guarantees. Pricing pressure stems from procurement fragmentation as marketing teams unbundle suites into separate vendor relationships. Event organizers in the United Kingdom and Netherlands exhibit highest price sensitivity; Fortune 500 technology headquarters in the United States show lowest elasticity for centralized analytics bundles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Fortune 500 event portfolios, bypassing traditional software distribution intermediaries. Cloud infrastructure supply concentrates in the United States, Ireland, and Germany where hyperscale providers maintain GDPR-compliant data residency zones. Raw material dependencies include silicon for beacon hardware, lithium-ion cells for wearable devices, and specialized optical components for AR navigation overlays. Supply chain risk centers on single-source vulnerability for EU-based data center capacity as localization rules multiply. Distribution runs through API-first integration marketplaces and direct enterprise sales teams rather than traditional software resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-classification framework for automated recommendation engines functions as a regulatory compounder, accelerating procurement demand for compliant platforms while extending vendor development timelines. This dynamic rewards early compliance investment and punishes laggards with frozen European sales pipelines.
For Market Incumbents: Anticipate margin compression from modular unbundling by reinforcing API interoperability investments that ease procurement fragmentation across best-of-breed toolchains. Accelerate edge computing deployments in Frankfurt and Dallas to reduce latency for real-time networking workloads before cloud-native challengers capture hyperscale accounts. Vertical integration into beacon hardware manufacturing insulates against supply volatility for trade show navigation deployments.
For New Entrants and Emerging Players: Independent event agencies in the Netherlands and United Kingdom represent the most penetrable channel partner type, as subscription fatigue has already fragmented their procurement patterns away from integrated suites. Target white-label mobile experiences for midsize German industrial trade show operators seeking branded deployments without per-seat SaaS premiums. Pursue API-first positioning that slots into existing marketing automation stacks rather than competing for full-suite replacement cycles.
For Investors and Strategic Acquirers: Enterprise software conglomerates with adjacent employee engagement portfolios are the most active acquirer in this space, seeking unified event suites to complement existing HR technology investments. Acquisition target archetypes include AI-powered networking specialists with documented GDPR compliance and established European enterprise references. Watch for inflection when European procurement committees mandate EU AI Act documentation as standard RFP criteria, compressing valuation multiples for non-compliant assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies virtual and physical event layers for Fortune 500 hybrid work policies. |
| GDPR Compliance Certification | Opens European procurement pipelines blocked by EU AI Act risk classification. |
| Edge Computing Deployment | Reduces networking latency for real-time matchmaking at German trade show complexes. |
| White-Label Channel Expansion | Captures exhibition organizer budgets seeking branded mobile independence from per-seat pricing. |
| API Interoperability Investment | Eases procurement fragmentation as marketing teams unbundle registration, networking, and analytics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with event technology CTOs, corporate marketing procurement officers, exhibition organizer operations directors, and platform integration specialists with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie mobile engagement data, and EU regulatory documentation. Bottom-up sizing of vendor-reported seat counts and top-down triangulation against enterprise software spending patterns anchored volume estimates.
Segment-weighting approaches distributed value across deployment models, organization size tiers, vertical concentration, and regional adoption patterns throughout the forecast period. CAGRs derived from elasticity modeling of event technology budgets against corporate employee engagement spend. Industry-specific inputs included GDPR enforcement trajectory, EU AI Act implementation timelines, and hybrid work normalization indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cross-border data localization rule proliferation and AI ethics audit burden expansion. Outputs reflect documented assumptions around enterprise SaaS pricing stability and hyperscale infrastructure capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
United States ICT Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Global Digital Business Card Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
India PLM Market
Digital Solutions
Game Engines Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
EHS Software Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Image Recognition in Retail Market