
 Global Dock and Yard Management System Market | 2026-2036
Global Dock and Yard Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dock and Yard Management System Market Foresight
Certified yard jockey and dispatch coordinator availability is collapsing across major logistics corridors, forcing distribution centers to automate gate check-in, trailer sequencing, and dock door assignments. Zebra Technologies Corporation leverages its hardware-software convergence in mobile computing and RFID to capture yard visibility contracts from operators desperate to reduce dwell-time penalties. Manhattan Associates Inc. anchors its position through deep warehouse management system integration, while Descartes Systems Group Inc. competes on multimodal connectivity spanning ocean, rail, and over-the-road freight handoffs.
A dock and yard management system orchestrates the physical and digital flow of trailers, containers, and inventory across facility perimeters through real-time location tracking, automated dock door scheduling, and rule-based carrier appointment systems, typically processing sub-minute updates via RFID, GPS, or computer-vision gate portals. Cloud-based deployment leads solution uptake among mid-market third-party logistics providers seeking subscription elasticity, while scheduling modules within the solution offering dimension command premium pricing due to their direct impact on carrier detention cost avoidance. Inventory tracking functions are maturing fastest as WMS vendors bundle yard visibility into core platform renewals, compressing standalone pricing for point solutions.
FAA regulations governing drone-based yard inventory counts and OSHA standards for pedestrian-traffic separation in loading zones are shaping product safety compliance modules, while the EU AI Act imposes documentation burdens on computer-vision gate systems deployed across European distribution networks. The EPA's idling-reduction mandates in the United States and China's MIIT dual carbon goals are accelerating electric yard truck integration, requiring dock management platforms to incorporate charging-schedule optimization. Stakeholders must decide whether to build in-house IoT sensor networks or rely on carrier-provided telematics feeds as the primary data layer for yard positioning accuracy.
Market Dynamics
Chronic shortages of certified yard jockeys and dispatch coordinators are forcing warehouse operators to automate gate check-in, trailer sequencing, and dock door assignments through real-time visibility platforms.
Growth Catalysts
- OSHA pedestrian-traffic separation mandates:Distribution centers in the United States face escalating compliance deadlines for loading zone safety, accelerating investment in automated gate portals and computer-vision monitoring systems that eliminate human traffic controllers.
- E-commerce fulfillment density:Third-party logistics providers handling high-velocity parcel flows require sub-minute yard updates to avoid carrier detention penalties, driving subscription uptake of cloud-native scheduling modules.
- MIIT dual carbon goals:China's electric yard truck integration mandates are compelling dock management platforms to incorporate charging-schedule optimization, creating new software attach opportunities for deployment across Shanghai and Shenzhen port clusters.
Market Restraints
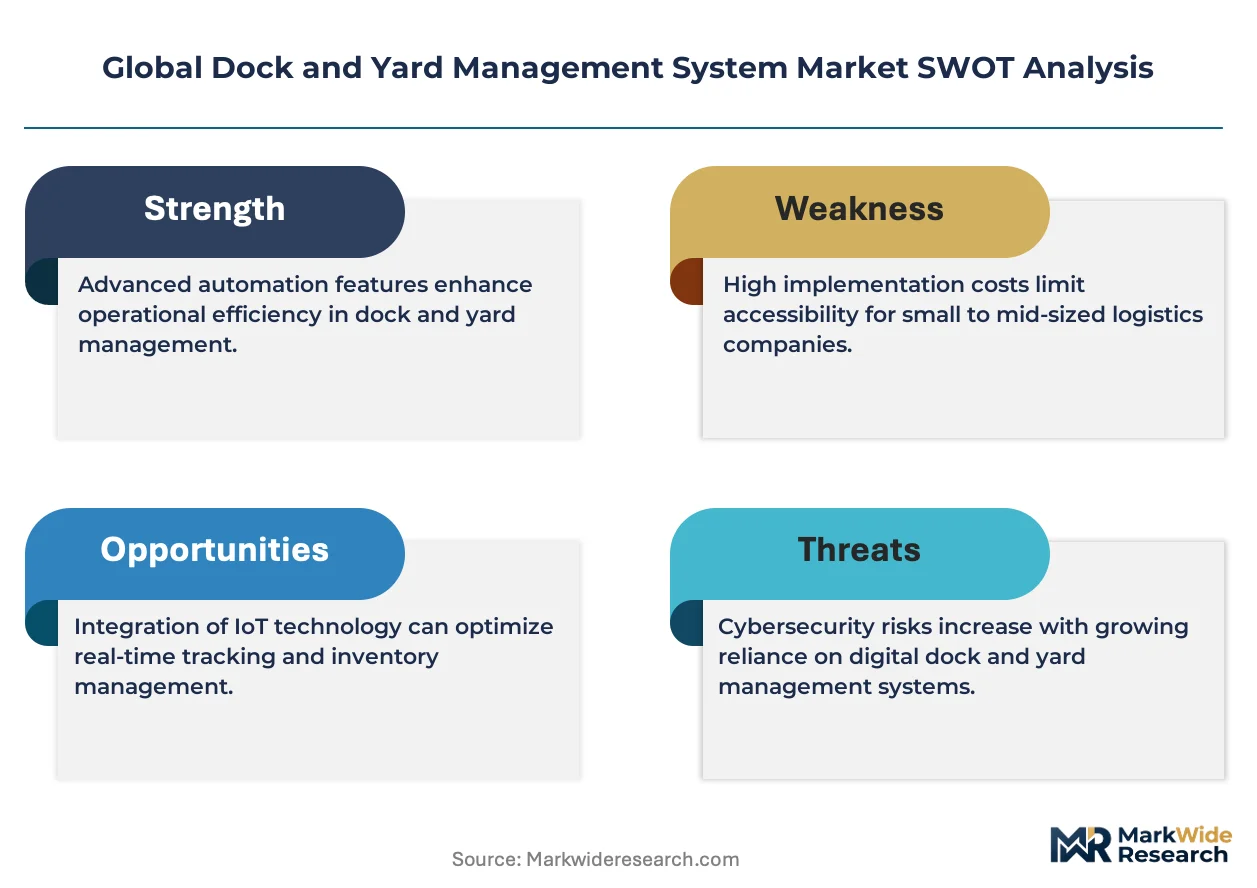
- RFID sensor hardware costs:Per-gate installation expenses for industrial-grade readers and ruggedized tags strain capital budgets at mid-market 3PL facilities, compressing ROI timelines below procurement committee thresholds.
- Telematics data fragmentation:Carrier-provided positioning feeds lack standardization across North American, European, and Asian fleet operators, forcing buyers to maintain parallel data integration layers for yard positioning accuracy.
- EU AI Act documentation burdens:Computer-vision gate systems deployed across German and Dutch distribution networks face algorithmic audit requirements that extend deployment timelines and inflate compliance consulting spend.
Strategic Opportunities
- India's PLI scheme for logistics infrastructure:Government production-linked incentives for automated material handling create favorable procurement conditions for dock scheduling platforms entering Mumbai and Delhi NCR warehouse markets.
- Drone-based yard inventory convergence:FAA regulatory frameworks for commercial unmanned aerial vehicle operations are enabling automated container counting and seal verification, opening new solution bundles for yard visibility vendors.
- API-first integration standards:Open connectivity protocols are displacing legacy EDI-based carrier appointment systems, allowing modular vendors to wedge into incumbent WMS-dominated accounts through interoperability guarantees.
Industry Challenges
- Certified systems integrator scarcity:Complex deployments combining RFID, GPS, and computer-vision layers require rare cross-functional expertise in industrial IoT and warehouse operations, extending implementation timelines and inflating professional services costs.
- Legacy WMS version fragmentation:Heterogeneous installed bases of decade-old warehouse management platforms resist API integration, forcing yard management vendors to maintain costly connector libraries for obsolete database architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dock and Yard Management System Market |
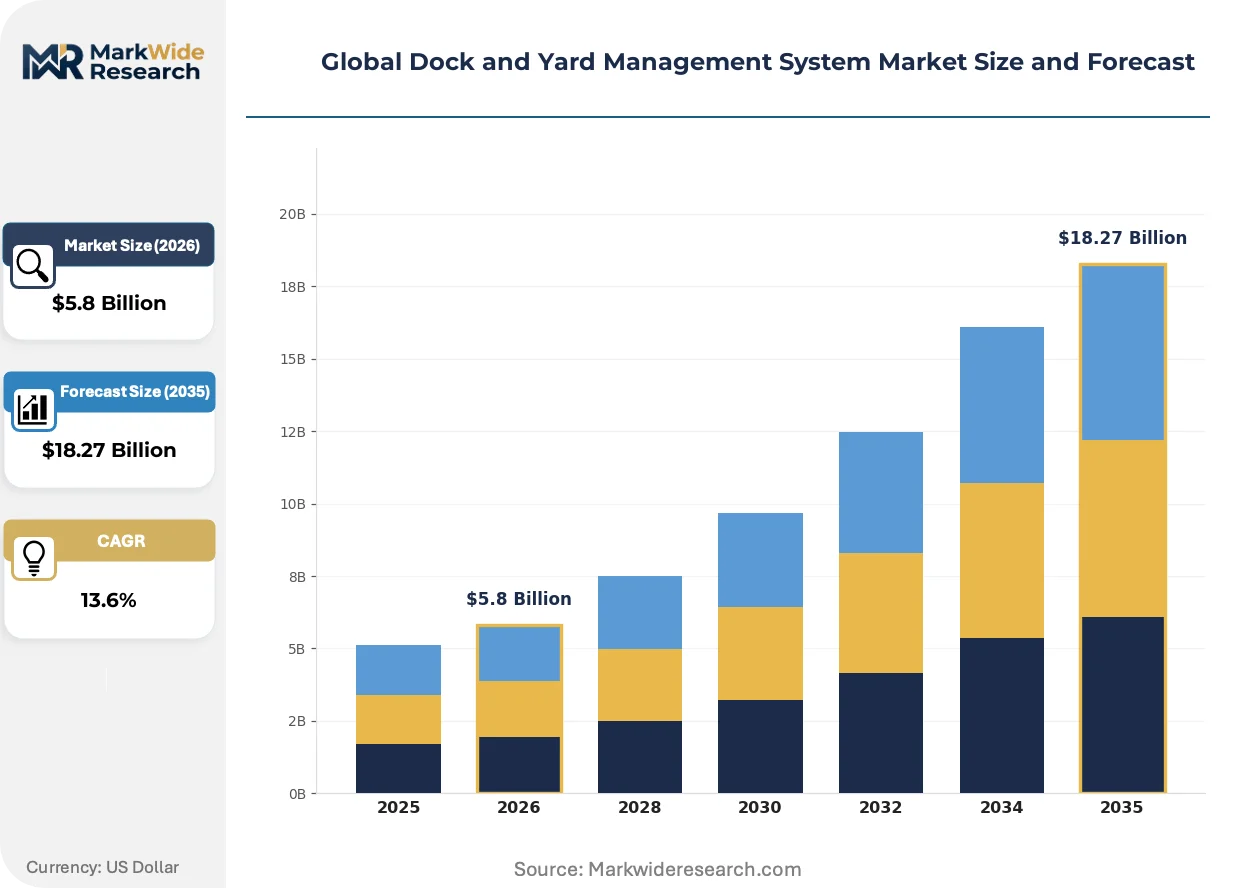
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $18.27 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Solution Offering: Scheduling, Resource Allocation, Inventory Tracking, Safety Compliance, Reporting Use Case: Freight Management, Inventory Optimization, Fleet Coordination, Loading Supervision End User Sector: Logistics Providers, Manufacturing Plants, Distribution Centers, Third-Party Administrators |
| Companies Covered | Zebra Technologies Corporation, Oracle Corporation, SAP SE, Manhattan Associates Inc., Descartes Systems Group Inc., Blue Yonder Group Inc., C3 Solutions Inc., 4SIGHT Connect, Epicor Software Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dock and Yard Management System Market Shifts & Advancements
Real-time location sensing hardware is compressing form factors and cost curves, while regulatory pressure on emissions and safety compliance reshapes software module priorities across deployment architectures.
Ultra-wideband (UWB) positioning chips are replacing legacy RFID for trailer-level yard tracking, delivering sub-meter accuracy in dense metallic environments. Regional grocery and parcel carriers in Germany and the Netherlands are piloting UWB anchor networks at 40% annual expansion rates. Component miniaturization is lowering per-trailer tag costs below passive RFID price points, compressing the addressable market for standalone GPS-based yard solutions.
EPA idling-reduction mandates in the United States are compelling dock management platforms to incorporate electric yard truck charging-schedule optimization as a core module. The regulation's industrial consequence is tighter coupling between vehicle dispatch algorithms and renewable energy availability windows. Cold-chain distribution centers in California and Texas are most affected, responding by procuring integrated yard-energy management bundles rather than standalone scheduling tools.
Subscription elasticity preferences among mid-market 3PLs are displacing perpetual-license procurement for dock and yard management software. Buyers now demand consumption-based pricing tied to gate transaction volumes rather than fixed seat counts. This behavioral shift is most visible among European freight forwarders operating seasonal peak-and-trough fulfillment patterns, who prioritize OpEx flexibility over long-term TCO optimization.
Global Dock and Yard Management System Market Segmentation
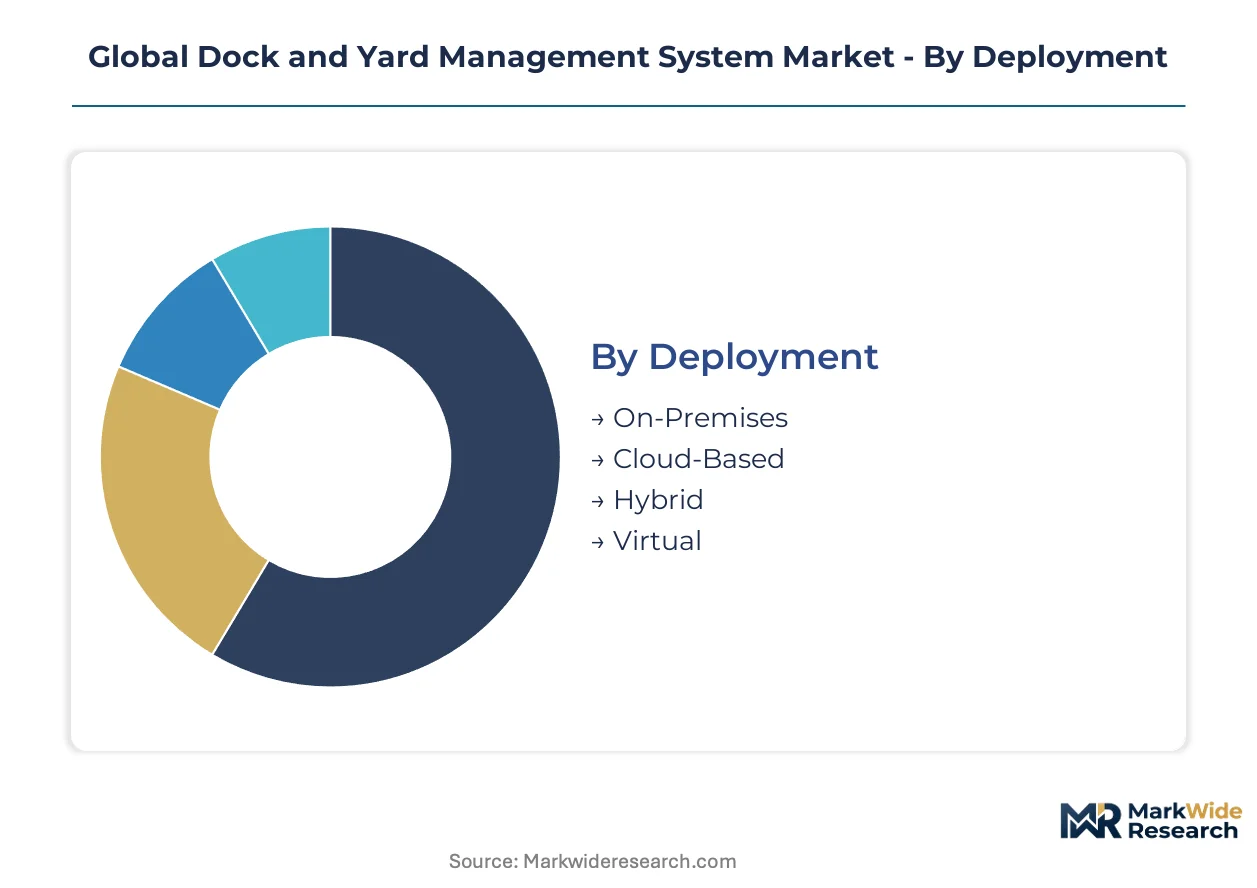
Deployment architecture choices determine capital intensity and integration complexity for yard automation projects. Solution packaging and use case prioritization vary sharply between domestic hub operators and export-oriented port facilities.
Deployment:
Domestic distribution networks favor subscription models, while export-heavy port clusters retain on-site control for latency-sensitive operations.
- On-Premises:Legacy server installations inside facility data centers deliver sub-millisecond response times for gate control hardware. German automotive plants and Shanghai port terminals maintain these deployments to satisfy data sovereignty requirements and avoid cloud connectivity dependencies during peak vessel berthing windows.
- Cloud-Based:Multi-tenant SaaS architectures eliminate upfront infrastructure spend and enable elastic scaling during seasonal volume spikes. Mid-market 3PLs across the United States and Netherlands select these platforms for rapid deployment across distributed warehouse footprints without dedicated IT staffing.
- Hybrid:Split architectures keep sensitive gate-control logic on-site while pushing analytics and carrier portals to hosted environments. This configuration dominates at California cold-chain facilities balancing OSHA compliance data retention with third-party carrier access requirements.
- Virtual:Containerized software deployments on hyperconverged infrastructure provide portability across edge computing nodes. Indian logistics parks under the PLI scheme pilot these setups for rapid replication across greenfield warehouse clusters near Mumbai and Delhi NCR.
On-Premises retains the largest installed base; momentum sits with Cloud-Based platforms expanding most quickly among capital-constrained operators.
Solution Offering:
Module selection tracks facility complexity, with high-volume hubs prioritizing carrier-facing functions over back-office analytics.
- Scheduling:Automated dock door appointment systems process carrier bookings, optimize trailer sequencing, and enforce detention penalty rules. E-commerce fulfillment centers in the United States and Germany pay premium subscription rates for these modules due to direct carrier cost avoidance.
- Resource Allocation:Yard jockey dispatch algorithms match driver availability to trailer priority queues in real-time. Texas and California distribution centers deploy these tools most aggressively to offset certified operator shortages and compress trailer dwell times.
- Inventory Tracking:RFID and UWB-enabled yard visibility functions monitor container location, seal status, and dwell duration. WMS vendors bundle these capabilities into platform renewals, compressing standalone pricing for point solutions.
- Safety Compliance:Pedestrian-traffic monitoring and OSHA documentation modules automate loading zone hazard detection. U.S. facilities facing escalating enforcement deadlines drive procurement of computer-vision gate systems with integrated incident logging.
- Reporting:Carrier scorecards, detention analytics, and yard throughput dashboards support continuous improvement programs. European freight forwarders prioritize these modules for CSRD-aligned sustainability disclosure and Scope 3 emissions tracking.
Scheduling commands the highest module pricing; Safety Compliance is climbing fastest on regulatory enforcement timelines.
Use Case:
Application prioritization splits between asset-heavy fleet operators and inventory-focused warehouse managers.
- Freight Management:Ocean-rail-truck handoff coordination across intermodal terminals demands real-time visibility across carrier systems. Port authorities in China and the Netherlands invest here to minimize vessel demurrage and railcar detention.
- Inventory Optimization:Yard-level stock positioning and cross-dock sequencing reduce safety stock requirements and accelerate order cycle times. Regional grocery distribution networks in Germany deploy these capabilities to support just-in-time store replenishment.
- Fleet Coordination:Electric yard truck dispatch and charging-schedule integration align vehicle availability with renewable energy windows. California cold-chain operators procure these solutions to satisfy EPA idling-reduction mandates.
- Loading Supervision:Dock door activity monitoring and load verification ensure trailer seal integrity and weight compliance. U.S. pharmaceutical distributors prioritize this use case for FDA supply chain security requirements.
Freight Management holds the largest addressable spend; Fleet Coordination is expanding most rapidly on electrification mandates.
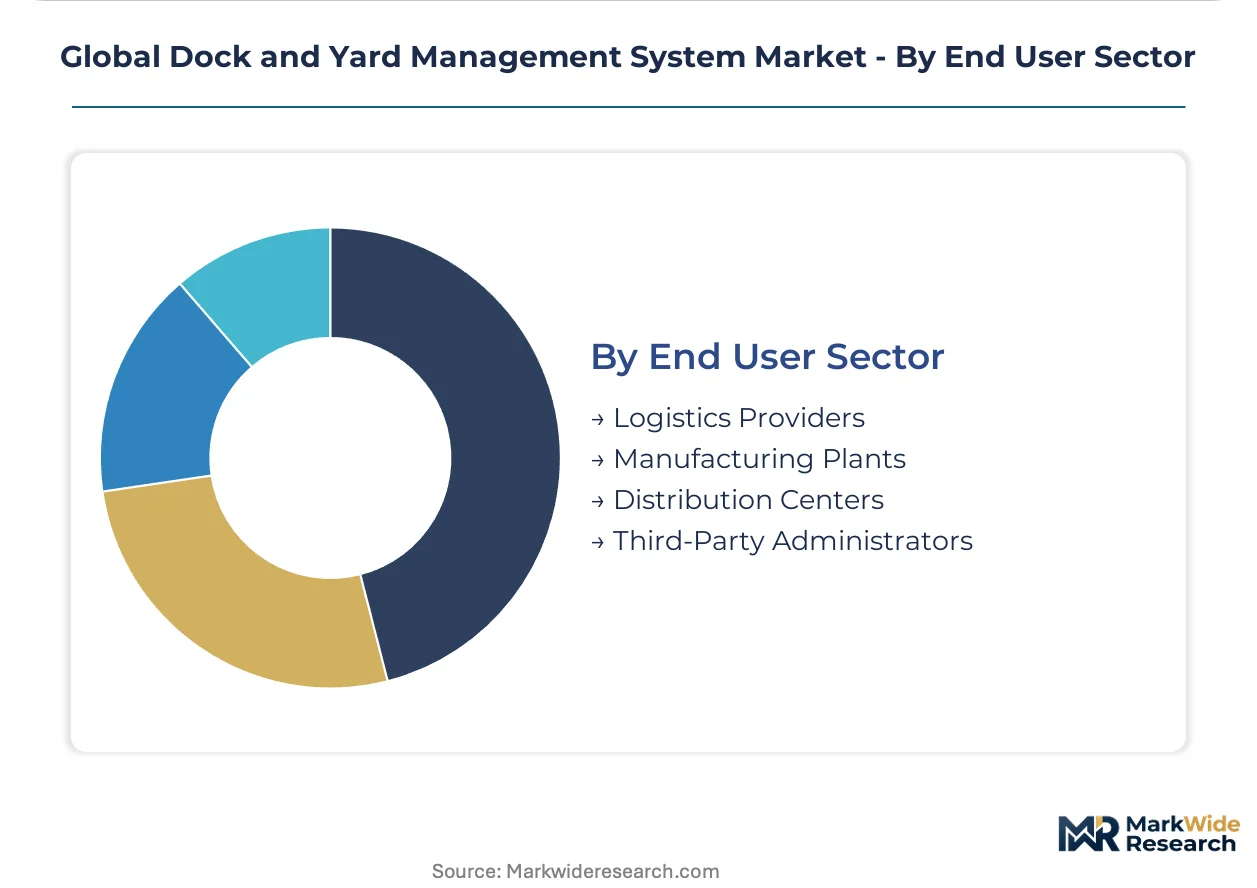
End User Sector:
Buyer sophistication and procurement authority vary sharply between outsourced operators and captive corporate facilities.
- Logistics Providers:Asset-based carriers and dedicated contract operators seek modular platforms supporting multi-customer yard visibility without data commingling.
- Manufacturing Plants:Automotive and electronics producers integrate dock scheduling with production line sequencing to enforce just-in-time inbound delivery windows.
- Distribution Centers:High-velocity parcel and grocery hubs prioritize sub-minute yard updates and automated gate processing to avoid carrier penalties.
- Third-Party Administrators:Freight brokers and managed transportation providers procure lightweight scheduling modules for carrier appointment coordination without physical yard infrastructure.
Distribution Centers represent the deepest installed base; Third-Party Administrators are gaining share fastest on asset-light 4PL model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA pedestrian-traffic separation mandates in the United States are accelerating automated gate portal deployments across distribution networks. Warehouse operators in Germany face EU AI Act documentation burdens for computer-vision systems. China's MIIT dual carbon goals are reshaping yard truck electrification requirements at port clusters.
United States
E-commerce fulfillment density and intermodal freight volumes drive demand for real-time yard visibility. EPA idling-reduction mandates compel dock management platforms to integrate electric yard truck charging-schedule optimization. California and Texas cold-chain distribution centers procure integrated yard-energy management bundles to satisfy compliance deadlines.
Germany
Automotive plants enforce just-in-time inbound delivery windows through production line sequencing integration. EU AI Act algorithmic audit requirements extend deployment timelines for computer-vision gate systems across German and Dutch distribution networks. Regional grocery and parcel carriers in Germany pilot ultra-wideband positioning anchor networks at expanding annual rates.
China
Shanghai and Shenzhen port clusters require dock management platforms to incorporate charging-schedule optimization for electric yard trucks. MIIT dual carbon goals mandate tighter coupling between vehicle dispatch algorithms and renewable energy availability windows. Export-heavy terminals retain on-premises deployments to satisfy data sovereignty requirements and avoid cloud connectivity dependencies during peak vessel berthing windows.
India
Government production-linked incentives for automated material handling create favorable procurement conditions for dock scheduling platforms. Mumbai and Delhi NCR warehouse markets pilot containerized software deployments on hyperconverged infrastructure for rapid replication across greenfield logistics parks. The country's national logistics infrastructure program accelerates adoption of subscription-based deployment models among capital-constrained operators.
Netherlands
European freight forwarders prioritize consumption-based pricing tied to gate transaction volumes for seasonal peak-and-trough fulfillment patterns. CSRD-aligned sustainability disclosure requirements drive procurement of reporting modules for Scope 3 emissions tracking. Rotterdam port authorities invest in ocean-rail-truck handoff coordination to minimize vessel demurrage and railcar detention across intermodal terminals.
Global Dock and Yard Management System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the dock and yard management system market. The upper tier combines warehouse management system depth with multimodal connectivity spanning ocean, rail, and over-the-road freight handoffs. Three archetypes dominate competitive positioning: hardware-software convergence specialists, deep WMS integrators, and modular API-first vendors. M&A activity concentrates on telematics data layer consolidation, while strategic partnerships target electric yard truck ecosystem integration.
Within the integrated leader tier, Zebra Technologies Corporation leverages its hardware-software convergence in mobile computing and RFID to capture yard visibility contracts. Manhattan Associates Inc. anchors its position through deep warehouse management system integration. Descartes Systems Group Inc. occupies a position competing on multimodal connectivity. These three represent distinct strategic vectors: hardware-software bundling, platform ecosystem depth, and transportation network reach.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| Oracle Corporation |
| SAP SE |
| Manhattan Associates Inc. |
| Descartes Systems Group Inc. |
| Blue Yonder Group Inc. |
| C3 Solutions Inc. |
| 4SIGHT Connect |
| Epicor Software Corporation |
| Others |
Supply & Pricing Matrix
Capacity-reservation contracts with UWB sensor manufacturers lock in both hardware supply access and price visibility for distribution centers facing OSHA compliance deadlines. These multi-year procurement structures insulate buyers from RFID component volatility while committing capital upfront.
Pricing Analysis
Subscription pricing spreads between North American and European deployments reflect differential cloud infrastructure costs and regulatory compliance burdens. SaaS-tiered models dominate, with premium tiers capturing carriers demanding sub-minute yard updates and economy tiers serving seasonal 3PLs. Price differentiation rests on integration complexity and WMS certification level. Cost compression in mid-market scheduling modules intensifies as WMS vendors bundle yard visibility into platform renewals. Asset-light freight brokers exhibit highest price sensitivity; automotive plants with JIT sequencing requirements show least.
Supply Chain Analysis
Taiwanese semiconductor foundry capacity constrains UWB positioning chip availability for trailer-tracking hardware. Industrial IoT sensor supply concentrates in China, South Korea, and Germany, drawing from rare earth magnet feeds and precision MEMS fabrication. Single-source vulnerability runs through Taiwanese 12-inch wafer output for UWB anchor networks. Distribution runs through direct OEM relationships and certified systems integrator channels serving warehouse automation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified systems integrator scarcity—combining industrial IoT expertise with warehouse operations knowledge—defines competitive moats in this market. Organizations that control this talent pipeline capture deployment timelines and margin structures.
For Market Incumbents: Fortify API-first integration standards to defend against modular vendors penetrating WMS-dominated accounts. Deepen backward integration into UWB sensor hardware to offset Taiwanese foundry chokepoints and capture margin from RFID-to-UWB technology transitions. Prioritize OSHA compliance module certification to lock out challengers facing escalating enforcement timelines. For New Entrants and Emerging Players: Anchor in India's PLI-funded logistics parks where greenfield warehouse clusters lack incumbent vendor relationships. Target containerized virtual deployments for rapid replication across Mumbai and Delhi NCR facilities without dedicated IT staffing. Lead with consumption-based pricing tied to gate transaction volumes to exploit seasonal 3PL procurement preferences. For Investors and Strategic Acquirers: Cross-functional industrial IoT specialists with warehouse domain expertise represent the most defensible acquisition profile over the coming decade. Telematics data layer consolidation signals inflection timing as carriers standardize positioning feeds and reduce parallel integration burdens. Monitor FAA drone regulation advancement as yard inventory automation creates new solution bundle categories.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Open connectivity protocols displace legacy EDI systems and enable modular vendor penetration of incumbent accounts. |
| Electric Yard Truck Ecosystem Partnership | Charging-schedule optimization modules satisfy EPA idling-reduction mandates and MIIT dual carbon goals. |
| UWB Hardware Backward Integration | In-house positioning chip sourcing insulates margins from Taiwanese foundry capacity constraints. |
| Drone-Based Yard Inventory Launch | FAA-compliant unmanned aerial vehicle operations enable automated container counting and seal verification bundles. |
| CSRD-Aligned Reporting Module Development | Scope 3 emissions tracking capabilities capture European freight forwarder procurement priorities. |
Research Methodology
Cross-validation between primary interviews with yard operations directors and secondary validation through customs trade data anchors the qualitative findings. CTOs at third-party logistics providers, dock supervisors at California cold-chain facilities, integration specialists at WMS vendors, and procurement leads at German automotive plants contributed structured input. SEC 10-K filings, EPC project databases, OSHA enforcement records, and EU AI Act implementation guidance provided external triangulation. Bottom-up deployment counts and top-down logistics infrastructure spend estimates were reconciled.
Sensitivity analysis across deployment architecture preferences, solution module uptake rates, and electrification compliance timelines shapes the analytical framework. Segmentation dimensions modeled include deployment model, facility complexity tier, end-user sector, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure investment trajectories. Electric yard truck penetration rates and UWB sensor cost curves represent critical forecast inputs.
Material uncertainties—OSHA enforcement acceleration, Taiwanese semiconductor supply disruptions, EU AI Act audit requirement expansion—sit outside the modeled envelope. Forecasts reflect assumptions about carrier telematics standardization and WMS vendor bundling strategies. Practitioners should keep alternative scenarios live as FAA drone regulation and MIIT electrification mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Machine Translation (MT) Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Captioning and Subtitling Solutions Market
Digital Solutions
Global Network Engineering Service Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Location As a Service Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
Latin America IT Market
Digital Solutions
APAC Smart Office Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Smart and Mobile Supply Chain Solutions Market