
 Demand Signal Repository Solutions Market | 2026-2036
Demand Signal Repository Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Demand Signal Repository Solutions Market Outlook
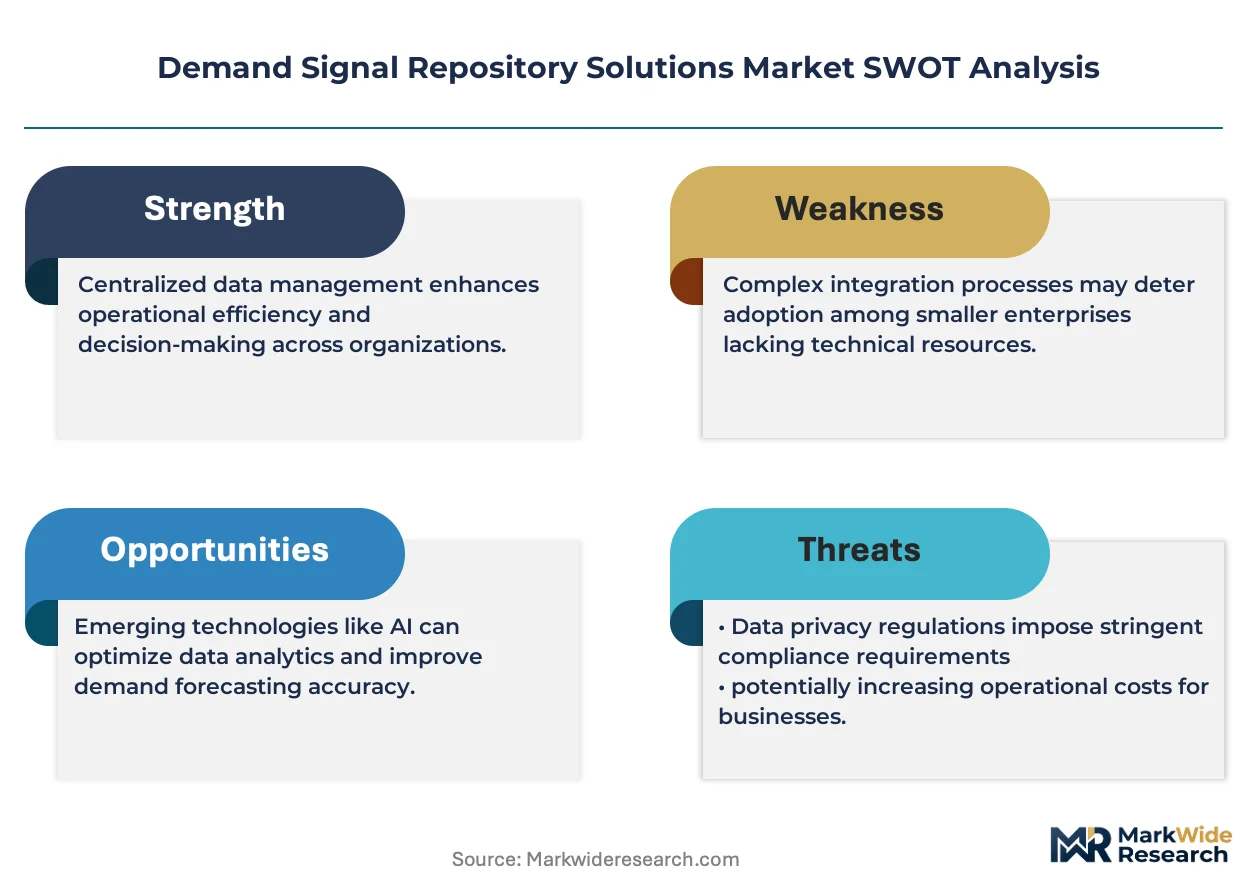
Data engineering talent scarcity is collapsing implementation timelines for demand signal repository deployments. Oracle Corporation leverages its enterprise database heritage to anchor large-scale retail analytics integrations. Infosys Limited sustains competitive positioning through specialized supply chain consulting bundled with platform deployment. Teradata dominates on-premise data warehouse environments where consumer goods manufacturers retain sensitive demand data.
Demand signal repository solutions aggregate, harmonize, and analyze downstream point-of-sale and inventory data to generate actionable demand intelligence for supply chain planning. These systems typically process streaming data feeds from retail EDI transactions, IoT shelf sensors, and distributor inventory levels with latency requirements under 24 hours for operational decision-making. Cloud-based deployments are capturing the fastest growth as consumer goods companies prioritize elastic compute for seasonal demand spikes. Supply chain optimization applications command the deepest margin pools because they integrate directly with ERP procurement modules and generate measurable working capital improvements. On-premise installations persist in manufacturing verticals where air-gapped environments satisfy stringent data sovereignty requirements.
FDA traceability mandates for food and pharmaceutical supply chains are compelling demand signal investments that enable lot-level tracking from retail shelf to supplier. The EU AI Act's risk classification framework for automated demand forecasting algorithms is reshaping vendor compliance roadmaps across European deployments. GDPR data localization requirements continue influencing hybrid architecture decisions for multinational consumer goods corporations. Stakeholders must evaluate whether their current data governance frameworks can accommodate emerging algorithmic audit requirements without compromising real-time demand sensing capabilities.
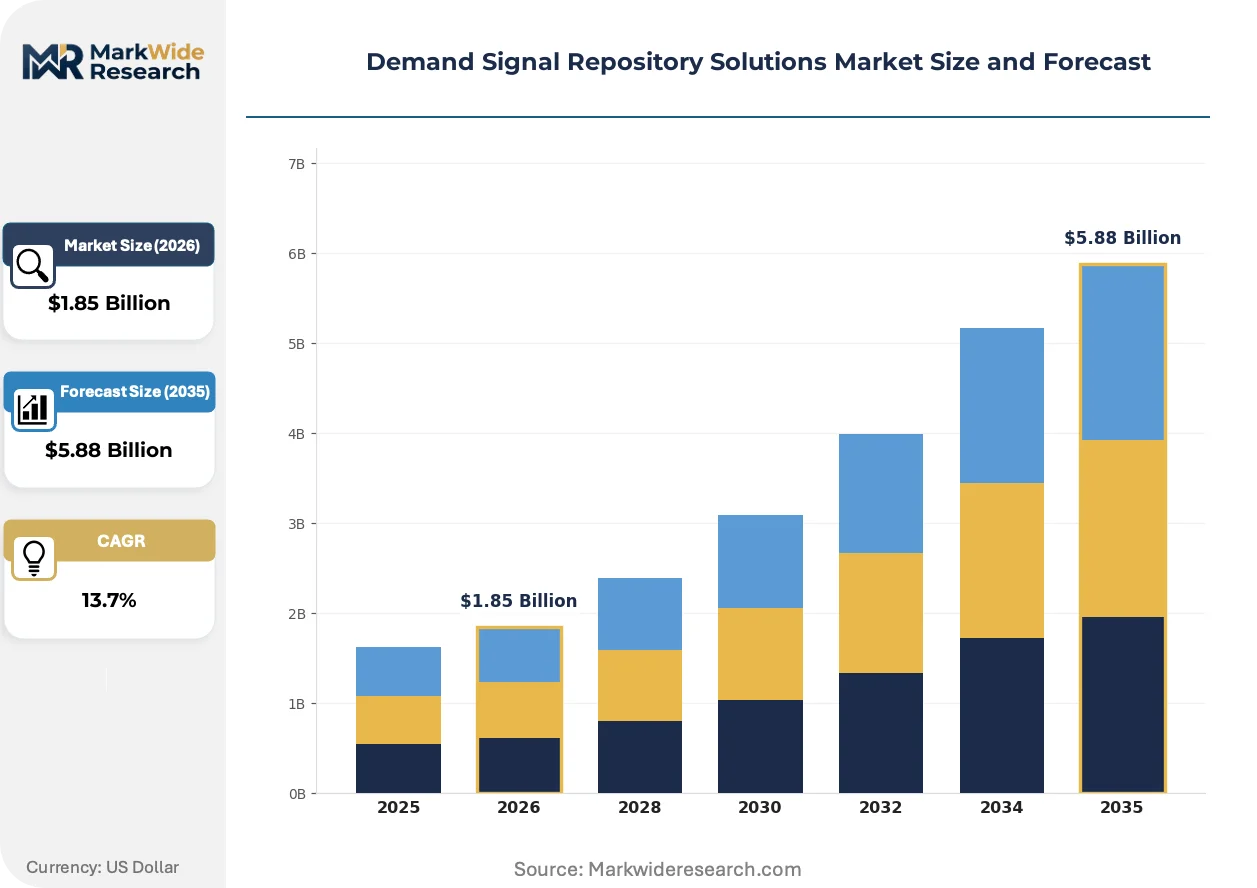
Market Dynamics
Cloud migration mandates under the EU AI Act and analogous data governance frameworks are compressing procurement timelines while forcing architectural redesigns for real-time demand sensing capabilities.
Growth Catalysts
- EU AI Act compliance deadlines:Consumer goods manufacturers accelerate platform investments to satisfy algorithmic audit requirements for automated demand forecasting systems.
- IoT shelf sensor proliferation:Retailers deploy edge computing devices that stream inventory velocity data directly into repository architectures with sub-hour latency.
- FDA traceability mandates:Food and pharmaceutical supply chains require lot-level tracking from retail shelf to supplier, embedding demand signal infrastructure into compliance workflows.
Market Restraints
- Data engineering talent scarcity:Implementation timelines collapse as specialized pipeline architects command premium compensation and limited availability.
- On-premise infrastructure lock-in:Manufacturing verticals with air-gapped environments face high switching costs when migrating sensitive demand data to cloud architectures.
- GDPR localization friction:Hybrid architecture decisions multiply for multinational corporations navigating divergent national data sovereignty interpretations.
Strategic Opportunities
- Seasonal elasticity demand:Consumer goods companies prioritize cloud-native deployments that scale compute resources during peak retail periods without permanent infrastructure expansion.
- Supply chain optimization integration:Repository platforms that connect directly with ERP procurement modules capture working capital improvement budgets.
- India's PLI scheme for electronics manufacturing:Domestic production incentives create greenfield demand signal infrastructure requirements for new consumer goods facilities.
Industry Challenges
- Real-time pipeline engineering:Maintaining sub-24-hour latency for operational decision-making strains data architecture teams across streaming EDI and sensor feeds.
- Algorithmic governance complexity:Automated demand forecasting systems require documented risk classification frameworks that satisfy emerging audit protocols without degrading predictive performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demand Signal Repository Solutions Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
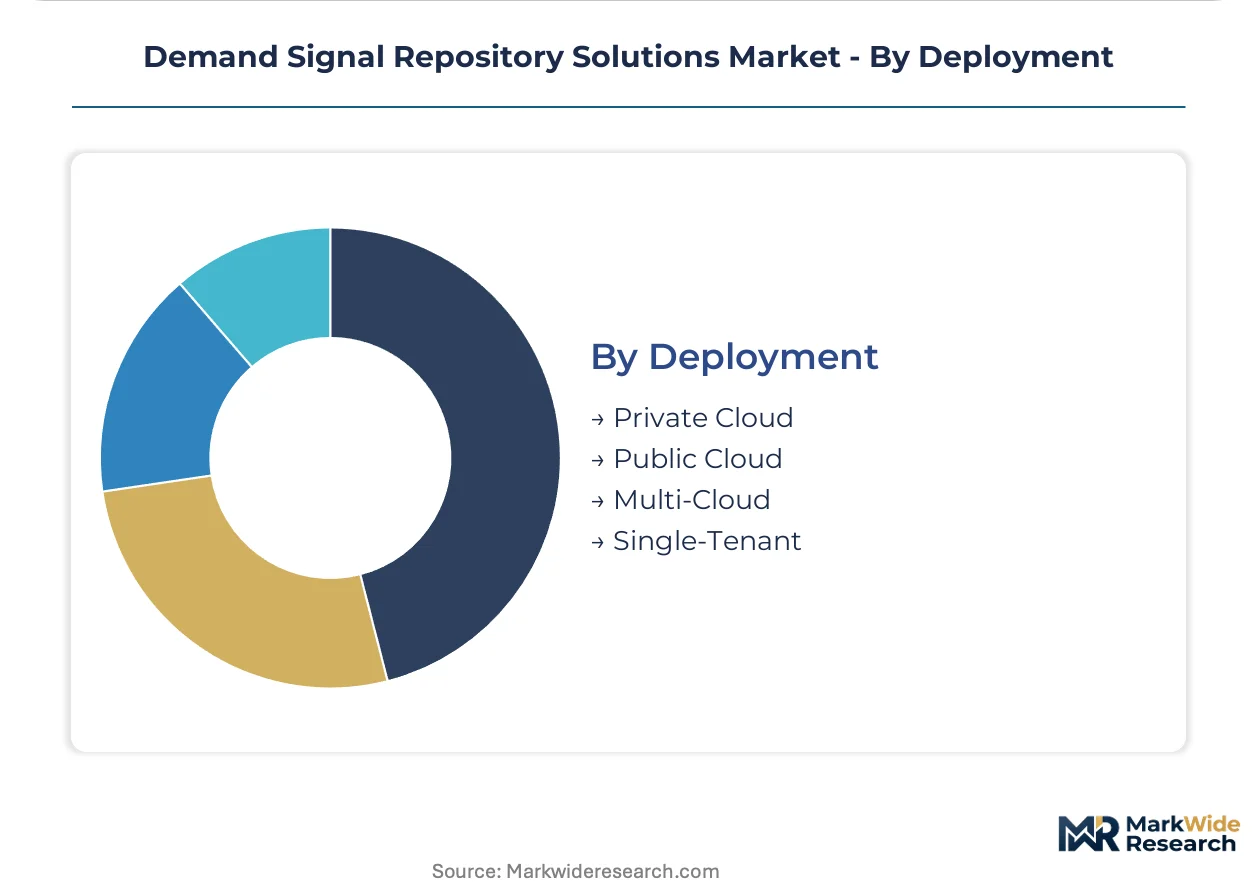
| Segmentation | Technology: Cloud-Based, On-Premise, Hybrid, SaaS Application: Retail Analytics, Inventory Management, Supply Chain Optimization, Demand Forecasting End User: Consumer Goods, Manufacturing, Wholesale Distribution, E-Commerce Deployment: Private Cloud, Public Cloud, Multi-Cloud, Single-Tenant |
| Companies Covered | Oracle Corporation, Infosys Limited, Teradata, Manthan Software Services Pvt. Ltd, ToolsGroup, One Network, To-Increase, Relational Solutions, Inc, Vendor Managed Technologies, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demand Signal Repository Solutions Market Strategic Shifts
Edge computing architectures are compressing data processing latency while regulatory algorithmic governance frameworks reshape vendor development roadmaps and procurement evaluation criteria.
Stream processing engines for retail EDI transactions is miniaturizing compute footprints required for point-of-sale harmonization. Mid-market consumer goods manufacturers adopt containerized deployments to bypass enterprise data center investments. This compression is miniaturizing total cost of ownership curves and expanding addressable buyer segments beyond Fortune 500 accounts.
REACH chemical traceability extensions are forcing ingredient-level data granularity into demand signal repositories serving European cosmetics and packaged food manufacturers. The industrial consequence cascades through formulation planning systems that must now reconcile retail velocity against substance of very high concern screening databases. Cosmetics brands with complex European distribution footprints reconfigure master data architectures to accommodate substance volume tracking.
Buyer concentration among mega-retailers is consolidating data feed negotiation leverage. Consumer goods manufacturers face standardized API requirements from dominant grocery and mass merchandise channels that constrain customization flexibility. This pattern concentrates most acutely in the United States where retail data infrastructure investments have outpaced supplier technology maturation.
Demand Signal Repository Solutions Market Segmentation
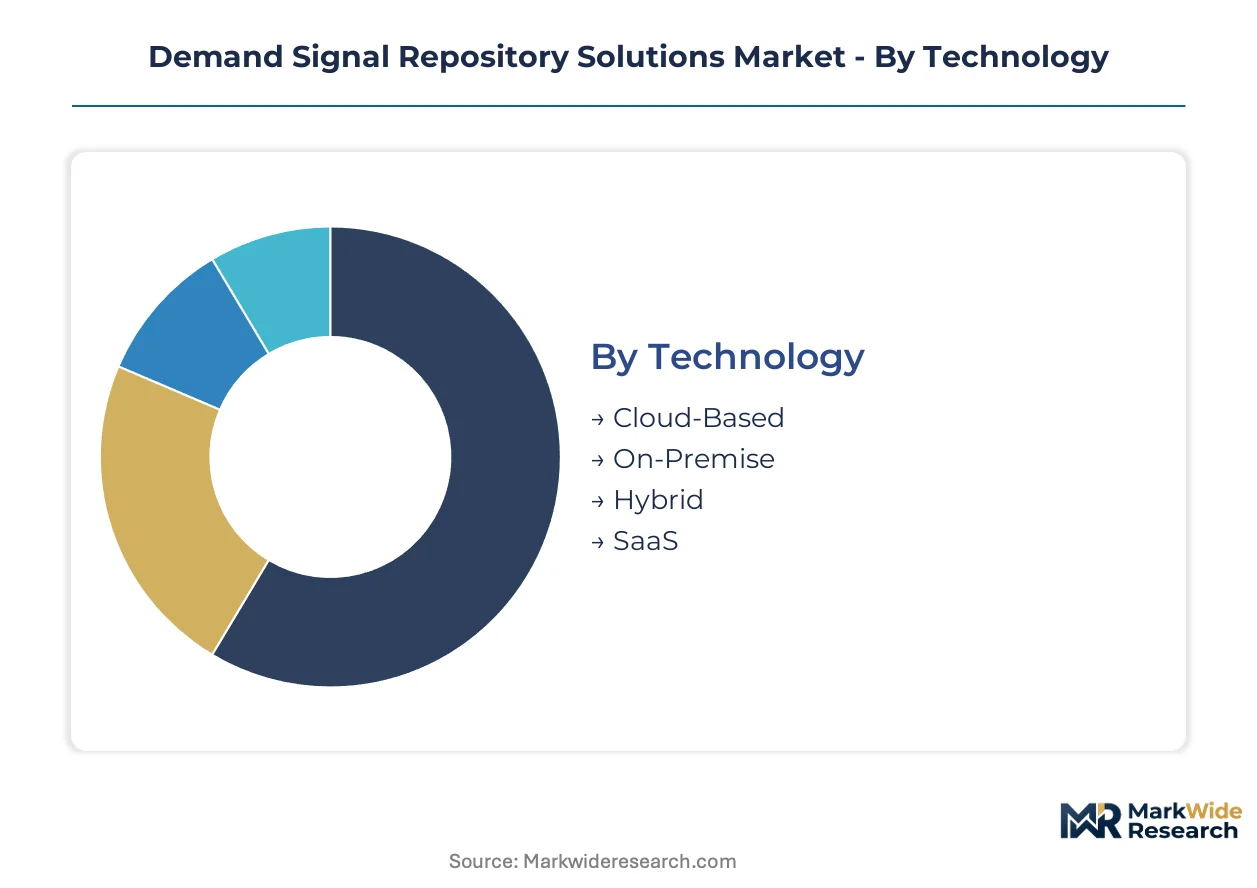
Technology deployment choices determine latency thresholds and compliance posture for demand signal architectures. Application focus areas separate working capital optimization budgets from pure analytics spending. End-user verticals exhibit divergent data sovereignty requirements that reshape vendor selection criteria.
Technology:
Margin pools concentrate in elastic compute configurations that monetize seasonal demand volatility without permanent infrastructure commitments.
- Cloud-Based:Elastic compute architectures process streaming EDI and IoT feeds with automatic scaling during retail peak periods. Consumer goods manufacturers in the United States prioritize these deployments to avoid capital expenditure lock-in while satisfying sub-24-hour latency requirements for operational decision-making.
- Hybrid:Split architectures retain sensitive demand data in air-gapped environments while pushing anonymized analytics workloads to public infrastructure. GDPR localization friction and FDA traceability mandates drive European and North American pharmaceutical manufacturers toward this configuration.
- On-Premise:Fixed-capacity data warehouses dominate manufacturing verticals with stringent data sovereignty requirements.
- SaaS:Subscription delivery models compress implementation timelines for mid-market consumer goods manufacturers lacking specialized data engineering talent.
On-Premise holds installed capacity. Cloud-Based is rotating up the share rankings.
Application:
Supply chain optimization commands premium pricing through direct ERP integration and measurable working capital improvements.
- Supply Chain Optimization:Repository platforms connect procurement modules to downstream demand signals, generating inventory reduction and service level improvements. Consumer goods manufacturers with complex distributor networks deploy these applications to collapse safety stock buffers without risking stockouts.
- Demand Forecasting:Algorithmic prediction engines ingest harmonized point-of-sale data to generate SKU-level projections with automated risk classification under EU AI Act frameworks. European deployments require documented audit trails that satisfy emerging algorithmic governance protocols without degrading predictive accuracy.
- Retail Analytics:Visualization and reporting layers aggregate multi-channel point-of-sale streams for category management negotiations.
- Inventory Management:Real-time stock positioning applications synchronize warehouse and shelf-level data for replenishment automation.
Retail Analytics holds installed capacity. Supply Chain Optimization is rotating up the share rankings.
End User:
Consumer goods manufacturers generate the deepest demand signal investments as retail data feed negotiations intensify.
- Consumer Goods:Manufacturers of packaged foods, beverages, and personal care products deploy repository solutions to unify mega-retailer EDI streams and IoT shelf sensor networks. FDA traceability mandates for lot-level tracking from retail shelf to supplier embed demand signal infrastructure into compliance workflows.
- Manufacturing:Industrial producers with captive distribution channels leverage demand signals for production scheduling and raw material procurement. Air-gapped environments persist in defense-adjacent and critical infrastructure verticals where data sovereignty requirements preclude cloud migration.
- Wholesale Distribution:Mid-tier distributors adopt containerized deployments to bypass enterprise data center investments.
- E-Commerce:Pure-play digital retailers prioritize real-time pipeline engineering for clickstream-to-fulfillment synchronization.
Manufacturing holds installed capacity. Consumer Goods is rotating up the share rankings.
Deployment:
Multi-cloud configurations attract procurement attention as buyer organizations seek to avoid vendor lock-in and satisfy divergent national data localization requirements.
- Multi-Cloud:Architectures distribute workloads across competing hyperscaler infrastructures to optimize cost-performance ratios and satisfy jurisdictional data residency rules. Multinational corporations navigating GDPR, EU AI Act, and FDA overlapping requirements deploy these configurations to maintain operational flexibility.
- Private Cloud:Dedicated infrastructure deployments serve consumer goods manufacturers with sensitive competitive intelligence or intellectual property concerns. Single-tenant environments satisfy procurement security questionnaires from tier-one retailers while retaining customization flexibility.
- Public Cloud:Shared infrastructure delivers lowest unit economics for seasonal elasticity demand.
- Single-Tenant:Isolated deployments persist in financial services-adjacent supply chain finance applications.
Private Cloud holds installed capacity. Multi-Cloud is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand signal repository deployments vary sharply by geography, with United States buyers prioritizing cloud elasticity for seasonal retail spikes while European manufacturers navigate algorithmic audit mandates under the EU AI Act.
United States
Mega-retailer data feed standardization and FDA traceability mandates for food and pharmaceutical supply chains drive platform investments. Retail data infrastructure investments outpace supplier technology maturation, concentrating negotiation leverage among dominant grocery and mass merchandise channels. Consumer goods manufacturers in Chicago and Minneapolis-St. Paul deploy these solutions to unify point-of-sale streams and IoT shelf sensor networks.
Germany
REACH chemical traceability extensions force ingredient-level data granularity into demand signal repositories serving cosmetics and packaged food manufacturers. The EU AI Act's risk classification framework for automated demand forecasting algorithms reshapes vendor compliance roadmaps across Bavaria and North Rhine-Westphalia. Industrial producers in Stuttgart's manufacturing corridor leverage demand signals for production scheduling amid stringent data sovereignty requirements.
China
Domestic electronics manufacturing expansion under industrial upgrading policies creates greenfield demand signal infrastructure requirements for new consumer goods facilities. MIIT data localization standards and SAMR algorithmic governance guidelines influence hybrid architecture decisions for multinational corporations operating production bases. Yangtze River Delta manufacturers deploy these platforms to synchronize warehouse and shelf-level data for replenishment automation.
India
The PLI scheme for electronics manufacturing generates demand signal investments as domestic production incentives attract new consumer goods facilities. CDSCO traceability requirements for pharmaceutical supply chains embed repository infrastructure into compliance workflows. Karnataka and Maharashtra-based manufacturers adopt containerized deployments to bypass enterprise data center investments while processing streaming EDI transactions.
United Kingdom
Post-Brexit regulatory divergence creates hybrid architecture complexity as manufacturers navigate GDPR localization friction alongside domestic algorithmic governance proposals. London-based consumer goods headquarters prioritize multi-cloud configurations to maintain operational flexibility across divergent national data residency rules. Midlands manufacturing clusters retain sensitive demand data in air-gapped environments while pushing anonymized analytics workloads to public infrastructure.
Demand Signal Repository Solutions Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with enterprise database heritage and supply chain consulting capabilities defining competitive differentiation. The market structure consolidates around technology providers with pre-existing retail analytics relationships and systems integrators bundling platform deployment with change management services. Two strategic archetypes dominate: hyperscaler-aligned platforms leveraging elastic compute architectures, and on-premise data warehouse specialists serving air-gapped manufacturing environments. Competitive moves center on cloud migration acceleration partnerships and algorithmic audit compliance certification programs.
Within the enterprise platform tier, Oracle Corporation and Teradata occupy positions reflecting divergent deployment philosophies, while Infosys Limited exemplifies the consulting-anchored systems integrator model. Oracle's enterprise database heritage supports large-scale retail analytics integrations, Teradata dominates fixed-capacity data warehouse environments where manufacturers retain sensitive demand data, and Infosys sustains positioning through specialized supply chain consulting bundled with platform deployment. These three entities collectively span the technology spectrum from on-premise infrastructure through hybrid configurations to fully managed cloud services.
| Leading Market Players |
|---|
| Oracle Corporation |
| Infosys Limited |
| Teradata |
| Manthan Software Services Pvt. Ltd |
| ToolsGroup |
| One Network |
| To-Increase |
| Relational Solutions, Inc |
| Vendor Managed Technologies, Inc |
| Others |
Value Chain & Pricing Dynamics
Containerized deployment architectures displacing traditional enterprise data center investments are redrawing supply geography toward India and Eastern European engineering hubs while collapsing total cost of ownership curves for mid-market buyers. This substitution simultaneously compresses pricing premiums historically commanded by on-premise specialists and expands addressable segments beyond Fortune 500 accounts.
Pricing Analysis
Long-term SaaS subscription contracts dominate enterprise procurement, with annual recurring revenue tiers scaling by data volume throughput and ERP integration complexity. Price differentiation separates hyperscaler-aligned platforms with elastic compute guarantees from fixed-capacity on-premise installations serving air-gapped manufacturing environments. Pricing pressure stems from data engineering talent scarcity collapsing implementation timelines and forcing vendors to absorb professional services costs. Mid-market consumer goods manufacturers exhibit highest price sensitivity, while pharmaceutical verticals with FDA traceability mandates accept premium positioning for compliance-certified configurations.
Supply Chain Analysis
Just-in-time pipeline engineering preferences dominate cloud-native deployments, though hybrid architectures require strategic stockpiles of specialized data engineering talent in European and North American delivery centers. Supply concentration centers on the United States, India, and Germany for platform development and systems integration capacity. Component dependencies include streaming EDI transaction processors, edge computing hardware for IoT shelf sensors, and algorithmic audit documentation frameworks. Single-source vulnerability concentrates around hyperscaler infrastructure commitments. Distribution runs through direct enterprise sales organizations and systems integrator partnerships bundling change management services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Demand signal repository solutions sit in early-cycle expansion as EU AI Act compliance deadlines force algorithmic audit investments across European consumer goods manufacturers. Cloud migration mandates under data governance frameworks accelerate replacement of legacy on-premise data warehouses.
For Market Incumbents: Shield installed base relationships by embedding algorithmic governance certification programs into existing enterprise contracts before compliance deadlines crystallize competitive switching opportunities. Accelerate cloud migration partnerships with hyperscalers to neutralize threat from SaaS-native entrants offering faster deployment timelines. Prioritize vertical integration into specialized supply chain consulting capabilities that bundle platform deployment with measurable working capital improvement guarantees.
For New Entrants and Emerging Players: EU AI Act algorithmic audit fast-tracks for automated demand forecasting systems open procurement doors at European consumer goods manufacturers facing compressed compliance timelines. Target mid-market packaged food and personal care segments in India under PLI scheme electronics manufacturing incentives, where greenfield facilities lack legacy infrastructure lock-in. Pursue containerized deployment go-to-market positioning that bypasses enterprise data center capital requirements and collapses sales cycles.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed supply chain software specialists holding fragmented retail analytics customer bases but lacking demand signal repository platform breadth. Long-term viability hinges on consolidation plays that assemble end-to-end demand-to-supply chain intelligence stacks. Watch FDA traceability mandate enforcement intensity as inflection indicator for pharmaceutical vertical platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Governance Certification Program | EU AI Act compliance positioning secures procurement preference at European consumer goods manufacturers. |
| Cloud Migration Acceleration Partnership | Hyperscaler alliances neutralize SaaS-native entrant advantages in elastic compute provisioning. |
| Supply Chain Consulting Capability Buildout | Working capital improvement guarantees deepen platform stickiness with procurement module integration. |
| Edge Computing Architecture Investment | Sub-hour latency IoT shelf sensor processing captures retailer data feed standardization leverage. |
| Multi-Cloud Configuration Development | Jurisdictional data residency flexibility satisfies GDPR localization friction across multinational deployments. |
Study Parameters
Desk research of SEC filings from enterprise software vendors, hyperscaler capex disclosures, and regulatory guidance documents from FDA and EU AI Act implementing bodies preceded structured interviews with supply chain planning directors, data engineering leads, retail analytics procurement officers, and systems integration partners. Primary fieldwork captured implementation timeline compression effects from talent scarcity and compliance-driven procurement acceleration. Secondary validation drew from trade association reports, customs records of edge computing hardware imports, and hospital procurement databases for pharmaceutical traceability investments. Bottom-up deployment sizing and top-down market sizing triangulated segment-level estimates.
Variance decomposition across technology deployment modes, application focus areas, and end-user verticals structured the analytical framework over the projection horizon. Modeled dimensions included cloud-hybrid-on-premise configurations, supply chain optimization versus demand forecasting application splits, and consumer goods versus pharmaceutical manufacturer adoption patterns. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated IoT shelf sensor deployment trajectories and EU AI Act enforcement timeline assumptions.
Decision-makers should treat outputs as directional under sustained cloud migration preference and regulatory compliance deadline adherence; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding data engineering talent availability and hyperscaler infrastructure capacity expansion. Revision becomes warranted when FDA traceability mandate enforcement intensity or EU AI Act audit protocol specificity crosses thresholds that fundamentally reshape procurement evaluation criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Messaging Platform Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Morocco ICT Market
Digital Solutions
India ICT Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Data As a Service (Daas) Market