
 APAC Green Data Center Market | 2026-2036
APAC Green Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Green Data Center Market Outlook
Capital-intensity divergence between hyperscale operators and regional colocation providers is bifurcating the competitive landscape. Equinix Inc. sustains premium positioning through interconnection density across Tokyo, Sydney, and Singapore nodes. NTT DATA Group Corp. anchors its expansion with liquid-cooled facilities in Osaka and Bangkok. AirTrunk Operating Pty Ltd. dominates the Australian market with renewable-powered campuses in Melbourne and Sydney.
A green data center integrates energy-efficient infrastructure, renewable power procurement, and advanced cooling architectures to minimize carbon intensity per compute unit while maintaining service availability above 99.99%. Facilities typically deploy power usage effectiveness ratios below 1.3 through liquid cooling loops, on-site solar or wind generation, and AI-optimized workload orchestration. Hyperscale data centers capture the dominant share of new capacity investment across the region as cloud demand from IT services and financial services end users intensifies. Edge data centers represent the fastest-growing deployment model, driven by latency requirements for telecommunications and healthcare applications in secondary cities.
China's MIIT enforces national data center efficiency standards that mandate power usage effectiveness thresholds, while Singapore's Infocomm Media Development Authority restricts new facility approvals to greenfield projects with carbon-neutral operations. Australia's Clean Energy Regulator issues renewable energy certificates that offset facility power draws. Stakeholders must monitor evolving cooling technology roadmaps and cross-border data sovereignty rules as capacity planning decisions lock in decade-long infrastructure commitments.
Market Dynamics
China's MIIT power usage effectiveness mandates and Singapore's carbon-neutral approval restrictions are compressing deployment timelines while concentrating capital flows toward liquid-cooled facilities with on-site renewable generation.
Growth Catalysts
- Cloud service provider expansion:Southeast Asian hyperscale operators are procuring dedicated renewable energy supply contracts to meet latency requirements for financial services and telecommunications workloads.
- India's BIS energy efficiency mandates:Retrofit obligations for existing facilities are accelerating cooling system replacements and on-site solar installations across Mumbai and Bangalore clusters.
- Liquid immersion cooling:Direct-to-chip thermal management architectures are enabling higher rack densities in Singapore's land-constrained zones without expanding facility footprints.
Market Restraints
- Land scarcity premium:Singapore's Infocomm Media Development Authority restrictions on new approvals have compressed available development sites into a single competitive bidding pool.
- Copper and rare earth input volatility:Power distribution and permanent magnet supply chains for on-site wind generation face concentrated sourcing from Chinese processing facilities.
- Grid interconnection queues:Australia's Clean Energy Regulator certificate issuance timelines lag behind facility commissioning schedules in Victoria and New South Wales renewable corridors.
Strategic Opportunities
- Indonesia's secondary city edge deployment:Latency requirements for healthcare imaging and industrial IoT in Surabaya and Bandung remain underserved by existing Jakarta-centric capacity.
- Japan's METI green innovation fund:Subsidies for hydrogen fuel cell backup systems create first-mover advantages for facilities integrating fuel cells into hybrid microgrids.
- AI-optimized workload orchestration:Convergence of predictive cooling algorithms with renewable generation forecasting enables dynamic compute scheduling aligned with solar and wind availability windows.
Industry Challenges
- Liquid cooling technician scarcity:Specialized plumbing and dielectric fluid management skills outpace vocational training program output across Australian and Southeast Asian labor markets.
- Legacy facility electrical retrofit complexity:Existing transformer and switchgear configurations in pre-2015 Indian and Chinese buildings require complete replacement to support higher-density racks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Green Data Center Market |
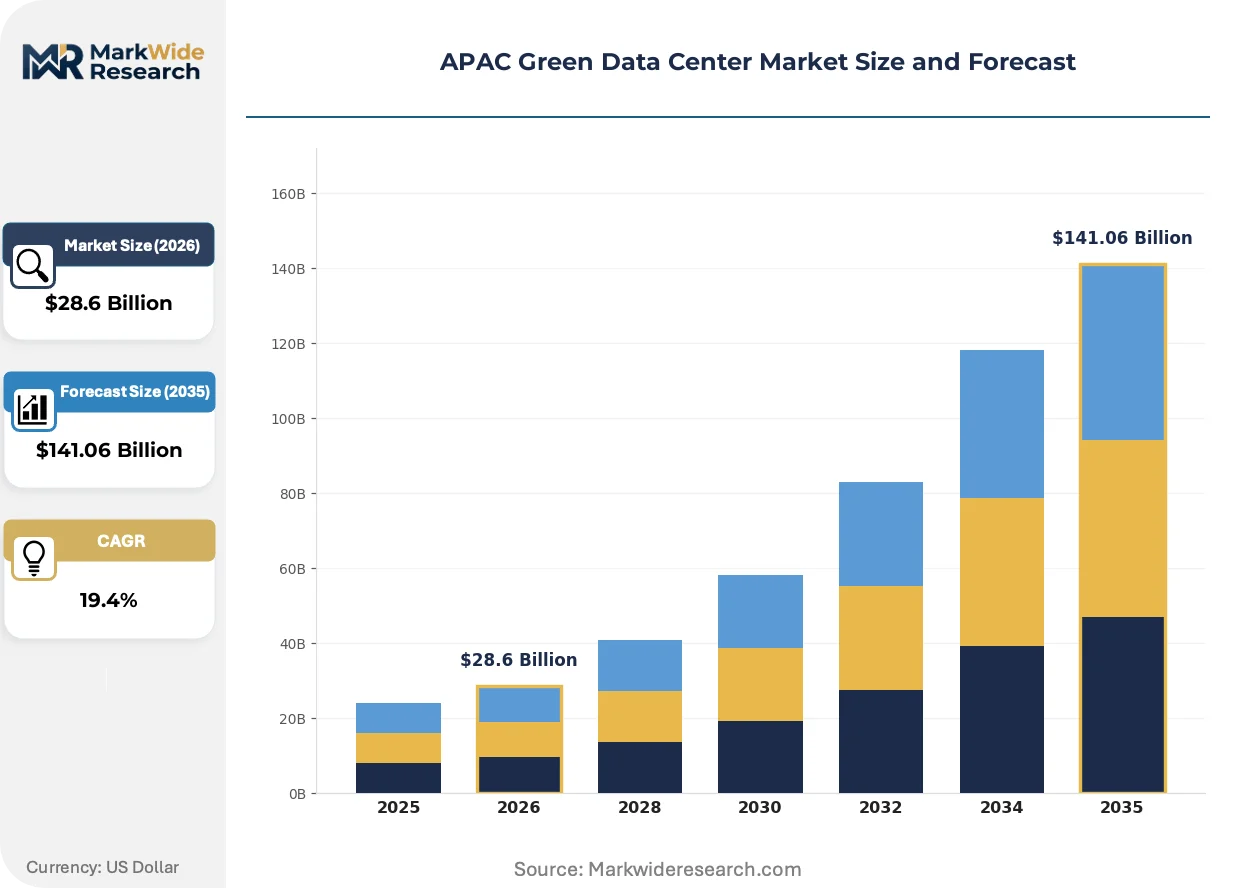
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $141.06 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Traditional Data Centers, Edge Data Centers, Hyperscale Data Centers Technology: AI Optimized, Renewable Energy Sources, Liquid Cooling, Smart Grid End User: IT Services, Telecommunications, Healthcare, Financial Services Deployment Model: On-Premises, Hybrid, Colocation, Cloud-Based |
| Companies Covered | Equinix Inc., Digital Realty Trust Inc., NTT DATA Group Corp., China Telecom Corp., Schneider Electric SE, Keppel DC REIT, AirTrunk Operating Pty Ltd., Alibaba Cloud Computing Co., Microsoft Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Green Data Center Market Strategic Shifts
Cooling architecture miniaturization and renewable procurement standardization are compressing facility design cycles while fragmenting vendor specialization across thermal management, power electronics, and energy trading platforms.
Direct liquid cooling is miniaturizing heat exchange infrastructure from room-scale CRAH units to server-level cold plates and immersion tanks. Cloud operators in Singapore and Sydney are deploying these systems at rack densities exceeding 50 kilowatts per cabinet. This density compression is miniaturizing the physical footprint required per petabyte of storage, enabling facility expansion within existing building envelopes.
Singapore's Infocomm Media Development Authority carbon-neutral mandate for new approvals is forcing renewable procurement integration into project financing structures. Developers must demonstrate power purchase agreements or on-site generation equivalent to 100 percent of forecasted load before groundbreaking. Australian facilities are responding through bundled solar-plus-storage microgrids that satisfy both the Singapore precedent and domestic Clean Energy Regulator certificate requirements.
Workload scheduling is migrating from static colocation contracts to dynamic capacity reservations aligned with renewable generation availability. Financial services buyers in Tokyo and Hong Kong are procuring compute credits priced by carbon intensity rather than flat per-kilowatt-hour rates. This preference shift is most visible in Singapore's limited land zone where renewable supply constraints create hourly price volatility that buyers now arbitrage through algorithmic placement decisions.
APAC Green Data Center Market Segmentation
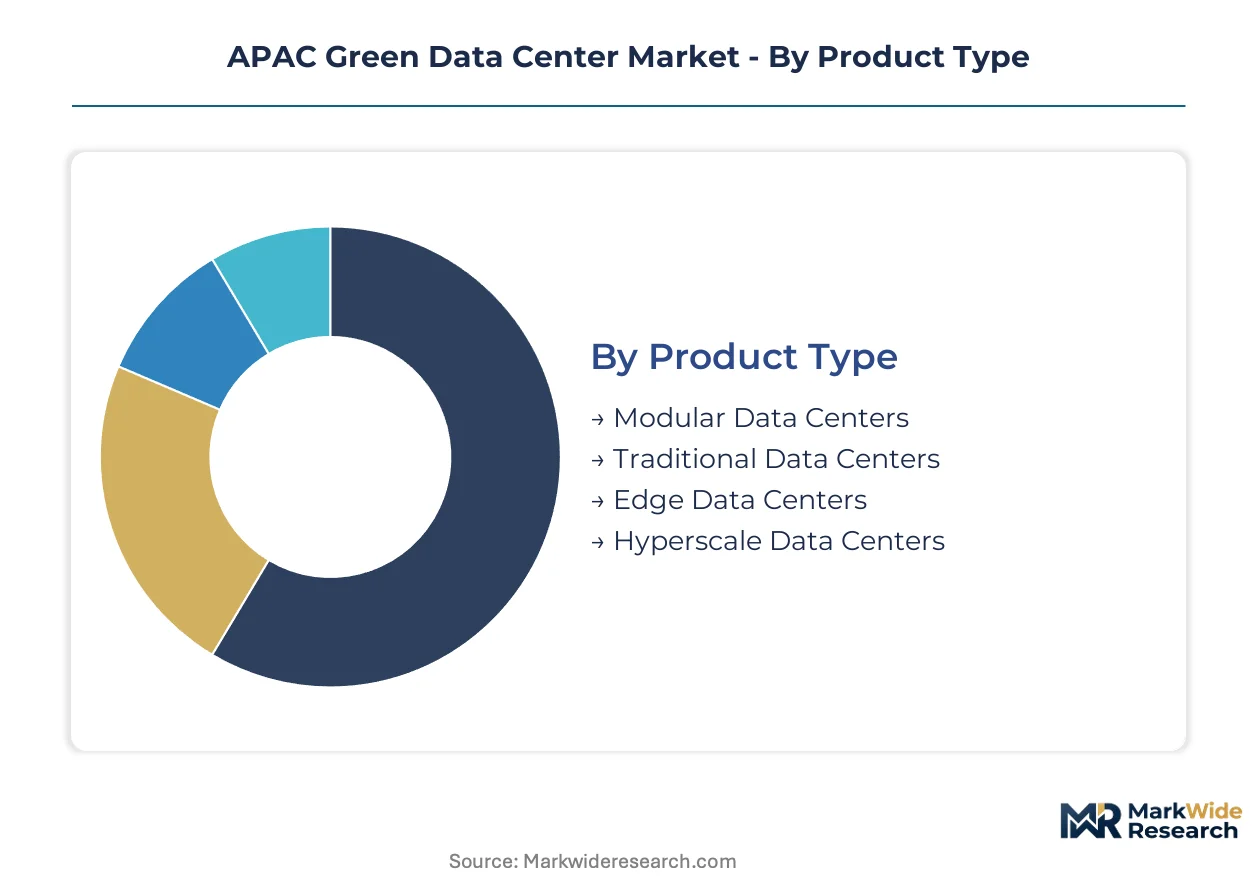
Segmentation reveals how capital allocation and regulatory pressure fragment across facility architectures, cooling technologies, and procurement models. Channel dynamics determine which configurations reach hyperscale operators versus regional colocation tenants.
Product Type:
Channel flow splits between direct hyperscale procurement and multi-tenant colocation intermediation, with facility scale determining financing structure and equipment vendor relationships.
- Hyperscale Data Centers:Single-tenant facilities exceeding 50 megawatts deploy customized liquid cooling loops and dedicated renewable power purchase agreements. Cloud service providers in Singapore and Sydney concentrate demand here, driven by latency requirements for financial services workloads and MIIT efficiency mandates in China.
- Edge Data Centers:Distributed sub-10 megawatt facilities enable sub-10 millisecond response times for industrial IoT and healthcare imaging. Secondary cities across Indonesia and Thailand absorb this capacity fastest as telecommunications operators bypass congested Jakarta-Singapore trunk routes.
- Modular Data Centers:Prefabricated containerized units accelerate deployment in land-constrained zones.
- Traditional Data Centers:Legacy raised-floor facilities dominate retrofit obligations under India's BIS mandates.
By volume, Hyperscale Data Centers lead. By growth pace, Edge Data Centers are expanding most quickly.
Technology:
Cost tiers separate proven mechanical systems from emerging thermal architectures, with premium pricing attached to density-enabled real estate savings.
- Liquid Cooling:Direct-to-chip and immersion systems achieve power usage effectiveness below 1.15 while supporting rack densities above 50 kilowatts. Singapore's land constraints and Australia's renewable corridors concentrate adoption where floor space carries premium valuations.
- AI Optimized:Predictive workload orchestration aligns compute scheduling with solar and wind generation windows. Financial services buyers in Tokyo and Hong Kong procure carbon-intensity-priced credits through algorithmic placement decisions.
- Renewable Energy Sources:On-site solar and wind microgrids satisfy Singapore's carbon-neutral approval requirements.
- Smart Grid:Bidirectional power management enables frequency response revenue streams in Australian facilities.
By installed base, Liquid Cooling leads. By adoption velocity, AI Optimized is climbing the fastest.
End User:
Application requirements dictate resilience tiers, with healthcare and financial services mandating redundant cooling architectures that telecommunications and IT services can relax.
- Financial Services:Latency-sensitive trading infrastructure and regulatory data residency requirements drive procurement of dedicated capacity in Tokyo, Hong Kong, and Singapore. BIS efficiency mandates and MAS operational resilience rules compress vendor selection to liquid-cooled facilities with renewable procurement documentation.
- Telecommunications:5G core network functions and edge computing nodes distribute across secondary Indonesian and Thai cities. Surabaya and Bandung clusters absorb capacity as operators deploy radio access network virtualization closer to subscribers.
- IT Services:Cloud brokerage and managed hosting consolidate through hybrid deployment models.
- Healthcare:Medical imaging and electronic health record systems demand specialized compliance certifications.
By current spend, Financial Services leads. By expansion rate, Telecommunications is gaining share fastest.
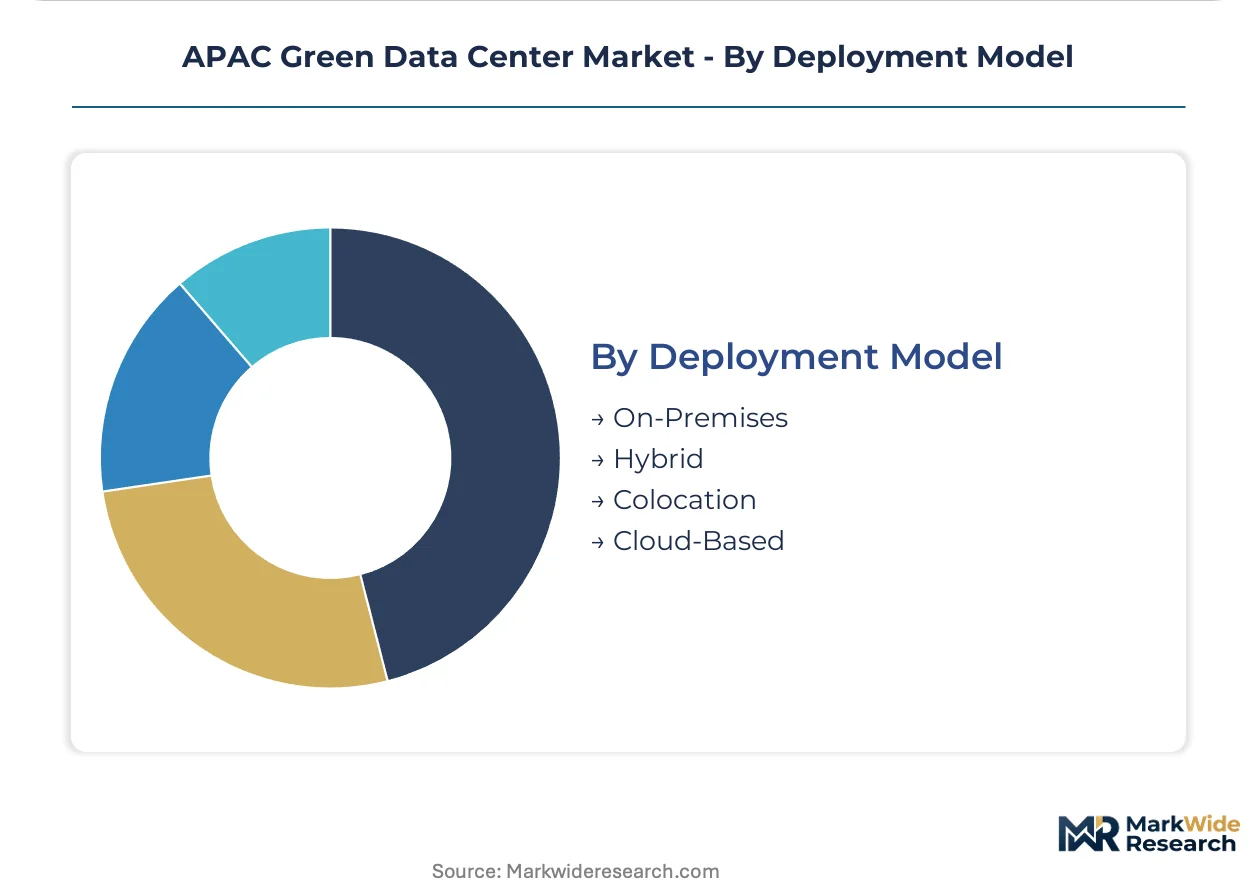
Deployment Model:
Customer type separates enterprises retaining capital expenditure control from those outsourcing facility operations to specialist operators.
- Colocation:Multi-tenant facilities transfer power and cooling infrastructure risk to specialist operators while preserving customer control over server deployment. Equinix and AirTrunk dominate channel flow in Australia and Singapore through interconnection density and renewable procurement integration.
- Cloud-Based:Hyperscale operators absorb capacity risk through reserved instance contracts and spot pricing mechanisms. Southeast Asian cloud service providers expand through dedicated renewable supply contracts that satisfy Singapore's carbon-neutral approval thresholds.
- On-Premises:Enterprise captive facilities persist in regulated sectors with data sovereignty constraints.
- Hybrid:Split workloads across owned and outsourced infrastructure based on sensitivity classification.
By contract volume, Colocation leads. By growth trajectory, Cloud-Based shows the steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the region. Singapore and Australia prioritize carbon-neutral procurement and renewable microgrids, while India and China focus on retrofitting legacy infrastructure under efficiency mandates. Southeast Asian markets emphasize edge deployment for latency-sensitive applications.
Singapore
Land scarcity drives hyperscale operators toward liquid-cooled, high-density rack configurations. The Infocomm Media Development Authority restricts new facility approvals to carbon-neutral projects with documented renewable power purchase agreements. Data center clusters concentrate in the Jurong and Tanjong Kling industrial zones where developers compete for limited development sites through competitive bidding.
Australia
Renewable energy corridors in Victoria and New South Wales attract hyperscale investment seeking solar and wind microgrid integration. The Clean Energy Regulator issues renewable energy certificates that offset facility power draws, though issuance timelines lag commissioning schedules. Melbourne and Sydney campuses dominate capacity expansion as operators target financial services and cloud brokerage demand.
China
MIIT power usage effectiveness mandates compress deployment timelines while accelerating cooling system replacements in pre-2015 facilities. The dual carbon goals framework drives retrofit obligations across Beijing-Tianjin-Hebei and Yangtze River Delta clusters. Hyperscale operators in Shanghai and Shenzhen procure dedicated renewable supply contracts to satisfy efficiency thresholds.
India
BIS energy efficiency mandates trigger retrofit waves across Mumbai and Bangalore data center clusters. Existing facilities replace transformer and switchgear configurations to support higher-density racks. On-site solar installations accelerate as operators seek compliance pathways for legacy raised-floor infrastructure.
Indonesia
Secondary city edge deployment lags Jakarta-centric capacity despite latency requirements for healthcare imaging and industrial IoT in Surabaya and Bandung. Telecommunications operators bypass congested trunk routes through distributed radio access network virtualization. This geographic gap creates deployment opportunities for sub-10 megawatt facilities.
APAC Green Data Center Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier. Hyperscale cloud operators and global colocation platforms control capital-intensive facility development, while regional specialists dominate interconnection density and renewable procurement integration. Three archetypes define competitive positioning: integrated infrastructure platforms with multi-node networks, renewable-powered campus developers, and cloud-native operators with captive supply chains. Capacity expansion and renewable power purchase agreement procurement constitute the dominant competitive moves.
Within the integrated platform tier, Equinix Inc. and Digital Realty Trust Inc. exemplify interconnection-first positioning across Tokyo, Sydney, and Singapore nodes. NTT DATA Group Corp. anchors the liquid-cooled facility archetype through Osaka and Bangkok deployments. AirTrunk Operating Pty Ltd. occupies the renewable-powered campus position within Australian markets. These three companies represent distinct strategic vectors: density-driven interconnection, thermal architecture specialization, and renewable energy integration.
| Leading Market Players |
|---|
| Equinix Inc. |
| Digital Realty Trust Inc. |
| NTT DATA Group Corp. |
| China Telecom Corp. |
| Schneider Electric SE |
| Keppel DC REIT |
| AirTrunk Operating Pty Ltd. |
| Alibaba Cloud Computing Co. |
| Microsoft Corp. |
| Others |
Value Chain & Pricing Dynamics
Long-term renewable power purchase agreements lock in both supply access and price visibility for hyperscale operators across Singapore and Sydney, insulating facility economics from hourly grid volatility while exposing developers to interconnection queue risk in Australian renewable corridors.
Pricing Analysis
Service and maintenance contracts spanning liquid cooling infrastructure drive lifetime value capture for specialist operators. Three-tier pricing structure across premium interconnection, standard colocation, and economy remote-hands tiers separates Equinix's cross-connect density from AirTrunk's renewable-powered campuses. Cost compression in standard colocation tiers intensifies because copper distribution and rare earth magnet supply chains face concentrated Chinese processing exposure. Financial services buyers in Tokyo and Hong Kong exhibit lowest price sensitivity, prioritizing latency and carbon-intensity documentation over per-kilowatt-hour rates.
Supply Chain Analysis
Port congestion along Shanghai-Singapore and Shenzhen-Sydney trade lanes elevates inbound logistics costs for precision cooling equipment and power distribution hardware. Manufacturing concentrates in China, South Korea, and Japan for advanced cooling systems, while Australia and Indonesia supply bauxite and nickel for thermal management alloys. Supply chains draw from Chinese rare earth processing facilities for permanent magnets in on-site wind generation, creating single-source vulnerability. Distribution runs through specialist data center contractors and EPC firms with liquid cooling certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hyperscale cloud operators with multi-hundred-megawatt procurement pipelines, fragmenting pricing leverage for regional colocation providers locked into fixed-rate contracts.
For Market Incumbents: Compound interconnection density advantages through Tokyo and Singapore node expansion, defending against cloud-native operators with captive renewable supply chains. Prioritize liquid cooling technician certification programs to offset labor scarcity in Australian and Southeast Asian markets. Secure long-term offtake agreements with Victoria and New South Wales solar developers before interconnection queues lengthen.
For New Entrants and Emerging Players: Differentiate on hydrogen fuel cell backup integration, targeting Japan's METI green innovation fund subsidies for first-mover positioning in Osaka hybrid microgrids. Surabaya and Bandung edge deployments remain the most penetrable white space, with sub-10 millisecond latency requirements for healthcare imaging currently underserved by Jakarta-centric capacity. Partner with Indonesian telecommunications operators for radio access network virtualization contracts.
For Investors and Strategic Acquirers: Capital is best deployed toward renewable-powered campus developers with documented Clean Energy Regulator certificate pipelines and liquid-cooled facility operational track records. Long-term viability hinges on regulatory alignment with Singapore's carbon-neutral approval mandates and China's MIIT efficiency thresholds. Watch for BIS mandate enforcement intensity in Mumbai and Bangalore as the signal for Indian retrofit market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Deployment | Enables rack densities above 50 kilowatts in Singapore's land-constrained Jurong zone. |
| Renewable Power Purchase Agreement | Satisfies IMDA carbon-neutral thresholds for new facility approvals. |
| Hydrogen Fuel Cell Integration | Captures METI green innovation fund subsidies for Tokyo and Osaka microgrids. |
| Edge Facility Expansion | Addresses latency requirements for Surabaya healthcare imaging and industrial IoT. |
| Technician Training Program | Offsets liquid cooling specialist scarcity across Australian and Southeast Asian labor markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of MIIT efficiency filings, IMDA approval databases, and Clean Energy Regulator certificate registries. Primary interviews engaged data center development executives, renewable procurement specialists, and liquid cooling system engineers across Singapore, Sydney, and Tokyo. Secondary sources encompassed hyperscaler capex disclosures, BIS mandate documentation, and EPC contractor project pipelines. Bottom-up facility-level capacity tracking triangulates against top-down regional demand modeling.
Segmentation dimensions modeled span facility type, cooling technology architecture, end-use industry vertical, and deployment model across the analysis window. CAGRs derive from facility commissioning schedules, renewable procurement contract tenors, and retrofit obligation timelines under India's BIS and China's MIIT frameworks. Inputs include power usage effectiveness trajectories, land availability constraints in Singapore's Tanjong Kling zone, and interconnection queue lengths in Victorian renewable corridors.
Material uncertainties — regulatory enforcement intensity shifts, rare earth supply disruptions, and grid interconnection delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding MIIT mandate compliance rates and IMDA approval throughput. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Mini Data Center Market