
 Global Workforce Productivity Systems Market | 2026-2036
Global Workforce Productivity Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Workforce Productivity Systems Market Foresight
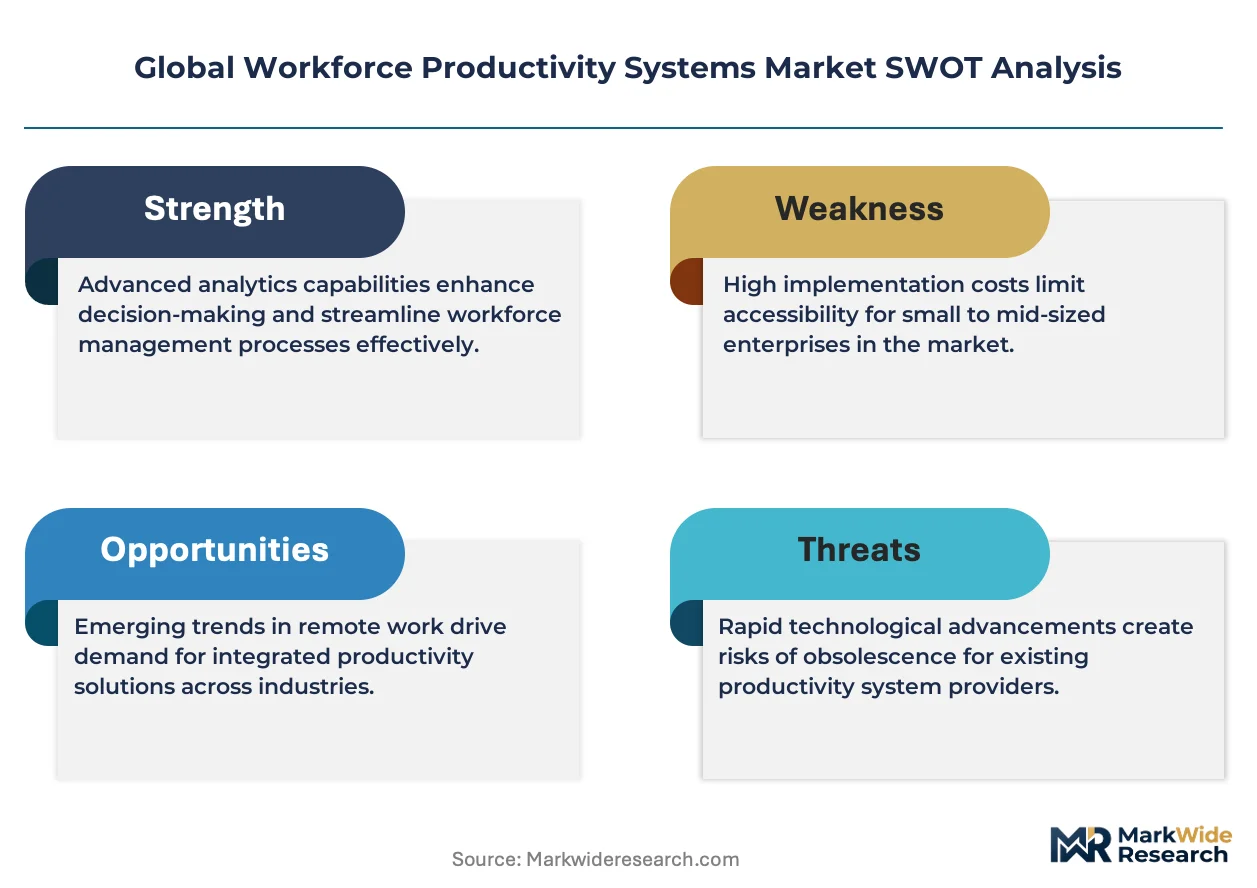
Subscription-based financing and asset-light SaaS leasing is reconfiguring competitive entry barriers for mid-sized vendors. UKG leverages its unified HCM-to-workforce platform to sustain pricing power across North American enterprise accounts. Workday anchors its position through native AI embedded in financial and HR planning modules. SAP competes by extending its S/4HANA ecosystem into workforce analytics, creating captive demand among existing ERP customers.
Workforce productivity systems encompass software platforms that orchestrate task allocation, time capture, performance measurement, and cross-functional collaboration through configurable workflow engines and real-time data pipelines. These systems primarily serve to reduce administrative overhead, enforce labor compliance, and surface operational bottlenecks across distributed work environments. Cloud-based deployment now leads in new bookings as hybrid work policies permanently altered infrastructure requirements, while integration-level demand tilts toward HRMS and payroll system coupling as buyers seek to consolidate vendor relationships. Collaboration tools and performance monitoring represent the fastest-expanding product categories as synchronous and asynchronous work models require new visibility frameworks.
The US Department of Labor enforces Fair Labor Standards Act record-keeping mandates that directly shape time-tracking feature requirements, while the EU AI Act imposes algorithmic transparency obligations on automated performance monitoring systems sold into European accounts. India's Digital Personal Data Protection Act introduces consent-layer complexity for employee behavioral analytics deployed by multinational corporations. Stakeholders must monitor how divergent privacy and labor compliance regimes fragment product roadmaps and inflate localization costs.
Market Dynamics
Cloud-to-edge workload distribution is fragmenting vendor architectures as enterprises demand sub-100ms latency for real-time workforce analytics while maintaining centralized compliance repositories.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European employers must deploy auditable performance monitoring systems, forcing upgrades from legacy time-tracking tools to integrated compliance platforms.
- India's Digital Personal Data Protection Act consent frameworks:Multinational corporations operating Indian back-office centers must reconfigure employee behavioral analytics with explicit opt-in layers, creating demand for privacy-embedded workforce suites.
- Hybrid work infrastructure permanence:Distributed team coordination requirements have shifted from temporary pandemic response to structural operating models, sustaining investment in asynchronous collaboration tooling.
Market Restraints
- API integration tax:Payroll system coupling with HRMS platforms requires expensive custom middleware development, inflating total cost of ownership for mid-market buyers.
- Cloud concentration risk:Three hyperscalers control over 70% of workforce productivity hosting infrastructure, creating single-point-of-failure exposure for enterprise continuity planning.
- Biometric data litigation exposure:Illinois Biometric Information Privacy Act class-action settlements have exceeded $500 million, chilling facial recognition time-clock deployments.
Strategic Opportunities
- German Works Council co-determination requirements:Employee consultation mandates for workplace monitoring create demand for transparency-first platforms that embed worker representatives in system configuration workflows.
- AI-augmented capacity planning convergence:Machine learning demand forecasting is merging with shift scheduling, opening white space for vendors that unify operational and workforce planning.
- Outcome-based pricing experimentation:Some vendors now tie subscription fees to measured productivity gains rather than seat counts, disrupting traditional SaaS monetization.
Industry Challenges
- Legacy mainframe payroll coupling:Decades-old COBOL-based systems in financial services resist REST API connectivity, forcing expensive parallel infrastructure during migration.
- Cross-border data residency fragmentation:Conflicting localization requirements between EU GDPR, China's PIPL, and India's DPDP Act complicate single-tenant global deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Workforce Productivity Systems Market |
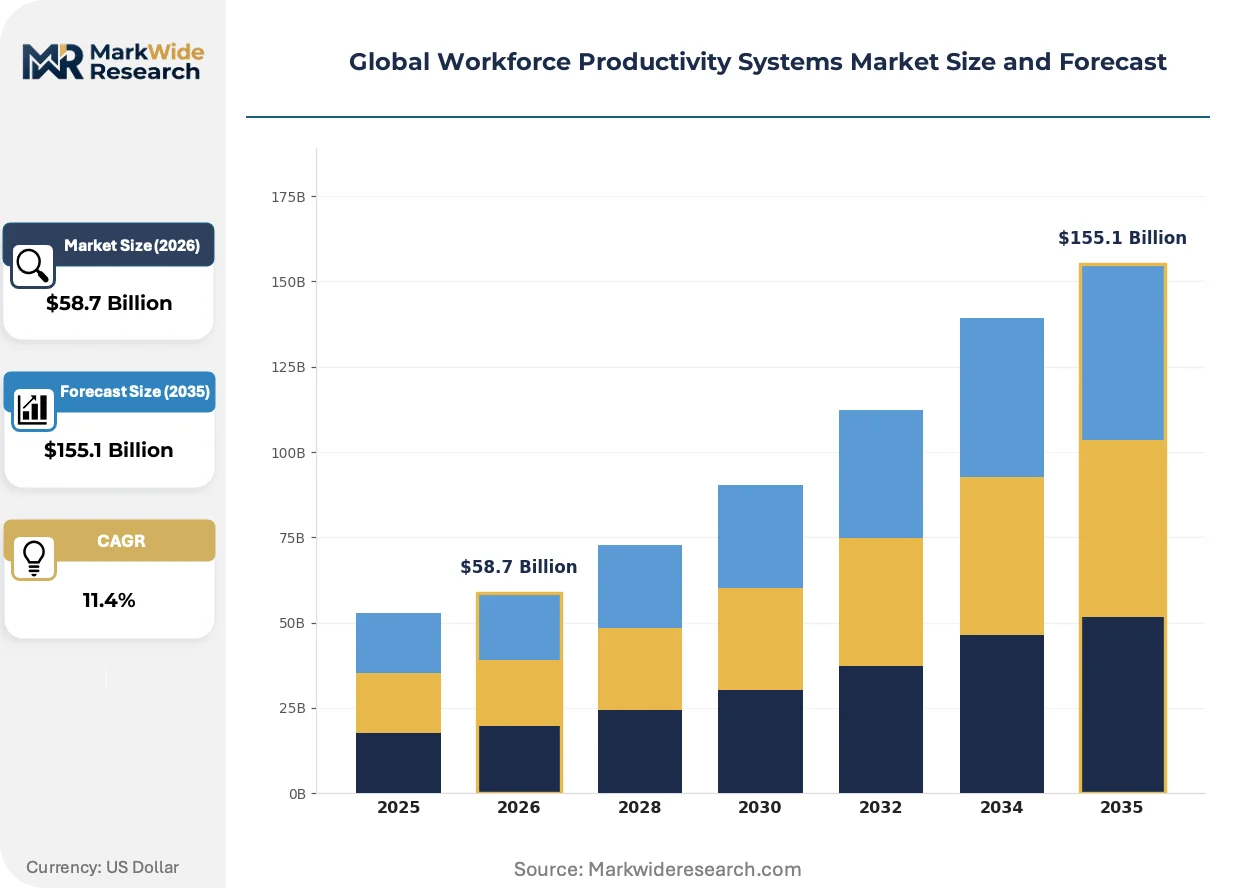
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $155.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Task Management, Time Tracking, Employee Scheduling, Performance Monitoring, Collaboration Tools, Reporting & Analytics Deployment: Cloud-based, On-premise, Hybrid, Mobile-based, Web-based End User Industry: Technology Providers, Professional Services, Educational Institutes, Government Agencies, Manufacturing Entities, Financial Institutions Integration Level: Standalone, ERP Integration, CRM Integration, HRMS Integration, Payroll System Integration |
| Companies Covered | UKG, Workday, ADP, Oracle, SAP, IBM, Ceridian, Infor, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Workforce Productivity Systems Market Shifts & Advancements
Generative AI is compressing the gap between workforce data collection and actionable insight generation, collapsing traditional business intelligence latency from weeks to minutes.
Natural language query interfaces for workforce analytics is hybridizing how managers interact with scheduling and performance systems. HR generalists without SQL training now surface labor cost variances through conversational prompts. This accessibility expansion is compressing the addressable market for specialized workforce analysts while expanding platform stickiness.
The EU AI Act's risk classification framework for employment-related algorithmic systems imposes documentation burdens on automated scheduling and performance scoring tools. Vendors must maintain technical files proving non-discrimination for high-risk deployments. German automotive manufacturers and French logistics operators are front-loading compliance investments ahead of enforcement deadlines.
Consolidated vendor relationships are displacing point-solution proliferation as procurement teams reduce supplier management overhead. Buyers now prioritize platforms with native payroll, benefits, and workforce analytics over best-of-breed integrations. This preference shift is most visible among United States healthcare systems and United Kingdom financial services firms with complex union bargaining agreements.
Global Workforce Productivity Systems Market Segmentation
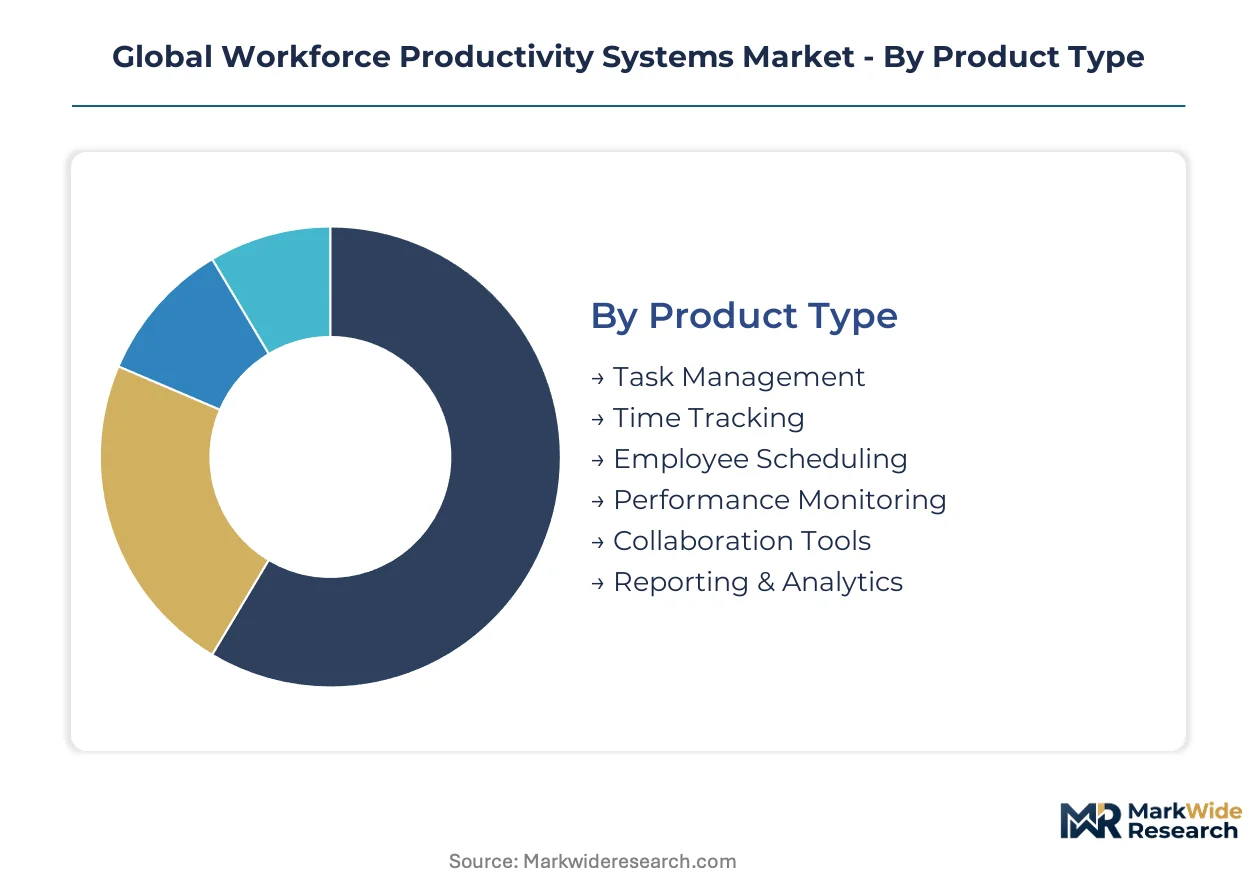
Workforce productivity systems fragment across multiple technical and commercial dimensions. Procurement patterns diverge sharply between enterprises seeking unified platforms and mid-market buyers prioritizing point-solution economics. Understanding these splits illuminates where vendor R&D investments concentrate and which integration pathways command pricing premiums.
Product Type:
Cost tier stratification across product categories reflects divergent technical complexity and compliance exposure. Premium modules embed AI-driven forecasting and predictive analytics, while entry tiers automate basic time capture and task routing.
- Task Management:Workflow orchestration engines allocate work items across distributed teams through configurable rule sets and priority scoring algorithms. Demand concentrates among professional services firms in Germany navigating co-determination consultation requirements for workload transparency.
- Time Tracking:Automated capture systems record labor hours through biometric authentication, mobile geofencing, or desktop activity monitoring. Financial institutions in the United States deploy these modules to satisfy Fair Labor Standards Act record-keeping mandates and operational risk documentation under Basel III frameworks.
- Employee Scheduling:Shift optimization platforms balance labor demand forecasts against worker availability constraints and union contract rules.
- Performance Monitoring:Behavioral analytics systems track productivity metrics and generate automated scoring for compensation and advancement decisions.
- Collaboration Tools:Synchronous and asynchronous communication platforms integrate messaging, video conferencing, and document co-editing within unified interfaces.
- Reporting & Analytics:Business intelligence layers transform raw workforce data into executive dashboards and regulatory compliance documentation.
Time Tracking holds installed capacity. Collaboration Tools is rotating up the share rankings.
Deployment:
Application context determines infrastructure choice, with latency requirements and data sovereignty rules fragmenting deployment patterns across customer profiles.
- Cloud-based:Multi-tenant SaaS architectures deliver workforce functionality through browser and mobile interfaces without local infrastructure. Technology providers in India leverage these deployments to serve multinational back-office operations while managing Digital Personal Data Protection Act consent-layer complexity through centralized configuration.
- On-premise:Self-managed installations run within customer data centers, preserving direct control over security patches and customization roadmaps. Government agencies in the United States mandate these deployments for classified or sensitive personnel data under federal information security standards.
- Hybrid:Split architectures process sensitive compliance data locally while routing analytics and collaboration workloads to cloud infrastructure.
- Mobile-based:Native applications optimized for smartphone and tablet interfaces serve field-based and frontline workforces.
- Web-based:Browser-delivered functionality without native installation requirements simplifies rollout across contractor and contingent worker populations.
Cloud-based deployments dominate new bookings. Hybrid architectures are climbing the fastest as edge analytics requirements mature.
End User Industry:
Customer type segmentation reveals how sector-specific labor regulations and union structures reshape feature prioritization and sales cycle complexity.
- Technology Providers:Software and IT services firms deploy workforce systems to manage globally distributed engineering teams and measure output against sprint-based delivery commitments. These buyers in the United States prioritize real-time capacity planning and integration with DevOps toolchain.
- Professional Services:Consulting, legal, and accounting firms track billable hours against client engagements and enforce utilization targets for partner-track professionals. German operations require transparency-first configurations accommodating Works Council consultation on monitoring scope.
- Educational Institutes:Universities and K-12 systems manage complex scheduling across academic calendars, unionized staff, and seasonal adjunct workforces.
- Government Agencies:Public sector employers navigate civil service classification systems and multi-layer approval hierarchies for workforce policy changes.
- Manufacturing Entities:Industrial operations coordinate shift-based production schedules with machine maintenance windows and safety certification requirements.
- Financial Institutions:Banks and insurers integrate workforce data with operational risk frameworks and trader surveillance systems.
Technology Providers hold installed capacity. Professional Services is rotating up the share rankings.
Integration Level:
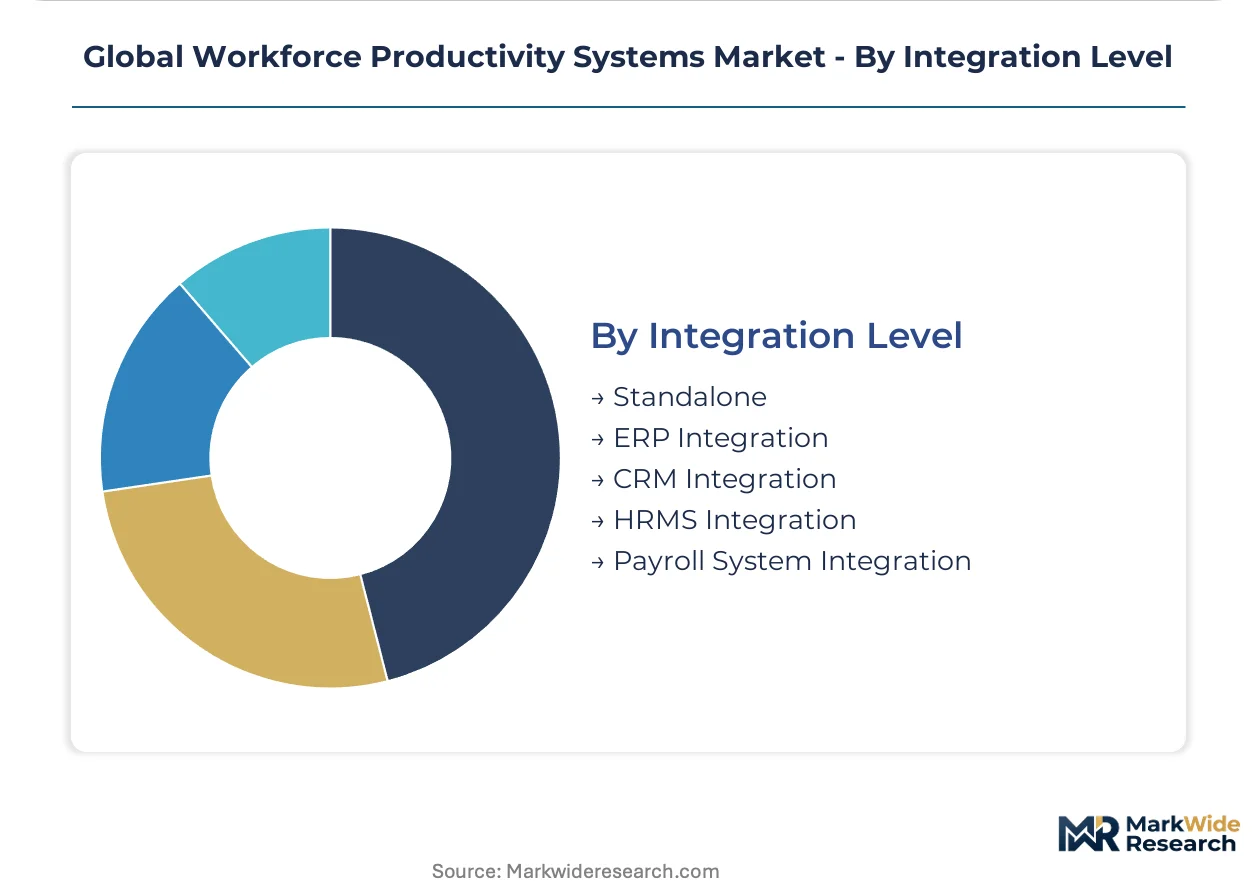
Supply concentration among ERP and HCM incumbents creates tiered purchasing patterns based on existing vendor relationships and middleware tolerance.
- Standalone:Self-contained platforms operate without external system dependencies, appealing to mid-market buyers avoiding complex procurement negotiations. Educational institutes in India favor these deployments for rapid implementation without IT infrastructure overhaul.
- ERP Integration:Native connectors synchronize workforce data with financial planning, procurement, and supply chain modules within unified enterprise suites. Manufacturing entities in Germany extend S/4HANA ecosystems into workforce analytics to maintain single-vendor accountability.
- CRM Integration:Sales force automation coupling links activity metrics to pipeline contribution and customer lifetime value calculations.
- HRMS Integration:Human capital management synchronization unifies recruitment, onboarding, and talent development workflows.
- Payroll System Integration:Direct coupling with compensation calculation engines eliminates manual re-entry and reduces reconciliation errors.
Standalone systems hold installed capacity. ERP Integration is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in workforce productivity software exports, while Germany and India represent net importers of cloud-based HCM platforms. Cross-border data flows concentrate licensing revenue in American hyperscaler jurisdictions.
United States
Financial institutions in New York and Chicago drive demand for Basel III-compliant operational risk documentation systems. The Department of Labor enforces Fair Labor Standards Act record-keeping mandates that shape time-tracking feature requirements. Silicon Valley technology providers prioritize real-time capacity planning tools integrated with DevOps toolchains.
Germany
Automotive manufacturers in Stuttgart and Wolfsburg require workforce analytics platforms that accommodate Works Council co-determination consultations. The EU AI Act imposes algorithmic transparency obligations on automated performance monitoring systems. Bavarian industrial clusters demand transparency-first configurations embedding worker representatives in system workflows.
India
Multinational back-office operations in Bangalore and Hyderabad create demand for privacy-embedded workforce suites managing consent-layer complexity. The Digital Personal Data Protection Act introduces explicit opt-in requirements for employee behavioral analytics. Technology providers leverage cloud-based deployments to serve global clients while maintaining centralized configuration control.
United Kingdom
Financial services firms in London with complex union bargaining agreements prioritize consolidated vendor relationships over best-of-breed integrations. The Information Commissioner's Office enforces GDPR-aligned accountability for automated decision-making in employment contexts. The City of London's trading floors integrate workforce data with trader surveillance and operational risk frameworks.
Japan
Manufacturing entities in the Chubu region around Nagoya coordinate shift-based production schedules with machine maintenance windows and safety certification requirements. METI guidelines encourage workforce digitalization while maintaining employment stability commitments. Osaka-based industrial conglomerates extend ERP ecosystems into workforce analytics to preserve single-vendor accountability.
Global Workforce Productivity Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in workflow engines and biometric authentication modules. The vendor landscape consolidates around three hyperscaler-dependent architectures, with mid-sized SaaS vendors occupying niche compliance verticals. Two strategic archetypes dominate: unified HCM-to-workforce suite providers and ERP-anchored analytics extenders. Competitive moves concentrate on API ecosystem expansion and outcome-based pricing experimentation.
Within the unified platform tier, UKG and Workday occupy positions representing North American enterprise-centric consolidation, while SAP exemplifies the ERP-anchored archetype extending S/4HANA ecosystems into workforce analytics. These three entities represent divergent strategic postures: subscription-based financing leverage, native AI embedding in planning modules, and captive demand cultivation among existing enterprise customers.
| Leading Market Players |
|---|
| UKG |
| Workday |
| ADP |
| Oracle |
| SAP |
| IBM |
| Ceridian |
| Infor |
| Microsoft |
| Others |
Supply & Pricing Matrix
Overcapacity in North American cloud infrastructure is compressing hosting margins and forcing hyperscalers to bundle workforce productivity modules at discounted rates, while simultaneously pressuring independent SaaS vendors to differentiate through compliance depth rather than price.
Pricing Analysis
Enterprise procurement teams anchor workforce productivity pricing through multi-year SaaS contracts with volume-scaled per-seat tiers. Three-tier pricing structure across premium AI-augmented forecasting, standard workflow automation, and economy time-capture levels reflects integration complexity and compliance certification depth. Pricing pressure stems from hyperscaler bundling strategies that subsidize workforce modules within broader cloud commitments. Mid-market buyers exhibit highest price sensitivity due to limited IT procurement leverage, while financial institutions accept premium tiers to satisfy Basel III operational risk documentation mandates.
Supply Chain Analysis
Export control regimes restricting AI chip flows to Chinese data centers are fragmenting global cloud infrastructure deployment patterns and accelerating regional capacity builds. Software development concentrates in the United States, India, and Germany, with Indian technology hubs serving multinational back-office demand under Digital Personal Data Protection Act constraints. Raw compute capacity, biometric authentication hardware, and specialized compliance middleware constitute critical input dependencies. Single-source vulnerability runs through three hyperscalers controlling dominant hosting infrastructure. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving regulated industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workforce productivity systems represent a service-attach opportunity where implementation consulting and ongoing compliance audit subscriptions expand faster than core platform licensing, creating recurring revenue depth that exceeds traditional software margins.
For Market Incumbents: Build switching-cost moats through deep HRMS and payroll system integration that embeds workflow data into compensation calculation engines. Incumbents should acquire specialized compliance module vendors to preempt regulatory fragmentation, and expand API ecosystem coverage to capture middleware revenue that independent integrators currently extract. Cloud hyperscaler bundling poses the primary substitution threat, requiring differentiation through sector-specific algorithmic transparency documentation that generic platforms cannot replicate. For New Entrants and Emerging Players: Build out white-space positions in German Works Council co-determination tooling and Indian DPDP Act consent-layer automation, where regulatory complexity exceeds incumbent platform adaptation speed. The most penetrable segment comprises mid-market professional services firms in Europe seeking transparency-first configurations without enterprise implementation timelines. A vertical-specific go-to-market angle targeting automotive manufacturers navigating EU AI Act employment algorithm documentation requirements offers fastest path to referenceable accounts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native workforce platforms as containerized deployment reduces infrastructure overhead, improving cash conversion metrics relative to legacy on-premise vendors. Long-term viability favors platforms with native AI forecasting capabilities and established hyperscaler partnership tiers rather than point-solution vendors facing integration tax pressures. Acquisition targets should demonstrate compliance localization depth across at least three regulatory jurisdictions. The signal to watch is EU AI Act enforcement action against non-compliant scheduling algorithms, which would accelerate replacement demand and validate premium pricing for auditable platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native coupling with SAP S/4HANA creates captive demand among German manufacturing ERP installed base. |
| Strategic Partnership | Hyperscaler alliances with AWS, Azure, or GCP reduce customer infrastructure procurement friction and accelerate deployment. |
| Acquisition of Specialist Firm | Biometric authentication vendors mitigate Illinois BIPA litigation exposure through proprietary non-facial recognition time-capture methods. |
| Product Launch | EU AI Act-compliant algorithmic transparency modules open addressable market among French logistics and German automotive employers. |
| Geographic Expansion | Localized India deployments addressing DPDP Act consent requirements capture multinational back-office center procurement budgets. |
Research Methodology
Initial hypotheses were tested against primary input from workforce technology procurement officers, HRIS implementation consultants, regulatory compliance leads, and cloud infrastructure architects, and refined through secondary validation against SEC 10-K filings, hyperscaler capex disclosures, EU regulatory impact assessments, and Indian parliamentary committee reports on data protection implementation. Bottom-up sizing of vendor bookings and top-down triangulation against enterprise software spending benchmarks ensured cross-verification of market estimates.
Demand-supply balance modeling across the projection horizon incorporated deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and policy enforcement timelines. Forecast inputs included EU AI Act implementation deadlines, DPDP Act consent framework operationalization, and Basel III operational risk documentation requirements for financial institutions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers into bundled workforce productivity offerings or rapid regulatory enforcement acceleration by EU or Indian authorities would shift outcomes beyond modeled ranges. Material shifts in cross-border data localization requirements or biometric privacy litigation exposure would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Telecom Site Management Software Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Legaltech Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global Network Monitoring Software Market
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
Artificial Intelligence (AI) in Marketing Market
Digital Solutions
Bangladesh ICT Market