
 Global Intellectual Property Management Software Market | 2026-2036
Global Intellectual Property Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intellectual Property Management Software Market Foresight
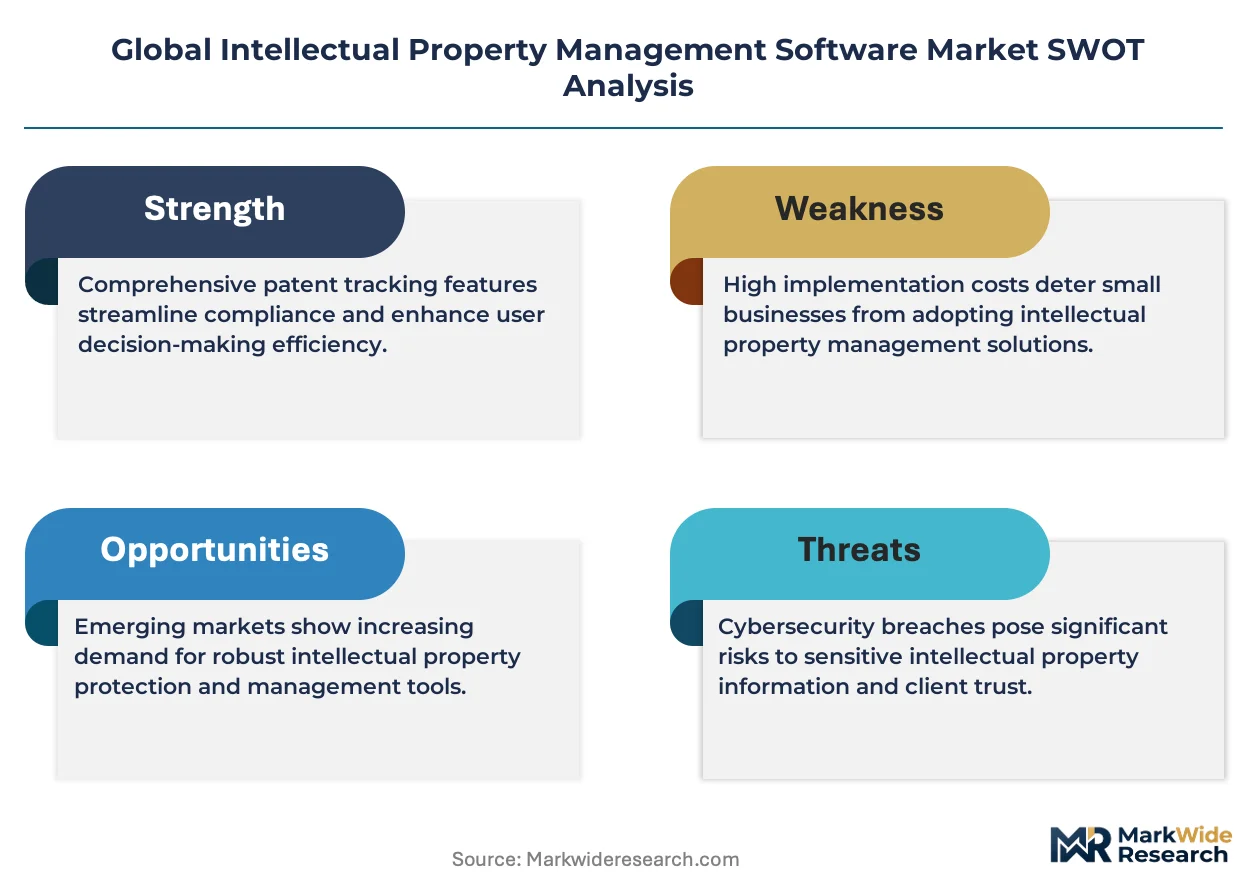
North American software vendors is restructuring enterprise IP workflows through cloud-native architectures. Clarivate PLC leverages deep patent data repositories to anchor its analytics platform across life sciences and technology sectors. Anaqua Inc. competes through integrated portfolio management tools that span prosecution through litigation. Questel sustains European market presence with specialized trademark and design search capabilities.
Intellectual property management software comprises modular platforms that automate patent lifecycle administration, trademark monitoring, and royalty compliance through structured databases, workflow engines, and API-connected analytics layers. These systems process bibliographic data, legal status events, and family relationships across 150-plus patent authorities to reduce administrative burden and mitigate infringement exposure. Cloud-based deployment leads solution architecture as corporate legal departments prioritize scalable subscription models over capital-intensive on-premise installations. Patent management and portfolio analytics command disproportionate margin pools due to specialized data feeds and machine-learning classification requirements. On-premise and hybrid configurations retain footholds in financial services and defense-adjacent sectors where data residency restrictions prevail.
The USPTO's electronic filing mandates and the EU's Unitary Patent System reshape platform requirements across transnational portfolios. FDA and EMA regulatory submissions increasingly require traceable IP documentation, tightening integration between R&D and legal software stacks. Stakeholders must evaluate vendor capabilities against evolving data localization rules in China and emerging ASEAN markets.
Market Dynamics
Cloud-native architectures are compressing deployment cycles and forcing incumbent vendors to re-platform legacy codebases, while the EU AI Act imposes algorithmic transparency mandates that reshape compliance module specifications across all major product tiers.
Growth Catalysts
- Pharmaceutical patent expansion:Life sciences firms filing in Brazil, India, and South Korea require localized docketing automation and multi-jurisdictional family tracking. This drives demand for API-connected prosecution workflows.
- USPTO electronic filing mandates:The transition to fully digital submission systems compels corporate legal departments to retire paper-based processes and adopt integrated document management layers.
- Machine learning classification:Automated patent categorization engines trained on international classification schemes reduce examiner backlog and accelerate prior art searches for technology sectors.
Market Restraints
- Data localization requirements:China's cybersecurity law and Russia's data sovereignty rules fragment cloud architectures, forcing vendors to maintain separate infrastructure instances and compliance certifications.
- Specialized talent scarcity:The intersection of patent law expertise and software engineering commands premium compensation, constraining vendor R&D expansion and implementation velocity.
- Legacy system entrenchment:Financial services and defense-adjacent sectors maintain on-premise installations due to classified information handling protocols, limiting addressable market for pure SaaS offerings.
Strategic Opportunities
- ASEAN regulatory harmonization:Vietnam, Indonesia, and Thailand are consolidating intellectual property offices, creating demand for unified portfolio management platforms across emerging innovation clusters.
- Standard-essential patent tracking:5G and Wi-Fi 7 licensing pools require automated royalty stack calculation tools, opening specialized modules for telecommunications and consumer electronics manufacturers.
- Blockchain-enabled provenance:Distributed ledger technology converging with IP registries offers tamper-evident filing timestamps and smart contract-based licensing execution for digital asset creators.
Industry Challenges
- Interoperability fragmentation:Proprietary data formats across national patent offices and private databases complicate unified search and analytics layer construction.
- Compliance timeline compression:The EU Unitary Patent System and Unified Patent Court operational deadlines force vendors to accelerate feature delivery while maintaining regulatory accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intellectual Property Management Software Market |
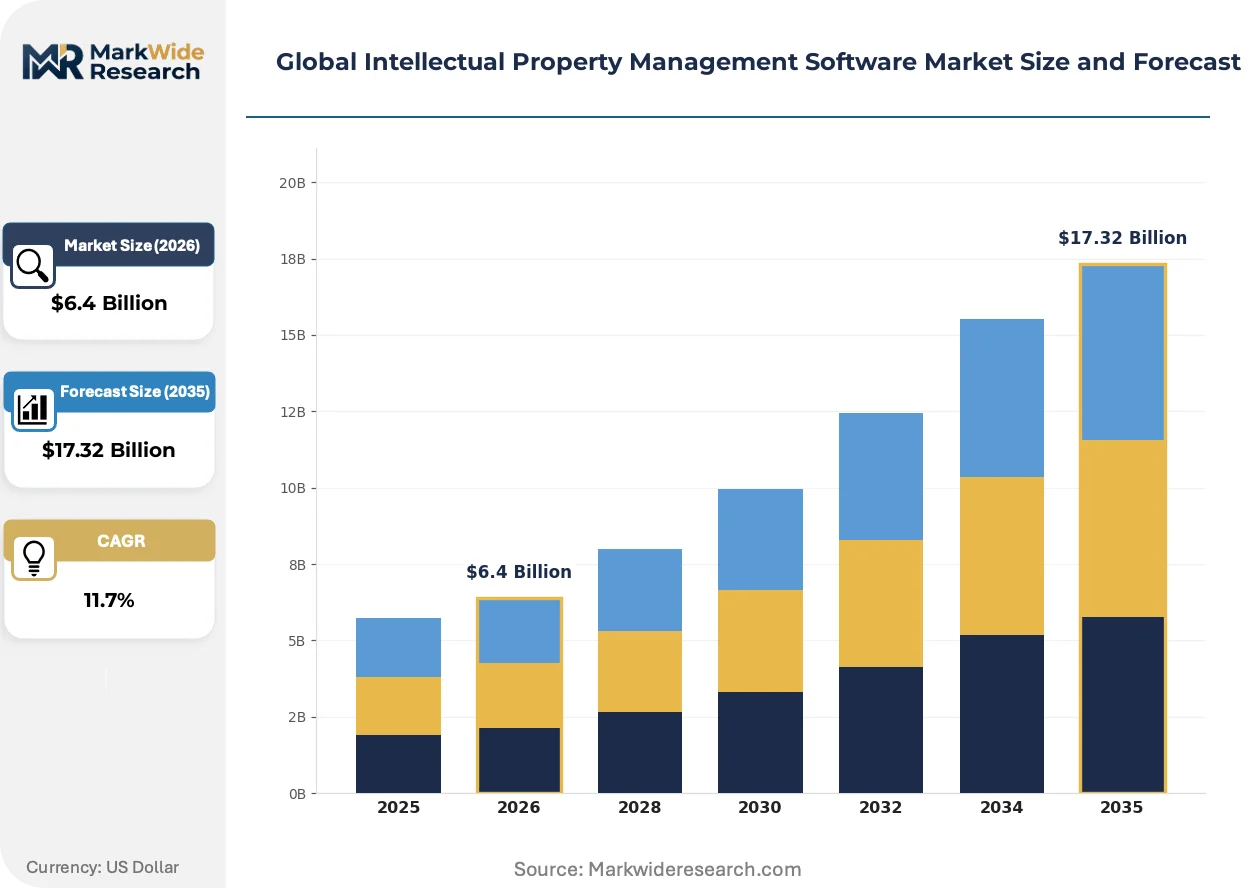
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Private Cloud Solution/Offering: Patent Management, Trademark Management, Copyright Management, Trade Secret Management, Portfolio Analytics, Case Management Application: Patent Filing, IP Valuation, License Management, IP Litigation Support, IP Renewal Tracking, Competitive Intelligence End User: Corporate Legal Departments, Law Firms, Research Institutions, Technology Transfer Offices, Startups |
| Companies Covered | Clarivate PLC, Anaqua Inc., Questel, LexisNexis, Thales, Innovation Asset Group Inc., Dennemeyer & Associates S.A., PatSnap, CPA Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intellectual Property Management Software Market Shifts & Advancements
Generative AI capabilities are penetrating prior art search and claim drafting assistance, compressing attorney hours per matter while raising bar association ethics scrutiny. Vendors must balance automation depth with professional liability frameworks.
Natural language processing engines trained on patent corpora are integrating semantic similarity scoring into examination support tools. The USPTO and EPO are piloting these systems for accelerated classification. This integration is compressing the traditional manual review bottleneck and forcing law firms to retrain associates on AI-augmented workflows.
The EU AI Act's high-risk system classification is extending to IP management platforms that automate legal decision support. Vendors serving European pharmaceutical and automotive clients must implement explainability layers and human-in-the-loop overrides. German and French regulators are conducting sector-specific audits, with compliance documentation becoming a procurement gate.
Corporate legal departments are consolidating vendor relationships and demanding outcome-based pricing tied to prosecution success rates and portfolio valuation metrics. This displaces traditional per-seat subscription models. United States-based technology and life sciences enterprises are leading this transition, with procurement teams requiring proof-of-value pilots before enterprise commitments.
Global Intellectual Property Management Software Market Segmentation
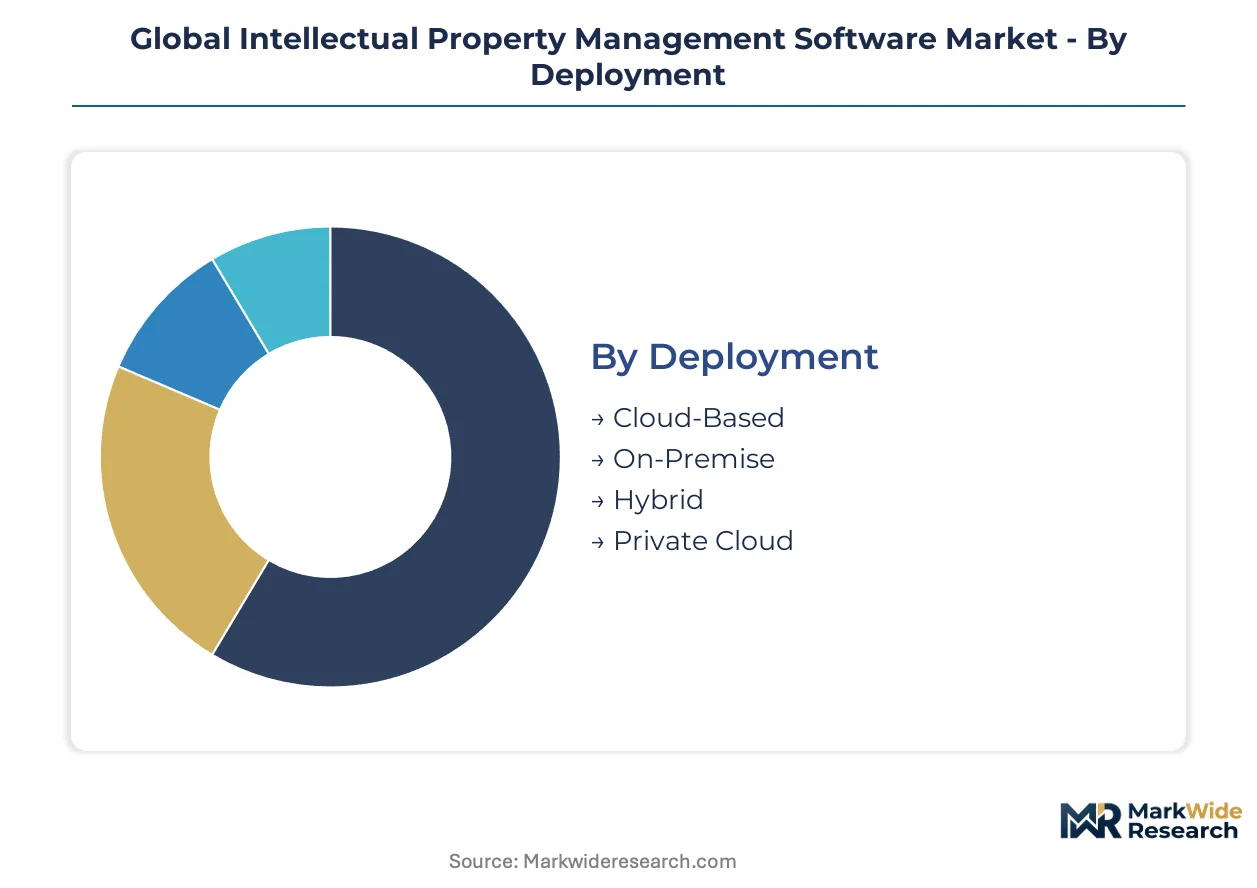
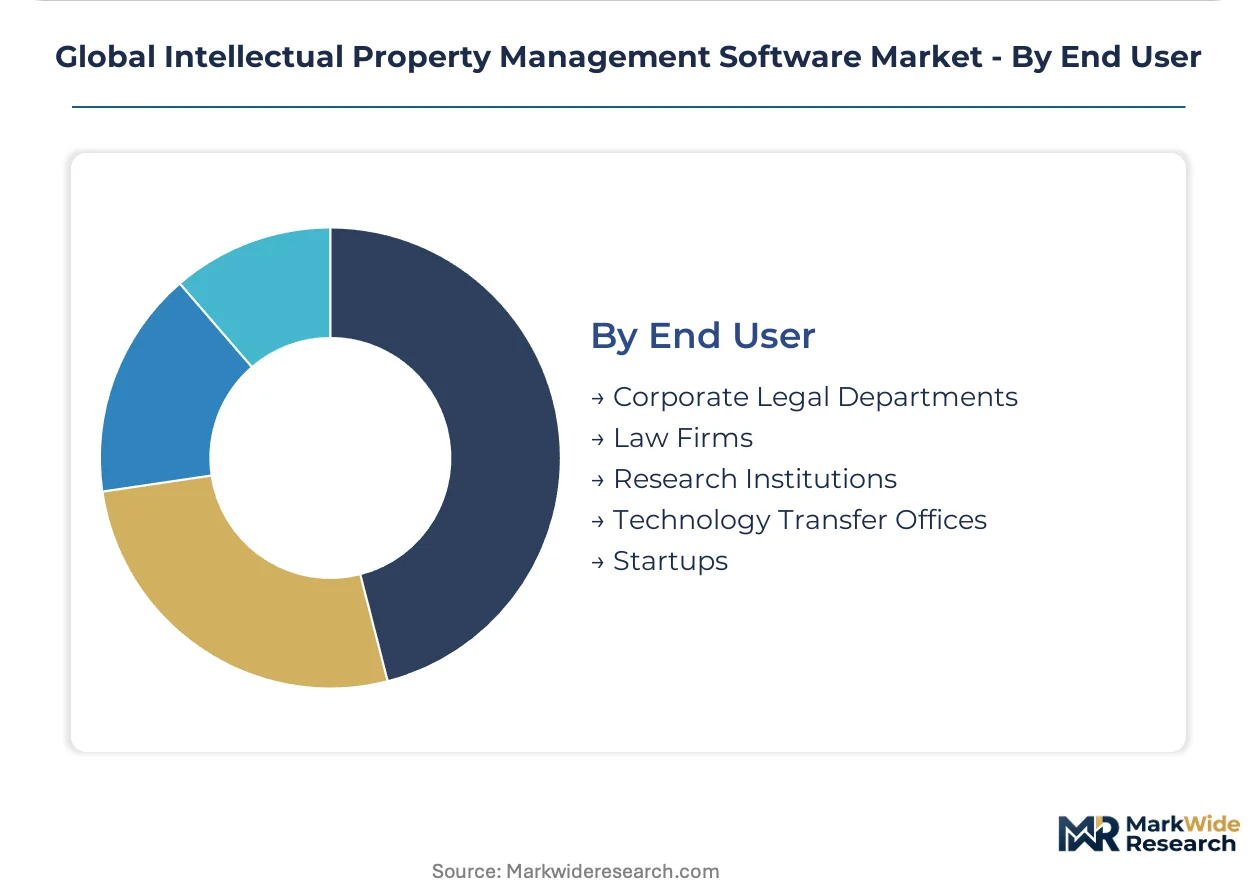
Intellectual property management software segments by deployment architecture, solution depth, functional application, and organizational user type. Each axis reveals distinct procurement patterns, margin structures, and compliance requirements that shape vendor product roadmaps and go-to-market strategies.
Deployment:
Cloud-native architectures dominate new procurement cycles as corporate legal departments prioritize elastic capacity and reduced infrastructure overhead.
- Cloud-Based:Multi-tenant SaaS platforms deliver automated scaling, continuous security patching, and API-first integration with patent office filing systems. Pharmaceutical companies in Germany and technology enterprises in the United States drive concentrated demand for subscription-based consumption models that convert capital expenditure to operational budgets.
- On-Premise:Single-tenant installations within client data centers enforce complete data sovereignty and air-gapped security protocols. Defense contractors and classified research facilities in the United States mandate these configurations to satisfy NIST 800-171 and ITAR requirements.
- Hybrid:Split architectures maintain sensitive prosecution data on-premise while pushing analytics workloads to public cloud infrastructure. Financial services firms in Switzerland and South Korea adopt this model to balance regulatory compartmentalization with machine-learning throughput.
- Private Cloud:Dedicated cloud instances within vendor-managed environments offer isolation without client-side infrastructure burden. Life sciences conglomerates operating across Brazil and India deploy these to satisfy data localization mandates while retaining managed service benefits.
Cloud-Based leads on scale; Hybrid leads on momentum.
Solution/Offering:
Functional modules align with distinct IP asset classes and lifecycle stages, each commanding differentiated pricing based on data source complexity and automation depth.
- Patent Management:End-to-end prosecution workflows spanning docketing, annuity payment, and family relationship tracking across 150-plus patent authorities. Biotechnology firms in South Korea and semiconductor manufacturers in Taiwan generate disproportionate demand for multi-jurisdictional deadline automation.
- Trademark Management:Watch services, opposition tracking, and renewal administration tied to national registry feeds. Consumer packaged goods companies in France and luxury brands in Italy sustain premium pricing for image recognition-based infringement detection.
- Copyright Management:Digital rights administration for creative content, software code, and media assets. Streaming platforms in the United States and publishing houses in the United Kingdom require automated takedown workflows and licensing marketplace integration.
- Trade Secret Management:Access control, audit trails, and employee departure protocols for proprietary technical know-how. Chemical manufacturers in Germany and battery producers in Japan deploy these modules to satisfy trade secret protection statutes.
- Portfolio Analytics:Valuation engines, competitive landscaping, and patent quality scoring using machine learning classification. Private equity firms conducting IP-backed lending in Singapore and corporate development teams in the United States drive adoption.
- Case Management:Litigation hold, evidence organization, and court deadline tracking for contested proceedings. Specialized IP boutiques in the United Kingdom and full-service firms in the United States integrate these with e-discovery platforms.
Patent Management captures the largest revenue pool; Portfolio Analytics climbs the fastest.
Application:
Use-case modules address specific workflow bottlenecks, with procurement decisions increasingly tied to measurable outcome metrics rather than feature checklists.
- Patent Filing:Structured document assembly, e-filing API connections, and formalities checking against USPTO, EPO, and JPO requirements. University technology transfer offices in California and independent inventors in Germany utilize automated form generation to reduce attorney review cycles.
- IP Valuation:Income-based, market-based, and cost-based valuation methodologies for transaction support and financial reporting. Venture capital firms in Massachusetts and corporate treasury functions in the Netherlands require these for impairment testing and collateralization.
- License Management:Royalty tracking, compliance auditing, and contract term monitoring for inbound and outbound agreements. Telecommunications equipment manufacturers in Finland and pharmaceutical licensors in Switzerland depend on automated milestone detection.
- IP Litigation Support:Prior art organization, claim chart construction, and expert witness material preparation. Trial-focused practices in Texas federal district courts and patent litigation specialists in Munich leverage these for accelerated case assembly.
- IP Renewal Tracking:Deadline monitoring, annuity calculation, and payment execution across patent and trademark portfolios. Industrial conglomerates with dispersed IP holdings in India and Brazil prevent inadvertent lapses through centralized dashboard visibility.
- Competitive Intelligence:R&D direction inference, white space identification, and technology landscape mapping from patent corpora. Strategic planning functions in South Korean electronics groups and Israeli cybersecurity vendors utilize semantic search for M&A targeting.
Patent Filing sustains the deepest installed base; Competitive Intelligence gains share fastest.
End User:
Organizational scale and legal sophistication determine module configuration, with enterprise procurement teams consolidating vendor relationships across multiple use cases.
- Corporate Legal Departments:In-house counsel managing captive IP portfolios with direct PTO interface and business unit coordination. Technology sector legal operations in Washington State and life sciences departments in New Jersey drive demand for unified platform consolidation.
- Law Firms:Partnership structures billing hourly for prosecution, litigation, and counseling services with client-matter cost allocation. Full-service practices in New York and specialized IP boutiques in London require granular time capture and client reporting.
- Research Institutions:Universities and national laboratories commercializing federally funded inventions through technology transfer. MIT, Stanford, and the Fraunhofer Society exemplify sophisticated disclosure intake and marketing workflows.
- Technology Transfer Offices:Dedicated units within academic medical centers and research foundations executing licensing and startup formation. Offices at the University of Tokyo and Imperial College London manage high-volume invention disclosure pipelines.
- Startups:Venture-backed companies with constrained legal budgets seeking automated prosecution and competitive monitoring. Seed-stage biotechnology ventures in Cambridge, Massachusetts and fintech startups in Singapore prioritize cost-efficient foreign filing automation.
Corporate Legal Departments lead on absolute spend; Startups lead on growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands deeper enterprise penetration than Germany, though both markets concentrate procurement among technology and life sciences clusters with distinct regulatory compliance architectures shaping platform requirements.
United States
Corporate legal departments in Washington State and New Jersey drive cloud-native procurement for patent prosecution automation. The USPTO's electronic filing mandates compress deployment timelines for integrated document management layers. Silicon Valley biotechnology ventures and Seattle enterprise software groups anchor demand for API-connected docketing systems.
Germany
Automotive and chemical manufacturers in Baden-Württemberg and North Rhine-Westphalia require trade secret management modules aligned with national know-how protection statutes. The EU AI Act imposes algorithmic transparency requirements on legal decision-support platforms. Munich and Stuttgart host concentrated procurement from patent-intensive engineering conglomerates.
China
Domestic technology groups and pharmaceutical filers in Beijing and Shanghai navigate data localization mandates under cybersecurity law. The National Intellectual Property Administration's digitization push accelerates demand for Mandarin-localized prosecution workflows. Shenzhen hardware manufacturers and Hangzhou e-commerce platforms drive trademark monitoring adoption.
South Korea
Semiconductor and display manufacturers in Seoul and Suwon deploy multi-jurisdictional family tracking for aggressive patent expansion. The Korean Intellectual Property Office's accelerated examination programs reward automated prior art search capabilities. Pangyo and Gwanggyo innovation clusters concentrate procurement from venture-backed deep-tech ventures.
United Kingdom
London-based private equity firms and technology transfer offices require portfolio analytics for IP-backed lending and startup formation. The UK Intellectual Property Office's post-Brexit alignment procedures reshape deadline automation specifications. Cambridge and Oxford research foundations drive disclosure intake platform adoption.
Global Intellectual Property Management Software Market Competitive Landscape
United States vendors anchor the cloud-native tier; European specialists hold position in trademark search and compliance modules. The market structures around three concentration layers: integrated platform providers with prosecution-through-litigation coverage, specialized analytics shops with machine-learning classification engines, and regional compliance-focused boutiques. Incumbents execute defensive M&A to capture API-first startups; challengers pursue vertical integration into proprietary patent data feeds.
Within the integrated platform tier, Clarivate PLC and Anaqua Inc. exemplify the data-anchored archetype, leveraging deep bibliographic repositories to differentiate analytics layers. Questel occupies a position among European specialists with concentrated trademark and design search capabilities. These three represent distinct geographic and functional positioning without overlapping core competencies.
| Leading Market Players |
|---|
| Clarivate PLC |
| Anaqua Inc. |
| Questel |
| LexisNexis |
| Thales |
| Innovation Asset Group Inc. |
| Dennemeyer & Associates S.A. |
| PatSnap |
| CPA Global |
| Others |
Supply & Pricing Matrix
Cloud-native re-platforming of legacy codebases is simultaneously compressing vendor cost structures and concentrating procurement leverage among hyperscale cloud providers in the United States and Germany. This technological transition reshapes margin economics across deployment tiers while tethering supply security to a narrow band of infrastructure-as-a-service operators.
Pricing Analysis
Capacity additions in Ireland and Singapore are reshaping price floors for cloud-hosted IP management platforms, intensifying margin pressure on pure-SaaS vendors. Three-tier pricing structure across premium, standard, and economy levels separates enterprise litigation modules from mid-market prosecution tools and startup-tier docketing automation. Price differentiation hinges on machine-learning classification depth and API integration density. Cost compression in the standard tier stems from open-source workflow engines, while corporate legal departments in the United States demonstrate lowest price sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Ireland, and Germany, where EU AI Act compliance certification creates vendor lock-in effects. Raw material dependencies span proprietary patent bibliographic databases, machine-learning training corpora, and API gateway services from national patent authorities. Supply chain risk centers on data localization mandates fragmenting cloud architectures across China and Russia. Distribution runs through direct enterprise sales teams and systems integrators serving legal operations functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification functions as a regulatory compounder, mandating explainability layers that drive replacement cycles across European pharmaceutical and automotive client bases.
For Market Incumbents: Deploy API-first acquisition strategies to neutralize cloud-native challengers threatening installed-base retention. Clarivate PLC and Anaqua Inc. must accelerate backward integration into proprietary patent data feeds before specialized analytics shops capture machine-learning classification tier premiums. Consolidation of trademark search capabilities in Europe defends against Questel's geographic moat. For New Entrants and Emerging Players: Blockchain-enabled provenance verification offers unclaimed white-space in digital asset creator segments underserved by incumbent docketing platforms. ASEAN regulatory harmonization across Vietnam, Indonesia, and Thailand presents the most penetrable geography, with unified portfolio management demand outpacing vendor supply. Channel partnerships with national intellectual property offices accelerate trust formation faster than direct enterprise sales cycles. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compliance-focused boutiques possessing captive relationships with China's National Intellectual Property Administration. Long-term viability in this market hinges on data residency certification breadth across fragmented jurisdictional requirements. Monitor USPTO electronic filing mandate acceleration as inflection indicator for platform replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-connected prosecution workflows reduce attorney hours per matter for life sciences firms filing in Brazil and India. |
| Acquisition of Specialist Firm | Machine-learning classification engines trained on international patent schemes compress prior art search bottlenecks. |
| Strategic Partnership | Collaboration with national patent offices secures real-time legal status feeds across 150-plus authorities. |
| Geographic Expansion | Private cloud instances in Brazil and India satisfy data localization mandates without client infrastructure burden. |
| Product Launch | Standard-essential patent tracking modules automate royalty stack calculations for 5G licensing pools. |
Research Methodology
Multiple input streams — structured interviews, regulatory filing analysis, and vendor capability assessments — were reconciled to construct market estimates. Primary fieldwork engaged patent prosecution attorneys, legal operations directors, chief technology officers, and intellectual property office digitization leads across the United States, Germany, China, and South Korea. Secondary validation drew from USPTO electronic filing statistics, EPO patent examination reports, EU AI Act implementation guidance, and SEC disclosures from publicly traded legal technology vendors. Bottom-up deployment counts and top-down enterprise software spending estimates were triangulated against vendor-reported subscription metrics.
Data-stream reconciliation across deployment architecture, solution depth, and end-user segmentation dimensions anchored the analytical framework. The projection horizon spans cloud-based, on-premise, hybrid, and private cloud configurations, with patent management, trademark management, and portfolio analytics modules modeled separately. CAGRs were derived from elasticity-adjusted adoption curves and regulatory deadline impacts. Machine-learning classification penetration rates and API integration density served as software-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement variance, data localization mandate expansion, and generative AI capability disruption. Forecasts reflect documented assumptions about regulatory timeline adherence and enterprise procurement cycle normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Back Testing Software Market
Software & Services
Generative Design Software Market
Software & Services
Advanced Process Control Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Global Script Writing Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Artwork Management Software Market
Software & Services
Global License Management Market
Software & Services
Content Services Platforms Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Session Support Software Market
Software & Services
Talent Management Software Market
Software & Services
SRM Software Market
Software & Services
Salon Booking Software Market
Software & Services
SMS Marketing Software Market