
 Global Digital Art Software Market | 2026-2036
Global Digital Art Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Art Software Market Foresight
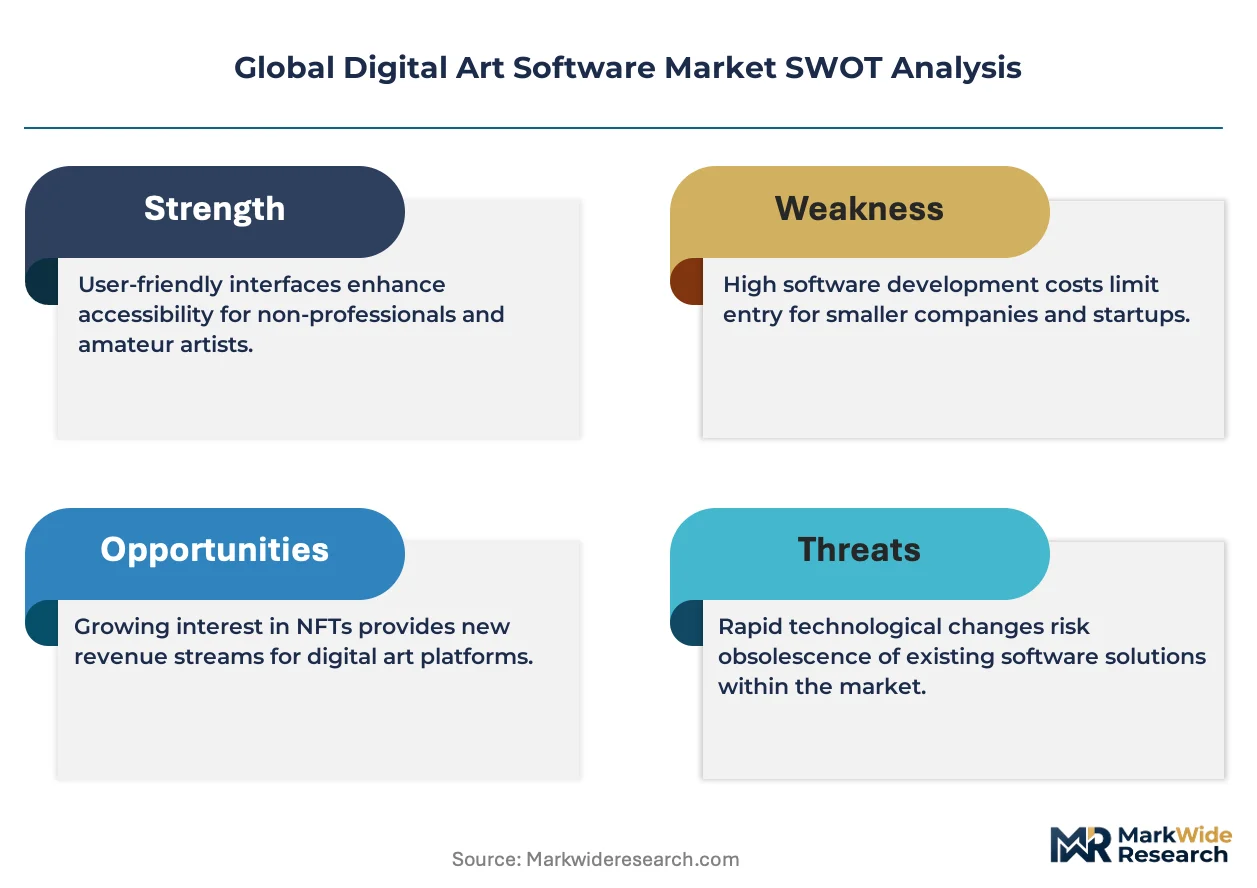
Subscription-based financing is tilting competitive dynamics toward recurring-revenue platforms that lower upfront barriers for individual creators. Adobe leverages its Creative Cloud ecosystem to sustain cross-selling across photography, illustration, and motion workflows. Krita anchors its position through open-source distribution that competes on accessibility for emerging markets and educational users.
Digital art software comprises programs that manipulate pixel arrays, mathematical vector paths, or polygonal meshes to produce visual assets for commercial and entertainment use. Raster graphics editors process bitmap data at defined resolutions, while vector graphics editors calculate scalable curves through Bézier mathematics for logo and typography work. Animation software commands premium pricing due to integrated timeline rigging and render pipeline complexity, whereas digital painting tools attract volume through stylus-optimized brush engines. Cloud-based deployment is expanding fastest as studios prioritize collaborative asset libraries over localized workstation storage.
The EU AI Act classifies generative art tools by risk category, compelling vendors to document training data provenance and output transparency. The US FCC monitors broadband infrastructure that underpins cloud rendering services, indirectly shaping market access for latency-sensitive applications. ISO standards for color management govern cross-platform fidelity in professional workflows. Stakeholders must weigh regulatory compliance costs against the creative velocity that generative features promise.
Market Dynamics
Subscription financing models are compressing upfront barriers for individual creators while concentrating competitive power in platforms with recurring-revenue architectures. This structural shift favors ecosystem bundling over standalone tool distribution.
Growth Catalysts
- EU AI Act compliance requirements:The EU AI Act mandates documentation of training data provenance for generative art tools, creating competitive moats for vendors with established transparency infrastructure.
- Real-time rendering engines:Game development studios in South Korea are expanding deployment of Unreal Engine and Unity for cinematic previsualization, accelerating hardware upgrade cycles.
- Cloud-based collaborative asset libraries:Distributed production teams in the United States are migrating from localized workstation storage to cloud rendering services that enable synchronous remote workflows.
Market Restraints
- GPU supply concentration:Discrete graphics processing unit fabrication concentrates in Taiwan and South Korea, exposing software vendors to semiconductor foundry bottlenecks.
- Perpetual license depreciation:Freelance artists in mature markets resist subscription migration, creating revenue recognition friction for vendors transitioning business models.
- Color management standardization gaps:Cross-platform fidelity remains constrained by inconsistent ISO 12646 implementation across monitor manufacturers.
Strategic Opportunities
- Educational institutional procurement:Open-source distribution models in India and Brazil penetrate price-sensitive academic markets where Adobe Creative Cloud pricing exceeds institutional budgets.
- Generative AI workflow integration:Text-to-image diffusion models converging with traditional brush engines create new product categories for concept artists in entertainment verticals.
- India's PLI scheme for electronics manufacturing:Production-linked incentives for hardware assembly could localize tablet and stylus supply chains, reducing input costs for digital painting tool vendors.
Industry Challenges
- Generative AI training data licensing:Copyright disputes over scraped artistic works create legal exposure for vendors integrating machine learning features.
- Legacy pipeline integration:Animation studios with established render farm investments face technical debt when adopting cloud-native collaboration tools.
- Specialized rigging talent scarcity:Complex timeline and bone-system expertise concentrates in experienced practitioners, constraining studio scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Art Software Market |
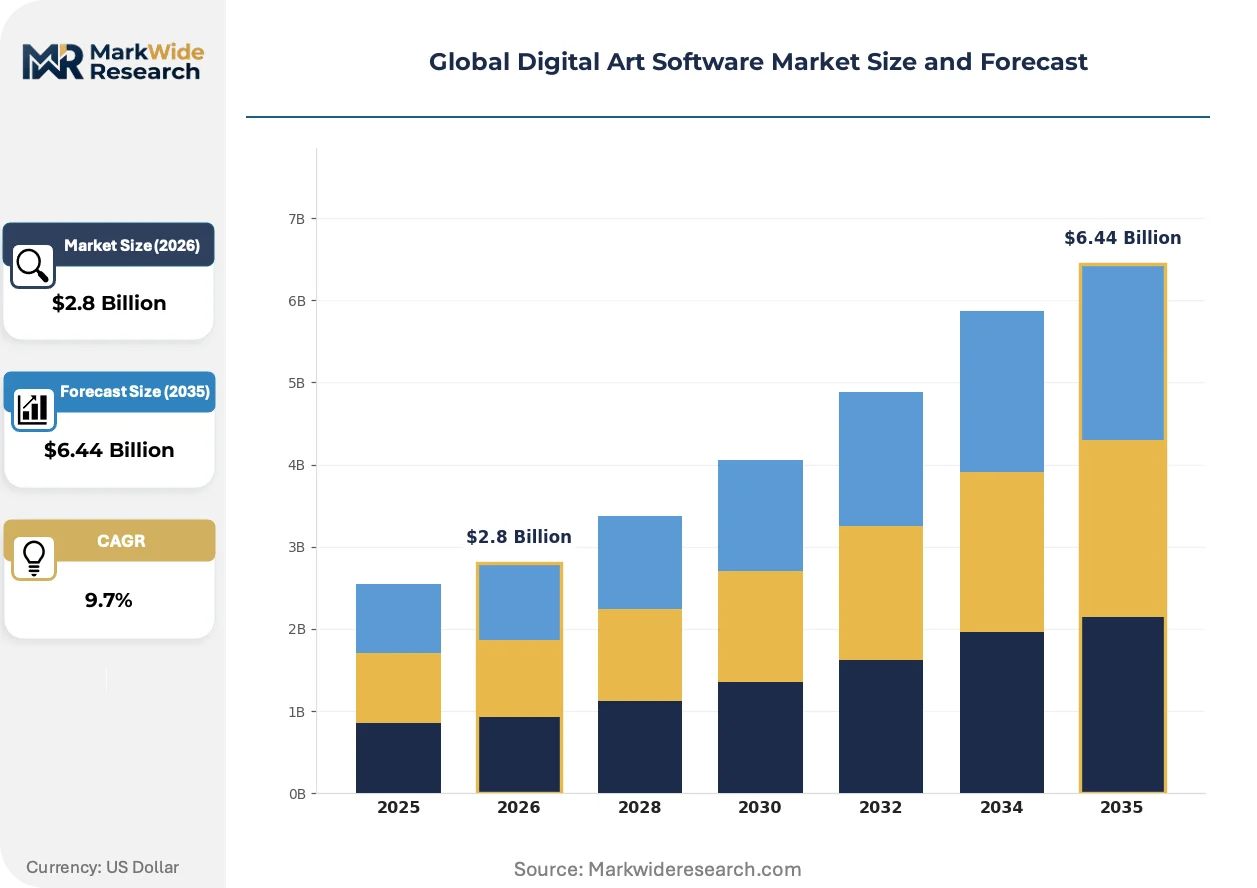
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raster Graphics Editors, Vector Graphics Editors, 3D Modeling Software, Animation Software, Digital Painting Tools Deployment: On-Premise, Cloud-Based, Hybrid Cloud, Mobile, Desktop Application: Game Development, Graphic Design, Advertising, Film Production, Web Design End User: Freelance Artists, Design Studios, Educational Institutions, Advertising Agencies, Media Houses |
| Companies Covered | Adobe Photoshop, Adobe Illustrator, Adobe, GIMP, Krita, Corel Painter, Adobe Fresco, Affinity Photo, Procreate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Art Software Market Shifts & Advancements
Neural rendering techniques are compressing production timelines for visual asset creation while regulatory frameworks reshape competitive compliance burdens. These forces are redistributing value capture across the software stack.
AI-assisted inpainting and outpainting tools are rendering obsolete manual background extension workflows in matte painting departments. Freelance concept artists in the United States are adopting these features within six-month upgrade cycles. Traditional rotoscoping and plate cleanup services are rendering obsolete as automated segmentation achieves production-grade edge fidelity.
The EU AI Act's risk-tier classification system for generative art tools is compelling vendors to restructure product roadmaps around transparency documentation. High-risk system providers must implement human oversight mechanisms and output labeling protocols. European animation studios are responding by bifurcating procurement between compliant generative tools and established non-AI alternatives.
Consumption patterns among independent creators are fragmenting across specialized single-purpose tools rather than consolidating in monolithic suites. Clip Studio Paint and Procreate are capturing illustration workflows that Photoshop once dominated. This unbundling is most visible in Japan and South Korea where mobile-first stylus workflows predominate among younger professionals.
Global Digital Art Software Market Segmentation
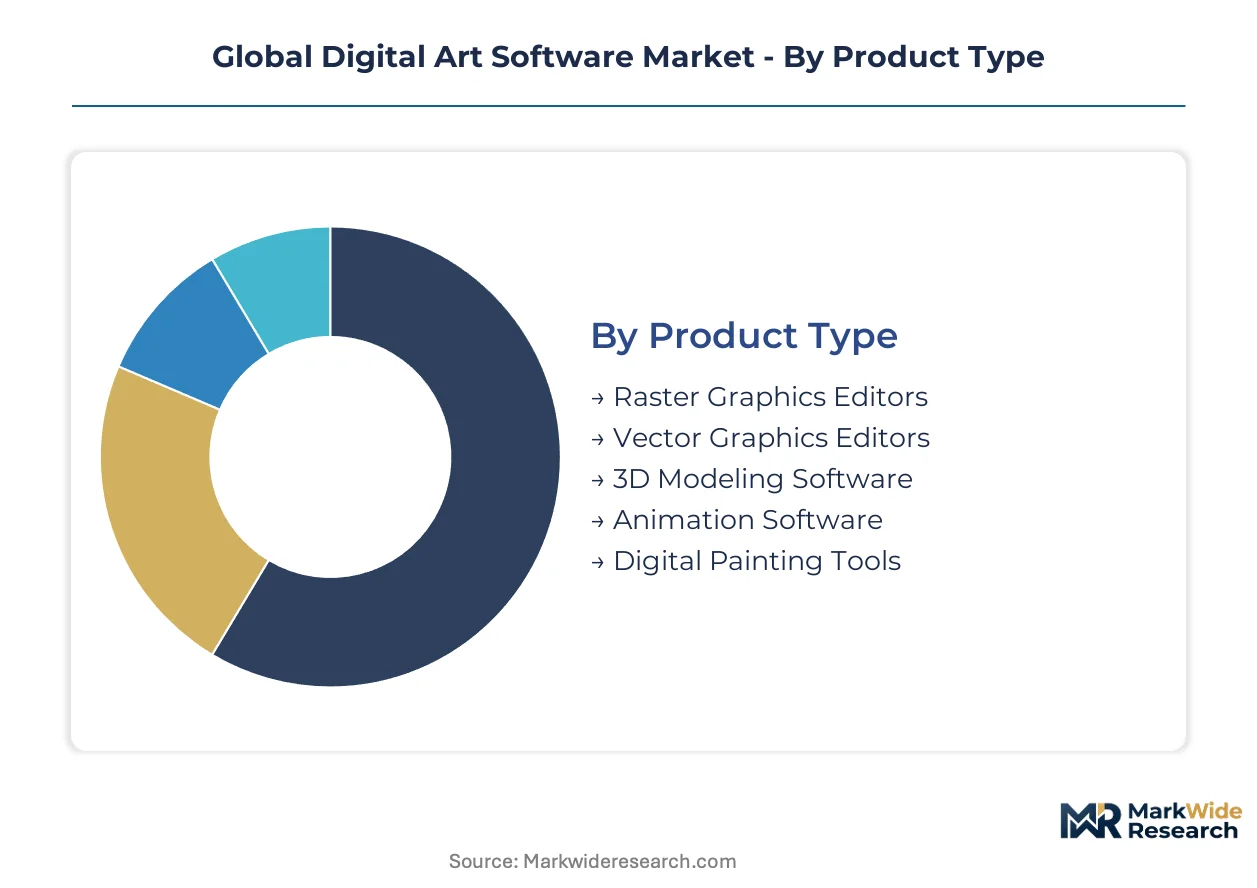
Digital art software vendors structure product portfolios around distinct technical architectures and consumption patterns. Segment-level profitability varies sharply with deployment complexity, end-user scale, and integration requirements across creative pipelines.
Product Type:
After-sales-service intensity correlates directly with feature depth and pipeline integration requirements. Animation suites demand ongoing rigging support and render farm troubleshooting, while raster editors require less intensive technical assistance.
- Raster Graphics Editors:These programs manipulate bitmap data at fixed resolutions, applying filter algorithms and layer compositing for photographic manipulation and texture work. Demand concentrates among freelance photographers and social media content creators in the United States, where subscription fatigue is accelerating migration toward alternatives with perpetual licensing options.
- Animation Software:Timeline-based systems integrate bone rigging, motion curves, and render pipeline management for cinematic and interactive media production. South Korean game development studios are expanding deployment of these tools for real-time cinematic previsualization, driving hardware upgrade cycles and technical support contracts.
- Vector Graphics Editors:Bézier-curve mathematics enable infinite scalability for logo, typography, and iconography workflows across print and digital outputs.
- 3D Modeling Software:Polygonal mesh manipulation and sculpting tools serve industrial design, architectural visualization, and entertainment asset pipelines.
- Digital Painting Tools:Stylus-optimized brush engines simulate physical media behavior for illustration and concept art workflows.
Raster graphics editors hold the largest share; momentum sits with animation software.
Deployment:
Cost tier stratification separates enterprise-grade cloud subscriptions from entry-level mobile applications. Premium deployments bundle collaborative asset libraries and dedicated support channels.
- Cloud-Based:Browser-accessible platforms with centralized asset storage and synchronous editing capabilities serve distributed production teams. United States-based advertising agencies are migrating from localized workstation storage to these services, prioritizing remote collaboration over single-user performance optimization.
- On-Premise:Perpetually licensed software installed on local hardware maintains data sovereignty and eliminates recurring subscription obligations. Freelance artists in mature markets favor this deployment mode to control long-term cost structures and avoid vendor lock-in.
- Hybrid Cloud:Split architectures process sensitive assets locally while offloading rendering and storage to remote infrastructure.
- Desktop:Traditional workstation-installed applications optimized for keyboard-shortcut workflows and GPU acceleration.
- Mobile:Touch-optimized tools for tablet and smartphone consumption, prevalent among younger professionals in Japan and South Korea.
On-premise retains the largest installed base; cloud-based deployment is climbing the fastest.
Application:
Volume concentration varies with production cycle length and asset reuse intensity. Game development commands the longest engagement horizons and deepest pipeline integration.
- Game Development:Real-time engine integration and iterative asset pipelines demand software with live-link capabilities between modeling, texturing, and level editing tools. South Korean studios are expanding use of Unreal Engine and Unity for cinematic previsualization, accelerating procurement of compatible authoring software.
- Film Production:High-resolution compositing and color grading workflows require HDR-capable display calibration and ACES color space compliance. European studios are bifurcating procurement between EU AI Act-compliant generative tools and established non-AI alternatives.
- Graphic Design:Print and digital layout workflows prioritize typographic precision and brand asset consistency.
- Advertising:Rapid-turnaround campaign production favors template-driven workflows and social media format automation.
- Web Design:Responsive layout tools and interactive prototyping capabilities serve digital product development teams.
Game development holds the largest share; film production shows the steepest expansion trajectory.
End User:
Customer type determines pricing elasticity and procurement centralization. Institutional buyers negotiate volume discounts and curriculum integration support that individual creators cannot access.
- Educational Institutions:Academic licensing programs penetrate price-sensitive markets where commercial subscription pricing exceeds departmental budgets. Open-source distribution models in India and Brazil are capturing procurement decisions through accessibility and curriculum flexibility.
- Design Studios:Mid-sized creative agencies balance tool standardization against individual artist preferences, creating mixed-vendor environments. These organizations are consolidating around ecosystem bundles that reduce license management overhead.
- Freelance Artists:Individual creators migrate between subscription and perpetual models based on project pipeline visibility.
- Advertising Agencies:Enterprise procurement teams negotiate multi-year contracts with cross-departmental deployment rights.
- Media Houses:Broadcast and publishing organizations maintain legacy pipeline investments while selectively adopting cloud collaboration features.
Design studios hold the largest share; educational institutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where subscription premiums exceed perpetual license costs in India by multiples. European regulatory compliance adds cost layers that Asian markets largely bypass.
United States
Freelance artists drive migration from perpetual licenses toward subscription models, consolidating spending in ecosystem bundles. The FCC monitors broadband infrastructure shaping cloud rendering service quality. Los Angeles and New York media clusters anchor demand for high-resolution compositing and collaborative asset pipelines.
South Korea
Game development studios expand real-time rendering engine deployment for cinematic previsualization, accelerating hardware procurement cycles. The MFDS maintains medical device oversight that indirectly shapes adjacent creative technology standards. Seoul Capital Area studios concentrate investment in Unreal Engine and Unity-compatible authoring tools.
Germany
Industrial design and architectural visualization sustain demand for precision 3D modeling workflows. The EU AI Act mandates training data provenance documentation for generative art tools, restructuring vendor compliance roadmaps. Bavaria and Baden-Württemberg automotive design clusters adopt cloud-native collaboration for distributed engineering teams.
India
Educational institutions and price-sensitive freelancers gravitate toward open-source distribution models that bypass commercial subscription costs. The PLI scheme for electronics manufacturing targets tablet and stylus supply chain localization. Maharashtra and Karnataka technology corridors incubate domestic digital painting tool adoption.
Japan
Mobile-first stylus workflows predominate among younger illustration professionals, fragmenting demand away from desktop-centric suites. METI standards govern display calibration and color management fidelity. Tokyo and Osaka animation studios maintain bifurcated procurement between EU AI Act-compliant generative tools and established non-AI alternatives.
Global Digital Art Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in brush engines and rendering modules. The vendor base stratifies between ecosystem bundlers and single-purpose tool developers. Three archetypes dominate: Creative Cloud-style subscription platforms, open-source accessibility plays, and mobile-native stylus-optimized applications. Competitive moves concentrate in ecosystem bundling to reduce license management overhead and in generative AI feature integration to capture concept art workflows.
Within the open-source accessibility tier, Krita and GIMP exemplify distribution models that penetrate price-sensitive academic markets. Adobe anchors the subscription platform archetype through Creative Cloud cross-selling across photography, illustration, and motion workflows. Procreate occupies a position within the mobile-native specialization tier, capturing illustration workflows that desktop suites once dominated.
| Leading Market Players |
|---|
| Adobe Photoshop |
| Adobe Illustrator |
| Adobe |
| GIMP |
| Krita |
| Corel Painter |
| Adobe Fresco |
| Affinity Photo |
| Procreate |
| Others |
Supply & Pricing Matrix
Taiwan and South Korea's stranglehold on discrete GPU fabrication concentrates cost leverage upstream, forcing software vendors to absorb foundry pricing volatility while subscription models compress downstream margin pools toward recurring-revenue platforms.
Pricing Analysis
Configured-to-order enterprise licensing commands multiples over standard individual subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates studio-grade animation suites with render farm support from entry-level raster editors and mobile painting applications. Price differentiation hinges on integration depth and after-sales service intensity. Cost compression in the freelance tier intensifies as open-source alternatives erode Adobe's perpetual license residual value.
Supply Chain Analysis
Tariff exposure between the United States and China dominates semiconductor component sourcing strategies for stylus and tablet hardware vendors. GPU supply concentrates in Taiwan and South Korea, while display panel fabrication anchors in China and Japan. Raw material dependencies span silicon wafers, rare earth magnets for stylus precision, and cobalt for battery cells. Single-source vulnerability in TSMC's leading-edge nodes threatens hardware refresh cycles. Distribution runs through direct-to-consumer digital storefronts and OEM pre-installation agreements with workstation manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where technical support contracts and training subscriptions expand faster than perpetual license revenue, rewarding vendors who embed workflow consulting into core offerings.
For Market Incumbents: Build data-provenance documentation infrastructure as the EU AI Act's high-risk system requirements create compliance moats. Consolidate around ecosystem bundling that reduces license management overhead for design studios. Deepen backward integration into cloud rendering capacity to capture infrastructure spend from migrating advertising agencies.
For New Entrants and Emerging Players: India's educational procurement gap offers the most penetrable white-space target where Adobe Creative Cloud pricing exceeds institutional budgets. Brazil's price-sensitive freelance community presents secondary entry terrain. Attack through open-source distribution with curriculum integration support rather than feature parity competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed animation tool specialists holding established studio relationships but lacking generative AI roadmaps. Five-to-ten year viability hinges on regulatory compliance architecture rather than feature velocity alone. Monitor EU AI Act enforcement patterns as the inflection signal for vendor restructuring urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Feature Integration | Text-to-image diffusion convergence with brush engines captures concept art workflows in entertainment verticals. |
| Cloud Rendering Infrastructure Expansion | Distributed production teams in the United States prioritize synchronous remote collaboration over localized storage. |
| Educational Curriculum Partnership | Open-source penetration in India and Brazil builds long-term user pipelines through academic institutional procurement. |
| EU AI Act Compliance Certification | Training data provenance documentation creates competitive moats for vendors serving European animation studios. |
| Mobile-First Stylus Optimization | Younger professionals in Japan and South Korea fragment demand away from desktop-centric suites toward specialized tools. |
Research Methodology
The analysis maps raster graphics editors, vector tools, animation suites, and 3D modeling platforms, each validated through CTOs at game development studios, IT procurement officers at advertising agencies, platform engineers at cloud rendering providers, and channel partners distributing educational licenses. Primary interviews with these stakeholders combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile download data, and ISO standards documentation. Bottom-up product-level sizing triangulated against top-down industry expenditure estimates.
Assumptions held fixed include current regulatory enforcement intensity and prevailing GPU supply chain configuration, while variables spanned adoption curve steepness for generative features and subscription migration velocity among freelance artists. Segmentation dimensions modeled encompass deployment model, organization size, vertical application, integration complexity, and regional adoption pattern. CAGRs derived from fitted growth curves anchored to observable license transaction volumes and cloud service consumption metrics. Forecast inputs included South Korean studio hardware procurement cycles and EU AI Act implementation timelines.
Practitioners should monitor semiconductor foundry utilization rates and generative AI copyright litigation outcomes for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Germany Digital Twin Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Smart Government Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Tablet Based E-Detailing Market
Digital Solutions
Dataops Platform Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Anticipatory Commerce Infrastructure Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Global Domain and Hosting Market