
 Digital Signature Market | 2026-2036
Digital Signature Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Signature Market Intelligence
The European Union's eIDAS regulation is decoupling the legal validity of electronic signatures from physical presence, fundamentally altering the cost-of-entry for service providers. DocuSign, Inc. leverages its extensive integration ecosystem to capture enterprise-level workflows. Adobe Inc. sustains its market position by embedding signature capabilities within its widely adopted document management software suite. Meanwhile, Thales Group specializes in hardware security modules that underpin high-assurance signature solutions for regulated industries.
A digital signature is a cryptographic mechanism used to verify the authenticity and integrity of a digital message or document. It employs a public key infrastructure (PKI) to create a unique, encrypted hash of the data, ensuring non-repudiation for the signer. Cloud-based solutions dominate the market due to their scalability and ease of deployment for small and medium-sized enterprises. Within end-user industries, the banking and legal documentation segments command the highest value due to stringent compliance requirements.
Global regulatory frameworks, including the US ESIGN Act and the EU's eIDAS, establish the legal equivalence of digital signatures to handwritten ones. Standards like ISO 32000 for PDF documents and FIPS 140-2 for cryptographic modules further dictate technical requirements for interoperability and security. Vendor selection increasingly depends on the ability to provide solutions that are compliant across multiple jurisdictions and can integrate with emerging blockchain-based identity systems.
Market Dynamics
The fundamental shift from physical presence to digital identity verification, codified by cross-border legal frameworks, is the central force shaping the digital signature market. This decouples transaction validity from geography, creating a standardized, accessible market for trust services.
Growth Catalysts
- EU eIDAS Regulation:The framework provides a predictable, pan-European legal environment for electronic signatures, which accelerates adoption for cross-border business transactions, particularly in financial services and legal documentation sectors.
- Paperless Government Initiatives:National campaigns, such as those in India, to digitize public services and promote a paperless economy create sustained, large-scale demand for digital signature solutions across administrative and commercial functions.
- Financial Sector Adoption:The banking industry's requirement for secure, auditable, and non-repudiable methods for remote contract execution and high-value transactions drives investment in high-assurance digital signature technologies.
Market Restraints
- PKI Interoperability:A lack of universal standards between different Public Key Infrastructure (PKI) implementations can create technical friction and compatibility issues, hindering seamless cross-platform and cross-organizational document exchange.
- Fragmented Legal Recognition:Outside of established frameworks like the EU's eIDAS and the US ESIGN Act, inconsistent legal status and varying admissibility standards for digital signatures in some jurisdictions create uncertainty for businesses.
- Implementation Costs:The initial capital expenditure for on-premise hardware security modules (HSMs) and the complexity of managing a private PKI present a significant cost barrier for many small and medium-sized enterprises.
Strategic Opportunities
- Blockchain Integration:The convergence of digital signatures with blockchain-based decentralized identity (DID) systems offers an opportunity to create more user-centric, secure, and tamper-proof verification methods independent of a central authority.
- Emerging Market Penetration:There is significant opportunity in Southeast Asian and Latin American economies where rapid digitalization, mobile-first populations, and growing e-commerce create fertile ground for cloud-based signature solutions.
- AI-Powered Security:Integrating artificial intelligence and machine learning algorithms can enhance security by providing real-time behavioral analysis and fraud detection during the signing process, creating a new value proposition.
Industry Challenges
- Legacy System Integration:Vendors face significant technical hurdles in seamlessly integrating modern, API-driven signature platforms with older, monolithic enterprise systems like legacy ERP or document management software still prevalent in large organizations.
- Cryptographic Skill Scarcity:A persistent shortage of cybersecurity professionals with deep expertise in applied cryptography, key management, and PKI architecture limits the ability of organizations to deploy and manage high-assurance solutions internally.
- Complex Compliance Pathways:The process for a service provider to become a Qualified Trust Service Provider (QTSP) under eIDAS involves lengthy audits and stringent security requirements, posing a high barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Signature Market |
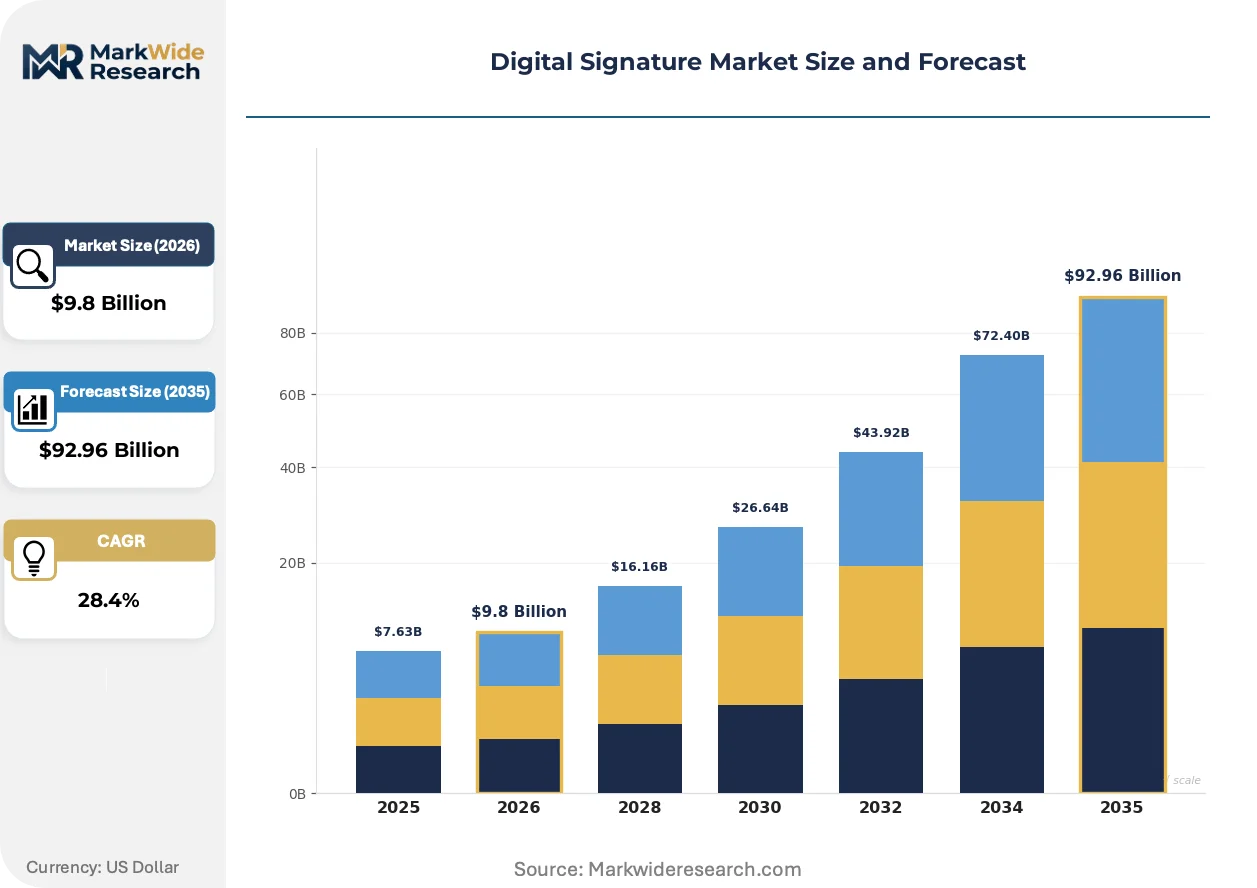
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $92.96 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premises, Hybrid, Mobile Application: Legal Documentation, Financial Transactions, Human Resources, Real Estate End User Industry: Banking, Insurance, Government Agencies, Education Deployment Model: Public Cloud, Private Cloud, Community Cloud, Managed Services |
| Companies Covered | GlobalSign, Inc., Thales Group, DocuSign, Inc., PandaDoc, Entrust Corporation, Adobe Inc., SIGNiX, Inc., Dropbox Sign, OneSpan, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Signature Market Strategic Shifts & Innovations
The market's evolution is defined by the democratization of trust services, driven by the convergence of cloud delivery models and mobile-first workflows. This expands access beyond traditional enterprise deployments to small businesses and individual professionals.
Cloud-based signature platforms deliver cryptographic key management and document workflow automation as a scalable service. Small and medium-sized enterprises (SMEs) are adopting these solutions rapidly to reduce the need for on-premise hardware and specialized IT staff. This shift is consolidating the market around large-scale providers who can leverage economies of scale in security infrastructure and multi-jurisdictional compliance.
Regulatory standardization, exemplified by the US ESIGN Act, provides a durable legal foundation for electronic commerce. The act grants electronic signatures the same legal status as handwritten ones, removing critical barriers for conducting business across state lines. This has been particularly transformative for the national real estate and financial lending industries, which now rely on ESIGN-compliant platforms.
User expectation is moving away from standalone signature applications toward functionality embedded directly within core business software. This trend favors API-first providers whose services can be integrated into existing CRM, HR, and contract lifecycle management systems, making the signing process a native part of a workflow. The shift is most pronounced within enterprise sales and procurement departments.
Digital Signature Market Segmentation
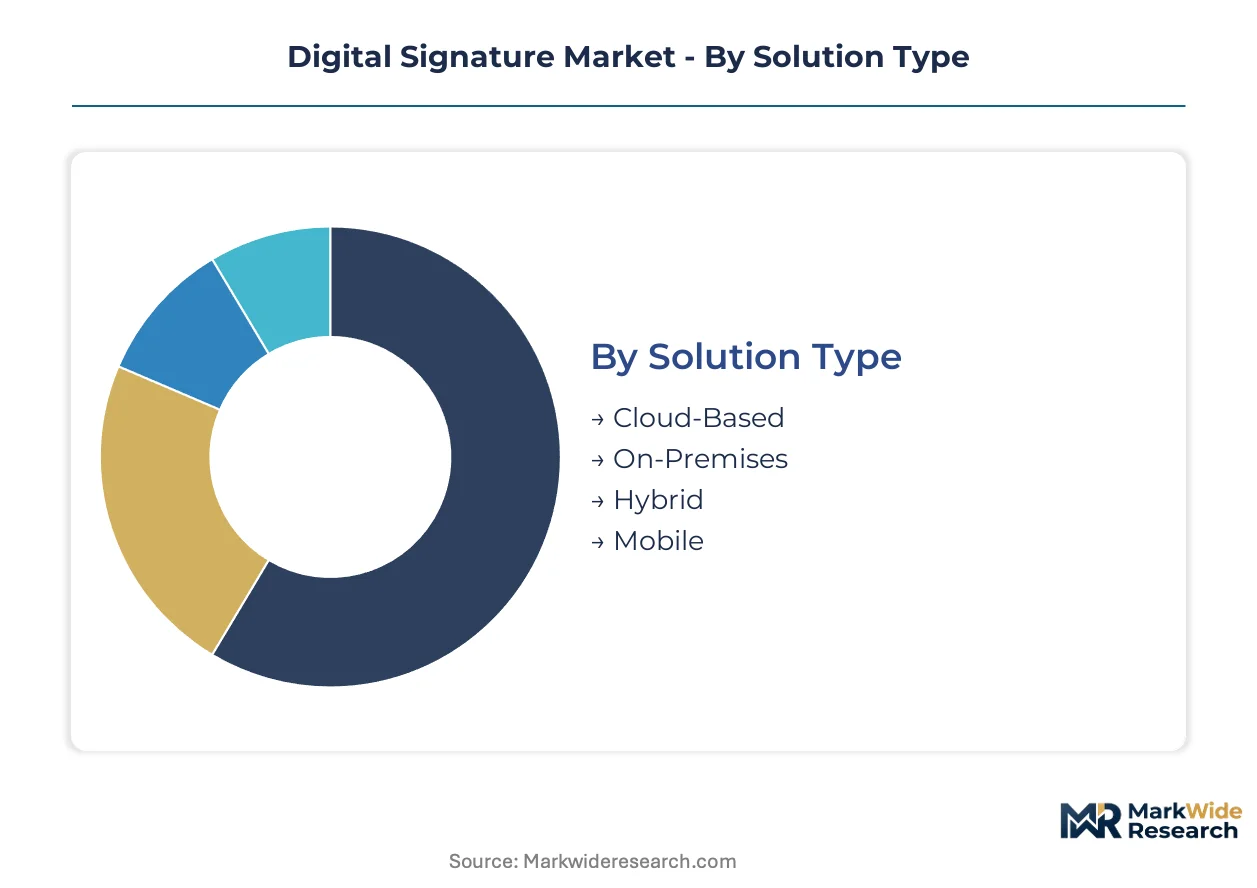
The digital signature market's segmentation reflects the diverse operational needs and regulatory environments across various industries. Understanding these distinctions is crucial for providers to tailor solutions that address specific compliance requirements, security levels, and integration complexities for different user groups.
Solution Type:
What differentiates buyers in this category is their preference for deployment infrastructure and control over cryptographic keys.
- Cloud-Based:Cloud-based solutions deliver cryptographic key management and document workflow automation as a scalable service. Small and medium-sized enterprises in India are rapidly adopting these due to ease of deployment and lower initial investment.
- On-Premises:On-premises solutions involve installing software and managing hardware security modules (HSMs) within an organization's own infrastructure. Large financial institutions in Europe prefer this for stringent data sovereignty and compliance requirements like eIDAS.
- Hybrid:Hybrid solutions combine aspects of both cloud and on-premises deployments, offering flexibility for data storage and key management. Organizations with mixed IT environments leverage hybrid models for phased digital transformation.
- Mobile:Mobile solutions enable digital signing directly from smartphones or tablets, enhancing accessibility and convenience for remote workers. This type supports field operations and on-the-go contract approvals.
Cloud-Based solutions lead volumes today; Mobile solutions are gaining share fastest.
Application:
Volume concentration defines demand within this category.
- Financial Transactions:Financial transactions require high-assurance digital signatures for remote contract execution and high-value transfers. European banks leverage these for secure cross-border payments under eIDAS regulations.
- Legal Documentation:Legal documentation applications ensure the authenticity and non-repudiation of agreements, such as property deeds and court filings. US legal firms rely on ESIGN-compliant platforms for remote client agreements.
- Human Resources:Human resources applications utilize digital signatures for secure employee onboarding, contract signing, and policy acknowledgements. Companies globally streamline HR workflows with these automated solutions.
- Real Estate:Real estate applications facilitate remote signing of leases, purchase agreements, and mortgage documents, accelerating transaction closures. The US real estate sector has widely adopted these for convenience.
Financial transactions generate the highest value, while human resources applications are expanding most quickly.
End User Industry:
Customer type and regulatory compliance drive purchasing decisions in this segment.
- Banking:Banking institutions demand secure, auditable, and non-repudiable digital signatures for high-value transactions and customer onboarding. The Reserve Bank of India mandates digital signatures for various financial processes.
- Government Agencies:Government agencies utilize digital signatures for secure public services, administrative documents, and citizen identity verification. India's paperless government initiatives create large-scale demand for these solutions.
- Insurance:Insurance companies deploy digital signatures for policy issuance, claims processing, and agent agreements, improving operational efficiency. Global insurers adopt these for enhanced security and compliance.
- Education:Educational institutions use digital signatures for academic records, administrative approvals, and online course certifications. Universities and schools digitize internal and external documentation flows.
Banking and insurance sectors demand high-assurance solutions, while education is seeing a rapid uptake in cloud-based platforms.
Deployment Model:
The level of infrastructure control and security requirements distinguish deployment model preferences.
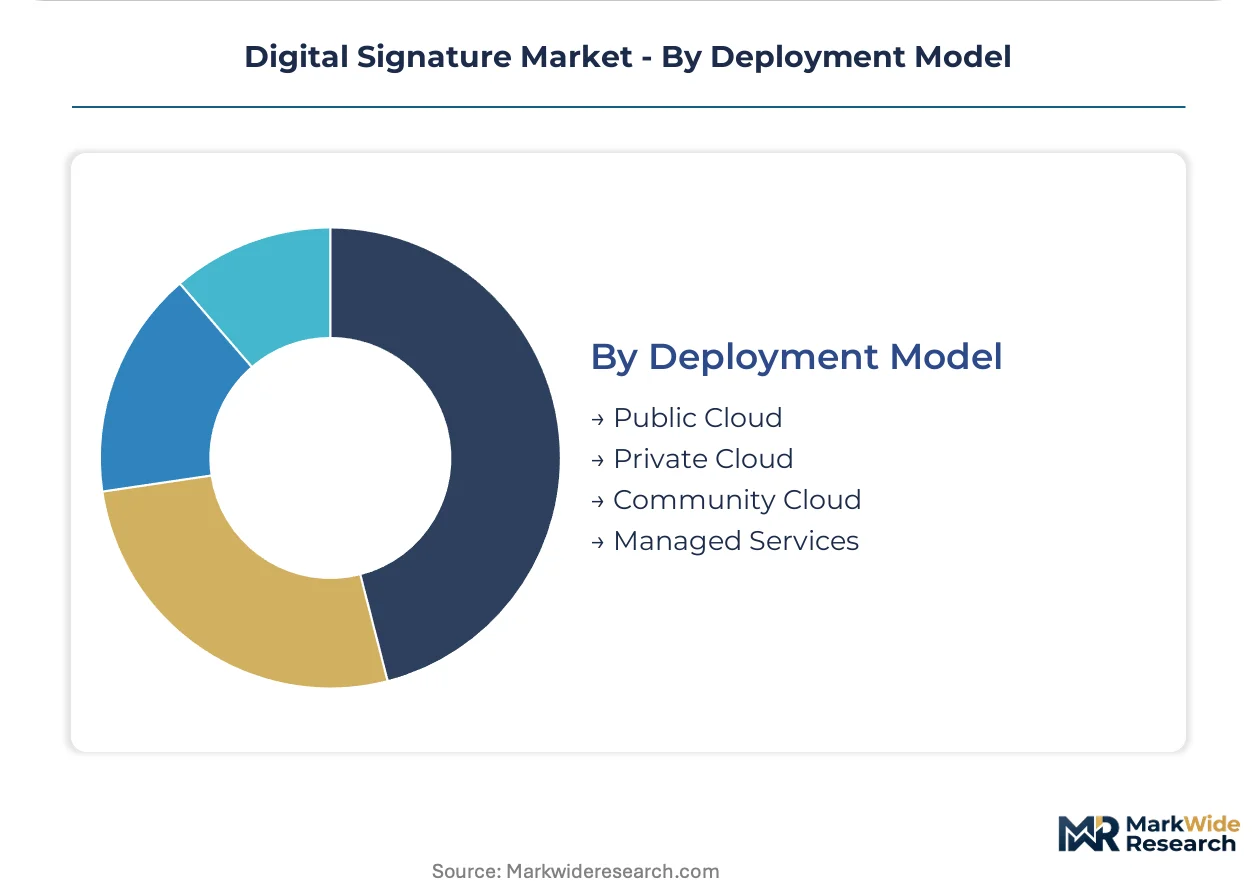
- Public Cloud:Public cloud deployments offer scalable, accessible digital signature services managed by third-party providers. Small and medium-sized enterprises globally favor these for cost-effectiveness and ease of integration.
- Managed Services:Managed services provide comprehensive digital signature solutions, including infrastructure, software, and ongoing support, reducing internal IT burden. Large enterprises in regulated industries often opt for this specialized expertise.
- Private Cloud:Private cloud deployments offer dedicated infrastructure and enhanced control over data and security, often hosted within an organization's own data center. Enterprises with strict data residency requirements prefer private cloud solutions.
- Community Cloud:Community cloud models share infrastructure among several organizations with common security and compliance concerns. This approach is prevalent in sectors like healthcare or government consortia.
Public cloud models dominate for scalability, while private cloud deployments meet stringent data residency needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A high concentration of skilled cybersecurity professionals and a robust technological infrastructure anchor the global digital signature market. This confluence drives innovation and accelerates the adoption of secure digital transaction platforms across various industries. Key regions are establishing distinct growth trajectories based on regulatory environments and digital transformation initiatives.
United States
The United States market thrives on the widespread adoption of digital signatures in financial lending and real estate transactions. The US ESIGN Act provides a strong legal foundation, granting electronic signatures the same legal status as handwritten ones. Technology hubs in California and financial centers in New York foster continuous innovation and integration into enterprise systems.
India
India's ambitious paperless government initiatives create large-scale demand for digital signature solutions across administrative and commercial functions. The Reserve Bank of India mandates digital signatures for various financial processes, ensuring secure and auditable transactions. Technology centers like Bengaluru and Hyderabad drive the rapid adoption of cloud-based solutions for small and medium-sized enterprises.
Germany
German enterprises, particularly in the financial and legal sectors, prioritize high-assurance digital signatures for stringent data sovereignty and compliance requirements. The EU's eIDAS regulation provides a predictable and standardized legal environment for cross-border business transactions within the European Union. Financial centers in Frankfurt leverage these solutions for secure cross-border payments and contract execution.
China
China's massive e-commerce market and rapid digitization of public services fuel significant demand for digital signature technologies. Relevant national regulations support the legal validity and security of electronic signatures for both consumer and business transactions. Major tech centers like Shanghai and Shenzhen are developing localized solutions tailored to the country's unique digital ecosystem.
Japan
Japanese corporations are increasingly adopting digital signatures for internal workflows, supply chain management, and remote collaboration. National legislation provides legal recognition for electronic documents and signatures, facilitating digital transformation efforts. Tokyo's vibrant business districts are seeing widespread integration of signature capabilities into existing enterprise resource planning and customer relationship management systems.
Digital Signature Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping the competitive dynamics of the digital signature market. The market structure is tiered, with established platform providers and agile innovators addressing different segments. Strategic archetypes include comprehensive workflow platforms, specialized security hardware providers, and API-first integrators. Competitive moves involve strategic partnerships and portfolio diversification to capture varied client needs across industries.
Among the established platform providers, DocuSign, Inc. exemplifies extensive integration ecosystems for enterprise-level workflows. Adobe Inc. sustains its market position by embedding signature capabilities within its widely adopted document management software suite. Thales Group, a French multinational, anchors the high-assurance segment, specializing in hardware security modules that underpin solutions for regulated industries.
| Leading Market Players |
|---|
| GlobalSign, Inc. |
| Thales Group |
| DocuSign, Inc. |
| PandaDoc |
| Entrust Corporation |
| Adobe Inc. |
| SIGNiX, Inc. |
| Dropbox Sign |
| OneSpan, Inc. |
| Others |
Cost & Logistics Intelligence
Publicly traded platform providers and venture-backed specialists shape supply behavior and pricing discipline in the digital signature market. These entities invest heavily in secure infrastructure and compliance certifications, influencing market entry costs and service offerings.
Pricing Analysis
Bundled service offerings, integrating signature capabilities with document workflow automation, define the core pricing structure. Subscription-based SaaS tiers are the dominant pricing model, reflecting ongoing service delivery and maintenance. Price differentiation stems from the level of cryptographic assurance required, such as eIDAS Qualified Electronic Signatures, and the volume of transactions or users. Pricing pressure arises from the proliferation of basic e-signature tools and intense competition among cloud providers. Small and medium-sized enterprises demonstrate higher price sensitivity, while large financial institutions prioritize compliance and security over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized cryptographic module manufacturers and trusted certificate authorities, critical components for high-assurance solutions. Geographic supply concentration for these foundational technologies often includes the United States, Germany, and Switzerland. Raw material dependencies involve advanced cryptographic algorithms and secure hardware elements like Hardware Security Modules (HSMs). A key structural risk is the scarcity of cybersecurity professionals with deep cryptographic expertise. Downstream distribution runs through direct enterprise sales and a network of value-added resellers and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU's eIDAS regulation consistently driving demand for legally robust and interoperable digital signature solutions across Europe.
For Market Incumbents: Anchor market share by continuously expanding integration ecosystems with enterprise software platforms like CRM and ERP. Innovate in AI-powered security features to counter emerging fraud vectors and enhance user experience, differentiating from basic e-signature providers. Invest in multi-jurisdictional compliance certifications to mitigate the threat of fragmented legal recognition across diverse geographies.
For New Entrants and Emerging Players: Underserved small and medium-sized enterprises in rapidly digitizing emerging markets present a significant white-space opportunity. Focus on cloud-native, mobile-first solutions with an API-first approach for seamless integration into existing business applications. Target niche industries with specific compliance needs, offering tailored, cost-effective solutions that simplify complex regulatory pathways. A freemium model can effectively penetrate new user segments.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with strong local compliance and customer bases, offering attractive acquisition targets. The long-term viability favors platforms capable of integrating with blockchain-based identity systems for enhanced security and decentralization. Watch the adoption rate of new interoperability standards for digital identities as a key inflection indicator for future market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand API Integration Ecosystem | Increases platform stickiness and extends reach into diverse enterprise workflows. |
| Invest in AI-Powered Security Features | Enhances fraud detection and user authentication, raising the bar for solution integrity. |
| Acquire Regional Compliance Specialists | Accelerates market entry and ensures adherence to specific local regulatory frameworks. |
| Develop Blockchain Identity Solutions | Positions for future decentralized trust models and tamper-proof verification. |
| Penetrate Emerging Market Verticals | Unlocks new revenue streams by addressing unmet demand in rapidly digitizing economies. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. This included in-depth conversations with CTOs, legal compliance officers, IT procurement managers, and cybersecurity architects. Secondary data sources comprised regulatory whitepapers, industry association reports, patent databases for cryptographic innovations, and academic research papers on digital trust.
The forecast framework anchored the projection horizon to historical reference periods, ensuring continuity and relevance. Segmentation dimensions modeled included deployment model, application, end-user industry, geographic region, and security assurance level. Compound annual growth rates were derived from a multi-factor analytical framework, projecting market evolution. Key industry-specific forecast inputs included enterprise digital transformation budgets and regulatory compliance deadlines.
Underlying measurement precision varies by segment; cloud-based solutions and financial transactions carry tighter precision than others, such as niche applications in highly fragmented regional markets. Forecasts reflect assumptions concerning technological advancements and market dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Online Dating Services Market
Digital Solutions
Global Drilling Data Management Systems Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
AQI App Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Data Pipeline Market
Digital Solutions
Premium Messaging Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Software Defined Application and Infrastructure Market