
 US Digital Twin Market | 2026-2036
US Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital Twin Market Insights
NIST's cybersecurity framework for operational technology is hardening the cost-of-entry calculus for digital twin vendors serving critical infrastructure. GE Vernova leverages its Predix platform heritage to dominate energy-sector deployments across regulated utilities. Siemens anchors its position through deep manufacturing automation integration and shop-floor data capture architectures. Autodesk competes by extending BIM-native workflows into operational-phase digital twins for commercial construction portfolios.
A digital twin constitutes a dynamic virtual representation of a physical asset, system, or process, maintained through real-time data synchronization via IoT sensors, edge computing nodes, and physics-based simulation engines with sub-second latency requirements. Its primary commercial purpose spans predictive intervention, design-space exploration, and operational optimization across capital-intensive industries. Software offerings capture the dominant margin pool as vendors embed AI-driven analytics layers atop core modeling kernels. Cloud deployment is accelerating fastest among mid-market manufacturers seeking to avoid on-premises data center capital expenditure. Predictive maintenance applications lead in realized ROI documentation, though design simulation retains higher per-seat pricing power.
The FAA, NIST, and FDA collectively shape US digital twin demand through airworthiness simulation standards, cybersecurity maturity requirements, and medical device validation protocols that mandate traceable virtual testing environments. OSHA's emerging interest in virtual hazard simulation for worker safety training further expands addressable use cases. Stakeholders must monitor how federal procurement guidelines evolve to prioritize vendors demonstrating interoperable model standards and sovereign data residency controls.
Market Dynamics
FAA airworthiness certification frameworks for simulation-based validation are forcing aerospace manufacturers to rebuild modeling architectures around traceable data lineage and sovereign compute environments.
Growth Catalysts
- Energy-sector decarbonization mandates:FERC grid modernization directives compel utilities to deploy asset-level digital twins for predictive capacity planning and renewable integration modeling.
- OSHA virtual hazard simulation protocols:Emerging worker safety training requirements expand addressable use cases beyond equipment optimization into immersive workforce development environments.
- Texas and California industrial metaverse clusters:Concentrated deployments by technology firms and energy utilities generate reference architectures that accelerate vendor sales cycles across adjacent states.
Market Restraints
- Physics engine licensing concentration:Proprietary multiphysics solver ecosystems from a narrow vendor base create switching costs that lock mid-market manufacturers into suboptimal platforms.
- NIST cybersecurity framework compliance:Operational technology hardening requirements impose documentation and audit burdens that extend sales-to-deployment timelines by quarters.
- Edge compute infrastructure capex:Sub-second latency requirements for real-time synchronization demand dedicated on-premise or sovereign cloud deployments that strain capital budgets.
Strategic Opportunities
- Medical device validation protocols:FDA mandates for traceable virtual testing environments open regulated healthcare as a high-margin vertical with documented ROI requirements.
- AI-driven analytics convergence:Embedding machine learning layers atop physics-based kernels creates differentiated pricing power and recurring revenue streams.
- Southeast aerospace manufacturing corridor:Fleet lifecycle management deployments by expanding manufacturers establish beachheads for multi-decade service relationships.
Industry Challenges
- Interoperable model standards gaps:Absence of unified data exchange protocols forces costly custom integration work for multi-vendor environments.
- Digital thread architect talent scarcity:Shortage of engineers fluent in both domain physics and cloud-native software architecture constrains deployment velocity.
- Legacy SCADA integration friction:Brownfield manufacturing sites require expensive retrofitting of data capture architectures to feed twin synchronization pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital Twin Market |
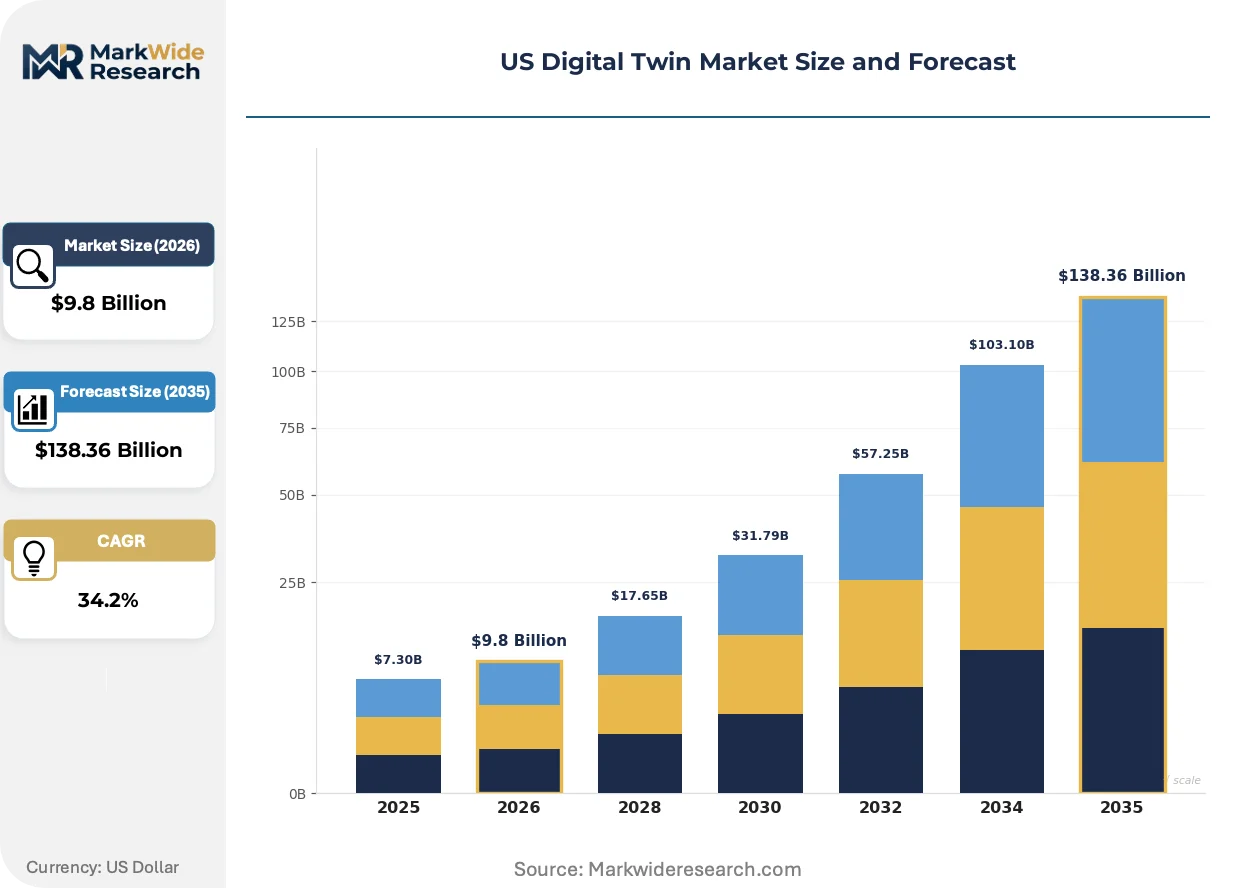
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $138.36 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Integration End User: Manufacturing, Healthcare, Automotive, Smart Cities Deployment: Cloud, On-Premises, Hybrid, Edge Application: Predictive Maintenance, Design Simulation, Performance Optimization, Asset Management |
| Companies Covered | Autodesk Inc., ANSYS Inc., PTC Inc., IBM Corporation, GE Vernova, Microsoft Corporation, Siemens, Dassault Systèmes, Oracle Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital Twin Market Trends and Innovations
Cloud-native deployment architectures are compressing time-to-value for mid-market manufacturers while federal procurement guidelines increasingly prioritize interoperable standards and data sovereignty controls.
Physics-based simulation engines are modularizing into composable microservices that discrete manufacturing sectors can configure without full-platform commitments. Automotive and industrial equipment producers in Michigan and Ohio are piloting componentized solver deployments that isolate specific failure modes rather than replicating entire asset models. This architecture is modularizing vendor competitive dynamics, allowing specialized firms to capture subsegments without competing against integrated platform incumbents.
FAA evolving certification pathways for model-based system engineering are mandating formal verification methods that trace every simulation output to validated physical test data. Aerospace suppliers in the US Southeast must now maintain immutable audit logs spanning design, operational, and maintenance-phase twins. Defense and commercial aviation subsegments are responding by investing in sovereign data residency controls that satisfy both regulatory inspectors and prime contractor security requirements.
Mid-market manufacturers are unbundling after-sales service contracts from initial platform licensing, preferring consumption-based pricing tied to realized predictive maintenance outcomes. Industrial distributors in the Midwest are repositioning as implementation partners that shoulder deployment risk in exchange for recurring performance fees. This behavioral shift is most visible among precision machining and packaging equipment buyers seeking to align vendor compensation with uptime improvements rather than software seat counts.
US Digital Twin Market Segmentation
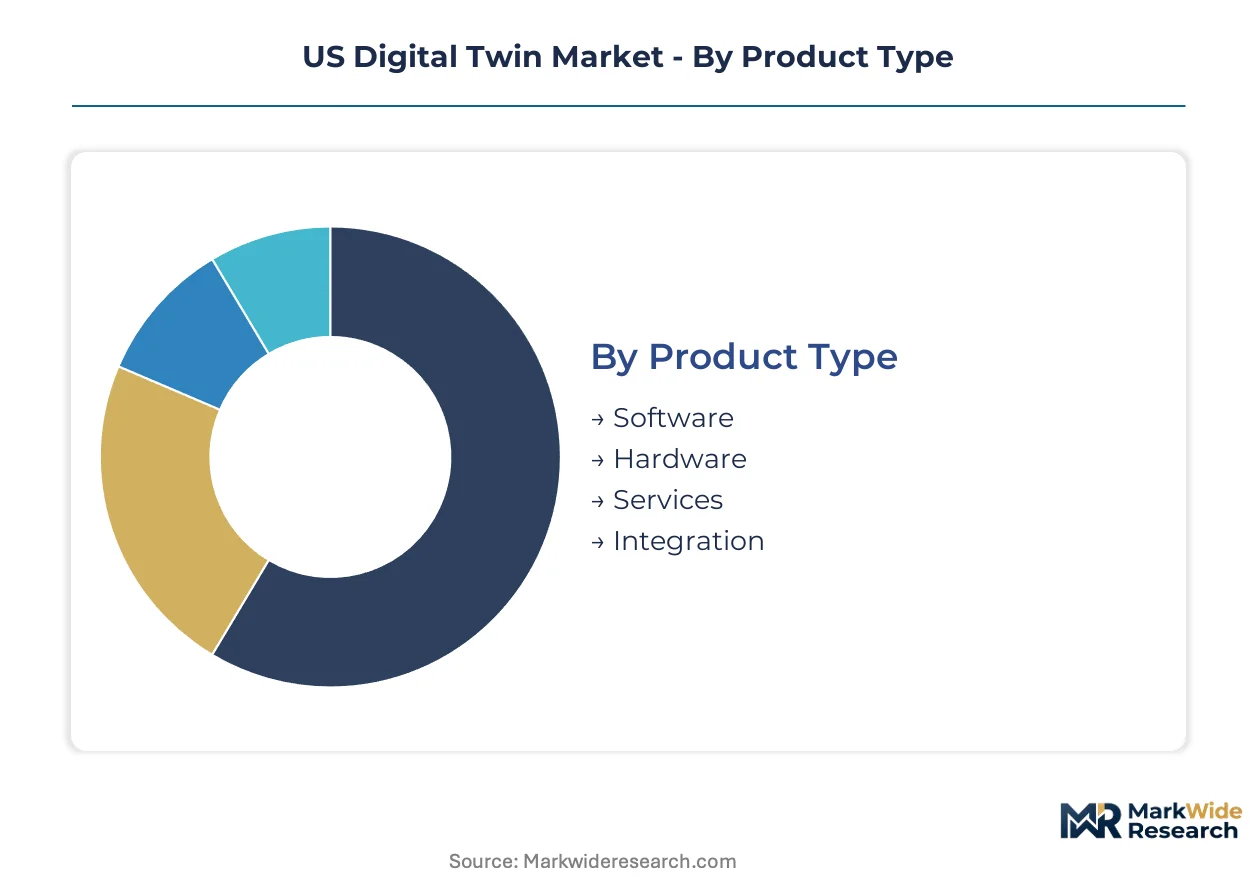
Digital twin procurement patterns diverge sharply across product architectures, with certification burdens and latency requirements dictating vendor selection. Segment boundaries blur as platform vendors bundle software, hardware, and integration layers into outcome-based contracts.
Product Type:
FAA airworthiness mandates and FDA medical device protocols impose distinct validation requirements on software versus hardware components, reshaping vendor R&D allocation.
- Software:Physics-based simulation kernels and AI analytics layers dominate margin capture. Aerospace manufacturers in the US Southeast prioritize traceable data lineage features to satisfy evolving FAA certification frameworks.
- Hardware:Edge computing nodes and IoT sensor arrays require sovereign data residency controls for defense and aviation prime contractors. Texas energy utilities deploy hardened OT hardware to meet NIST cybersecurity maturity tiers.
- Services:Implementation and ongoing model calibration support recurring revenue streams.
- Integration:Custom data pipeline engineering bridges legacy SCADA with cloud-native twin architectures.
Leading the category by volume: Software. Growing fastest: Hardware.
End User:
Customer procurement sophistication spans from outcome-based contracting among precision manufacturers to capital-budget cycles at municipal infrastructure operators.
- Manufacturing:Automotive and industrial equipment producers in Michigan and Ohio pilot componentized solver deployments that isolate specific failure modes. Brownfield retrofitting costs constrain deployment velocity at legacy assembly plants.
- Healthcare:FDA mandates for traceable virtual testing environments position medical device validation as a high-margin vertical. Device manufacturers face documentation burdens that extend sales-to-deployment timelines.
- Automotive:Fleet lifecycle management and connected vehicle platforms drive digital thread investments.
- Smart Cities:Municipal infrastructure operators deploy asset-level twins for predictive capacity planning.
Manufacturing commands the largest addressable spend. Healthcare climbs fastest as regulatory validation protocols mature.
Deployment:
Latency requirements and data sovereignty concerns fragment cloud migration patterns across customer scale tiers.
- Cloud:Mid-market manufacturers accelerate adoption to avoid on-premises data center capital expenditure. Consumption-based pricing aligns vendor compensation with uptime improvements rather than seat counts.
- On-Premises:Sub-second synchronization demands strain capital budgets at regulated utilities and defense suppliers. Sovereign compute environments satisfy both FAA inspectors and prime contractor security requirements.
- Hybrid:Split architectures isolate sensitive physics kernels on-premise while pushing analytics to cloud.
- Edge:Dedicated edge nodes serve real-time synchronization requirements for predictive maintenance applications.
Cloud deployment widens fastest among new adopters. Edge infrastructure captures premium pricing for latency-critical use cases.
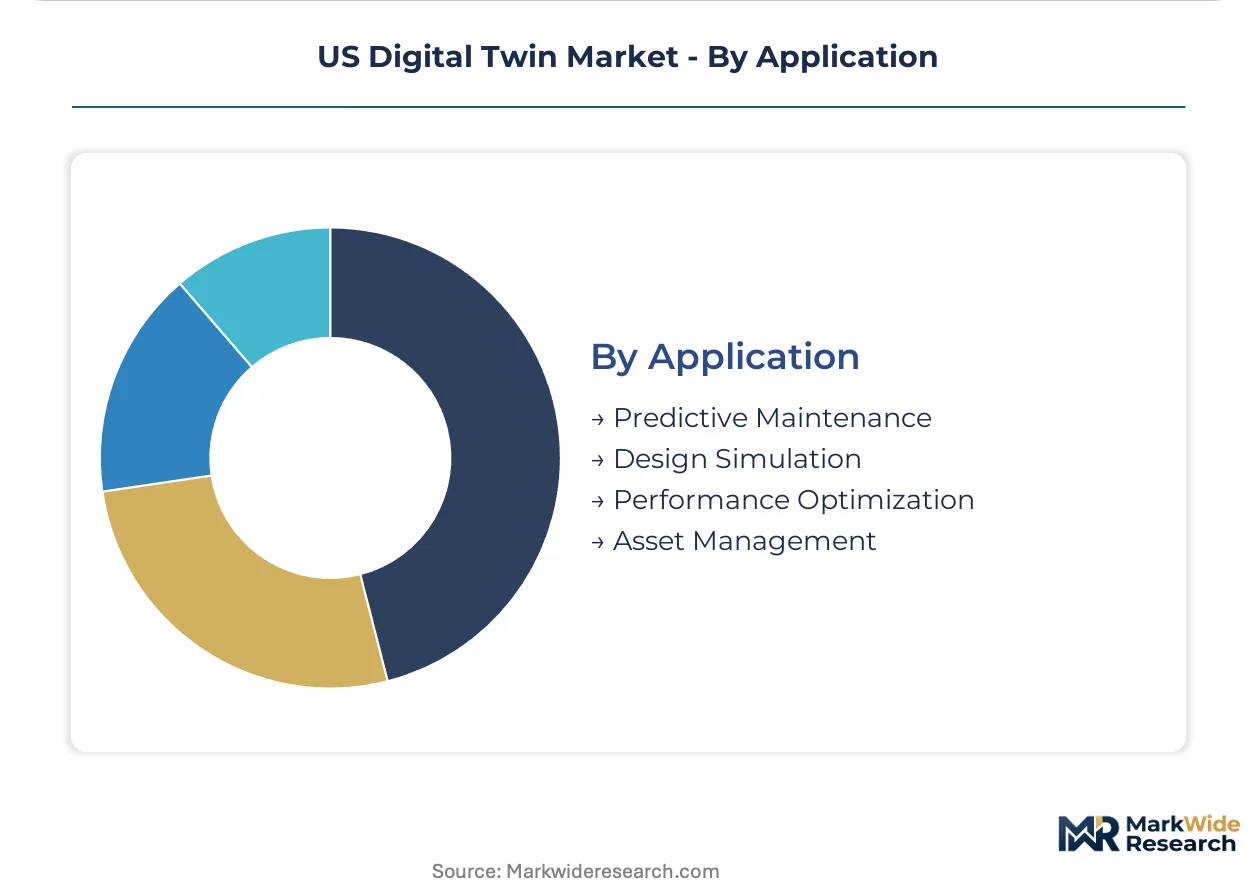
Application:
ROI documentation quality varies dramatically across use case maturity, shaping vendor pricing power and customer referenceability.
- Predictive Maintenance:Documented uptime improvements support outcome-based contracting models. Industrial distributors in the Midwest shoulder deployment risk in exchange for recurring performance fees tied to realized results.
- Design Simulation:Per-seat pricing power exceeds operational-phase applications despite narrower addressable base. FAA model-based system engineering mandates drive formal verification investments by aerospace suppliers.
- Performance Optimization:Real-time operational tuning generates measurable efficiency gains for energy utilities.
- Asset Management:Fleet lifecycle management establishes multi-decade service relationships with expanding manufacturers.
Predictive maintenance leads in documented ROI. Design simulation retains highest pricing power per deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and California concentrate the nation's densest industrial metaverse deployments, attracting energy utilities and technology firms with accelerated depreciation allowances.
Southeast Aerospace Corridor
Fleet lifecycle management demand from expanding manufacturers drives digital twin procurement across Georgia, Florida, and South Carolina. FAA airworthiness certification frameworks for simulation-based validation mandate traceable data lineage architectures. Charleston and Savannah anchor multi-decade service relationships as defense and commercial aviation suppliers invest in sovereign compute environments.
Texas Energy Cluster
FERC grid modernization directives compel utilities to deploy asset-level twins for renewable integration modeling and predictive capacity planning. NIST cybersecurity framework compliance imposes operational technology hardening requirements that extend vendor sales cycles. Houston and Dallas-Fort Worth host the country's largest regulated utility deployments, with hardened edge infrastructure satisfying sub-second latency requirements.
California Technology Belt
Mid-market manufacturers accelerate cloud-native adoption to avoid on-premises data center capital expenditure. OSHA emerging protocols for virtual hazard simulation expand addressable use cases into immersive workforce development. Silicon Valley and Los Angeles Basin technology firms operate reference architectures that accelerate vendor sales cycles across adjacent western states.
Midwest Manufacturing Belt
Automotive and industrial equipment producers in Michigan and Ohio pilot componentized solver deployments isolating specific failure modes. Brownfield SCADA integration friction constrains deployment velocity at legacy assembly plants. Detroit and Cleveland precision machining operations unbundle after-sales service contracts, preferring consumption-based pricing tied to realized predictive maintenance outcomes.
Pacific Northwest Defense Hub
Prime contractor security requirements drive sovereign data residency controls for physics-based simulation engines. Edge compute infrastructure capex strains capital budgets as sub-second synchronization demands dedicated deployments. Seattle and Portland aerospace suppliers rebuild modeling architectures around immutable audit logs spanning design, operational, and maintenance-phase twins.
US Digital Twin Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Platform vendors bundle software, hardware, and integration layers into outcome-based contracts that blur traditional segment boundaries. Three archetypes dominate: industrial automation incumbents with deep manufacturing data capture heritage, cloud-native challengers embedding AI analytics layers, and specialized physics engine licensors. Consolidation pressure intensifies through strategic partnerships and technology licensing arrangements as customers demand interoperable model standards.
Within the industrial automation tier, GE Vernova and Siemens occupy anchor positions representing platform heritage strategies. Autodesk exemplifies the design-native workflow extension archetype, competing by operationalizing building information modeling into commercial construction portfolios. Among cloud-native entrants, Microsoft Corporation sits within the infrastructure-as-a-service vector, leveraging hyperscale compute and edge orchestration capabilities.
| Leading Market Players |
|---|
| Autodesk Inc. |
| ANSYS Inc. |
| PTC Inc. |
| IBM Corporation |
| GE Vernova |
| Microsoft Corporation |
| Siemens |
| Dassault Systèmes |
| Oracle Corporation |
| Others |
Pricing and Supply Chain Analysis
Digital thread architect scarcity in the Southeast aerospace corridor widens pricing-tier spreads, as vendors absorb premium labor costs for engineers fluent in both domain physics and cloud-native software architecture.
Pricing Analysis
Lead-time-driven pricing premiums attach to sovereign compute environments satisfying FAA inspectors, while spot inventory discounts appear in commoditized cloud-native SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Cost compression in mid-market manufacturing subscriptions is intensifying because industrial distributors shoulder deployment risk in exchange for recurring performance fees. Municipal infrastructure operators exhibit highest price sensitivity; defense prime contractors demonstrate least.
Supply Chain Analysis
Single-source vulnerability sits with proprietary multiphysics solver ecosystems from Germany, France, and the United States. Hardware components draw from Taiwan for edge computing nodes, South Korea for advanced sensors, and domestic US fabs for defense-grade semiconductors. Tariff exposure on Chinese-manufactured IoT sensor arrays threatens margin stability at tier-two vendors. Distribution runs through systems integrators and industrial distributors repositioning as implementation partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
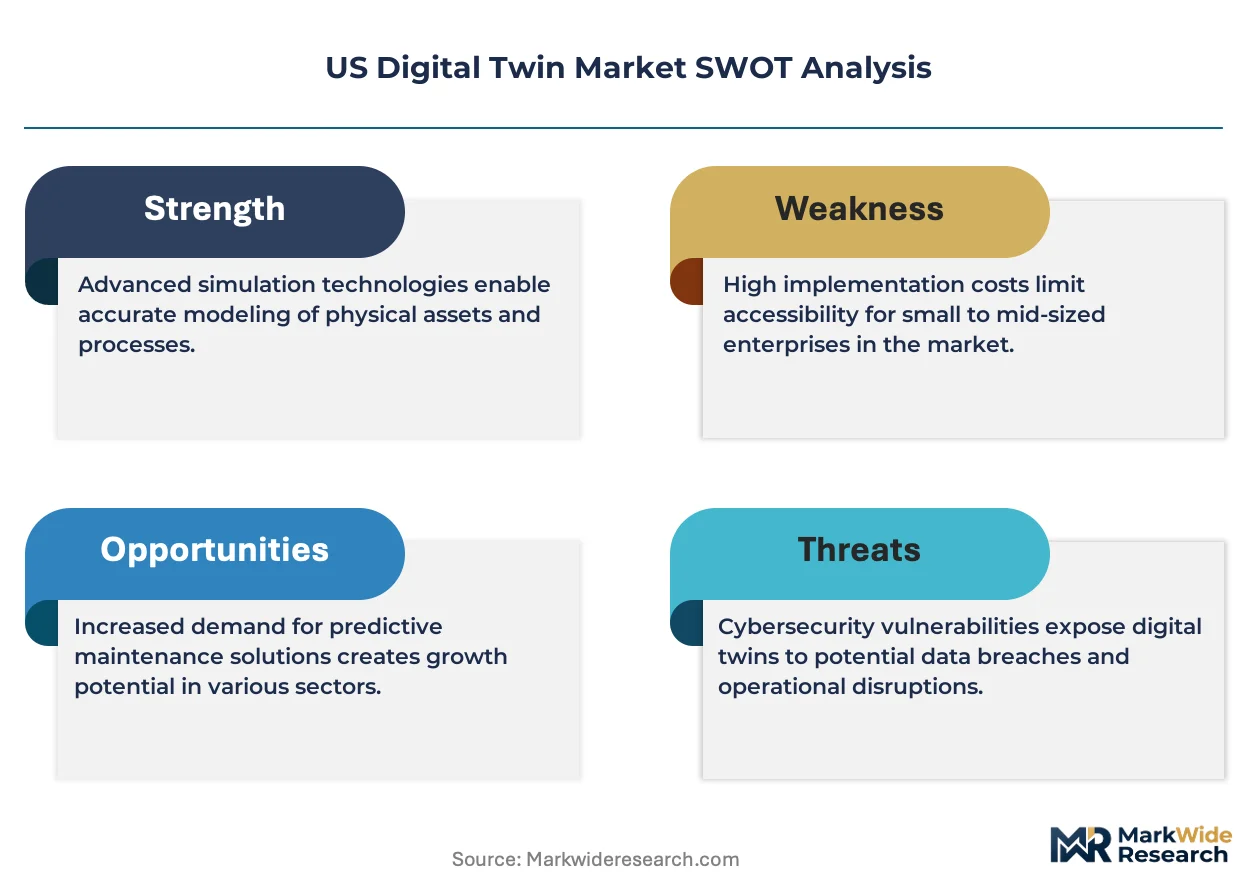
The US digital twin market reads as supply-constrained, with digital thread architect talent scarcity propping pricing power for vendors with captive training pipelines.
For Market Incumbents: Cement platform dominance by deepening sovereign compute partnerships with Charleston and Savannah aerospace suppliers facing FAA audit log mandates. Acquire specialized physics engine licensors to neutralize modularization threats from componentized solver entrants. Prioritize certification investment in FDA medical device validation protocols to lock in high-margin healthcare verticals before cloud-native challengers embed AI analytics layers. For New Entrants and Emerging Players: OSHA emerging protocols for virtual hazard simulation in California open a window for immersive workforce development platforms targeting precision machining operations in Detroit and Cleveland. Penetrate the Midwest manufacturing belt through consumption-based pricing tied to realized predictive maintenance outcomes. Pursue hospital system partnerships as the most penetrable healthcare entry vector, leveraging FDA documentation burden complexity to differentiate against incumbent platform bundles. For Investors and Strategic Acquirers: The window for entry favors specialized physics engine licensors with modular microservice architectures. Long-term viability hinges on acquisition targets demonstrating interoperable model standards and sovereign data residency controls. Watch federal procurement guideline evolution as the inflection signal prioritizing vendors with traceable virtual testing environments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk extends BIM-native workflows into operational-phase twins for commercial construction portfolios. |
| Strategic Partnership | GE Vernova leverages Predix heritage to dominate energy-sector deployments across FERC-regulated utilities. |
| Acquisition of Specialist Firm | Siemens deepens manufacturing automation integration through shop-floor data capture architecture specialists. |
| Geographic Expansion | Microsoft Corporation deploys hyperscale edge orchestration across Texas and California industrial metaverse clusters. |
| Product Launch | ANSYS modularizes physics-based simulation engines into composable microservices for automotive failure mode isolation. |
Research Methodology
Multi-period observation of vendor R&D allocation, FAA certification pathway evolution, and utility procurement patterns anchored the trend analysis, supplemented by interviews with platform engineers at cloud-native challengers, maintenance directors at Midwest precision machining operations, regulatory affairs leads at Southeast aerospace suppliers, and biomedical engineers at FDA-regulated device manufacturers. Secondary validation drew from SEC filings, FERC grid modernization directives, FAA airworthiness guidance documents, and NIST cybersecurity framework updates. Bottom-up deployment volume estimates triangulated against top-down addressable spend calculations.
Segment-weighting applied deployment model, organization size, vertical regulatory burden, and integration complexity dimensions across the modeling period. CAGRs derived from curve-fitting observed adoption velocities against infrastructure capex cycles and certification timeline compression. Industry-specific forecast inputs included FERC renewable integration mandates and OSHA virtual training protocol development trajectories.
The model assumes a particular technology adoption path; alternative pathways for sovereign edge compute architectures would alter the outlook. Forecasts reflect assumptions about FAA certification timeline acceleration and NIST cybersecurity tier enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Digital Commerce Software Market
Digital Solutions
Data Broker Market
Digital Solutions
Global Machine Translation (MT) Market
Digital Solutions
AI Infrastructure Solutions Market
Digital Solutions
Location Targeted Mobile Advertising Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Data Enrichment Solutions Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Global Procurement-As-A-Service (PAAS) Market
Digital Solutions
Global Network Monitoring Software Market
Digital Solutions
Laser Page-Turning Pen Market
Digital Solutions
Legaltech Market
Digital Solutions
Global Freight Software Market
Digital Solutions
Global Process Orchestration Market