
 Correspondence Management Solution Market | 2026-2036
Correspondence Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Correspondence Management Solution Market Outlook
GDPR Article 17 right-to-erasure enforcement is decoupling correspondence storage from legacy archive economics, forcing vendors to rebuild retention architectures around granular deletion capabilities. DocuWare leverages deep integration with European enterprise content management stacks to sustain channel control in regulated industries. NICE CXone anchors its position through AI-powered interaction analytics that map full correspondence lifecycles for compliance audit trails. Zendesk competes by extending its ticketing DNA into asynchronous correspondence orchestration across messaging, email, and social channels.
A correspondence management solution is a software platform that captures, routes, tracks, and archives inbound and outbound communications across multiple channels, typically processing structured metadata fields, retention policies, and audit logs at throughput rates exceeding thousands of documents per hour. Its primary commercial purpose is to eliminate information silos, enforce regulatory retention, and accelerate response resolution in high-volume communication environments. Cloud-based deployments now lead technology adoption as enterprises abandon capital-intensive on-premise hardware refresh cycles, while AI integration represents the fastest-expanding capability layer where natural language processing automates routing decisions and sentiment classification. Email management retains the largest product-type volume base, though case management captures disproportionate margin pools in legal and public-sector implementations where workflow complexity justifies premium pricing.
The EU AI Act and GDPR jointly shape product standards by mandating explainability logs for automated correspondence handling, while the SEC in the United States enforces retention and surveillance rules that drive financial sector procurement specifications. ISO 27001 certification has become a de facto market-access threshold for vendors serving government agencies and corporations with cross-border data flows. Stakeholders must monitor how divergent sovereignty requirements across jurisdictions fragment cloud deployment strategies and force architectural decisions between centralized platforms and federated national instances.
Market Dynamics
Healthcare digitization mandates and the EU AI Act's explainability requirements are compressing procurement cycles for auditable correspondence platforms, forcing vendors to embed granular deletion capabilities and automated audit trails into core architecture.
Growth Catalysts
- GDPR Article 17 enforcement:Right-to-erasure mandates are decoupling storage economics from legacy archive models, creating demand for granular deletion-capable platforms in regulated European enterprises.
- Healthcare communication expansion:Patient correspondence volumes are accelerating structured platform adoption as systems consolidate fragmented point solutions into unified governance frameworks.
- Natural language processing integration:AI-powered routing and sentiment classification are compressing response resolution times in high-volume contact center environments.
Market Restraints
- Data sovereignty fragmentation:Divergent national cloud deployment rules are forcing architectural choices between centralized platforms and federated instances, raising infrastructure complexity.
- Legacy system integration costs:Deep ECM stack integration requirements in regulated industries extend implementation timelines and professional services dependency.
- ISO 27001 certification barriers:Cross-border data flow requirements create de facto market-access thresholds that exclude smaller vendors from government and multinational procurement.
Strategic Opportunities
- German federal digitization mandates:Strict data sovereignty rules and local deployment preferences favor compliant, on-premise or sovereign cloud correspondence infrastructure.
- Case management premiumization:Workflow complexity in legal and public-sector implementations justifies higher-margin deployments beyond commoditized email management.
- AI-powered interaction analytics convergence:Mapping full correspondence lifecycles for compliance audit trails creates differentiation in financial services surveillance requirements.
Industry Challenges
- Retention architecture rebuilds:Vendors must reconstruct storage systems around granular deletion capabilities rather than additive archive economics, demanding significant R&D reallocation.
- Explainability log engineering:Automated decision-making contexts require traceable communication chains that capture routing logic and human oversight touchpoints at throughput scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Correspondence Management Solution Market |
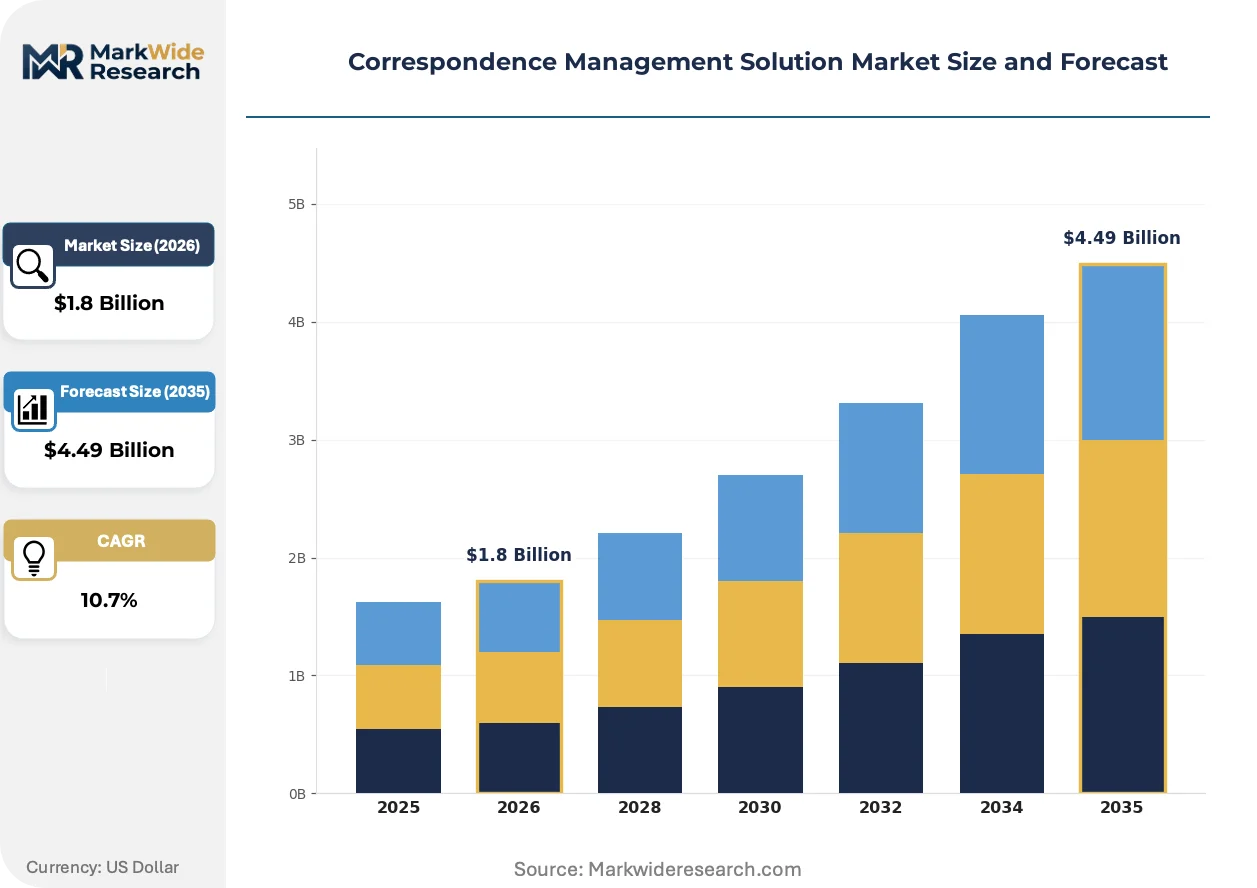
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Email Management, Letter Sorting, Document Tracking, Case Management Technology: Cloud-Based, On-Premise, Mobile Application, AI Integration End User: Government Agencies, Corporations, Educational Institutions, Non-Profits Deployment: Public Cloud, Private Cloud, Hybrid, Local Server |
| Companies Covered | SharePoint, Genesys Cloud CX, DocuWare, Zendesk, NICE CXone, M-Files, Box, Twilio Flex, Laserfiche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Correspondence Management Solution Market Strategic Shifts
Cloud abandonment of capital-intensive hardware refresh cycles is converging with AI integration layers to reshape competitive positioning around operational expenditure models and automated governance capabilities.
Intelligent document processing is unifying capture, classification, and routing functions previously handled by separate point solutions. Financial services institutions are deploying these platforms at enterprise scale to compress compliance review cycles. The technology is unifying metadata extraction with real-time retention policy enforcement, collapsing the architectural separation between operational correspondence and long-term archive management.
The EU AI Act mandates explainability logs for automated correspondence handling, creating binding documentation requirements for algorithmic routing decisions. Financial institutions must now maintain surveillance-grade audit trails that capture human oversight interventions. The SEC's retention and surveillance rules are driving convergent procurement specifications that favor platforms with pre-built regulatory reporting modules.
Asynchronous messaging preferences are displacing synchronous voice channels as the primary customer touchpoint. Enterprise buyers now prioritize platforms orchestrating email, social, and messaging channels through unified ticketing DNA rather than siloed point solutions. This behavioral pivot is most visible in technology and retail verticals where response velocity directly correlates with retention metrics.
Correspondence Management Solution Market Segmentation
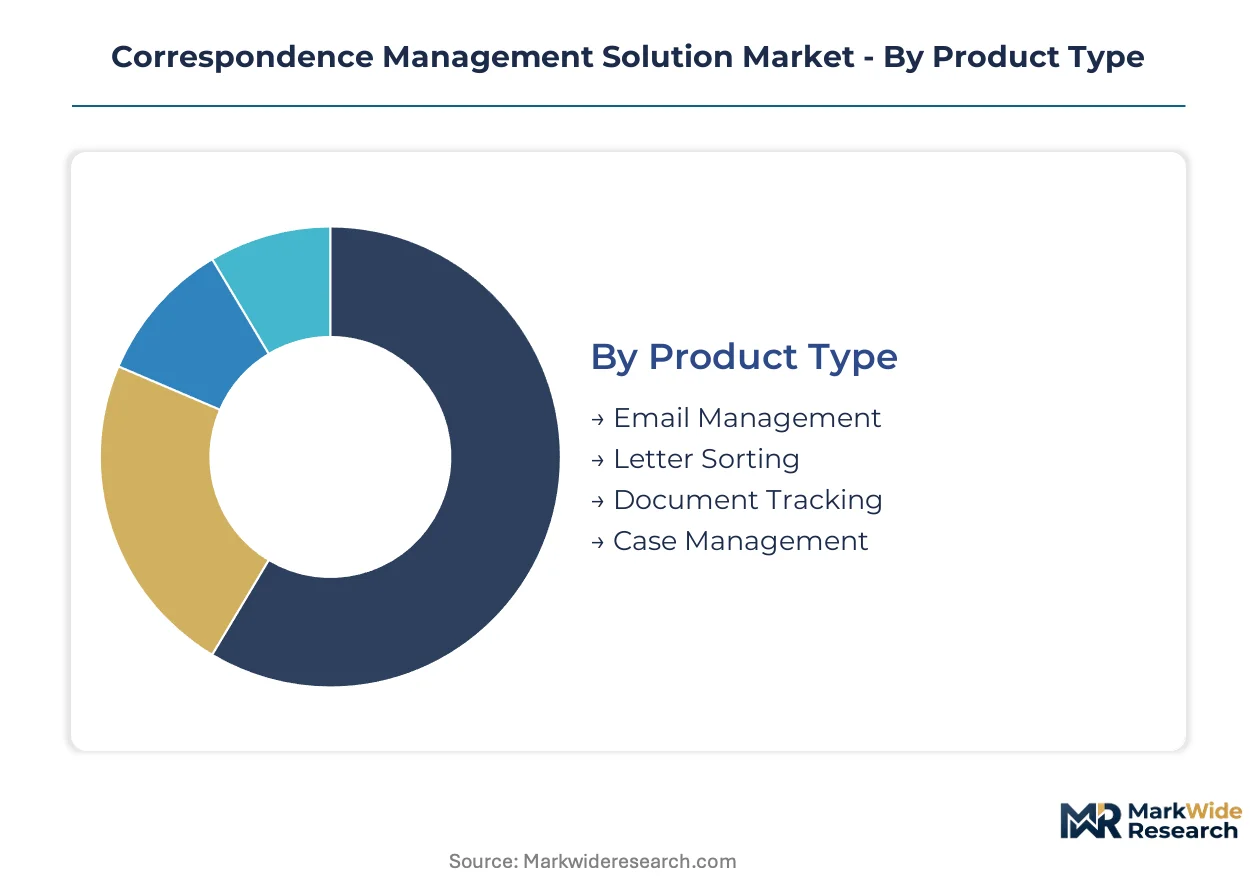
Correspondence management solutions fragment across four structural dimensions that determine procurement priorities and vendor positioning. Buyers select architectures based on regulatory exposure, integration complexity, and operational expenditure preferences rather than feature checklists alone.
Product Type:
Organizations prioritize product types based on communication volume intensity and workflow complexity rather than channel preference alone.
- Email Management:Processes high-throughput digital correspondence with automated routing rules and retention policy enforcement. Financial services institutions in Germany and the United States deploy these systems to satisfy SEC surveillance requirements and GDPR audit trail mandates. Volume concentration reflects legacy infrastructure dependence and regulatory documentation burdens.
- Case Management:Orchestrates multi-step correspondence workflows with decision tracking and escalation protocols. Legal departments and public-sector agencies pay premium pricing for implementations that map human oversight touchpoints to EU AI Act explainability requirements. Workflow complexity justifies higher-margin deployments compared to commoditized channel management.
- Letter Sorting:Automates physical mail digitization through optical character recognition and barcode indexing.
- Document Tracking:Provides chain-of-custody verification for sensitive correspondence requiring non-repudiation guarantees.
Email management leads volumes today; case management is gaining share fastest.
Technology:
Technology selection hinges on data sovereignty exposure and capital expenditure constraints rather than performance specifications.
- Cloud-Based:Delivers subscription-priced correspondence infrastructure with elastic scaling and automated compliance updates. Enterprises across France and the Netherlands abandon hardware refresh cycles to convert capital expenditure into operational spending. GDPR Article 17 granular deletion capabilities are accelerating migration from legacy archive economics.
- AI Integration:Embeds natural language processing for sentiment classification, automated routing decisions, and anomaly detection. Healthcare systems deploy these layers to compress patient response resolution times while maintaining explainability logs for regulatory examination. The capability represents the fastest-expanding technology investment across surveyed procurement budgets.
- On-Premise:Maintains physical infrastructure control for organizations with strict data residency requirements.
- Mobile Application:Extends correspondence access to field personnel and remote decision-makers.
Cloud-based deployments dominate new procurement; AI integration commands the steepest expansion trajectory.
End User:
End-user categories diverge sharply in compliance stringency and integration depth requirements.
- Government Agencies:Mandate ISO 27001 certification and sovereign data residency for all correspondence platforms. Federal digitization initiatives in Germany favor locally deployed infrastructure with granular audit capabilities. Procurement specifications exclude vendors lacking pre-built regulatory reporting modules.
- Corporations:Span regulated financial institutions to technology firms with asynchronous messaging preferences. Cross-border data flow requirements fragment deployment strategies between centralized platforms and federated national instances. Buyers prioritize unified ticketing DNA over siloed point solutions.
- Educational Institutions:Manage student communications and administrative correspondence with limited IT resources.
- Non-Profits:Operate donor correspondence and grant documentation on constrained procurement budgets.
Corporations account for the largest procurement volume; government agencies are expanding fastest.
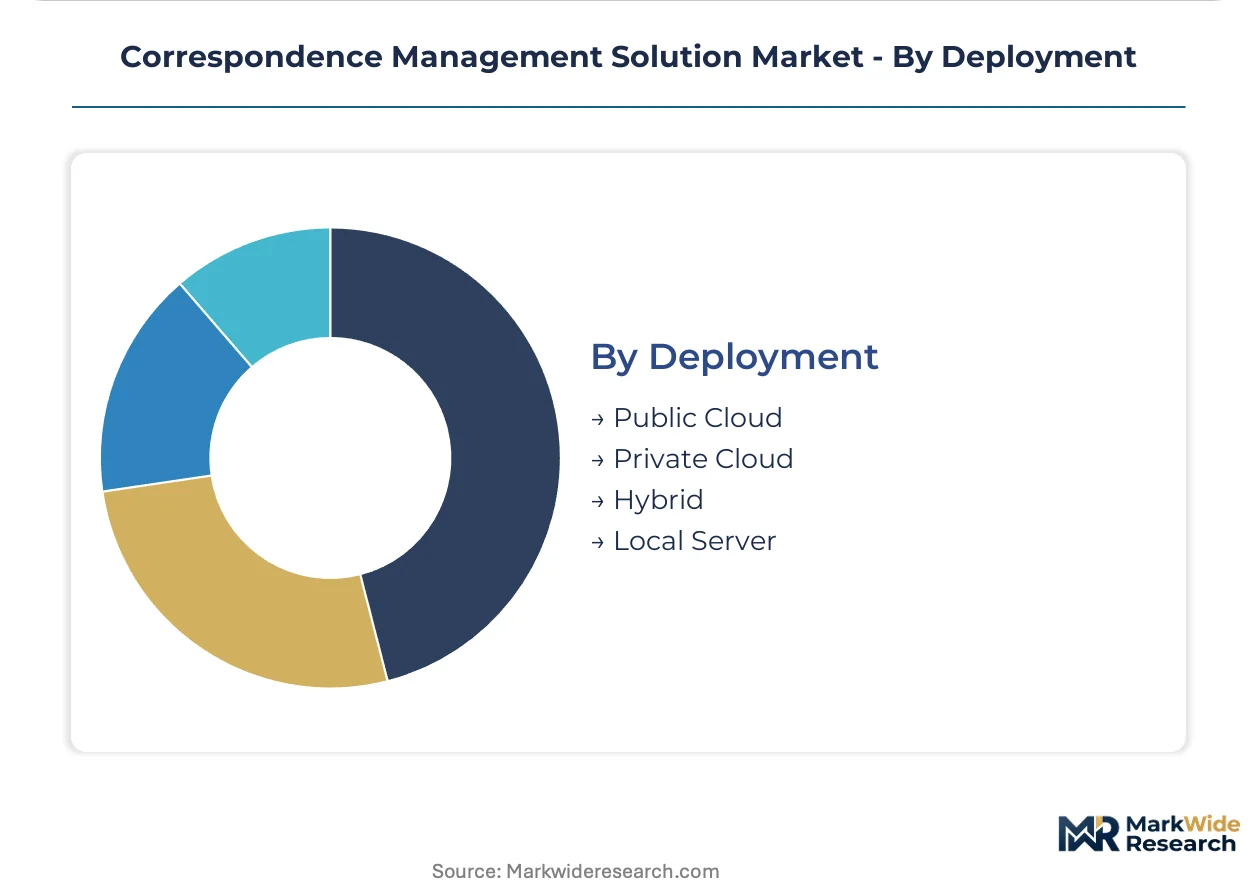
Deployment:
Deployment architecture selection reflects jurisdictional data sovereignty fragmentation and risk tolerance.
- Private Cloud:Delivers dedicated infrastructure with tenant-isolated security controls and geographic data pinning. German enterprises select this model to satisfy federal data sovereignty rules while avoiding capital-intensive on-premise hardware. The architecture bridges compliance requirements with operational expenditure preferences.
- Hybrid:Combines public cloud elasticity with on-premise retention for sensitive correspondence categories. Financial institutions deploy this model to maintain surveillance-grade audit trails for SEC-regulated communications while leveraging cloud processing for routine operations. Architectural complexity raises implementation timelines and professional services dependency.
- Public Cloud:Offers lowest-cost entry with shared infrastructure and standardized compliance certifications.
- Local Server:Preserves complete physical control for organizations with air-gapped security requirements.
Private cloud leads procurement in regulated verticals; hybrid deployments are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep engineering talent pools in enterprise software hubs anchor geographic demand concentration for correspondence management platforms. Regulatory divergence across jurisdictions fragments deployment architectures and procurement specifications.
Germany
Federal digitization mandates and strict data sovereignty requirements drive procurement of locally deployed correspondence infrastructure. The EU AI Act and GDPR jointly enforce explainability logs and granular deletion capabilities across automated systems. Bavaria's Munich-Frankfurt corridor hosts concentrated financial services procurement, with institutions demanding sovereign cloud or on-premise retention for surveillance-grade audit trails.
United States
SEC retention and surveillance rules compress procurement cycles for financial sector correspondence platforms with pre-built regulatory reporting modules. HIPAA enforcement accelerates healthcare system adoption of auditable patient communication systems. New York and Chicago financial clusters deploy enterprise-scale platforms to satisfy cross-border data flow requirements while maintaining surveillance infrastructure.
France
CNIL enforcement of GDPR Article 17 right-to-erasure mandates decouples storage economics from legacy archive models. The country's national data protection authority scrutinizes automated decision-making contexts in correspondence handling. Paris-based banking and insurance headquarters favor compliant platforms with embedded granular deletion capabilities and French-language NLP layers.
United Kingdom
Post-Brexit data adequacy negotiations fragment cloud deployment strategies between EU-aligned and independent retention architectures. Financial services regulators maintain surveillance requirements convergent with SEC specifications. London's concentrated fintech and insurance clusters drive demand for hybrid deployments combining public cloud elasticity with on-premise retention for sensitive categories.
Netherlands
Enterprise abandonment of hardware refresh cycles accelerates cloud-based correspondence adoption across Amsterdam-Rotterdam logistics and financial hubs. GDPR enforcement through the Dutch Data Protection Authority mandates granular audit capabilities. The Randstad's dense corporate headquarters concentration favors subscription-priced platforms with automated compliance updates and elastic scaling.
Correspondence Management Solution Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Enterprise content management incumbents leverage deep stack integration to defend channel control in regulated verticals. Three archetypes dominate: cloud-native platform builders, legacy ECM extenders, and contact-center-originated orchestration specialists. Competitive moves concentrate on M&A for AI capability acquisition and strategic partnerships for sovereign cloud localization.
Within the legacy ECM extender tier, DocuWare and M-Files exemplify European-origin specialists leveraging deep integration with existing enterprise content stacks to sustain positioning in compliance-intensive industries. NICE CXone anchors the contact-center-originated archetype, representing vendors that map full correspondence lifecycles for financial services surveillance requirements. These three occupy positions that reflect divergent strategic bets on integration depth versus channel breadth.
| Leading Market Players |
|---|
| SharePoint |
| Genesys Cloud CX |
| DocuWare |
| Zendesk |
| NICE CXone |
| M-Files |
| Box |
| Twilio Flex |
| Laserfiche |
| Others |
Value Chain & Pricing Dynamics
Professional services engineering costs cascade through correspondence management solution pricing tiers, with German sovereign cloud deployments absorbing premium labor inputs while standardized SaaS offerings compress implementation margins through automated provisioning pipelines.
Pricing Analysis
Bundled implementation services separate premium case management deployments from unbundled email management subscriptions. Three-tier pricing structure across enterprise, mid-market, and entry-level segments reflects ISO 27001 certification requirements and GDPR granular deletion capabilities. Pricing pressure stems from cloud-native entrants undercutting legacy ECM extenders on professional services dependency. Government agencies exhibit lowest price sensitivity due to sovereign data residency mandates; mid-market corporations in the Netherlands show highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with hyperscaler infrastructure concentrated in Ireland, Germany, and the Netherlands for EU data residency compliance. Cloud compute instances, optical character recognition engines, and natural language processing APIs anchor upstream dependencies. Tariff exposure on semiconductor components threatens hardware refresh timelines for hybrid deployment architectures. Distribution runs through direct enterprise sales teams with systems integrator channel partners handling complex ECM stack integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Correspondence management solutions represent a late-cycle quality story as procurement committees prioritize explainability audit trails over feature breadth, elevating vendors with pre-built EU AI Act compliance modules.
For Market Incumbents: Anticipate displacement by cloud-native platform builders through accelerated AI capability acquisition and sovereign cloud localization partnerships. Reinforce channel control by deepening integration with European enterprise content management stacks and embedding automated deletion architectures that satisfy GDPR Article 17 enforcement timelines. For New Entrants and Emerging Players: The EU AI Act in Germany opens a window for compliant, locally deployed correspondence infrastructure targeting Bavarian financial services clusters. Penetrate the case management premium segment in legal and public-sector verticals where workflow complexity justifies higher-margin implementations. Lead with AI-powered interaction analytics that map full correspondence lifecycles for surveillance-grade audit trails. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 27001 certification barriers exclude smaller vendors from government and multinational procurement pools. Position for five-to-ten year horizon around vendors with pre-built regulatory reporting modules and federated national cloud instances. Monitor GDPR enforcement velocity through CNIL and Dutch Data Protection Authority penalty announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Localization | Establishes compliant data residency for German federal procurement specifications. |
| AI Capability Acquisition | Accelerates natural language processing deployment for automated routing decisions. |
| ECM Stack Integration Partnership | Secures channel control through deep embedding with legacy enterprise content systems. |
| Regulatory Reporting Module Development | Captures financial services procurement with pre-built SEC surveillance compliance. |
| Granular Deletion Architecture Investment | Addresses GDPR Article 17 enforcement decoupling storage from archive economics. |
Study Parameters
Direct dialogue with correspondence management vendors, healthcare IT procurement officers, financial services compliance directors, and systems integration specialists combined with secondary validation against SEC regulatory filings, GDPR enforcement databases, Dutch Data Protection Authority decisions, and hyperscaler sovereign cloud announcements. Bottom-up deployment volume estimates triangulated against top-down market sizing.
Segmented outputs across product type, technology layer, end-user vertical, and deployment architecture feed into growth trajectory modeling across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating healthcare digitization mandate timelines and EU AI Act implementation phases. Forecast inputs include patient correspondence volume expansion rates and financial services surveillance infrastructure refresh cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GDPR penalty enforcement or delayed federal digitization procurement approvals. Assumptions reflect current regulatory trajectories and sovereign cloud availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Voice Remote Control Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Inventory Management Market
Digital Solutions
Digital Twin Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
UAE ICT Market
Digital Solutions
Customer-To-Customer (C2C) Community Market
Digital Solutions
Event Apps Market
Digital Solutions
APAC Digital Signage Market
Digital Solutions
Europe Digital Marketing Software Market