
 AQI App Market | 2026-2036
AQI App Market Size, Share, and Industry Trends Forecast 2026-2036
AQI App Market Insights
Sensor manufacturers in South Korea are repositioning their hardware outputs toward API-first delivery models that feed directly into mobile platforms. IQAir leverages its proprietary monitoring station network to sustain data accuracy premiums across Asian metropolitan markets. BreezoMeter anchors its competitive stance through machine-learning dispersion models that compete with government-grade forecasting systems. Plume Labs specializes in street-level pollution mapping, differentiating its output for cyclist and pedestrian navigation segments.
An AQI app is a software application that aggregates particulate matter, ozone, nitrogen dioxide, and volatile organic compound readings from distributed sensor networks, presenting actionable air quality indices through standardized color-coded scales. These platforms integrate real-time data streams via REST APIs and process them through interpolation algorithms to deliver location-specific health guidance for outdoor activity planning. Mobile apps dominate current deployment volumes, though IoT integration represents the fastest-expanding architecture as wearable manufacturers embed air quality alerts into fitness bands and smartwatches. Subscription monetization captures the most concentrated margin pool among health professionals and environmental agencies seeking historical analytics and predictive modeling tools.
The EPA enforces National Ambient Air Quality Standards that mandate public reporting protocols, directly shaping the data infrastructure requirements for apps serving US jurisdictions. China's MEE operates the national air quality monitoring network whose GB-standardized outputs populate domestic platforms, while India's BIS certification for PM2.5 and PM10 sensors governs which data sources apps may legally reference. Stakeholders must monitor evolving cross-border data portability rules as satellite imagery and crowdsourced inputs challenge traditional government-sensor hierarchies.
Market Dynamics
Sensor-to-API data pipelines are consolidating around government-certified monitoring networks, forcing app developers to secure regulatory data licenses rather than rely on crowdsourced inputs. This shift compresses the competitive moat for platforms lacking direct MEE or EPA data partnerships.
Growth Catalysts
- EPA NAAQS tightening:Stricter ozone and particulate thresholds expand mandatory public reporting infrastructure, creating captive data feeds for US-facing platforms.
- Wearable integration:Fitness band manufacturers embed real-time AQI alerts, extending app utility beyond smartphones into continuous exposure monitoring.
- Delhi's pollution emergencies:Persistent air quality crises drive citizen app downloads and municipal procurement of public alert systems.
Market Restraints
- Sensor hardware concentration:South Korean and Chinese component suppliers control MEMS particulate sensor production, exposing apps to single-source supply risk.
- Calibration cost volatility:Reference-grade monitor maintenance and field validation cycles consume disproportionate operational budgets for accuracy-dependent platforms.
- Cross-border data friction:China's GB standard outputs and India's BIS certification requirements create incompatible data formats that fragment regional app architectures.
Strategic Opportunities
- Indonesia's underpenetrated outdoor worker base:Smartphone penetration among agricultural and logistics laborers in Jakarta and Surabaya exceeds current app coverage.
- Subscription analytics for environmental agencies:Historical pollution modeling and predictive dispersion tools command premium pricing from institutional buyers.
- Satellite-ground sensor fusion:European Space Agency Sentinel data combined with ground networks enables rural coverage without dense hardware deployment.
Industry Challenges
- Interpolation algorithm talent scarcity:Machine learning engineers with atmospheric dispersion expertise command premium compensation, constraining mid-tier platform development.
- BIS certification timelines:Indian PM2.5 sensor approval cycles delay app launches by months, compressing first-mover advantages.
- Legacy government API integration:Municipal data portals built on decade-old protocols require costly middleware adaptation for real-time mobile delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AQI App Market |
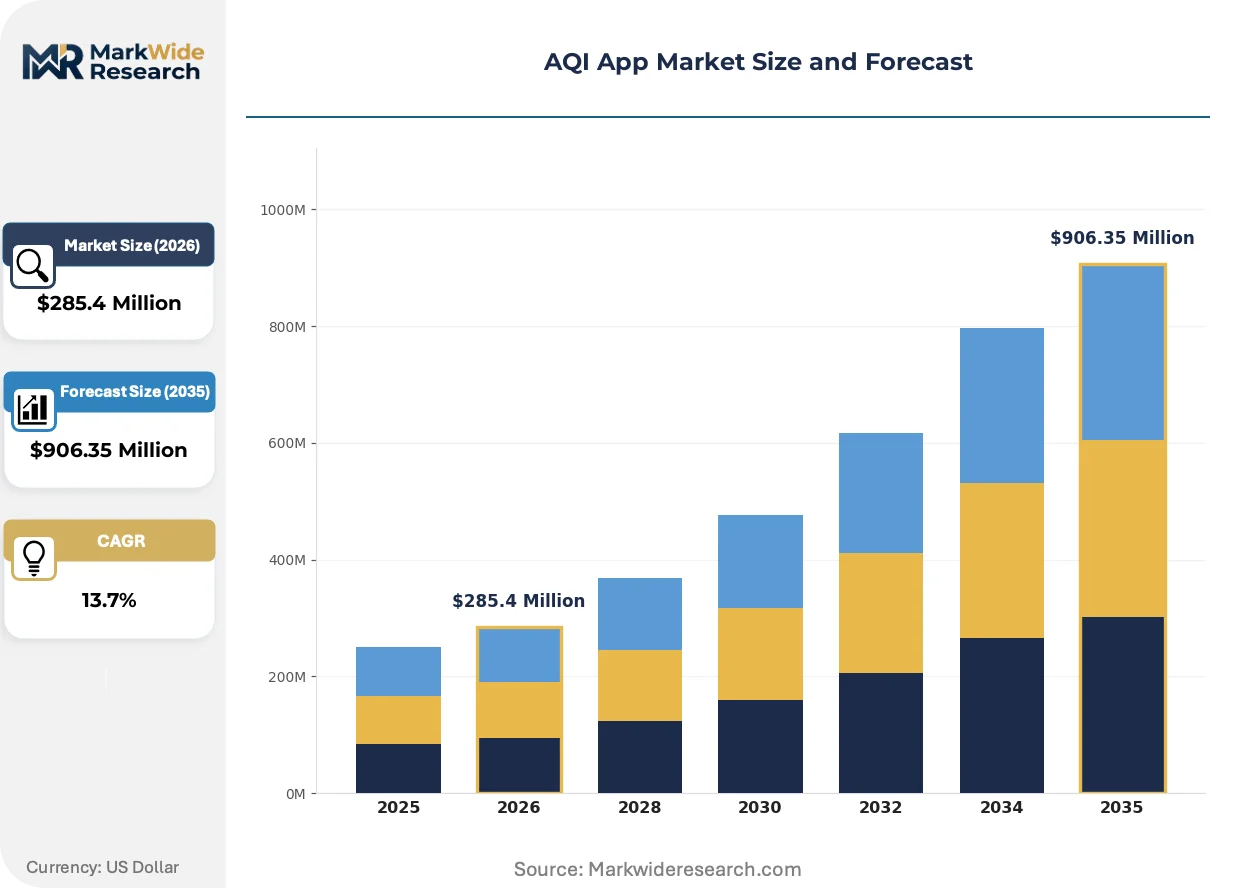
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Mobile Apps, Web Apps, Desktop Software, IoT Integration Target User: General Public, Health Professionals, Environmental Agencies, Researchers Data Source: Government Sensors, Private Stations, Crowdsourced Data, Satellite Imagery Monetization Model: Subscription, Freemium, One-Time Purchase, Ad-Supported |
| Companies Covered | IQAir, BreezoMeter, Air Matters, Awair, Blueair, Airthings, Plume Labs, Sonoma Technology (eSIMS), AirVisual, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AQI App Market Trends and Innovations
Edge computing architectures are pushing AQI processing from centralized cloud servers toward distributed sensor nodes, reducing latency for hyperlocal alerts. This infrastructure shift enables street-level resolution that static monitoring networks cannot achieve.
Low-power wide-area network (LPWAN) modules are modularizing how remote sensors transmit particulate readings to mobile backends. Agricultural cooperatives in Vietnam and plantation operators in Malaysia deploy these units for worker safety compliance without cellular infrastructure. The technology is modularizing the cost structure of rural air quality networks, compressing hardware deployment expenses by eliminating gateway dependencies.
China's MEE mandates real-time data publication through standardized GB/T interfaces, forcing domestic apps to rebuild ingestion pipelines around official feeds. Foreign platforms face exclusion from this data architecture unless they establish local hosting partnerships. The policy most affects multinational apps serving cross-border travelers, which must maintain parallel data stacks for Chinese and non-Chinese jurisdictions.
Outdoor activity planners now demand predictive rather than reactive air quality guidance, shifting platform value toward forecast reliability. Cycling clubs in Seoul and running groups in Bangkok subscribe to premium tiers that bundle multi-hour pollution trajectory modeling. Southeast Asian fitness communities exhibit the strongest willingness to pay for anticipatory health recommendations over current-condition reporting.
AQI App Market Segmentation
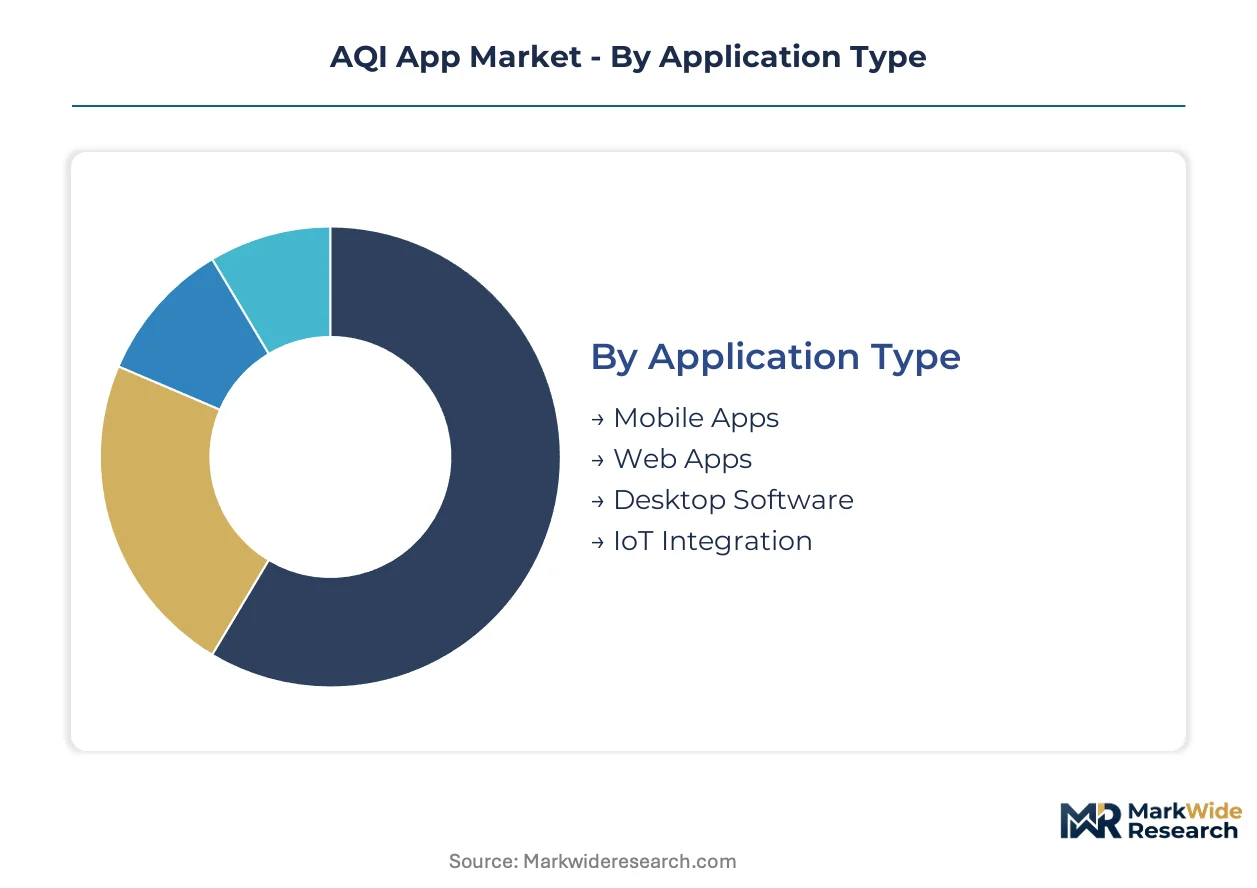
AQI app architectures fragment across four distinct dimensions, each imposing unique certification burdens and data licensing requirements. Application type determines hardware integration depth, while monetization model dictates margin sustainability against sensor calibration costs.
Application Type:
Certification requirements diverge sharply: IoT Integration demands FCC and CE marking for wearable hardware, while Mobile Apps face lighter app store compliance but heavier EPA data partnership vetting.
- Mobile Apps:Native iOS and Android platforms dominate current deployment, processing REST API feeds through interpolation engines for location-specific alerts. Demand concentrates in Delhi, Mumbai, and Jakarta where smartphone penetration among outdoor workers outpaces dedicated hardware ownership. BIS certification for referenced sensor data delays Indian launches by regulatory review cycles.
- IoT Integration:Embedded firmware in fitness bands and smartwatches enables continuous exposure monitoring through low-power particulate sensors. Samsung and Garmin hardware partnerships in Seoul and Busan drive this segment's expansion. CE marking and FCC Part 15 compliance add hardware certification layers absent from pure software deployments.
- Web Apps:Browser-based dashboards serve institutional subscribers requiring multi-device access without app store distribution friction.
- Desktop Software:Native Windows and macOS applications target environmental agencies performing batch historical analysis and custom dispersion modeling.
Leading the category by volume: Mobile Apps. Growing fastest: IoT Integration.
Target User:
Cost tier stratification separates mass-market freemium offerings from premium institutional contracts, with subscription pricing scaling directly against data granularity and forecast horizon depth.
- General Public:Free-tier consumers drive download volume through color-coded AQI scales and basic health activity recommendations. This segment monetizes through ad impressions and freemium upsells, with highest concentration in Southeast Asian metropolitan areas experiencing recurrent pollution emergencies.
- Environmental Agencies:Municipal and national regulators purchase historical analytics and predictive dispersion tools for policy planning. China's MEE and India's Central Pollution Control Board procure multi-year licenses for GB-standard and BIS-certified data integration. Contract values scale with sensor network density and API call volume.
- Health Professionals:Pulmonologists and occupational health officers subscribe to patient exposure tracking and alert systems for respiratory disease management.
- Researchers:Academic institutions access bulk data exports and custom interpolation parameters for epidemiological and atmospheric science studies.
Dominating revenue per user: Environmental Agencies. Expanding most quickly: Health Professionals.
Data Source:
Supply concentration in certified monitoring networks is displacing crowdsourced architectures, as EPA and MEE licensing requirements harden against uncertified sensor inputs.
- Government Sensors:EPA-maintained stations in the US and MEE networks in China provide reference-grade PM2.5, ozone, and nitrogen dioxide readings. These feeds command data licensing fees but eliminate calibration uncertainty. Apps serving cross-border travelers must maintain parallel stacks for incompatible GB and EPA output formats.
- Satellite Imagery:European Space Agency Sentinel data enables rural coverage without ground hardware deployment. Fusion algorithms combine orbital aerosol optical depth with sparse sensor networks for agricultural and remote region applications. This source gains traction where LPWAN infrastructure remains uneconomical.
- Private Stations:IQAir and BreezoMeter proprietary networks supplement official feeds in data-sparse metropolitan peripheries.
- Crowdsourced Data:Consumer-grade sensor aggregations face declining platform acceptance as BIS and EPA certification mandates tighten.
Highest reliability premium: Government Sensors. Gaining share fastest: Satellite Imagery.
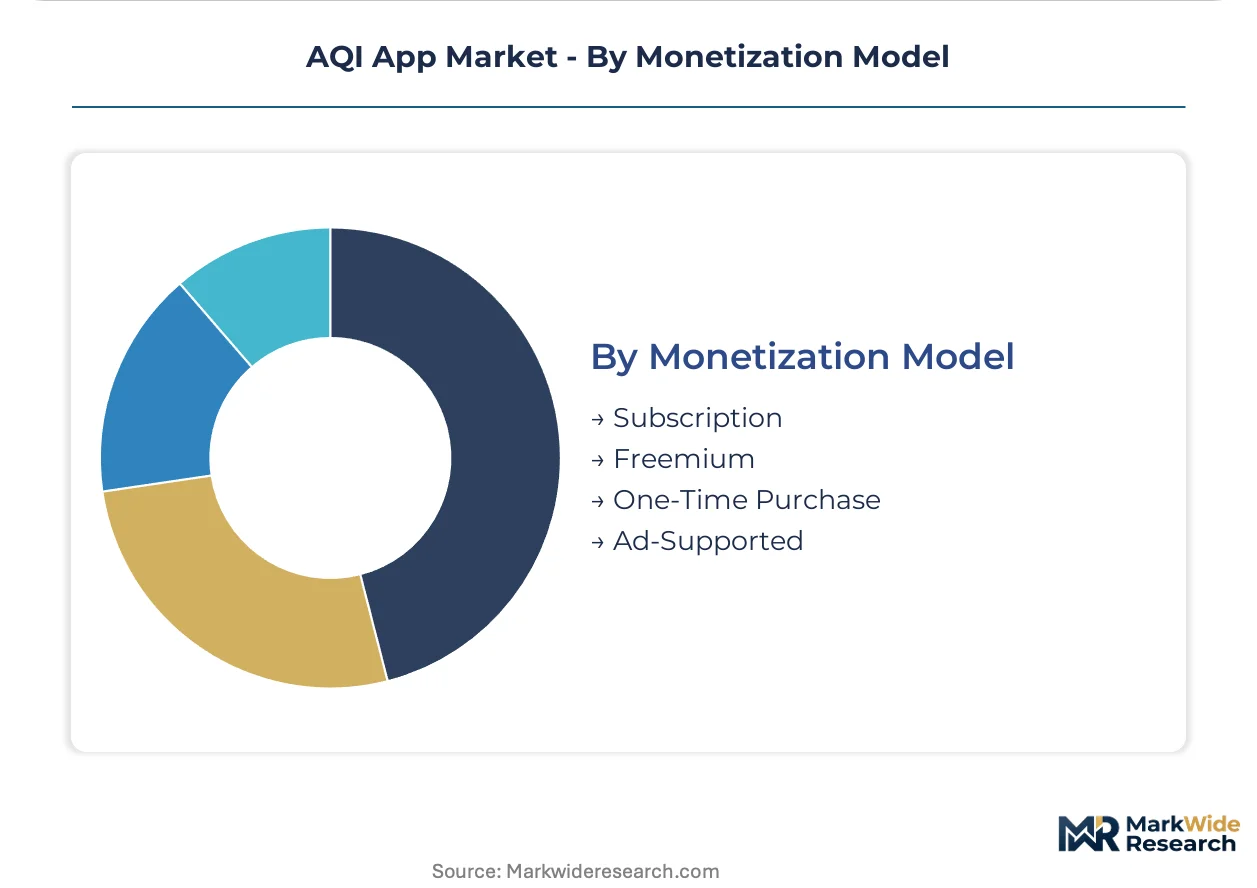
Monetization Model:
Margin structure varies by customer lifetime value, with institutional subscriptions capturing concentrated profitability against high acquisition costs.
- Subscription:Recurring revenue from environmental agencies and health professionals funds sensor network expansion and machine learning talent acquisition. Annual contracts bundle historical data, predictive modeling, and API access tiers. This model sustains the highest customer lifetime values in the analysis.
- Freemium:Basic AQI displays convert a minority of general public users to paid tiers featuring pollen counts, wildfire smoke tracking, and multi-day forecasts. Conversion rates concentrate in pollution-alert seasons across Delhi, Beijing, and Bangkok.
- Ad-Supported:Impression-based revenue serves price-sensitive mass markets with minimal data infrastructure investment.
- One-Time Purchase:Perpetual licenses persist in desktop software for legacy institutional procurement systems.
Leading the category by revenue concentration: Subscription. Steepest expansion trajectory: Freemium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor manufacturing clusters in Seoul and Shenzhen anchor hardware supply for AQI platforms, while data licensing partnerships concentrate in regulatory capitals where EPA, MEE, and BIS standards govern platform legitimacy.
United States
EPA's tightening National Ambient Air Quality Standards expand mandatory public reporting infrastructure, creating captive data feeds for domestic platforms. The agency's ozone and particulate thresholds force municipal procurement of real-time alert systems. Los Angeles and Houston metropolitan areas drive highest per-capita app engagement during wildfire seasons.
China
MEE mandates real-time data publication through standardized GB/T interfaces, forcing domestic apps to rebuild ingestion pipelines around official feeds. Foreign platforms face exclusion without local hosting partnerships. Beijing and Shanghai municipal networks provide reference-grade PM2.5 readings that populate domestic platforms.
India
BIS certification requirements for PM2.5 and PM10 sensors delay app launches by regulatory review cycles, compressing first-mover advantages. Delhi's persistent pollution emergencies drive citizen-level downloads and municipal procurement of public alert systems. Mumbai and Bengaluru smartphone penetration among outdoor workers outpaces dedicated hardware ownership.
South Korea
MEMS particulate sensor production concentrates in Seoul-Incheon manufacturing corridors, exposing apps to single-source supply risk. Samsung and Garmin hardware partnerships drive IoT integration segment expansion. Busan and Daegu cycling clubs exhibit strongest willingness to pay for anticipatory health recommendations.
Indonesia
Smartphone penetration among agricultural and logistics laborers in Jakarta and Surabaya exceeds current app coverage, creating underpenetrated demand pools. LPWAN infrastructure enables plantation operator deployments without cellular dependency. Vietnam and Malaysia agricultural cooperatives deploy modular sensor units for worker safety compliance.
AQI App Market Competitive Landscape
Global majors compete with regional champions across data licensing partnerships and sensor network density, creating tiered competitive dynamics. The vendor base stratifies between proprietary monitoring station operators, machine-learning dispersion specialists, and API-first platform integrators. Two archetypes dominate: hardware-origin platforms with captive sensor networks, and software-native platforms with algorithmic interpolation capabilities. Dominant competitive moves include M&A for sensor network expansion and strategic partnerships for regulatory data access.
Within the hardware-origin tier, IQAir and AirVisual represent platforms leveraging proprietary monitoring infrastructure to sustain data accuracy premiums. BreezoMeter exemplifies the algorithmic archetype, anchoring competitive positioning through machine-learning dispersion models. These three companies occupy positions across the premium data licensing spectrum, with geographic footprints spanning Asian metropolitan markets where government-certified feeds command highest reliability premiums.
| Leading Market Players |
|---|
| IQAir |
| BreezoMeter |
| Air Matters |
| Awair |
| Blueair |
| Airthings |
| Plume Labs |
| Sonoma Technology (eSIMS) |
| AirVisual |
| Others |
Pricing and Supply Chain Analysis
API-first platform developers backed by venture financing dominate the mid-market tier, compressing margins for sensor-dependent competitors while sustaining pricing discipline through recurring subscription contracts. Their capital efficiency allows aggressive freemium-to-premium conversion investments that hardware-origin incumbents cannot match without diluting sensor calibration budgets.
Pricing Analysis
Warranty and field validation service bundling separates premium subscription tiers from stripped-down API access licenses in the environmental agency segment. Three-tier pricing structure across premium, standard, and economy levels correlates directly with forecast horizon depth and historical data granularity, with BIS-certified sensor integration commanding reliability premiums. Cost compression in the ad-supported tier intensifies as smartphone penetration saturates Southeast Asian metropolitan markets. General public users exhibit highest price sensitivity, while municipal environmental agencies demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Freight cost volatility from Seoul-Incheon MEMS sensor clusters to Jakarta and Surabaya assembly points compresses margin buffers for hardware-integrated deployments. Component sourcing draws from South Korean particulate sensor foundries, Chinese LPWAN module manufacturers, and Taiwanese semiconductor packaging facilities. Single-source vulnerability concentrates in reference-grade monitor calibration equipment anchored in German and Swiss metrology suppliers. Distribution runs through direct API licensing to platform developers rather than traditional hardware channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EPA and MEE data licensing requirements force weaker platforms without regulatory partnerships toward distressed exits.
For Market Incumbents: Anchor defensive positioning through exclusive MEE and EPA data partnership renewals that crowd out mid-tier competitors lacking regulatory access. Deepen backward integration into sensor network ownership in Delhi and Beijing to eliminate third-party calibration cost volatility. Machine-learning dispersion talent acquisition in Seoul and Bangalore represents the critical capability lever against algorithmic challengers. For New Entrants and Emerging Players: Satellite-ground sensor fusion technology offers a technology-first wedge into Indonesian agricultural and Malaysian plantation segments where LPWAN infrastructure bypasses cellular dependency. Target Jakarta and Surabaya outdoor worker bases with freemium mobile deployments ahead of hardware saturation. Partner with European Space Agency data aggregators for rural coverage without dense ground sensor capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor API-first specialists with existing BIS certification pipelines in India and GB/T integration capabilities in China. Five-to-ten year viability hinges on regulatory data access moats rather than algorithmic differentiation alone. Watch MEE foreign platform exclusion enforcement as the critical inflection signal for multinational app viability.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Regulatory Data Partnership | EPA and MEE licensing agreements create captive feed infrastructure that competitors cannot replicate. |
| Sensor Network Acquisition | Proprietary monitoring station ownership in Delhi and Beijing eliminates third-party calibration cost exposure. |
| Machine Learning Talent Acquisition | Atmospheric dispersion engineers in Seoul and Bangalore anchor algorithmic forecasting differentiation. |
| LPWAN Infrastructure Deployment | Modular sensor units in Indonesian plantations enable rural coverage without cellular gateway dependencies. |
| Satellite Data Integration | European Space Agency Sentinel fusion extends platform utility to agricultural cooperatives in data-sparse regions. |
Research Methodology
Multi-period observation of EPA NAAQS enforcement patterns, MEE GB/T interface mandates, and BIS certification timelines anchored the trend analysis, supplemented by interviews with platform engineering leads, environmental agency procurement officers, sensor hardware manufacturers, and mobile app product managers. Secondary validation drew from EPA regulatory filings, MEE data publication standards, BIS certification registries, and European Space Agency satellite mission disclosures. Bottom-up sensor network deployment tracking and top-down smartphone penetration data were triangulated against subscription revenue estimates.
Input-output matrices modeled relationships between regulatory enforcement intensity, sensor network density, and platform adoption rates across the projection horizon. Segmentation dimensions included application type, target user archetype, data source certification tier, and monetization model structure. CAGRs were derived from regression analysis correlating pollution emergency frequency with citizen download velocity and municipal procurement cycles. Forecast inputs incorporated Delhi pollution crisis patterns and Jakarta smartphone penetration trajectories.
Several conditions sit outside the modeled scope, including potential MEE foreign platform exclusion enforcement shifts and unforeseen BIS certification timeline compressions. Forecasts reflect documented assumptions about regulatory data access continuity and sensor hardware cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Molecular Information Systems Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Graph Technology Market
Digital Solutions
Australia Digital Marketing Software Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Global Freelance Platforms Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Product Information Management Market
Digital Solutions
Data Governance Market
Digital Solutions
Digital Signature Market