
 Precision Agriculture Software Market | 2026-2036
Precision Agriculture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Agriculture Software Market Insights
Premium subscription tiers built on AI-driven prescription maps and autonomous machinery integration are decoupling from commodity farm management tools that handle basic record-keeping. Deere & Company leverages its installed base of connected equipment to anchor recurring software revenue through Operations Center subscriptions. Trimble Inc. competes through specialized guidance and correction services that dominate high-accuracy field operations. AGCO Corporation differentiates via Fuse platform openness, allowing third-party data flows that sustain farmer loyalty across mixed fleets.
Precision agriculture software encompasses digital platforms that collect, process, and act upon spatially referenced farm data using GPS coordinates, sensor networks, and algorithmic models to optimize input application and harvest logistics. These systems integrate telemetry from tractors, drones, and soil probes with cloud-based analytics to generate machine-executable instructions that reduce nitrogen runoff and maximize yield per hectare. Farm management and crop management platforms currently lead deployment, as their integration of financial planning with field-level operations captures the largest margin pools among product categories. IoT and remote sensing technologies are expanding fastest, driven by falling sensor costs and satellite imagery resolution improvements that enable sub-field intervention. Cloud deployment dominates new installations, though hybrid architectures persist where cellular connectivity remains intermittent.
The EPA enforces nutrient management standards under the Clean Water Act that pressure farms toward documented input tracking, while the USDA's conservation programs incentivize precision adoption through cost-share arrangements. State-level regulations in Iowa and Illinois now require certified nutrient management plans that software platforms increasingly automate for compliance filing. Stakeholders must monitor whether emerging carbon intensity scoring for agricultural commodities creates premium access for farms with verifiable precision agriculture data trails.
Market Dynamics
Consolidation of farmland into professional management entities across the US Midwest is compressing procurement cycles and forcing software vendors to demonstrate measurable ROI on input reduction and yield optimization within single growing seasons.
Growth Catalysts
- USDA Conservation Programs:Cost-share arrangements under EQIP and CSP offset platform subscription costs for farms implementing variable-rate nutrient application. Participation thresholds have tightened, favoring integrated software suites over point solutions.
- Carbon Credit Verification:Emerging protocols from the Verified Carbon Standard and Climate Action Reserve require auditable field-level data trails that precision agriculture platforms generate automatically. Early adopters in the Corn Belt are securing premium access to offtake agreements.
- Sensor Cost Collapse:MEMS-based soil moisture probes and multispectral cameras have fallen below price points that enable sub-field resolution at commercial scale. Deployment density per hectare is tripling in Iowa and Illinois row-crop operations.
Market Restraints
- Cellular Connectivity Gaps:Rural broadband deserts in Nebraska and Kansas force hybrid architectures that raise total cost of ownership. Satellite backhaul adds latency that degrades real-time machinery coordination.
- Data Interoperability Friction:Proprietary telemetry formats from major equipment manufacturers lock farm records into walled gardens. Third-party platform migration requires manual CSV exports that lose spatial reference integrity.
- Specialized Agronomist Scarcity:Interpretation of prescription maps and algorithmic recommendations demands certified crop advisors. The American Society of Agronomy reports credentialing bottlenecks that slow deployment velocity.
Strategic Opportunities
- Autonomous Machinery Integration:Convergence of computer vision and RTK-GPS guidance is electrifying demand for software that orchestrates unmanned planting and spraying fleets. Equipment manufacturers are opening API access to secure platform partnerships.
- State-Level Nutrient Mandates:Iowa's mandatory certified nutrient management plans and Illinois' watershed-specific phosphorus restrictions create compliance automation opportunities. Software vendors embedding filing workflows capture recurring regulatory subscription revenue.
- Specialty Crop Penetration:California almond orchards and Washington apple operations remain underpenetrated relative to Midwest row crops. Drip irrigation integration and pest pressure modeling represent expandable addressable markets.
Industry Challenges
- Legacy System Integration:Farms operating decade-old yield monitors and first-generation GPS units face data format incompatibilities. Middleware development consumes engineering resources that could advance core analytics capabilities.
- Cybersecurity Certification Delays:State agriculture departments are introducing data protection requirements for platforms handling farm financial records. SOC 2 and ISO 27001 compliance timelines stretch 12-18 months for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Agriculture Software Market |
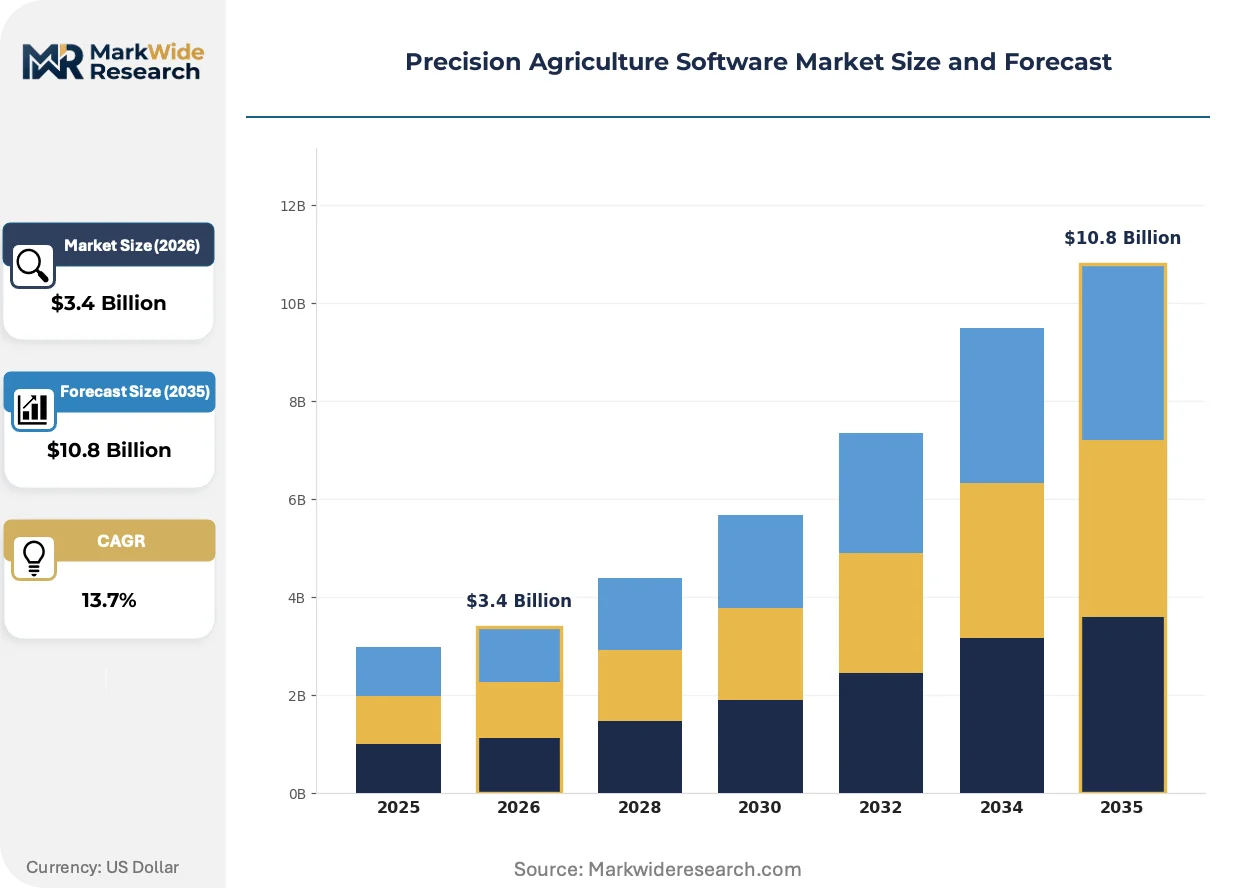
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $10.8 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Management, Soil Monitoring, Farm Management, Yield Prediction Technology: IoT, AI, Machine Learning, Remote Sensing End User: Farmers, Agronomists, Cooperatives, Agricultural Consultants Deployment: Cloud, On-premises, Hybrid, Mobile |
| Companies Covered | Deere & Company, Trimble Inc., AGCO Corporation, CNH Industrial N.V., Topcon Corporation, Kubota Corporation, Corteva Inc., Ag Leader Technology, AgEagle Aerial Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Agriculture Software Market Trends and Innovations
Algorithmic prescription generation is displacing rule-based input recommendations as machine learning models ingest multi-year yield response data. The competitive frontier has shifted from data collection to actionable intelligence delivery.
Edge computing architectures are electrifying field-level decision latency. NVIDIA Jetson modules deployed on planter and sprayer implements now process NDVI imagery locally, eliminating round-trip cloud delays. Professional farm management companies in Indiana and Ohio are specifying edge-capable platforms in RFPs. This compression of feedback loops is enabling sub-acre intervention windows that were previously uneconomical.
EPA enforcement discretion under the Clean Water Act is narrowing as nutrient load Total Maximum Daily Loads tighten in the Chesapeake Bay and Mississippi River watersheds. Farms exceeding discharge thresholds face consent decrees that mandate documented precision agriculture adoption. Corn and soybean operations in Minnesota and Wisconsin are accelerating software procurement to preempt enforcement exposure.
Subscription unbundling is fragmenting buyer relationships that previously consolidated through bundled equipment-software packages. Large-scale operators are separating machinery acquisition from analytics procurement, running competitive tenders for prescription services independent of hardware vendors. This disintermediation is most advanced among professional management companies controlling 10,000+ hectares in the Dakotas, where platform switching costs have fallen below two growing seasons.
Precision Agriculture Software Market Segmentation
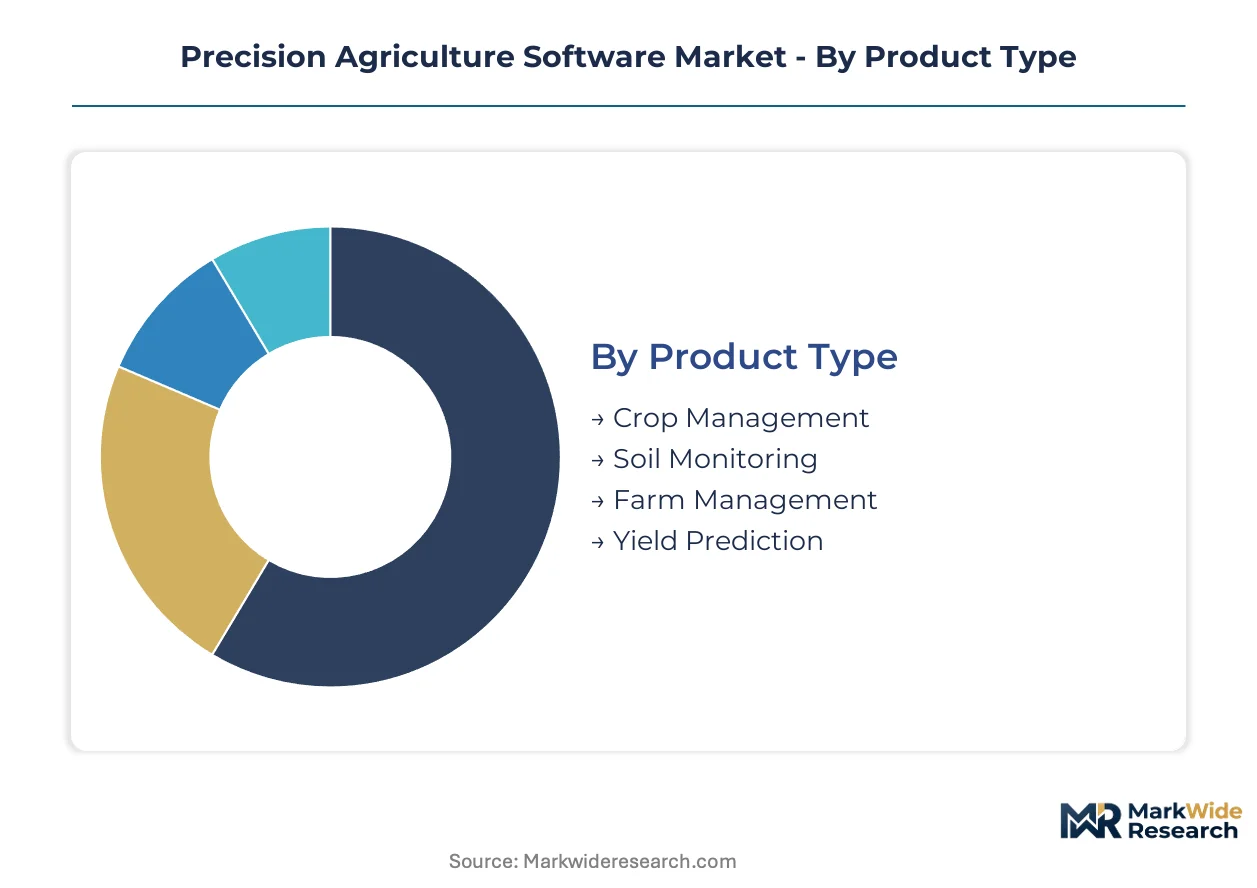
Segmentation reveals how precision agriculture software vendors align product architecture with distinct operational workflows and technical infrastructures across the farm economy. Different buyer profiles demand fundamentally different interface designs, data processing locations, and integration capabilities.
Product Type:
Standardization dominates basic record-keeping functions while customization intensity rises with agronomic complexity and prescription specificity.
- Farm Management:Unified platforms integrating financial planning, inventory tracking, and labor scheduling with field operation logs. Demand concentrates among professional management companies in Iowa and Illinois where consolidated operations require enterprise-grade resource coordination across multiple properties.
- Crop Management:Field-level platforms tracking planting dates, input applications, pest scouting, and harvest logistics with spatial reference. Adoption accelerates in Minnesota and Wisconsin row-crop operations facing EPA nutrient discharge enforcement under tightening Total Maximum Daily Loads.
- Soil Monitoring:Probe networks and electrical conductivity mapping for moisture, nutrient, and compaction assessment.
- Yield Prediction:Algorithmic harvest forecasting combining weather data, satellite imagery, and historical response curves.
Most installed capacity flows through Farm Management. Expansion is steepest in Crop Management.
Technology:
Cost tier stratification separates commodity sensor networks from premium predictive systems requiring specialized computational infrastructure.
- Remote Sensing:Satellite and aerial imagery platforms delivering NDVI, thermal, and multispectral data for vegetation health mapping. Deployment density triples in Corn Belt operations as sub-field resolution reaches commercial viability.
- IoT:Distributed sensor networks for soil moisture, microclimate, and equipment telemetry with cellular or LoRa backhaul. Nebraska and Kansas operators face connectivity gaps forcing hybrid architectures that elevate total cost of ownership.
- AI:Neural network models generating prescription maps from multi-year yield response databases.
- Machine Learning:Supervised learning systems for pest pressure prediction and input optimization recommendations.
Remote Sensing commands the largest addressable base. AI applications are gaining share fastest among large-scale operators.
End User:
Customer type determines pricing elasticity and support intensity, from individual producers to institutional procurement entities.
- Farmers:Owner-operators and family enterprises selecting platforms based on equipment compatibility and subscription affordability. Midwest consolidation shifts this segment toward professional management structures with centralized software procurement.
- Cooperatives:Member-owned grain and input suppliers extending precision services to patron growers. These entities aggregate data across hundreds of operations to benchmark performance and negotiate input pricing.
- Agricultural Consultants:Independent advisors prescribing variable-rate applications and nutrient management plans.
- Agronomists:Certified crop advisors interpreting algorithmic outputs and validating prescription recommendations.
Cooperatives maintain the deepest installed base. Agricultural Consultants show the steepest adoption curve as regulatory filing requirements proliferate.
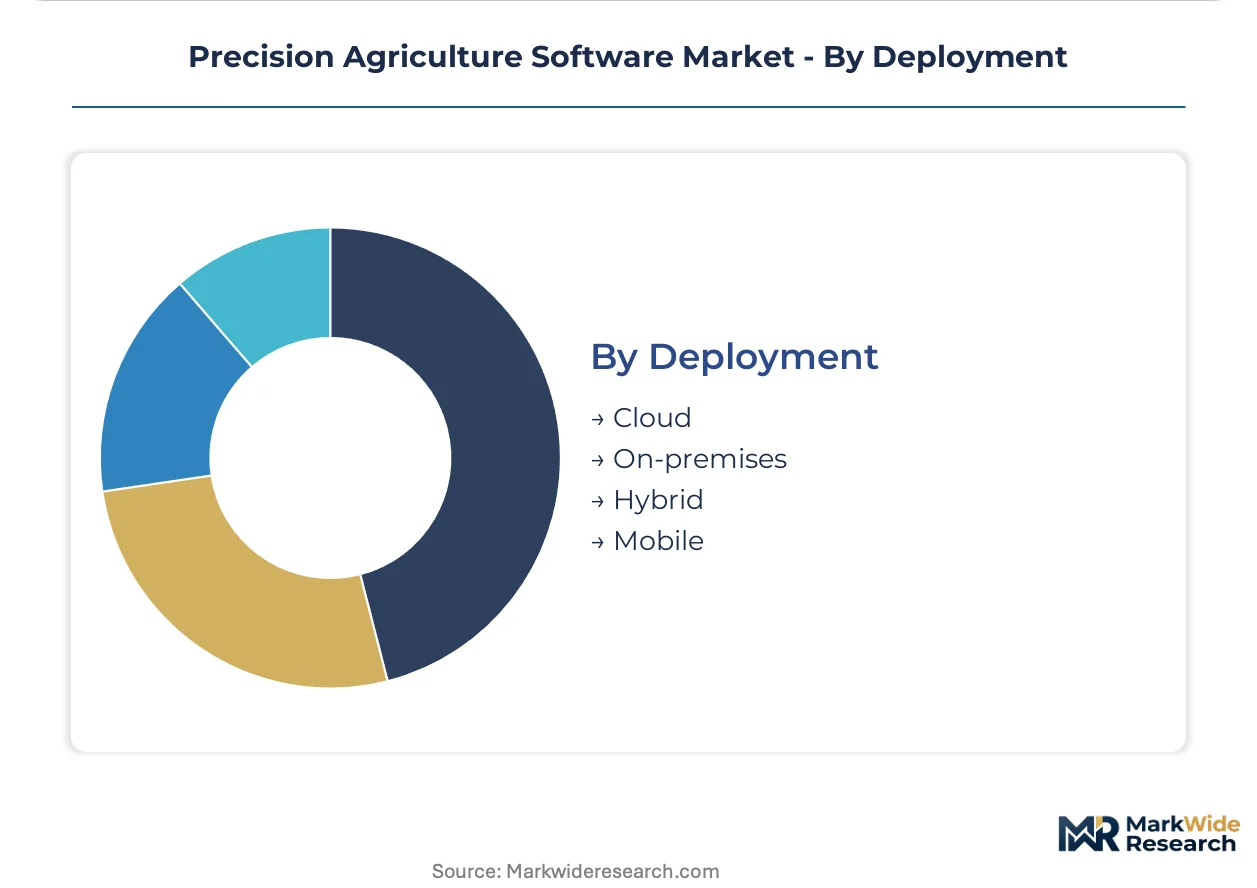
Deployment:
Maturity gradients separate established cloud architectures from emerging edge-computing implementations reducing field-level latency.
- Cloud:Centralized data processing with browser and mobile application access dominating new installations. Indiana and Ohio professional management companies specify cloud-native platforms for multi-location oversight.
- Hybrid:Local data caching with periodic cloud synchronization addressing intermittent cellular coverage in rural broadband deserts. This architecture elevates hardware costs but ensures operational continuity during critical planting and spraying windows.
- On-premises:Server installations within farm office environments retaining full data sovereignty.
- Mobile:Smartphone and tablet applications for in-field data entry and alert receipt.
Cloud deployment carries the majority of new subscriptions. Hybrid configurations are climbing fastest where connectivity infrastructure lags equipment capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified crop advisors and precision agriculture specialists concentrate in the US Corn Belt, anchoring global deployment density for prescription mapping platforms. Their expertise concentration in Iowa and Illinois accelerates technology transfer from research stations to commercial operations. This talent clustering shapes regional adoption velocity more than capital availability or equipment subsidies.
United States
Professional farm management companies controlling 10,000+ hectares in the Dakotas and Indiana drive enterprise software procurement through competitive tendering. The EPA enforces nutrient discharge thresholds under tightening Total Maximum Daily Loads in the Chesapeake Bay and Mississippi River watersheds. Corn Belt operations in Iowa and Illinois accelerate platform adoption to preempt consent decree exposure.
Brazil
Large-scale soybean and sugarcane operations in Mato Grosso and Goiás states expand variable-rate application adoption as export markets demand carbon intensity documentation. The national agricultural research corporation EMBRAPA validates precision protocols for tropical soil conditions. São Paulo-based agritech clusters develop localized prescription algorithms for cerrado biome management.
Canada
Prairie Province grain operations in Saskatchewan and Alberta deploy remote sensing platforms to optimize fertilizer application across expansive wheat and canola acreage. Agriculture and Agri-Food Canada cost-share programs under the Agricultural Clean Technology Program offset subscription investments. Winnipeg and Regina host concentrated agronomist networks interpreting satellite-derived vegetation indices.
Australia
Broadacre wheat and barley operations in Western Australia and New South Wales adopt soil moisture probe networks to manage irrigation risk in variable rainfall zones. The national agricultural regulator enforces water use efficiency standards that pressure farms toward documented input optimization. Adelaide-based precision service providers benchmark performance across mixed-enterprise operations.
Argentina
Pampas region soybean and corn producers integrate guidance systems to reduce input costs amid currency volatility and export tax pressures. The national agricultural technology institute INTA validates variable-rate protocols for no-till systems dominating regional practice. Buenos Aires province hosts the densest concentration of independent agronomic consultants prescribing platform configurations.
Precision Agriculture Software Market Competitive Landscape
Top-tier vendors anchor integrated equipment-software ecosystems, while mid-tier specialists compete through crop-specific analytics and third-party data interoperability. The market structure stratifies between machinery manufacturers capturing recurring subscription revenue and independent software vendors penetrating mixed-fleet operations. Three archetypes dominate: equipment-anchored platforms, guidance-specialist services, and open-architecture integrators. Dominant competitive moves include API partnerships with autonomous machinery developers and regulatory compliance automation embedding state-level filing workflows.
Within the equipment-anchored tier, Deere & Company exemplifies the installed-base leverage model, while Trimble Inc. occupies the high-accuracy guidance specialist position. AGCO Corporation represents the open-architecture archetype through platform designs sustaining farmer loyalty across heterogeneous machinery fleets. These three companies illustrate how competitive positioning diverges between hardware-coupled recurring revenue and software-centric interoperability strategies.
| Leading Market Players |
|---|
| Deere & Company |
| Trimble Inc. |
| AGCO Corporation |
| CNH Industrial N.V. |
| Topcon Corporation |
| Kubota Corporation |
| Corteva Inc. |
| Ag Leader Technology |
| AgEagle Aerial Systems Inc. |
| Others |
Pricing and Supply Chain Analysis
MEMS sensor price indices collapsing below commercial viability thresholds cascade through precision agriculture software supply chains, compressing hardware-enabled subscription tiers while elevating pure-play analytics premiums. Input cost deflation in soil probes and multispectral cameras concentrates margin capture with platform orchestrators rather than component vendors.
Pricing Analysis
Bundled equipment-software packages versus unbundled prescription service procurement splits pricing architecture across the market. Subscription tiers stratify by AI prescription sophistication and edge computing capability, with autonomous machinery integration commanding premiums against basic record-keeping modules. Cost compression in sensor hardware intensifies competition at the economy tier, eroding margins for point-solution vendors. Professional management companies in the Dakotas exhibit lowest price sensitivity, running competitive tenders that separate machinery acquisition from analytics procurement.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries fabricating edge-computing modules for field-level processing units. NVIDIA Jetson supply chains draw from China, Mexico, and Malaysia assembly operations. Lithium-ion cell dependencies for remote sensor power supplies rest on South Korean and Japanese chemical producers. Tariff exposure on Chinese-manufactured telemetry hardware elevates landed costs for US Midwest deployments. Distribution runs through equipment manufacturer dealer networks and independent agronomic consultancy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through EPA nutrient discharge enforcement tightening under Chesapeake Bay and Mississippi River watershed Total Maximum Daily Loads.
For Market Incumbents: Deepen API ecosystem partnerships with autonomous machinery developers to anchor platform stickiness against unbundling pressures. Fortify compliance automation workflows for state-level nutrient management filing requirements in Iowa and Illinois. Invest in edge computing certification to capture professional management company RFPs specifying sub-acre intervention latency. For New Entrants and Emerging Players: Independent agronomic consultancy networks offer channel access with lowest competitive saturation. California almond and Washington apple specialty crop operations present underpenetrated white-space against Midwest row-crop concentration. Pursue cooperative data aggregation partnerships that benchmark performance across patron grower portfolios. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native prescription platforms lacking captive equipment bases but commanding interoperability premiums. Five-to-ten-year viability hinges on carbon credit verification protocol consolidation. Watch for EPA consent decree acceleration in Minnesota and Wisconsin as inflection signal for compliance-automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Automation | State-level nutrient mandate embedding secures recurring subscription revenue from Iowa and Illinois filings. |
| Edge Computing Certification | Sub-acre intervention capability satisfies professional management company procurement specifications in Indiana and Ohio. |
| Autonomous Machinery API Partnership | Unmanned fleet orchestration integration anchors platform switching costs above two growing seasons. |
| Specialty Crop Algorithm Development | Drip irrigation and pest pressure modeling penetrates California almond and Washington apple addressable markets. |
| Carbon Credit Data Trail Verification | Auditable field-level records unlock premium offtake agreements under Verified Carbon Standard protocols. |
Research Methodology
Direct dialogue with precision agriculture software product managers, certified crop advisors at American Society of Agronomy credentialing bodies, professional farm management company procurement officers, and EPA regional enforcement coordinators grounded qualitative findings. Secondary validation drew from USDA EQIP and CSP program disbursement records, EPA Clean Water Act enforcement actions, state agriculture department nutrient management plan filings, and equipment manufacturer SEC disclosures. Bottom-up platform deployment estimates triangulated against top-down addressable hectare calculations.
Bottom-up modeling aggregated subscription pricing tiers across deployment modes, organization scale, and integration complexity, while top-down approaches scaled from Corn Belt cultivated acreage under professional management. Segmentation dimensions spanned product type, technology layer, end-user archetype, and deployment architecture. CAGRs derived from year-over-year platform procurement velocity among 10,000+ hectare operations. Forecast inputs incorporated sensor cost decline curves and cellular infrastructure buildout timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement discretion shifts and carbon credit protocol standardization. Assumptions reflect current regulatory trajectories and equipment connectivity penetration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Mobile Collaboration Market
Digital Solutions
OSS/BSS Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Bahrain ICT Market
Digital Solutions
Online Dating Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
IT As a Service Market
Digital Solutions
Global Mobile Content Management Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Data Broker Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Enterprise Mobility Market