
 US Voice Recognition Market | 2026-2036
US Voice Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
US Voice Recognition Market Insights
Enterprise-grade accuracy tiers is bifurcating the competitive landscape as buyers separate mission-critical deployments from consumer convenience tools. Nuance Communications Inc. anchors the healthcare vertical through deep clinical workflow integration. Amazon.com, Inc. leverages its Alexa ecosystem to dominate smart home and retail voice interfaces. Microsoft sustains enterprise relevance by embedding speech services across Azure and productivity suites.
Voice recognition technology converts acoustic speech signals into machine-readable text or commands through digital signal processing, acoustic modeling, and language modeling algorithms operating at latency thresholds below 300 milliseconds for real-time applications. The technology serves industrial and commercial purposes ranging from hands-free vehicle control to automated patient charting and biometric identity verification. Software and API segments capture the dominant share of value as enterprises prioritize cloud-based deployment over on-premise hardware. Healthcare application demand is accelerating fastest among verticals as ambient clinical intelligence reduces physician administrative burden. Natural Language Processing technology leads R&D investment intensity as vendors compete on contextual understanding accuracy.
The FDA regulates voice-enabled clinical decision support tools under software-as-medical-device frameworks, requiring validation evidence for diagnostic or treatment-related outputs. FCC guidelines govern telecommunications relay services and accessibility mandates for speech-recognition interfaces in consumer devices. NHTSA oversees voice-activated automotive systems through distracted-driving safety standards that shape HMI design constraints. Stakeholders must monitor evolving federal procurement standards for biometric voice authentication in government contracts.
Market Dynamics
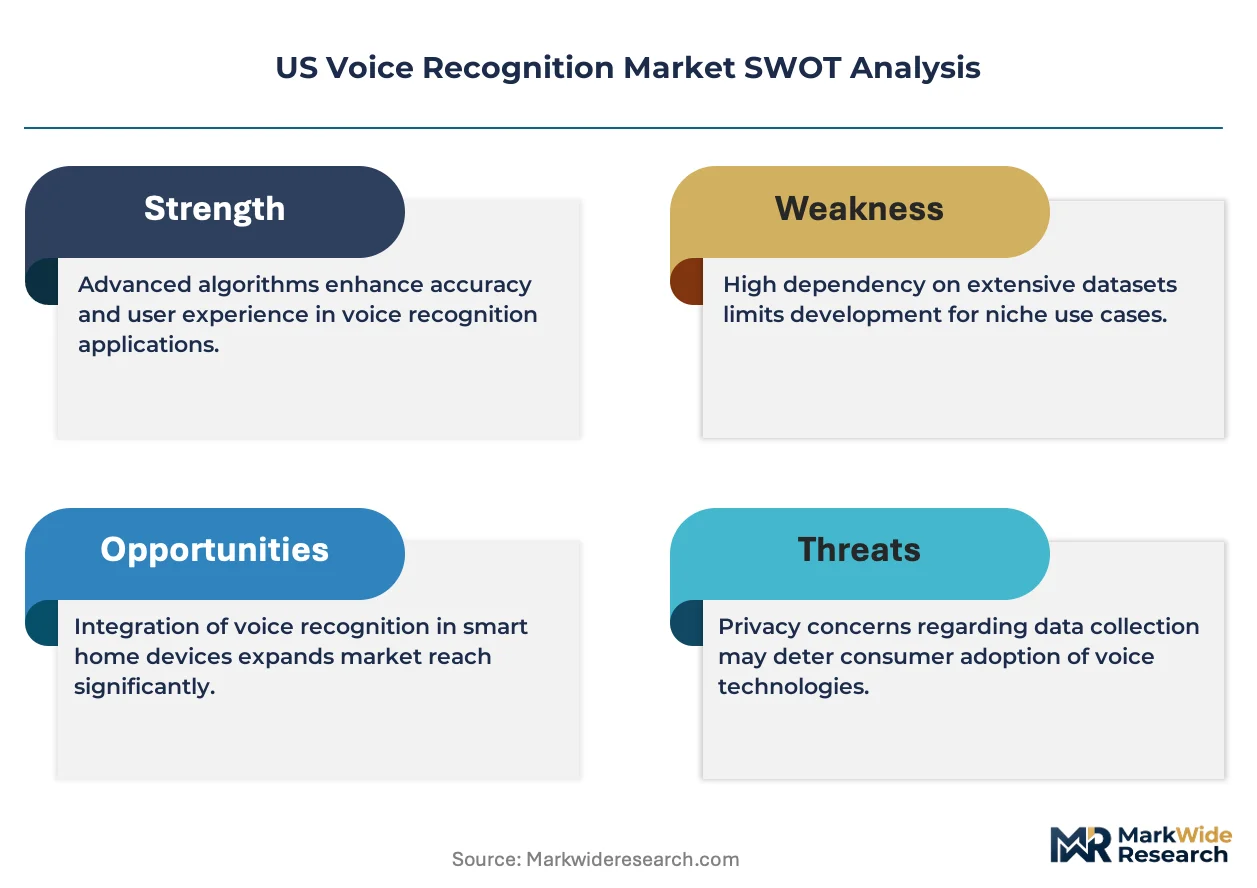
Enterprise buyers are bifurcating accuracy tiers, separating mission-critical clinical deployments from convenience-driven consumer applications. This structural split concentrates vendor resources on FDA-validated healthcare workflows while commoditizing smart home interfaces.
Growth Catalysts
- FDA Software-as-Medical-Device Guidance:The framework provides validation pathways for clinical decision support tools, accelerating provider adoption of ambient documentation systems in acute care settings.
- Cloud API Deployment Models:Healthcare IT departments prioritize software and API segments over hardware, reducing capital expenditure barriers for multi-site health system rollouts.
- Texas Healthcare Hub Concentration:Major medical centers in Houston and Dallas anchor enterprise demand, creating reference-site effects that accelerate purchasing decisions across neighboring states.
Market Restraints
- GPU and Specialized Chip Input Costs:Training large acoustic models requires sustained access to high-performance compute infrastructure, squeezing margins for mid-tier API providers.
- California Technology Corridor Supply Concentration:Voice AI engineering talent pools concentrate in San Francisco Bay Area and Seattle metro regions, creating compensation inflation and recruitment bottlenecks.
- Latency Floor Technical Limitation:Real-time clinical applications demand sub-300 millisecond processing thresholds that edge deployments struggle to meet consistently.
Strategic Opportunities
- Florida and Arizona Senior Care Expansion:Retirement community density in these states creates concentrated demand for voice-enabled fall detection and medication adherence monitoring.
- Automotive Voice HMI Convergence:Integration with advanced driver-assistance systems opens new licensing revenue streams as NHTSA safety standards mandate hands-free control interfaces.
- IRA Healthcare Digitization Incentives:Federal reimbursement adjustments for technology-enabled care coordination accelerate hospital capital allocation toward clinical intelligence platforms.
Industry Challenges
- Phonetic Transcription Specialist Talent Gap:Healthcare NLP deployment requires rare expertise in medical ontologies and acoustic model fine-tuning that outpaces university pipeline output.
- EHR Integration Complexity:Legacy electronic health record systems demand custom middleware development, extending implementation timelines and requiring specialized systems integrator partnerships.
- Biometric Voiceprint Certification Delays:NIST standards for speaker verification in federal procurement create extended validation cycles that stall government contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Voice Recognition Market |
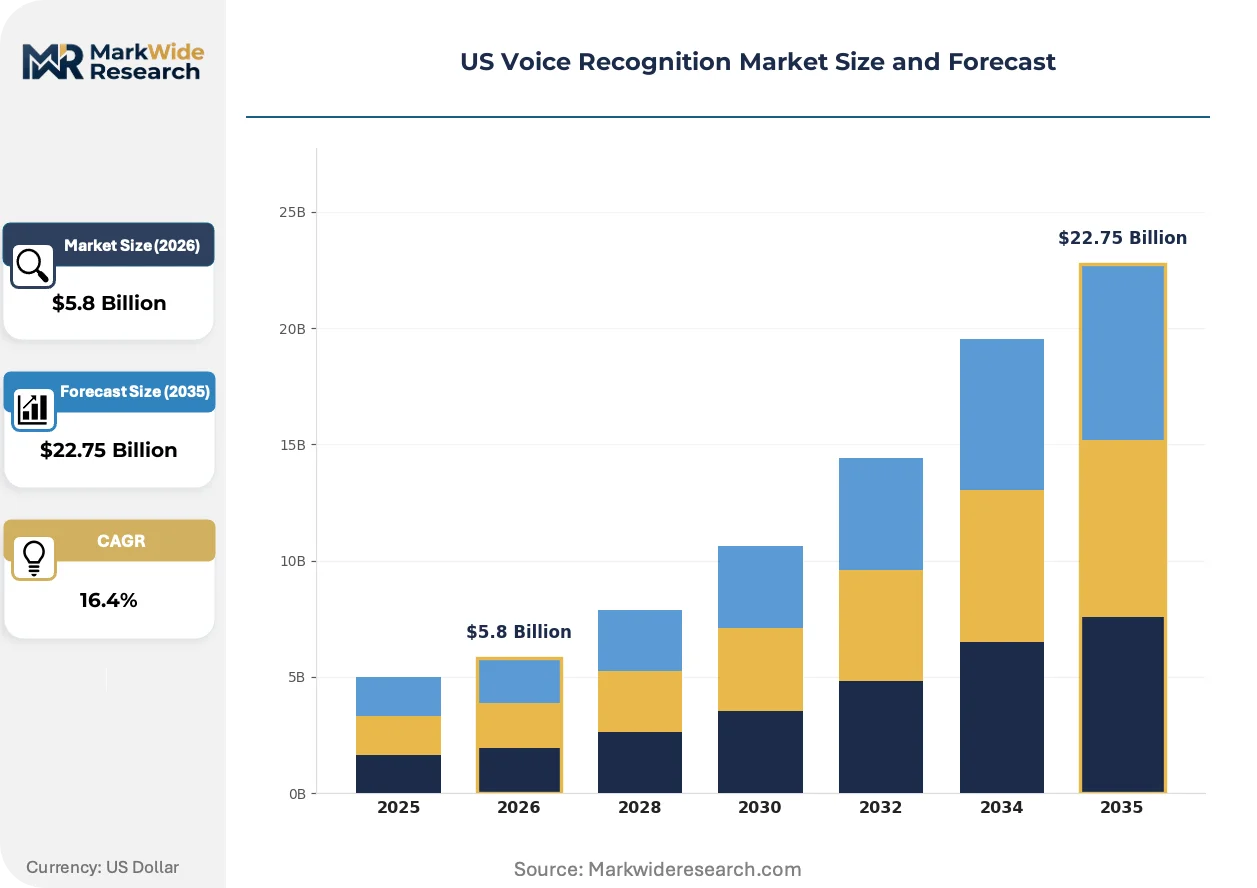
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $22.75 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, API, SDK Application: Customer Support, Virtual Assistants, Healthcare, Automotive End User: Consumers, Enterprises, Government, Healthcare Providers Technology: Natural Language Processing, Machine Learning, Speech-to-Text, Pattern Recognition |
| Companies Covered | Nuance Communications Inc., Advanced Voice Recognition Systems, Inc., LumenVox, Apple Inc., Google LLC, Amazon.com, Inc., Microsoft, International Business Machines Corporation, M2SYS Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Voice Recognition Market Trends and Innovations
Natural language processing architectures are compressing the gap between acoustic transcription and contextual understanding. Vendors compete on clinical accuracy benchmarks rather than word-error-rate alone.
Transformer-based acoustic models are displacing recurrent neural network architectures in enterprise deployments. Healthcare systems in California and Texas demand these architectures for their superior handling of medical terminology disambiguation. The shift is compressing R&D timelines for vendors still maintaining legacy codebases.
FDA software-as-medical-device frameworks now govern clinical voice applications with diagnostic or treatment-related outputs. Manufacturers must submit validation evidence demonstrating accuracy in intended-use conditions before commercial distribution. The requirement most affects ambient documentation vendors targeting emergency department and surgical workflows.
Health system procurement committees now unbundle speech recognition from broader EHR contracts, issuing standalone RFPs for best-of-breed clinical documentation tools. This purchasing pattern disrupts incumbent platform bundling strategies and opens evaluation windows for specialized vendors. The behavior is most visible in multi-hospital systems across the Midwest and Southeast seeking to reduce physician administrative burden.
US Voice Recognition Market Segmentation
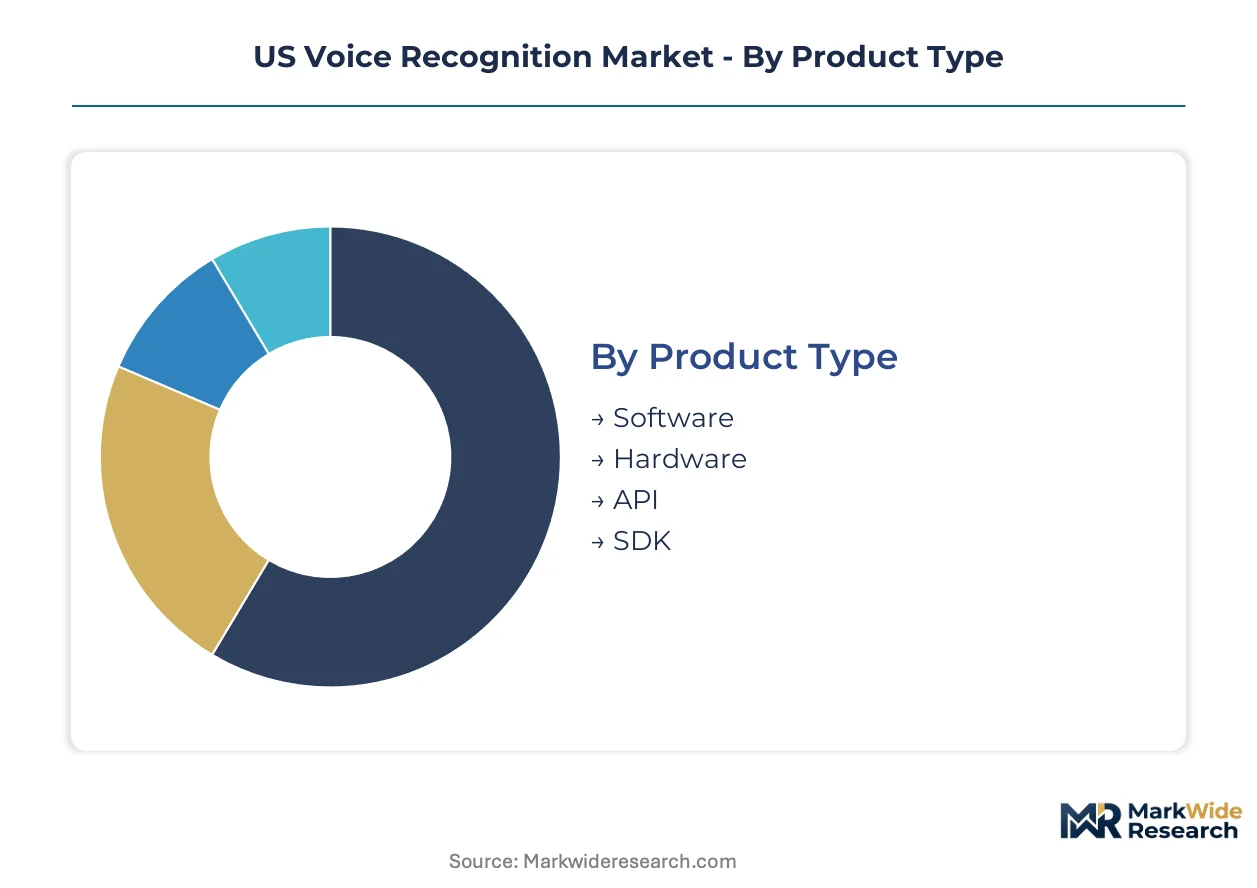
Voice recognition technology fragments across distinct product architectures, application environments, and deployment models. Buyers in the US market separate cloud-based consumption from on-premise infrastructure based on latency requirements and data sovereignty constraints. Understanding these segment boundaries clarifies where vendor R&D investments concentrate versus where commoditization pressures dominate.
Product Type:
Cloud APIs and embedded SDKs flow through developer marketplaces and direct enterprise sales channels, while hardware appliances and perpetual software licenses move through systems integrators and value-added resellers.
- Software:Perpetual licenses and subscription deployments for on-premise transcription engines. Healthcare providers in Texas and California anchor demand as HIPAA-compliant local processing requirements override cloud preferences for sensitive patient data.
- API:RESTful and WebSocket interfaces enabling real-time speech integration into third-party applications. Startups and mid-market SaaS vendors in Austin and Seattle drive consumption through usage-based metering that aligns costs with transaction volumes.
- Hardware:Dedicated speech processing appliances with onboard acoustic models. Edge deployments in automotive manufacturing plants and secure government facilities sustain this segment despite cloud migration trends.
- SDK:Embedded development kits for mobile and IoT device integration. Consumer electronics manufacturers building Alexa-competing products represent the primary uptake channel.
Software dominates installed base in legacy healthcare environments. API is where expansion concentrates as developers prioritize cloud-native integration speed over infrastructure ownership.
Application:
Healthcare and automotive applications command premium pricing tiers due to regulatory validation requirements and safety-critical performance thresholds, while customer support and virtual assistant deployments compete on scale economics.
- Healthcare:Ambient clinical documentation and diagnostic decision support tools. The FDA software-as-medical-device framework shapes validation pathways for emergency department and surgical workflow deployments.
- Automotive:Hands-free control interfaces integrated with advanced driver-assistance systems. NHTSA distracted-driving safety standards mandate voice HMI adoption, creating regulatory-pull demand across Detroit and Southern California manufacturing clusters.
- Customer Support:Interactive voice response and agent-assist transcription for call center operations. Financial services and telecommunications providers in New York and Chicago drive volume through cost-per-call reduction mandates.
- Virtual Assistants:Smart home and mobile device conversational interfaces. Consumer convenience use cases face margin compression as platform economics concentrate value in ecosystem owners rather than component vendors.
Customer support captures the largest transaction volume. Healthcare is climbing the fastest as physician burnout drives capital allocation toward administrative automation.
End User:
Enterprise procurement committees unbundle speech recognition from broader platform contracts, creating standalone evaluation windows that favor specialized vendors over bundled incumbents.
- Healthcare Providers:Hospital systems and physician practices deploying clinical documentation tools. Multi-site health systems in the Midwest and Southeast issue separate RFPs for best-of-breed ambient intelligence platforms.
- Enterprises:Cross-industry adoption for meeting transcription, compliance documentation, and customer interaction analysis. Technology and financial services firms in California and New York represent the concentration of advanced deployment.
- Government:Federal agencies and state departments requiring biometric voice authentication and accessibility compliance. NIST speaker verification standards create extended procurement cycles that stall contract awards.
- Consumers:Individual adoption through smart speakers, mobile assistants, and automotive interfaces. Price sensitivity and platform stickiness limit standalone vendor opportunity in this segment.
Enterprises hold the deepest penetration of paid deployments. Healthcare providers are gaining share fastest as IRA digitization incentives accelerate hospital technology budgets.
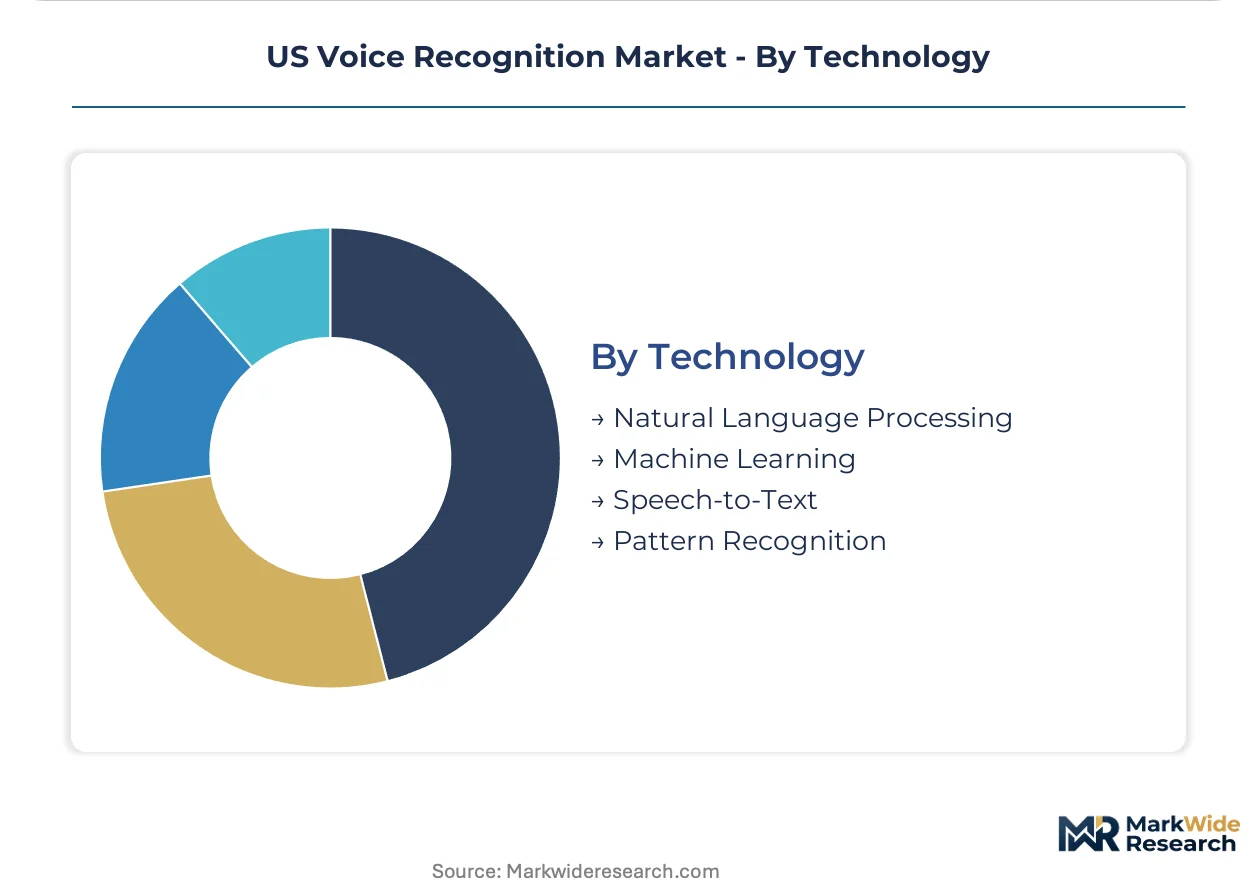
Technology:
Transformer-based architectures are displacing recurrent neural networks in enterprise deployments, compressing R&D timelines for vendors maintaining legacy codebases while concentrating competitive advantage on training data scale.
- Natural Language Processing:Contextual understanding and intent classification beyond acoustic transcription. Healthcare systems demand medical ontology disambiguation capabilities that separate clinical-grade deployments from consumer tools.
- Machine Learning:Acoustic model training and speaker adaptation algorithms. GPU infrastructure requirements for large model training create barriers for mid-tier providers without cloud-scale compute access.
- Speech-to-Text:Core acoustic signal processing and phoneme recognition engines. Real-time clinical applications demand sub-300 millisecond latency thresholds that edge deployments struggle to meet consistently.
- Pattern Recognition:Speaker identification and voice biometric verification. Federal procurement standards for voiceprint authentication drive certification investment for vendors targeting government contracts.
Speech-to-Text anchors commercial revenue through API consumption. Natural Language Processing shows the steepest expansion trajectory as accuracy benchmarks shift from word-error-rate to clinical outcome measures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US voice recognition technology exports flow primarily to Canadian healthcare systems and Mexican automotive manufacturing corridors, establishing North American trade corridors as the dominant commercial pathway for clinical documentation and hands-free control systems.
California
Silicon Valley technology corridors anchor enterprise software development and cloud API deployment for healthcare and automotive verticals. FDA software-as-medical-device guidance shapes validation requirements for clinical decision support tools targeting emergency department workflows. San Francisco Bay Area engineering talent pools concentrate voice AI R&D investment, though compensation inflation creates recruitment bottlenecks for mid-tier providers.
Texas
Houston and Dallas medical centers drive demand for ambient clinical documentation systems that reduce physician administrative burden. IRA healthcare digitization incentives accelerate hospital capital allocation toward clinical intelligence platforms across multi-site health systems. The state's healthcare hub concentration generates reference-site effects that accelerate purchasing decisions across neighboring Oklahoma and Louisiana markets.
New York Metro
Financial services and telecommunications providers in Manhattan and Jersey City deploy interactive voice response and agent-assist transcription for call center cost reduction mandates. FCC accessibility guidelines govern telecommunications relay services compliance for speech-recognition interfaces in consumer-facing deployments. The Northeast corridor's enterprise density sustains premium pricing tiers for mission-critical transcription accuracy benchmarks.
Michigan
Detroit automotive manufacturing clusters integrate voice HMI systems with advanced driver-assistance systems under NHTSA distracted-driving safety standards. Hands-free control interfaces represent regulatory-pull demand rather than discretionary feature adoption across vehicle production lines. Tier 1 suppliers in the Great Lakes region license embedded SDKs for production-scale deployment across multiple OEM platforms.
Florida
Retirement community density in Tampa and Orlando metro areas creates concentrated demand for voice-enabled fall detection and medication adherence monitoring systems. Senior care expansion attracts specialized vendors targeting aging-in-place technology adoption curves. The state's healthcare provider networks prioritize ambient monitoring solutions that reduce emergency response latency for elderly populations.
US Voice Recognition Market Competitive Landscape
Listed leaders compete with private specialists across healthcare validation tiers and cloud deployment models. The competitive structure concentrates around three to four dominant platform owners with deep clinical workflow integration, while mid-tier API providers face margin compression from GPU infrastructure requirements. Strategic archetypes separate FDA-validated healthcare specialists from smart home ecosystem owners and enterprise cloud service bundlers. Competitive moves center on EHR integration partnerships and acoustic model training data scale rather than hardware differentiation.
Within the healthcare validation tier, Nuance Communications Inc. and M2SYS Technology exemplify specialized clinical documentation providers. Amazon.com, Inc. and Microsoft occupy positions as cloud ecosystem owners embedding speech services across productivity and smart home platforms. Advanced Voice Recognition Systems, Inc. sits within the mid-tier API segment serving developers with usage-based metering models.
| Leading Market Players |
|---|
| Nuance Communications Inc. |
| Advanced Voice Recognition Systems, Inc. |
| LumenVox |
| Apple Inc. |
| Google LLC |
| Amazon.com, Inc. |
| Microsoft |
| International Business Machines Corporation |
| M2SYS Technology |
| Others |
Pricing and Supply Chain Analysis
FDA software-as-medical-device validation tiers gate both supplier qualification and price differentiation, separating clinical-grade deployments from commoditized consumer interfaces through certification investment barriers that vendors must clear before accessing premium healthcare procurement channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Healthcare providers purchasing FDA-validated ambient documentation systems face limited price elasticity due to physician burnout reduction mandates, while call center operators in customer support segments drive aggressive per-minute cost compression. Pricing pressure stems from GPU infrastructure requirements for acoustic model training, squeezing mid-tier API providers unable to achieve cloud-scale compute efficiencies. Enterprise IT departments exhibit lowest price sensitivity for HIPAA-compliant on-premise deployments, whereas startup developers consuming metered APIs demonstrate highest sensitivity to transaction-volume pricing.
Supply Chain Analysis
Port congestion on trans-Pacific lanes elevates inbound logistics costs for specialized AI training hardware originating from Taiwan and South Korea. Cloud API providers draw from concentrated semiconductor fabrication in East Asia for GPU accelerators, while on-premise hardware vendors source acoustic processing chipsets from domestic foundries. Single-source vulnerability in advanced node semiconductor manufacturing creates supply chain risk for vendors training large transformer models. Distribution runs through direct enterprise sales teams for healthcare systems, developer marketplaces for API consumption, and systems integrator channels for embedded SDK deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from open-source speech models that erode proprietary API differentiation, requiring defensive positioning around clinical workflow integration and regulatory validation moats.
For Market Incumbents: Shield core healthcare relationships through deepening EHR integration partnerships that increase switching costs for hospital systems. Acquire specialized phonetic transcription talent pools to close the healthcare NLP expertise gap that open-source alternatives cannot replicate. Prioritize FDA software-as-medical-device certification investment as a defensive moat against unvalidated competitors.
For New Entrants and Emerging Players: Differentiate on Florida and Arizona senior care verticals where ambient fall detection and medication adherence monitoring demand outpaces incumbent coverage. Target retirement community networks with voice-enabled aging-in-place solutions that established clinical documentation vendors have underserved. Pursue direct partnerships with regional health systems seeking best-of-breed alternatives to bundled EHR contracts.
For Investors and Strategic Acquirers: FDA software-as-medical-device framework maturation reshapes the acquisition landscape toward validated clinical workflow specialists. Long-term viability centers on vendors with demonstrated emergency department deployment references and scalable acoustic model training infrastructure. Monitor NIST speaker verification certification progress as the signal indicating government contract readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Unlocks acute care procurement channels requiring validation evidence for diagnostic outputs. |
| EHR Integration Partnership | Reduces implementation friction through pre-built middleware connecting to legacy hospital systems. |
| Platform Integration | Embeds speech services across productivity suites to capture enterprise IT standardization decisions. |
| Acquisition of Specialist Firm | Addresses phonetic transcription talent gaps through targeted healthcare NLP expertise consolidation. |
| Geographic Expansion | Establishes reference sites in Texas healthcare hubs that accelerate neighboring state purchasing decisions. |
Research Methodology
The analysis maps software, API, hardware, and SDK product architectures, each validated through hospital CIOs, clinical informaticists, health system procurement committees, and biomedical engineers. Primary fieldwork combined with secondary sources including FDA 510(k) filings, CMS Medicare reimbursement databases, hospital GPO contract records, and hyperscaler cloud service disclosures. Bottom-up segment sizing triangulated against top-down market aggregate checks.
Consistency validation against external benchmarks ensured analytical robustness across the projection horizon. The forecasting framework modeled deployment model, organization size, healthcare vertical, integration complexity, and regional adoption pattern dimensions. CAGRs derived from segment-level growth trajectory analysis incorporating IRA healthcare digitization incentive impacts and clinical workforce shortage intensity metrics.
The analysis sits within stated boundaries; outcomes outside sustained FDA regulatory pathway clarity and cloud infrastructure cost trajectories would require recalibration. Forecasts reflect documented assumptions regarding physician adoption curves and health system capital allocation priorities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence As a Service Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
AI Text Generator Market
Artificial Intelligence (AI)
Brain Computer Interface Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Emotion AI Software Market