
 Global Digital Commerce Market | 2026-2036
Global Digital Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Commerce Market Foresight
Grocery and fast-moving consumer goods retail is hardening as the dominant end-use vertical for digital commerce infrastructure. Amazon sustains unmatched fulfillment density across North America and Western Europe. Alibaba Group anchors cross-border trade flows through its logistics and payments ecosystem. JD.com competes on owned supply chain velocity, particularly in perishable categories where delivery speed determines retention.
Digital commerce encompasses the electronic exchange of goods, services, and information through internet-connected platforms, relying on encrypted payment gateways, distributed order management systems, and real-time inventory synchronization across multi-node fulfillment networks. Mobile commerce leads platform type adoption where smartphone penetration exceeds fixed broadband availability, while buy now pay later represents the fastest-growing payment method among underbanked customer segments. Cloud-based deployment models capture the dominant share of merchant technology spending as elasticity requirements spike during promotional cycles.
The EU Digital Services Act, GDPR, and PCI DSS collectively shape platform liability, data handling protocols, and transaction security standards across operational jurisdictions. India's RBI and the EU's EBA impose divergent but equally stringent requirements on digital wallet providers and cross-border payment aggregators. Stakeholders must monitor regulatory fragmentation in data localization and consumer protection as the primary determinant of market access cost and competitive moat durability.
Market Dynamics
Unified payments infrastructure is compressing merchant onboarding timelines from months to days, reshaping competitive entry barriers and forcing fulfillment networks to synchronize with real-time settlement rails.
Growth Catalysts
- India's UPI expansion:The National Payments Corporation of India's real-time payment rails enable instant merchant settlement, accelerating small-business participation in digital commerce.
- EU Digital Services Act compliance:Platform accountability mandates are standardizing transparency requirements across cross-border transactions, reducing jurisdictional friction for compliant operators.
- Perishable category velocity:Cold-chain logistics automation is extending shelf-stable delivery windows, expanding addressable grocery SKU counts for digital channels.
Market Restraints
- Data localization mandates:India's RBI and the EU's divergent data residency requirements force redundant infrastructure deployment, inflating compliance capital intensity.
- Payment aggregator concentration:Cross-border settlement flows depend on a narrowing tier of licensed wallet providers, creating systemic failure risk.
- Last-mile labor cost inflation:Gig-economy delivery networks face regulatory reclassification pressures across multiple jurisdictions, compressing unit economics.
Strategic Opportunities
- Brazil's underpenetrated grocery segment:ANVISA's evolving e-pharmacy frameworks and logistics deregulation are opening perishable digital commerce corridors.
- Voice commerce integration:Natural language processing convergence with inventory APIs is creating hands-free reordering interfaces for household staples.
- Buy-now-pay-later regulatory tailwinds:India's RBI digital lending guidelines are legitimizing embedded credit products for underbanked customer acquisition.
Industry Challenges
- PCI DSS certification bottlenecks:Small and mid-sized merchants face 6-12 month compliance timelines, delaying platform onboarding and revenue recognition.
- Legacy ERP synchronization:Real-time inventory APIs struggle with decades-old on-premise retail management systems, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Commerce Market |
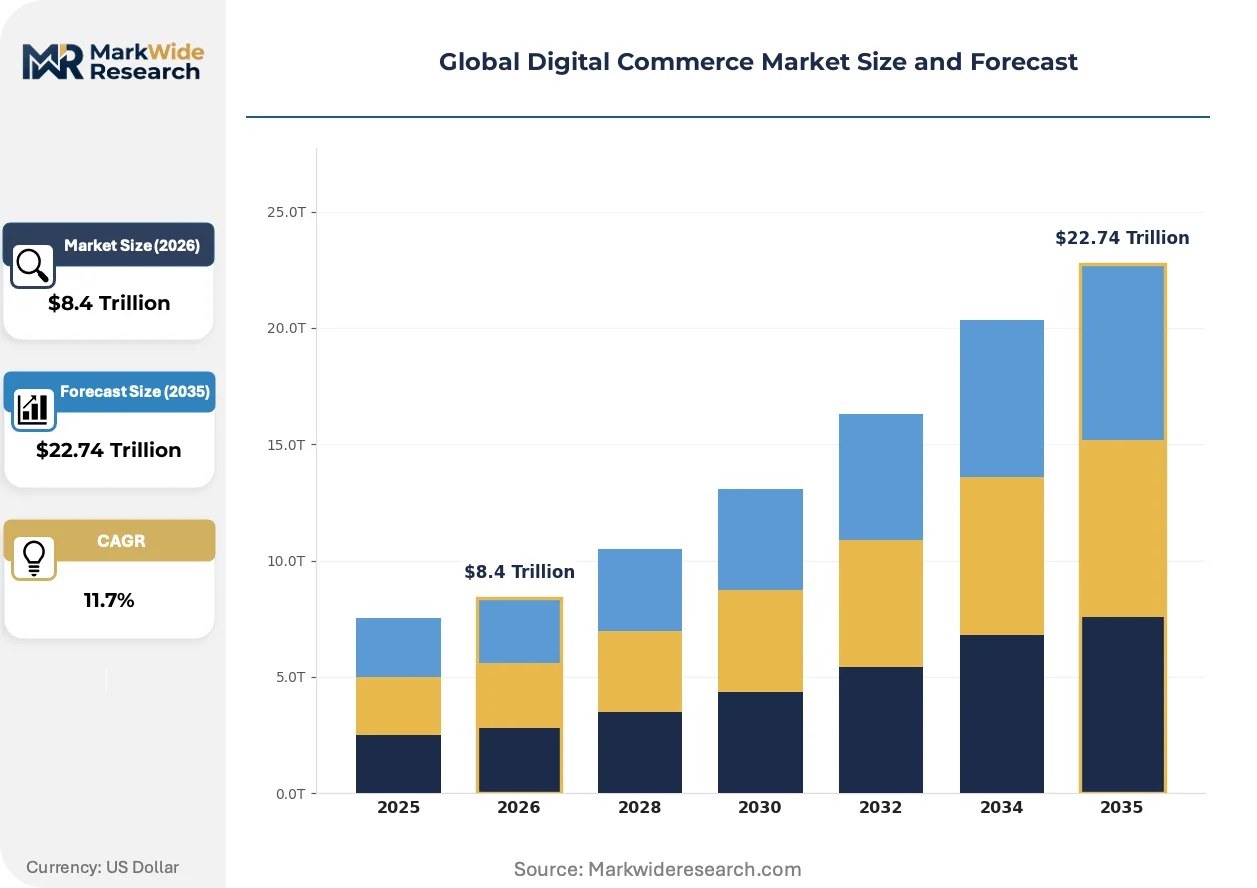
| Market Size in 2026 | $8.4 Trillion |
| Market Size in 2035 | $22.74 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Mobile Commerce, Social Commerce, Web Commerce, Voice Commerce, Chat Commerce Payment Method: Credit Cards, Digital Wallets, Bank Transfers, Buy Now Pay Later, Cryptocurrency Customer Type: Individual Consumers, Small Businesses, Enterprises, Non-Profit Organizations, Freelancers Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS, PaaS |
| Companies Covered | Amazon, Alibaba Group, Shopify, PDD Holdings, JD.com, MercadoLibre, Sea Limited, eBay, Walmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Commerce Market Shifts & Advancements
Artificial intelligence is compressing demand forecasting cycles from weeks to hours, enabling dynamic pricing and inventory positioning that follows micro-seasonal consumption patterns rather than monthly aggregates.
Distributed order management systems are unifying inventory visibility across dark stores, micro-fulfillment centers, and third-party logistics nodes into single-pane orchestration layers. Grocery retailers in the United Kingdom and Germany are deploying these systems at scale to collapse delivery promise windows. The technology is unifying previously siloed warehouse management and transportation management functions into continuous optimization loops.
The EU AI Act's risk-tiered compliance framework is mandating algorithmic audit trails for automated pricing and recommendation engines. Platforms serving European consumers must document decision logic for high-risk AI applications, extending development cycles. Fashion and electronics verticals are most affected, with merchants restructuring data science teams to embed compliance-by-design protocols.
Subscription-based replenishment models are displacing episodic purchase behavior in household consumables. Direct-to-consumer brands bypass traditional retail intermediaries, capturing recurring revenue and first-party data. This pattern is most visible in South Korea and Japan, where MFDS-regulated health and beauty categories lead subscription commerce penetration.
Global Digital Commerce Market Segmentation
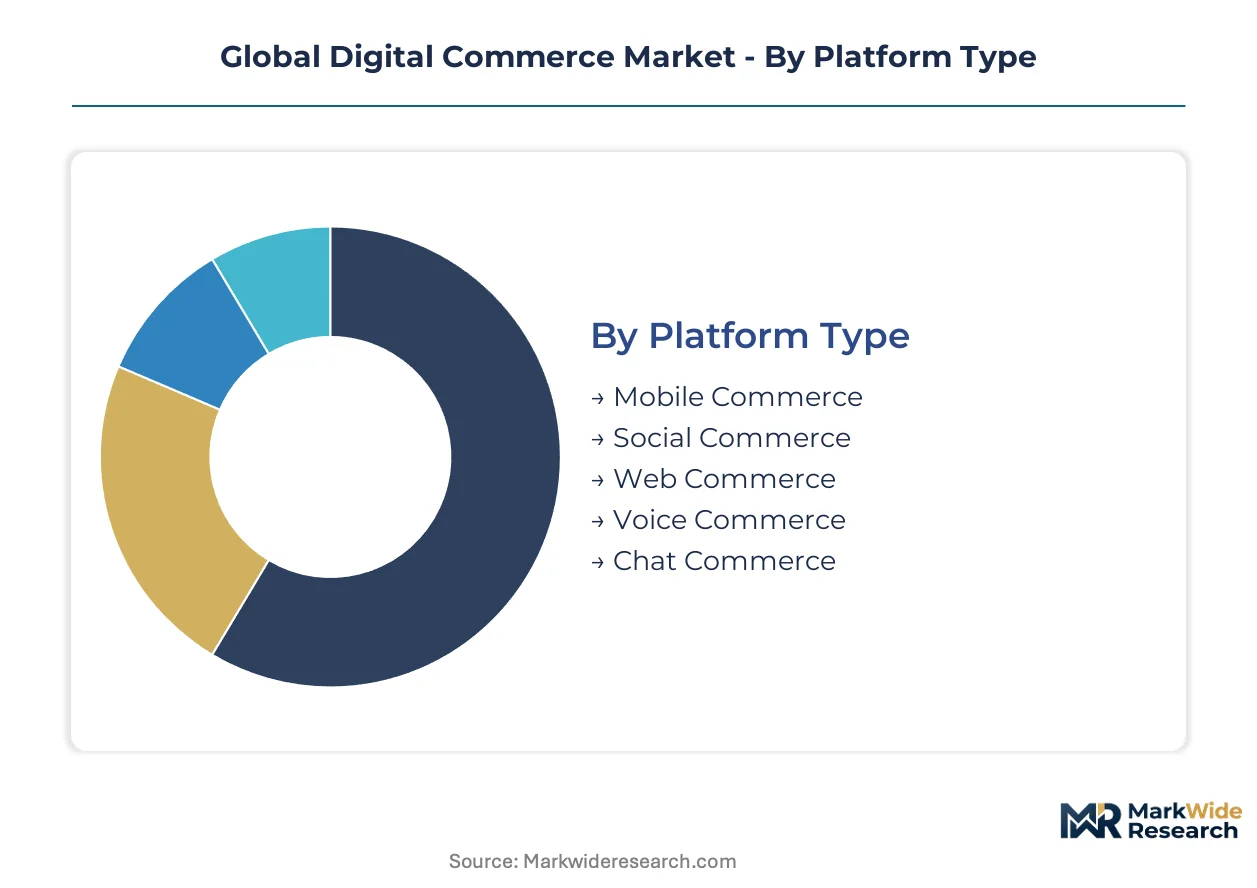
Segmentation in digital commerce infrastructure reveals divergent capital requirements and margin profiles across technology stacks. Merchant technology decisions cascade through payment acceptance costs, fulfillment network design, and regulatory compliance architecture.
Platform Type:
Capital intensity varies dramatically by platform type, with voice commerce requiring the heaviest upfront investment in natural language processing infrastructure and acoustic model training.
- Mobile Commerce:Smartphone-native transaction interfaces dominate where fixed broadband infrastructure remains underdeveloped. India's UPI rails and Indonesia's QRIS standards concentrate merchant investment in lightweight Android SDKs rather than full-stack web development.
- Social Commerce:Embedded checkout within content feeds demands creator economy tooling and livestream transaction infrastructure. China's Douyin and South Korea's Naver Shopping anchor demand through influencer-led discovery mechanisms.
- Web Commerce:Browser-based storefronts retain dominance in high-consideration purchases requiring detailed specification comparison.
- Voice Commerce:Hands-free reordering interfaces for household staples leverage smart speaker penetration in US and UK households.
- Chat Commerce:Conversational interfaces through WhatsApp Business and WeChat Mini Programs enable merchant presence without standalone app development.
Most installed capacity flows through Mobile Commerce. Expansion is steepest in Social Commerce.
Payment Method:
Payment method selection determines regulatory capital reserves, fraud liability allocation, and cross-border settlement complexity for platform operators.
- Digital Wallets:Stored-value instruments linked to bank accounts or cards compress checkout friction. India's Paytm and PhonePe, Indonesia's GoPay, and Brazil's Pix-enabled wallets concentrate volume where card penetration lags.
- Buy Now Pay Later:Point-of-sale credit products embedded at checkout capture underbanked customer segments. India's RBI digital lending guidelines and Australia's ASIC responsible lending frameworks shape compliance architecture.
- Credit Cards:Revolving credit instruments maintain dominance in North American and Western European markets with mature rewards ecosystems.
- Bank Transfers:Account-to-account payment rails gain traction where real-time settlement infrastructure exists.
- Cryptocurrency:Blockchain-based settlement remains confined to cross-border remittance corridors and speculative asset purchases.
Digital Wallets command the largest transaction volume base. Buy Now Pay Later is climbing the fastest among emerging payment modalities.
Customer Type:
Customer type segmentation maps to divergent service level requirements, with enterprise clients demanding API reliability guarantees and dedicated support tiers.
- Enterprises:Large organizations require procurement workflow integration, multi-entity billing, and negotiated interchange rates. Manufacturing and pharmaceutical verticals in Germany and Japan drive demand for punchout catalog connectivity and three-way matching automation.
- Small Businesses:Merchants with limited technical resources prioritize turnkey solutions with minimal configuration overhead.
- Individual Consumers:End-user purchasers drive volume through convenience-oriented interface design and loyalty program participation.
- Non-Profit Organizations:Donation processing and recurring giving workflows require specialized compliance with charitable solicitation regulations.
- Freelancers:Independent contractors need invoicing tools with international currency support and escrow protections.
Enterprises generate the highest revenue per account. Small Businesses show the steepest expansion trajectory in emerging market onboarding.
Deployment Model:
Deployment model choice reflects trade-offs between capital expenditure control and operational flexibility during demand spikes.
- Cloud-Based:Elastic infrastructure provisioning enables merchants to scale compute and storage through promotional cycles without stranded capacity. AWS, Azure, and Google Cloud Platform capture merchant technology spending where traffic predictability remains low.
- SaaS:Subscription-licensed commerce platforms abstract infrastructure management entirely, accelerating time-to-market for non-technical merchants.
- On-Premises:Self-managed data center deployments persist where data localization mandates or latency requirements preclude public cloud adoption.
- Hybrid:Mixed architectures partition sensitive transaction data on-premises while burst capacity leverages public cloud.
- PaaS:Developer-oriented platforms provide managed runtime environments for custom commerce application construction.
Cloud-Based deployments absorb the majority of new merchant capacity. SaaS models are gaining share fastest among mid-market retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting digital commerce infrastructure investment toward jurisdictions where compliance costs remain manageable relative to market scale. India's unified payments interface and Brazil's Pix rails attract merchant technology spending that might otherwise flow to Europe's costlier GDPR-DSA compliance environment. Capital allocation patterns now favor real-time settlement markets with lighter data localization burdens.
United States
Voice commerce adoption concentrates in smart speaker households where Amazon Alexa and Google Home penetration exceeds 40 percent. The FTC's intensifying scrutiny of platform self-preferencing under Section 5 authority is forcing marketplace operators to restructure search ranking algorithms. Seattle and San Francisco anchor fulfillment technology development, with dark store automation pilots collapsing grocery delivery windows to under two hours.
India
UPI transaction volumes crossed 15 billion monthly payments, compressing merchant onboarding from months to days for small businesses. RBI's digital lending guidelines and data localization mandates require wallet providers to maintain domestic server infrastructure, inflating compliance capital intensity. Mumbai and Bengaluru concentrate fintech engineering talent, with PhonePe and Paytm scaling merchant acceptance networks into tier-three cities.
Germany
Grocery retailers deploy distributed order management systems to unify inventory across dark stores and micro-fulfillment centers. The EU AI Act's risk-tiered compliance framework mandates algorithmic audit trails for automated pricing engines, extending development cycles. Berlin and Munich anchor logistics technology clusters, with Flink and Gorillas legacy forcing incumbents to match 10-minute delivery promises.
Brazil
Pix instant payment rails enable zero-fee merchant settlement, accelerating small-business digital adoption in underpenetrated grocery corridors. ANVISA's evolving e-pharmacy frameworks and logistics deregulation are opening perishable commerce channels previously restricted to physical retail. São Paulo concentrates marketplace engineering operations, with MercadoLibre expanding fulfillment density to counter Amazon's regional entry.
China
Social commerce through Douyin and WeChat Mini Programs displaces traditional search-based discovery, with livestream transactions capturing double-digit share of fashion and electronics volume. SAMR's antitrust enforcement against platform exclusivity arrangements is restructuring merchant multi-homing incentives. Hangzhou and Shenzhen anchor cross-border logistics infrastructure, with Alibaba's Cainiao network synchronizing inventory positioning for 72-hour global delivery windows.
Global Digital Commerce Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated marketplace operators commanding fulfillment density advantages while SaaS enablers capture merchant technology spending. The vendor base concentrates around three strategic archetypes: vertically integrated retailers owning end-to-end logistics, platform enablers providing merchant tooling without inventory risk, and payment infrastructure specialists monetizing transaction flows. Competitive dynamics center on fulfillment network expansion and regulatory compliance automation as primary defensive moves.
Within the integrated retail tier, Amazon and JD.com exemplify divergent geographic concentration strategies, with the former anchoring North American and Western European fulfillment density and the latter competing on owned supply chain velocity in perishable categories. Alibaba Group occupies a position spanning cross-border trade facilitation through its logistics and payments ecosystem. Shopify represents the SaaS enabler archetype, abstracting infrastructure management for non-technical merchants without assuming inventory risk.
| Leading Market Players |
|---|
| Amazon |
| Alibaba Group |
| Shopify |
| PDD Holdings |
| JD.com |
| MercadoLibre |
| Sea Limited |
| eBay |
| Walmart |
| Others |
Supply & Pricing Matrix
Platform engineering talent concentration in Bengaluru and Shenzhen drives labor-cost differentials that widen pricing-tier spreads between premium enterprise SaaS and economy self-serve tiers. India's RBI data localization mandates and the EU's AI Act compliance requirements add fixed-cost layers that compress margins at the mid-market level, forcing vendors to stratify pricing more aggressively by customer sophistication.
Pricing Analysis
Direct-to-merchant subscription tiers bypass traditional distributor markups, with platform operators capturing margin through payment processing spreads rather than channel intermediation. Price differentiation hinges on API call volume thresholds and PCI DSS certification level, with enterprise clients paying premium rates for dedicated infrastructure isolation. Pricing pressure stems from cloud compute cost compression as AWS and Azure discount reserved instances, squeezing SaaS provider gross margins. Small businesses exhibit highest price sensitivity, while enterprise procurement teams negotiate on reliability SLAs rather than unit cost.
Supply Chain Analysis
Workforce availability for distributed systems engineering concentrates in India, Poland, and Vietnam, where technical universities feed talent pipelines into fulfillment technology development. Raw material dependencies span semiconductor fabrication for edge computing nodes, lithium-ion cells for delivery fleet electrification, and cold-chain refrigerants for perishable logistics infrastructure. Supply chain risk centers on single-source vulnerability in payment processor licensing, where RBI and EBA approvals constrain aggregator substitution. Distribution runs through hyperscaler marketplaces and direct sales teams, with channel partners receding in developer-centric tooling segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with grocery and FMCG retailers prioritizing fulfillment reliability over cost minimization in vendor selection criteria. Premium specifications around sub-two-hour delivery windows and real-time inventory synchronization now dominate RFP evaluation frameworks.
For Market Incumbents: Acquire dark-store real estate in tier-one metropolitan corridors to defend against quick-commerce insurgents. Consolidate payment aggregator licenses ahead of RBI and EBA regulatory tightening, which threatens to fragment settlement infrastructure. Build backward integration into cold-chain logistics to capture margin that currently leaks to third-party providers.
For New Entrants and Emerging Players: The mid-market pricing gap between Shopify Plus and basic tier offerings creates entry space for vertical specialists serving regulated categories like pharmaceuticals and alcohol. Brazil's underpenetrated grocery corridors and Germany's fragmented independent retailer base represent the most penetrable geographies. Lead with compliance-automation tooling that accelerates PCI DSS and GDPR readiness as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Private equity firms with logistics technology portfolios are the most active acquirer in this space, consolidating point solutions into unified commerce stacks. Long-term viability favors platforms with embedded payment licenses and owned fulfillment density rather than pure software layers. Watch UPI transaction velocity in India's tier-three cities as the signal for emerging market infrastructure readiness inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Flink and Gorillas legacy in Berlin forces 10-minute delivery promise matching by incumbents. |
| Payment License Consolidation | RBI and EBA regulatory tightening threatens unlicensed aggregator viability across settlement flows. |
| AI Compliance Infrastructure | EU AI Act audit trail requirements extend development cycles for automated pricing engines. |
| Cold-Chain Backward Integration | Perishable category velocity demands owned refrigeration assets rather than third-party logistics. |
| Voice Commerce Platform Development | Amazon Alexa and Google Home penetration exceeds 40 percent in US smart speaker households. |
Research Methodology
Bottom-up merchant onboarding modeling reconciled against top-down payment volume tracking forms the analytical core of this study. Primary interviews with platform engineering leads, merchant acquisition heads, regulatory compliance officers, and logistics operations directors informed demand-side assumptions. Secondary validation drew from NPCI UPI transaction disclosures, ECB payment statistics, SEC filings of listed marketplace operators, and customs data on fulfillment technology imports. Top-down macroeconomic indicators and bottom-up cohort retention analysis were triangulated to anchor growth rate derivations.
Input-output matrices mapped transaction volume drivers across platform type, payment method, customer segment, and deployment model dimensions throughout the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by current revenue contribution. Cloud infrastructure spending patterns and real-time settlement rail adoption curves served as industry-specific forecast inputs, with promotional cycle elasticity modeled separately from baseline commerce growth.
Caveats apply where RBI data localization enforcement intensity or EU AI Act audit requirement scope could materially shift the outlook. Forecasts embed assumptions around UPI expansion velocity and Pix merchant adoption that regulatory intervention or macroeconomic disruption might revise. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
E-Commerce Fashion Accessories Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
Food E Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Global B2B E-Commerce Market
E-Commerce Solutions
E-Commerce Household Appliances Market