

Supplier Contract Management Market Size, Share, and Industry Trends Forecast 2026-2036
Supplier Contract Management Market Insights
Artificial intelligence integration into contract authoring and obligation extraction is narrowing the gap between procurement intent and legal enforcement. SAP leverages its ERP-installed base to embed contract modules directly into enterprise financial workflows. Icertis anchors its position through AI-native clause intelligence that maps regulatory changes against active supplier agreements. Oracle competes by extending cloud infrastructure into contract performance analytics, binding compute and compliance spend.
Supplier contract management encompasses the systematic creation, negotiation, execution, and performance monitoring of agreements between buyers and vendors, typically governed by metadata schemas that track deliverables, pricing tiers, and termination conditions across thousands of active documents. Its primary purpose is to reduce value leakage from maverick spending, missed renewals, and unenforced service-level agreements. Cloud-based deployment now leads solution delivery by enabling real-time collaboration across distributed procurement teams, while contract lifecycle management captures the largest margin pool through recurring subscription and professional services revenue. Risk management represents the fastest-growing segment as supply chain disruption and ESG liability force enterprises to model vendor failure scenarios proactively.
The EU AI Act, GDPR, and ISO 37001 anti-bribery framework shape product requirements by mandating explainable decision trails, data residency controls, and third-party due diligence documentation. FDA 21 CFR Part 11 and SEC disclosure rules extend these demands in US life sciences and public equities procurement, where supplier contracts trigger audit scrutiny. Procurement leaders must now evaluate whether their contract platforms can autonomously flag regulatory exposure before it crystallizes into liability.
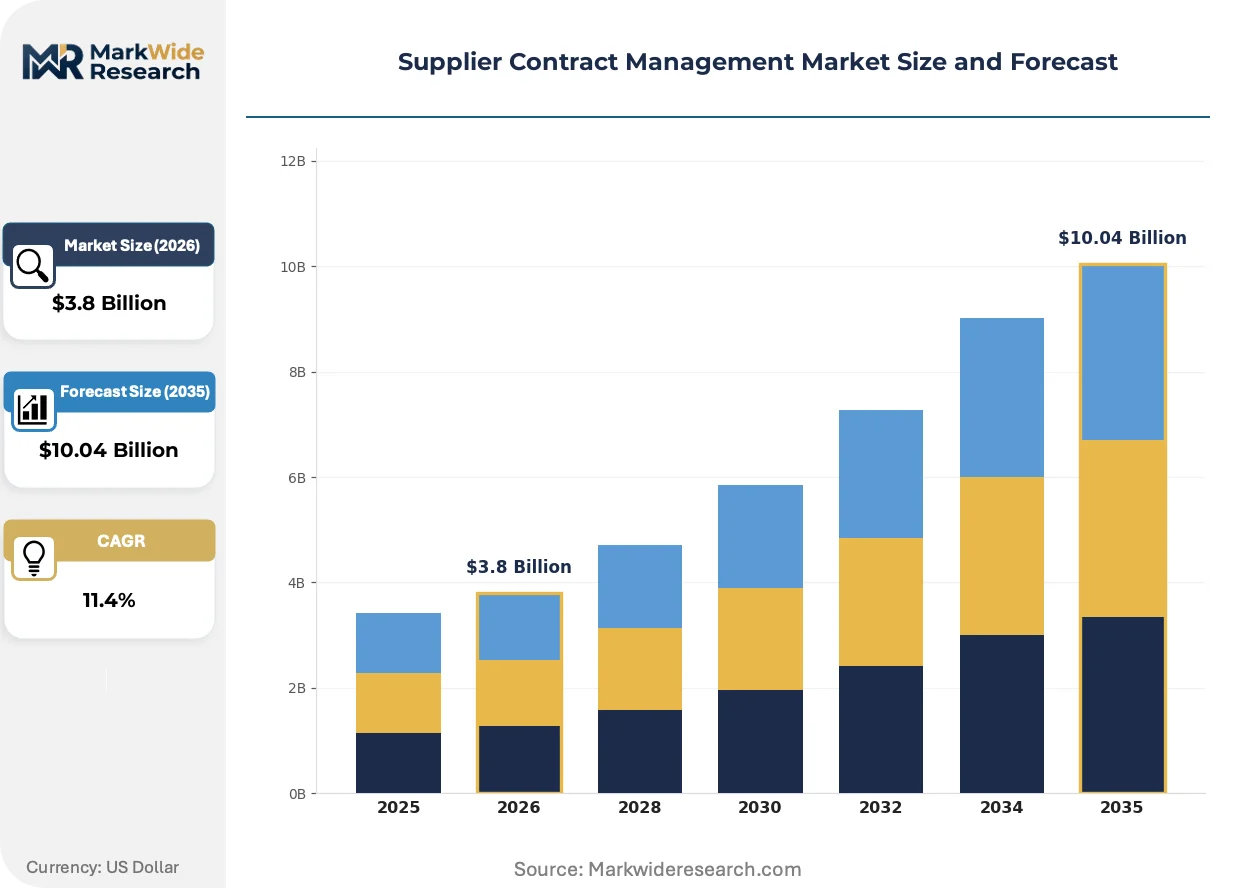
Market Dynamics
EU AI Act enforcement timelines are compressing procurement cycles as enterprises scramble to embed explainable AI documentation into active supplier agreements before audit deadlines crystallize.
Growth Catalysts
- GDPR Article 30 mandates:Automated processing records now require vendor data flow mapping, forcing procurement teams to adopt contract platforms with built-in data residency controls.
- Automotive supply chain reconfiguration:German OEMs are mandating ISO 37001 anti-bribery certification tiers across tier-2 and tier-3 suppliers, expanding contract governance tool deployment.
- Natural language processing:Clause extraction engines now parse obligation metadata from unstructured PDF archives, collapsing manual contract review timelines from weeks to hours.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and GCP dominate hosting for contract lifecycle platforms, creating single-point-of-failure exposure for audit-critical documentation.
- Legacy ERP integration costs:SAP and Oracle on-premise instances require custom API middleware, inflating implementation budgets by 40-60% versus greenfield deployments.
- Substitute workflow fragmentation:Microsoft Word with SharePoint remains entrenched in mid-market legal departments, delaying centralized contract repository adoption.
Strategic Opportunities
- India manufacturing corridors:PLI scheme beneficiaries in electronics and pharmaceuticals lack mature vendor compliance infrastructure, creating first-mover advantage for contract governance platforms.
- CSRD scope expansion:EU corporate sustainability reporting mandates will require supplier ESG data integration into contract performance dashboards by 2026.
- Blockchain-anchored verification:Immutable timestamping of contract amendments is converging with smart contract automation to create self-executing payment triggers.
Industry Challenges
- Procurement-legal coordination gaps:Commercial teams negotiate terms that legal cannot operationalize into enforceable SLA monitoring, creating post-signature value leakage.
- Multi-jurisdiction template standardization:French CNIL data processing addenda conflict with German BDSG worker council consultation requirements, fragmenting pan-European contract playbooks.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplier Contract Management Market Trends and Innovations
Contract intelligence platforms are absorbing adjacent workflow categories as vendors race to own the full procurement-to-payment data thread rather than remaining isolated document repositories.
Generative AI for contract drafting is migrating from experimental pilot programs to production deployment at Fortune 500 legal departments. Healthcare systems in the US are adopting clause generation tools to standardize FDA 21 CFR Part 11-compliant quality agreements with contract research organizations. This migration is compressing the competitive moat between specialized CLM vendors and adjacent ERP providers.
REACH substance restriction updates are forcing chemical and industrial manufacturers to embed automated regulatory change monitoring into supplier qualification workflows. The ECHA SVHC candidate list expansion triggers immediate contract amendment obligations for importers. Automotive coatings and electronics assembly sectors in Germany and Belgium are deploying AI-native regulatory tracking to preempt supply interruption.
Centralized procurement functions are consolidating vendor management authority previously dispersed across business units. Industrial conglomerates in Japan are dissolving subsidiary-level contracting autonomy in favor of METI-inspired supply chain resilience frameworks. This concentration is visible in Tokyo-Osaka manufacturing clusters where parent-company procurement centers now mandate unified contract templates for all domestic suppliers.
Supplier Contract Management Market Segmentation
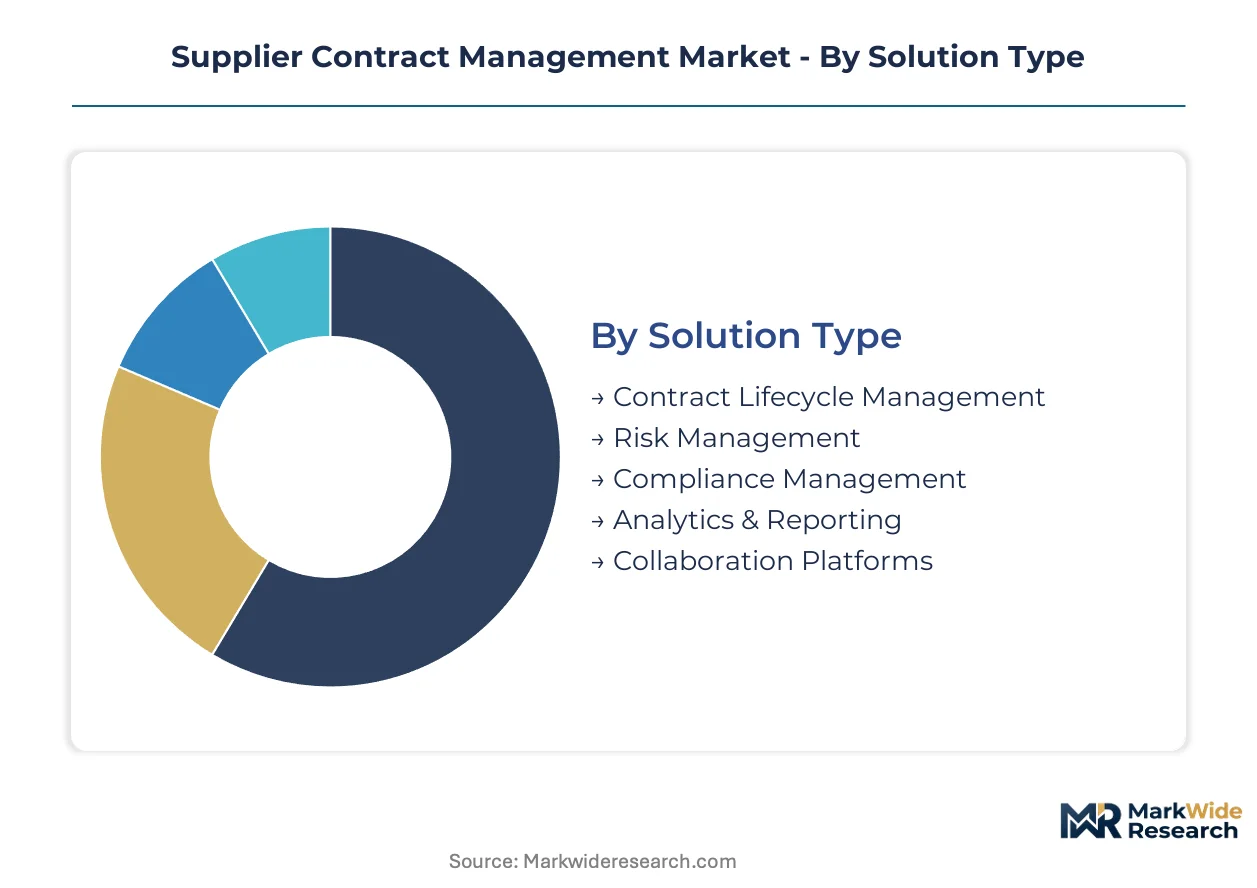
Segmentation reveals how contract governance tools align with distinct operational intensities and compliance burdens across buyer profiles. Procurement leaders select modules based on integration depth, regulatory exposure, and cross-functional collaboration requirements rather than generic feature checklists.
Solution Type:
After-sales service intensity varies sharply across solution categories, with ongoing clause monitoring and regulatory update feeds creating divergent support cost structures.
- Contract Lifecycle Management:Core platforms orchestrate authoring, negotiation, execution, and renewal workflows through centralized metadata repositories. German automotive manufacturers deploy these systems to enforce ISO 37001 certification tiers across multi-tier supplier networks. CLM holds the largest share; momentum sits with Risk Management.
- Risk Management:Specialized modules model vendor failure scenarios, ESG liability exposure, and supply chain disruption probabilities using Monte Carlo simulations. Energy utilities in Belgium leverage these tools to assess REACH substance restriction impacts on chemical supplier portfolios.
- Compliance Management:Automated regulatory mapping engines track GDPR Article 30 data flow obligations and EU AI Act explainability requirements across active agreements.
- Analytics & Reporting:Performance dashboards consolidate obligation extraction outputs into procurement KPIs and executive risk scorecards.
- Collaboration Platforms:Real-time negotiation workspaces enable distributed legal teams to redline contracts without version control fragmentation.
Deployment economics favor solutions with embedded professional services over pure software subscriptions.
Deployment Mode:
Cost tier stratification separates enterprise buyers with dedicated infrastructure budgets from mid-market adopters prioritizing operational expenditure predictability.
- Cloud-Based:Multi-tenant architectures deliver automatic regulatory update propagation and elastic compute for AI-powered clause extraction. Healthcare procurement agencies in the US select these deployments to satisfy HIPAA Business Associate Agreement automation requirements. Cloud-Based dominates current bookings; Hybrid configurations are climbing the fastest.
- On-Premise:Air-gapped installations persist in defense and classified government contracting where data residency mandates prohibit third-party hosting.
- Hybrid:Split architectures maintain sensitive contract metadata on-premises while pushing collaboration workloads to managed cloud instances.
- SaaS:Subscription pricing with standardized implementation timelines appeals to mid-market manufacturers lacking dedicated IT procurement resources.
- Private Cloud:Single-tenant virtualized environments serve financial institutions subject to ECB and national banking authority audit protocols.
Cloud-based deployments command the majority of new license value; private cloud engagements show steepest expansion trajectory among regulated sectors.
End User:
Application context determines feature prioritization, with procurement agencies demanding regulatory automation while logistics providers emphasize performance monitoring.
- Procurement Agencies:Centralized buying functions require template standardization across business units and automated approval hierarchy enforcement. Japanese industrial conglomerates under METI supply chain resilience directives consolidate these capabilities at parent-company level.
- Manufacturers:Production-dependent organizations integrate contract systems with ERP inventory modules to trigger payment releases against verified delivery milestones.
- Logistics Providers:Freight and warehousing operators track service-level agreement penalties and fuel surcharge escalation clauses through specialized obligation extraction.
- Retail Chains:High-volume supplier bases necessitate automated renewal flagging and minimum purchase commitment monitoring across thousands of vendor relationships.
- Educational Institutions:Universities and research consortia manage grant-funded procurement with unique compliance documentation and intellectual property ownership terms.
Procurement agencies represent the most concentrated revenue pool; manufacturers are gaining share fastest through Industry 4.0 digitization mandates.
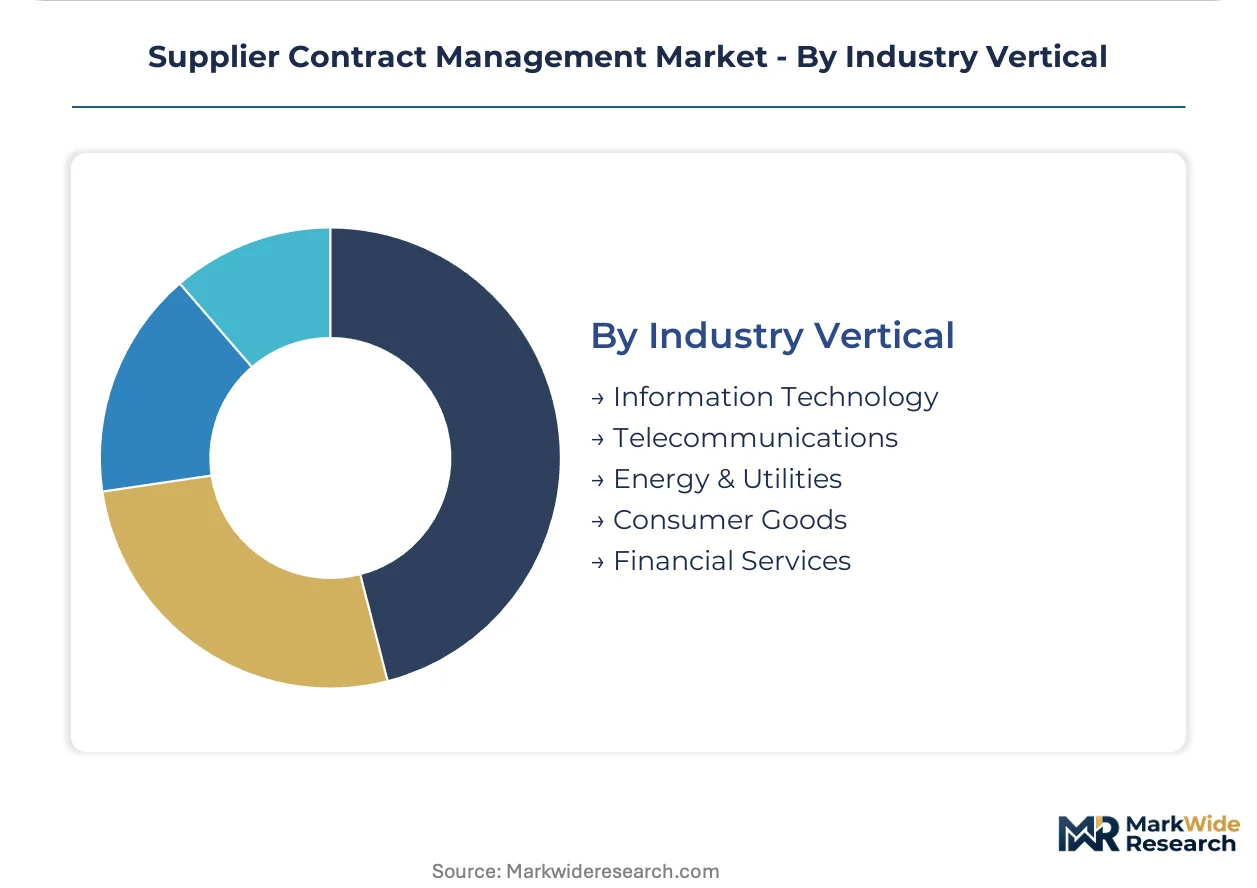
Industry Vertical:
Customer type segmentation exposes divergent regulatory velocity, with financial services facing continuous audit pressure while consumer goods prioritize margin protection.
- Financial Services:Banks and insurers deploy contract intelligence to automate SEC disclosure trigger identification and vendor risk concentration reporting. GDPR and DORA operational resilience requirements in the EU accelerate replacement of spreadsheet-based vendor tracking.
- Energy & Utilities:Grid operators and renewable developers manage long-term power purchase agreements with complex index-linked pricing and force majeure clause libraries.
- Information Technology:Software vendors and cloud service providers standardize data processing addenda to satisfy cross-border data transfer mechanism requirements.
- Telecommunications:Spectrum licensees and infrastructure operators track regulatory commitment deadlines embedded in concession agreements.
- Consumer Goods:Brand owners monitor supplier ESG certifications and packaging material compliance against extended producer responsibility frameworks.
Financial services anchor current vertical spending; energy and utilities demonstrate steepest expansion trajectory through renewables contract complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers export contract governance frameworks to tier-1 manufacturing partners across Central Europe. This trade corridor shapes regulatory adoption patterns in adjacent procurement markets.
United States
Healthcare procurement agencies at HCA and Kaiser Permanente deploy automated contract governance for FDA 21 CFR Part 11 compliance with contract research organizations. SEC disclosure rules trigger vendor risk concentration reporting in financial services procurement. Boston and San Francisco biotech clusters mandate audit-ready documentation workflows for supplier qualification.
Germany
Volkswagen and BMW mandate ISO 37001 anti-bribery certification tiers across tier-2 and tier-3 suppliers in the automotive supply chain. The EU AI Act explainability requirements compress procurement cycles for embedded AI documentation. Stuttgart and Munich industrial corridors deploy AI-native clause extraction to monitor REACH substance restriction impacts on chemical suppliers.
Japan
Toyota and Hitachi dissolve subsidiary-level contracting autonomy under METI supply chain resilience directives. The country's national pharmaceutical regulator enforces documentation standards for medical device supplier agreements. Tokyo-Osaka manufacturing clusters consolidate vendor management authority at parent-company procurement centers.
India
PLI scheme beneficiaries in electronics and pharmaceuticals lack mature vendor compliance infrastructure for contract lifecycle management. The central bank's operational resilience guidelines extend to third-party risk management in banking procurement. Bangalore and Hyderabad IT corridors attract first-mover contract governance platform deployments for software services export compliance.
Belgium
Energy utilities model REACH substance restriction impacts on chemical supplier portfolios through Monte Carlo simulation modules. ECHA SVHC candidate list expansion triggers immediate contract amendment obligations for importers. Antwerp chemical and coatings sectors deploy regulatory tracking to preempt supply interruption from substance restriction updates.
Supplier Contract Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment modes and integration depth. The market exhibits tiered consolidation where ERP-installed base incumbents anchor enterprise accounts while AI-native challengers penetrate mid-market legal departments. Three archetypes dominate: infrastructure-integrated suite providers, standalone contract intelligence specialists, and document-centric workflow platforms. Competitive moves concentrate on API ecosystem expansion and regulatory content partnership networks.
Within the infrastructure-integrated tier, SAP and Oracle occupy positions binding compute spend to compliance automation through cloud infrastructure extension. Icertis represents the AI-native specialist archetype, anchoring competitive positioning through clause intelligence that maps regulatory changes against active agreements. These three entities exemplify the strategic divergence between ERP-embedded workflow depth and standalone AI acceleration.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| Icertis |
| Coupa Software |
| DocuSign |
| IBM |
| Agiloft |
| Sirion |
| Zycus |
| Others |
Pricing and Supply Chain Analysis
Single-source cloud infrastructure dependency determines both pricing tier spreads and supply chain shape in contract lifecycle management platforms. AWS, Azure, and GCP concentration creates chokepoint exposure that compresses margins for mid-market SaaS vendors while inflating premium-tier pricing for air-gapped private cloud alternatives.
Pricing Analysis
The current-generation AI-native clause extraction versus legacy rules-based parsing creates a three-tier pricing structure across premium, standard, and economy levels. Premium tiers bundle embedded regulatory content partnerships and dedicated implementation support, while economy SaaS subscriptions compete on per-seat pricing with stripped-down workflow automation. Cost compression in the mid-market stems from Microsoft 365 ecosystem bundling that delays standalone CLM procurement decisions. Healthcare procurement agencies exhibit lowest price sensitivity due to FDA 21 CFR Part 11 compliance mandates, whereas educational institutions and mid-market manufacturers drive hardest bargain on subscription terms.
Supply Chain Analysis
Upstream feedstock for contract intelligence platforms centers on NLP model training data, regulatory content libraries, and hyperscaler compute capacity. The United States, Ireland, and Germany anchor primary data center infrastructure for cloud deployments. Proprietary clause ontology development draws from legal publisher partnerships and court filing corpora. Single-source vulnerability concentrates in AWS GovCloud and Azure sovereign cloud instances required for defense and banking procurement. Distribution runs through direct enterprise sales teams, systems integrator channels, and marketplace listings on SAP and Oracle cloud exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where switching costs from ERP-embedded workflow depth create durable competitive insulation. Regulatory entrenchment through pre-built compliance content libraries compounds this structural advantage.
For Market Incumbents: Pre-empt AI-native challenger encroachment by accelerating clause intelligence R&D investment and locking exclusive regulatory content partnerships with ECHA, FDA, and national banking authorities. Vertical integration into managed services for implementation and change management deepens customer dependency. Defend against Microsoft 365 ecosystem expansion by embedding contract modules deeper into financial planning and procurement-to-payment workflows.
For New Entrants and Emerging Players: Mid-market legal departments in India and Southeast Asia represent the most penetrable entry point given immature vendor compliance infrastructure and PLI scheme beneficiary growth. Specialized risk management modules for REACH substance restriction monitoring and ESG liability modeling offer differentiated positioning against full-suite incumbents. Channel partnership with regional systems integrators accelerates footprint building without direct enterprise sales investment.
For Investors and Strategic Acquirers: EU AI Act enforcement timeline compression reshapes the acquisition landscape toward platforms with pre-built explainable AI documentation capabilities. Long-term viability favors contract intelligence specialists with durable regulatory content moats over document-centric workflow tools facing generative AI commoditization. Watch for consolidation signals when mid-tier vendors miss two consecutive renewal cycles in German automotive procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Content Partnership | Exclusive ECHA and FDA feed integration locks in automotive and healthcare procurement agencies. |
| AI-Native Clause Extraction | Generative AI deployment collapses contract review timelines from weeks to hours for legal departments. |
| ERP Cloud Extension | SAP and Oracle marketplace listings capture procurement workflow spend from installed base migrations. |
| Private Cloud Certification | ECB and national banking authority audit protocols create financial services procurement entry barriers. |
| Vertical Risk Module Launch | REACH substance restriction tracking preempts supply interruption for German coatings and electronics sectors. |
Research Methodology
Operator-level perspectives from procurement directors, legal operations leads, CLM platform product managers, and systems integrator partners anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory implementation guidance. Bottom-up deployment sizing and top-down vertical spending analysis triangulated market estimates.
Scenario-bracketing framed analytical approach across the analysis window, with low-case assumptions reflecting Microsoft 365 ecosystem retention and high-case assumptions modeling EU AI Act compliance-driven replacement cycles. Segmentation dimensions modeled included solution type, deployment mode, end-user archetype, and industry vertical. CAGRs derived from regression against historical CLM adoption curves and regulatory deadline alignment.
Macroeconomic conditions sit as an overlay; deviation in enterprise software budget cycles and cloud infrastructure pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and ERP migration patterns. Material shifts in EU AI Act implementation deadlines or hyperscaler market concentration rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.