
 E-Commerce Search Software Market | 2026-2036
E-Commerce Search Software Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Search Software Market Insights
Vector embedding is hardening as the dominant retrieval architecture over traditional inverted-index systems, compressing latency budgets and improving semantic relevance scores. Algolia leverages proprietary indexing infrastructure to sustain sub-100ms query response times across distributed edge nodes. Elasticsearch anchors the open-source tier with deep integration into analytics pipelines. Bloomreach specializes in commerce-specific merchandising controls that differentiate its platform from general-purpose search layers.
E-commerce search software encompasses query interpretation, ranking, and results presentation systems purpose-built for transactional digital storefronts, typically operating with p99 latency thresholds below 200 milliseconds to prevent cart abandonment. Cloud-based deployment captures the dominant share of new implementations as retailers prioritize elastic scaling during peak traffic events without capital-intensive hardware provisioning. AI Integration functionality within the functionality segment commands expanding budget allocation as merchants demand intent prediction beyond exact-match retrieval. Retailers remain the largest end-user category, though B2B platforms represent the fastest-growing adoption profile as procurement digitization accelerates.
The EU AI Act imposes risk-classification requirements on automated decision systems including personalized search ranking, compelling vendors to document algorithmic logic and human oversight protocols. The Federal Trade Commission scrutinizes search personalization for discriminatory output patterns, while GDPR mandates explicit consent frameworks for behavioral data used in query customization. Stakeholders must weigh compliance tooling investments against feature velocity as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
Vector embedding architectures are compressing latency budgets and displacing inverted-index systems as the dominant retrieval paradigm, forcing vendors to rebuild indexing infrastructure around semantic relevance rather than keyword density.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for automated decision systems compel retailers to upgrade search personalization stacks, creating replacement demand for documented algorithmic logic and human oversight protocols.
- Fashion and apparel vertical expansion:AI-powered intent prediction replaces rule-based matching as merchandising teams demand dynamic ranking that responds to real-time inventory signals and behavioral signals.
- Edge computing infrastructure maturation:Distributed query processing nodes enable sub-100 millisecond response thresholds that prevent cart abandonment during peak traffic events.
Market Restraints
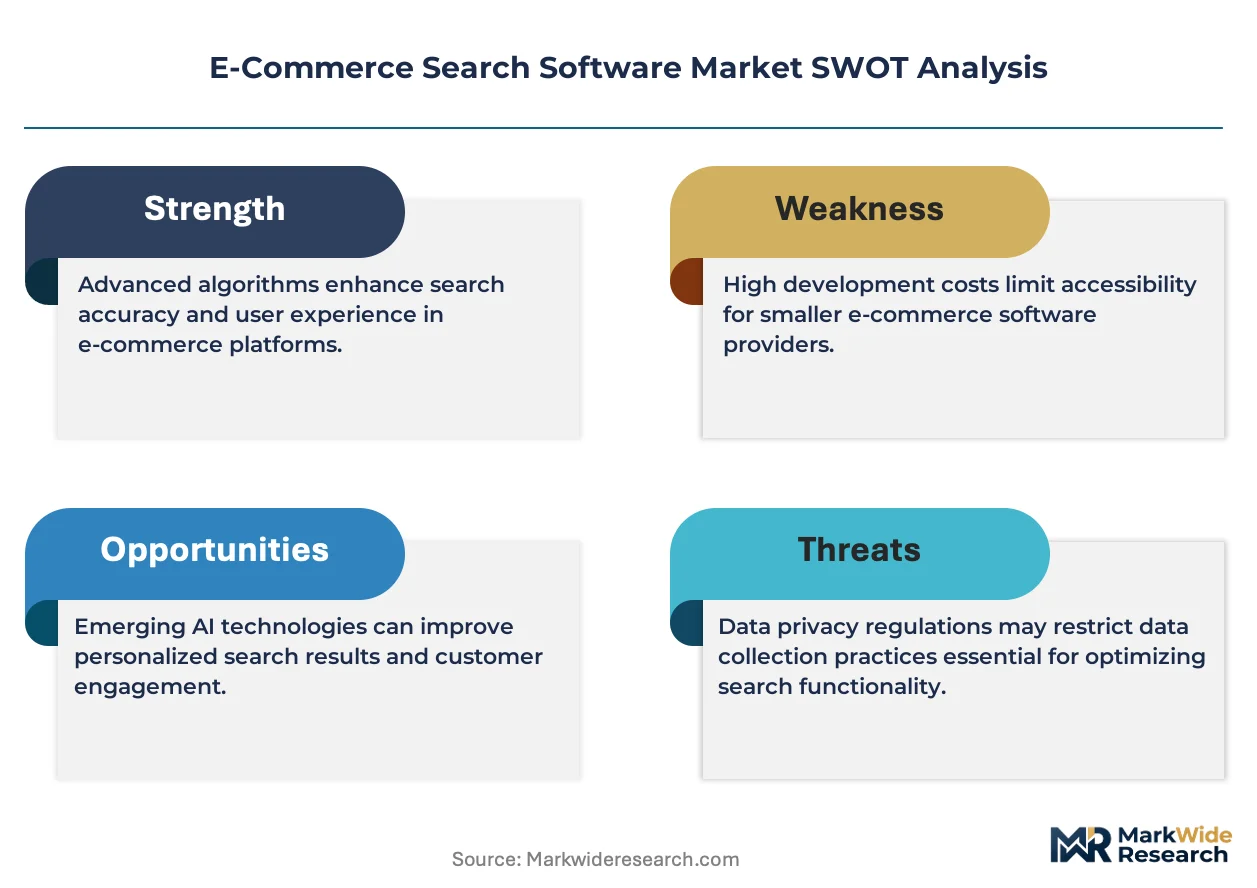
- GDPR consent framework friction:Explicit opt-in requirements for behavioral data used in query customization increase implementation complexity and reduce available training signal for personalization models.
- Specialized talent scarcity:Shortage of machine learning engineers with commerce-domain expertise constrains vendor development velocity and enterprise deployment timelines.
- Legacy system integration costs:Existing catalog management and order management platforms require expensive middleware development to expose APIs compatible with modern search layers.
Strategic Opportunities
- B2B procurement digitization:Industrial distributors and manufacturing marketplaces represent underpenetrated demand as punchout catalogs and contract pricing search replace phone-based ordering.
- Generative query expansion convergence:Large language models paired with vector retrieval enable conversational product discovery that collapses multi-step browse-to-buy funnels into single-turn interactions.
- India digital commerce infrastructure:Unified Payments Interface penetration and Open Network for Digital Commerce protocols create standardized integration targets for search vendors entering the market.
Industry Challenges
- Algorithmic audit documentation:Vendors must maintain explainability trails for ranking decisions that satisfy both EU AI Act technical documentation requirements and FTC non-discrimination scrutiny.
- Multilingual embedding quality gaps:Semantic retrieval performance degrades significantly for low-resource languages, limiting addressable market in linguistically diverse geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Search Software Market |
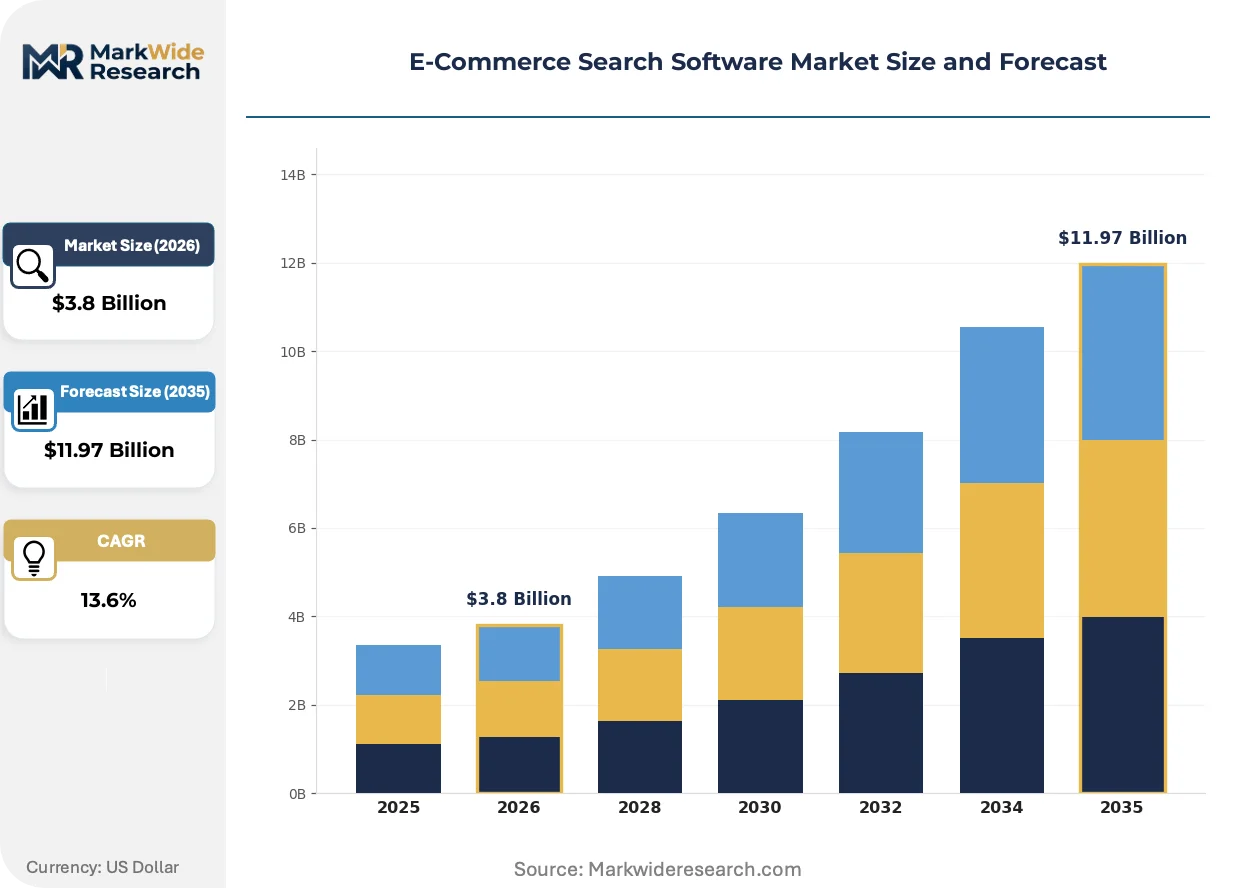
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retailers, B2B Platforms, Marketplaces, Service Providers Functionality: Natural Language Processing, Personalization, Voice Search, AI Integration Technology: Machine Learning, Big Data, Analytics, Visual Search |
| Companies Covered | Algolia, Elasticsearch, Searchanise, AddSearch, Doofinder, Bloomreach, Insider, Luigi's Box, Bayezon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Search Software Market Trends and Innovations
Retrieval architecture is undergoing fundamental reconstruction as semantic methods replace lexical matching, regulatory jurisdictions impose divergent compliance obligations, and buyer expectations compress toward instantaneous intent fulfillment.
Vector embedding is overtaking inverted-index systems as the dominant retrieval architecture. Dense neural representations encode product attributes and query intent into shared latent spaces that capture synonymy and conceptual similarity. Fashion retailers with large, visually-driven catalogs are adopting multimodal embeddings fastest. This compression of the relevance-ranking pipeline is overtaking traditional two-stage retrieve-then-rank workflows.
The EU AI Act imposes risk-classification tiers on personalized search ranking systems that process behavioral data for automated decision-making. Vendors must document training data provenance, model performance metrics, and human oversight mechanisms in technical files subject to conformity assessment. Retailers operating cross-border storefronts face the steepest compliance burden as they reconcile Brussels requirements with divergent national implementations.
Buyer tolerance for multi-step product discovery is collapsing toward single-turn intent fulfillment. Voice-activated commerce and generative interfaces trained on product knowledge graphs are displacing faceted navigation hierarchies in premium mobile applications. Grocery and fast-moving consumer goods verticals exhibit the most pronounced behavioral shift as replenishment queries bypass traditional browse patterns entirely.
E-Commerce Search Software Market Segmentation
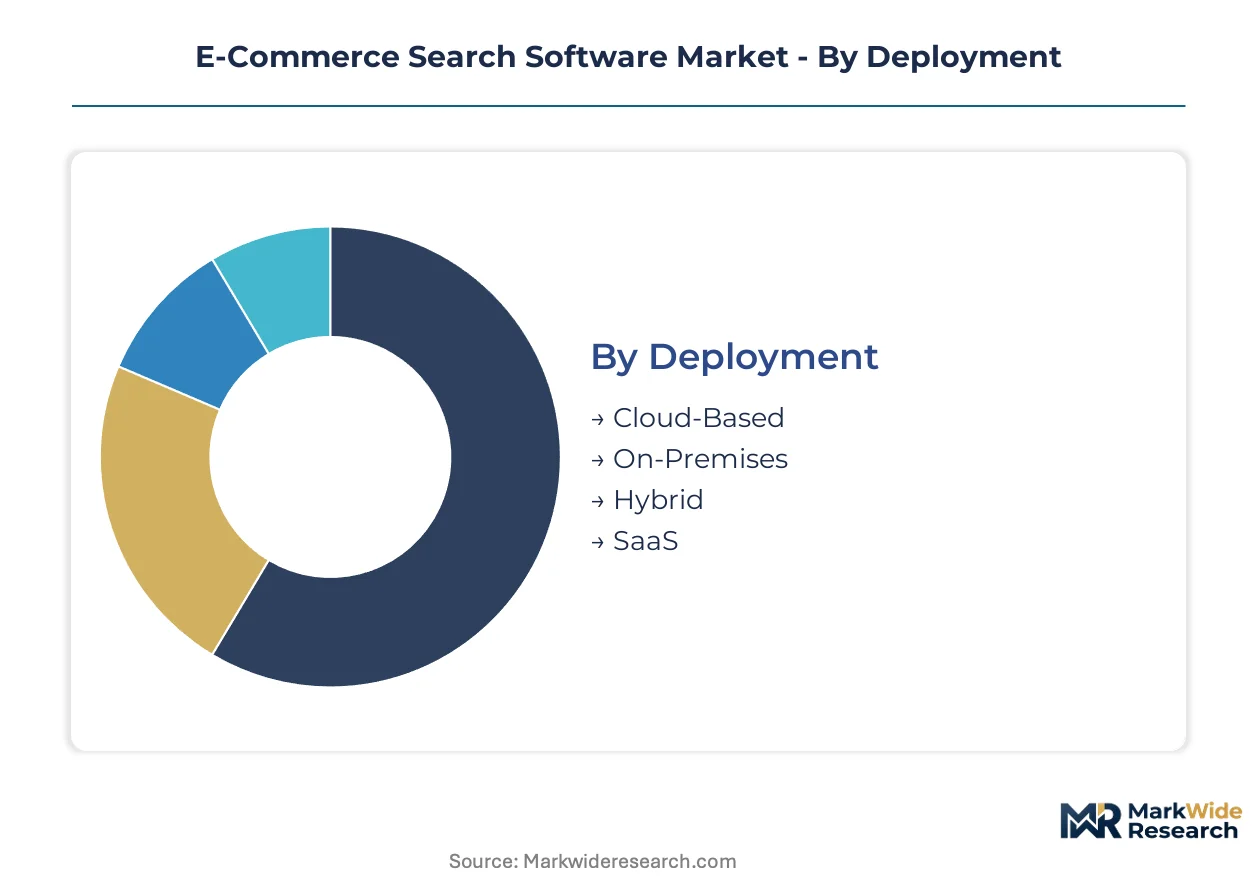
E-commerce search software segments reflect divergent infrastructure maturity and compliance burden across deployment modes. Procurement patterns cluster around latency requirements and data sovereignty obligations that reshape vendor selection criteria.
Deployment:
Standalone cloud implementations dominate new capacity additions, while embedded hybrid configurations serve legacy retail environments with strict data residency mandates.
- Cloud-Based:Distributed edge nodes enable sub-100ms query response for peak traffic events. Fashion and apparel retailers in the United States and Germany prioritize elastic scaling without hardware provisioning.
- On-Premises:Dedicated infrastructure hosts sensitive behavioral data behind corporate firewalls. German retailers facing GDPR audit requirements maintain on-premises personalization stacks to satisfy data localization obligations.
- Hybrid:Split architectures process anonymized queries in cloud layers while retaining customer profiles on-site. Indian marketplaces adopt hybrid models to reconcile UPI transaction data sensitivity with cost efficiency.
- SaaS:Subscription access to managed search layers eliminates infrastructure overhead. B2B procurement platforms favor SaaS deployments for rapid time-to-value without engineering team expansion.
Volume placements concentrate in Cloud-Based configurations; the faster expansion belongs to Hybrid architectures bridging compliance and performance demands.
End User:
Customer-type segmentation reveals divergent search complexity requirements across transaction models and catalog scales.
- Retailers:Direct-to-consumer storefronts demand real-time inventory synchronization with ranking algorithms. Apparel merchants in India leverage AI-powered visual search to compress browse-to-buy funnels.
- B2B Platforms:Contract pricing and punchout catalog integration dominate procurement digitization. Industrial distributors in Germany replace phone-based ordering with parameterized search for negotiated rate cards.
- Marketplaces:Multi-tenant architectures must reconcile divergent merchandising policies across seller bases. Indian ONDC protocol compliance shapes marketplace search standardization requirements.
- Service Providers:White-label search layers power franchise and affiliate commerce networks. US-based platform aggregators embed search APIs for mid-market retail clients lacking in-house ML engineering.
Revenue concentration sits with Retailers; B2B Platforms are climbing the fastest as procurement digitization accelerates.
Functionality:
Feature-layer segmentation tracks the displacement of rule-based matching by predictive intent systems.
- Natural Language Processing:Semantic parsing captures synonymy and conceptual relationships absent from keyword indexes. German retailers deploy multilingual NLP to serve cross-border EU storefronts.
- Personalization:Behavioral signal integration ranks results by individual propensity scores. GDPR consent friction constrains training data availability for EU-facing implementations.
- Voice Search:Conversational interfaces bypass faceted navigation for replenishment queries. Grocery verticals in the United States exhibit the steepest voice-activated commerce adoption.
- AI Integration:End-to-end neural architectures replace retrieve-then-rank pipelines. EU AI Act documentation requirements add compliance overhead to AI Integration deployments.
Budget allocation concentrates in Personalization capabilities; AI Integration is expanding most quickly as vector architectures mature.
Technology:
Technical foundation choices determine latency budgets, explainability requirements, and talent acquisition strategies.
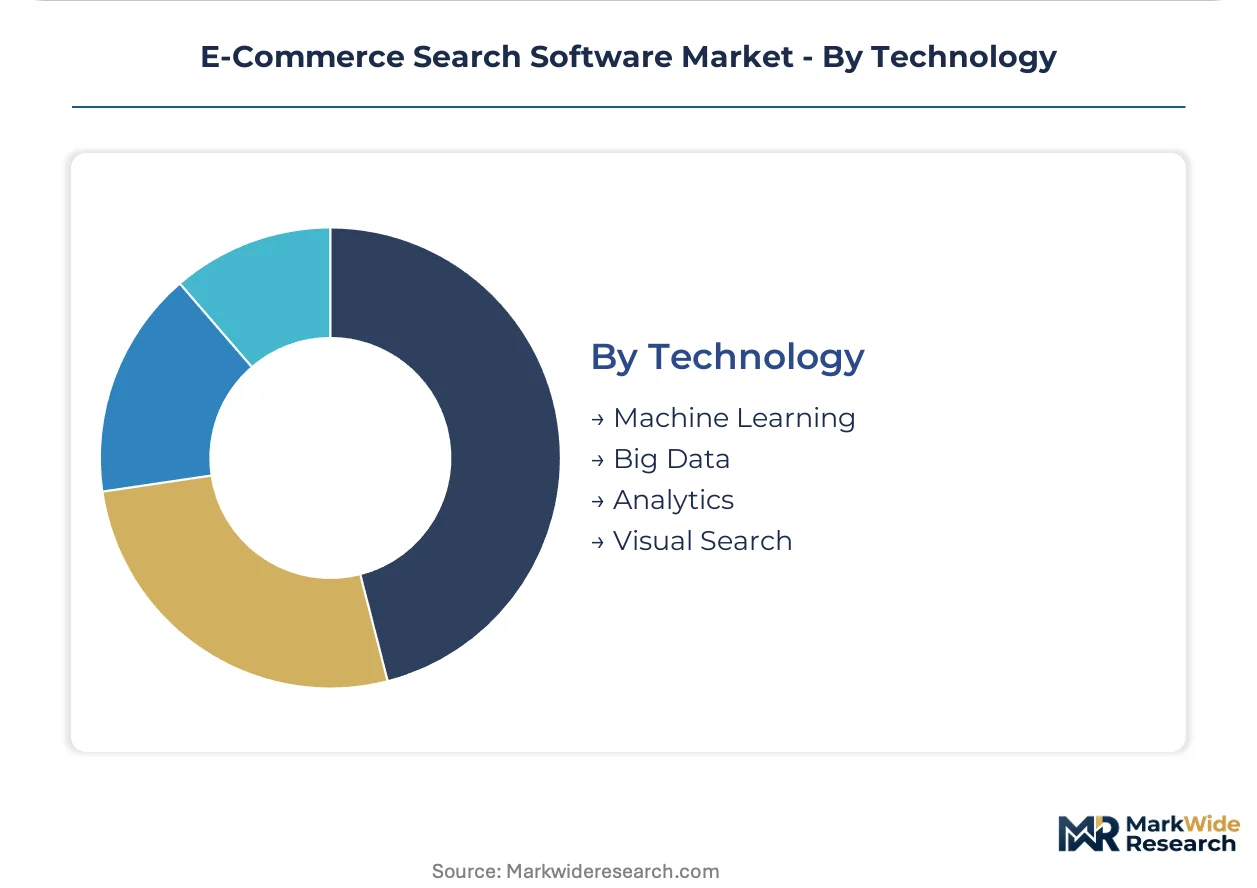
- Machine Learning:Dense embedding models encode product attributes into shared latent spaces. Specialized ML engineering scarcity constrains vendor development velocity across all geographies.
- Big Data:Distributed processing frameworks handle petabyte-scale catalog and behavioral datasets. Indian marketplaces leverage Big Data layers for real-time inventory reconciliation across fragmented seller networks.
- Analytics:Search performance telemetry feeds merchandising optimization workflows. US retailers integrate analytics pipelines with existing business intelligence infrastructure.
- Visual Search:Multimodal embeddings match photographic queries to product imagery. Fashion retailers deploy Visual Search fastest due to large image-native catalogs.
Implementation density clusters around Machine Learning foundations; Visual Search is gaining share fastest as mobile camera commerce proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Bangalore and Hyderabad accelerate vendor concentration. India's Unified Payments Interface penetration creates standardized integration targets. Digital commerce infrastructure matures fastest where regulatory sandboxes coexist with enterprise demand.
United States
Fashion retailers drive sub-100 millisecond latency requirements to prevent cart abandonment. FTC scrutiny of search personalization for discriminatory output patterns intensifies vendor documentation obligations. San Francisco Bay Area clusters host edge computing nodes for distributed query processing.
Germany
GDPR mandates explicit consent frameworks for behavioral data used in query customization. EU AI Act risk-classification requirements compel retailers to upgrade personalization stacks with human oversight protocols. Berlin and Munich industrial districts concentrate B2B procurement digitization for contract pricing search.
India
Open Network for Digital Commerce protocols create standardized integration targets for search vendors entering the market. TRAI data localization guidelines shape hybrid deployment architectures reconciling UPI transaction sensitivity with cost efficiency. Bangalore and Hyderabad SEZs host machine learning engineering talent pools for vendor R&D centers.
United Kingdom
Multilingual NLP deployments serve cross-border EU storefronts despite post-Brexit regulatory divergence. Information Commissioner's Office enforcement of GDPR consent frameworks constrains training data availability for personalization models. London fintech clusters drive SaaS adoption for rapid time-to-value without engineering expansion.
Japan
METI digital transformation subsidies accelerate cloud migration for legacy retail infrastructure. JIS standards for data interoperability reduce middleware development costs for catalog management integration. Tokyo-Osaka corridor concentrates voice-activated commerce adoption for grocery replenishment queries.
E-Commerce Search Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around three tiers: cloud-native platforms with proprietary indexing infrastructure, open-source anchored ecosystems with deep analytics integration, and commerce-specific merchandising control specialists. Strategic moves center on vector architecture migration to displace inverted-index systems and compliance tooling investments to satisfy EU AI Act documentation requirements.
Within the cloud-native tier, Algolia and Bloomreach exemplify divergent positioning around latency optimization versus merchandising control. Elasticsearch anchors the open-source tier with distributed ecosystem penetration. These three companies occupy positions that map directly to the deployment mode segmentation: edge-native infrastructure, analytics-integrated stacks, and commerce-specialized control layers.
| Leading Market Players |
|---|
| Algolia |
| Elasticsearch |
| Searchanise |
| AddSearch |
| Doofinder |
| Bloomreach |
| Insider |
| Luigi's Box |
| Bayezon |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure spot pricing indices cascade through vendor cost structures, compressing SaaS subscription tiers as hyperscaler compute rates reset quarterly. This input volatility stratifies pricing power between edge-native platforms with captive infrastructure and analytics-integrated stacks tethered to third-party hosting.
Pricing Analysis
Short lead-time provisioning commands premium SaaS tiers, while annual commitment discounts anchor standard offerings. Pricing stratifies across premium, standard, and economy tiers differentiated by query volume thresholds and SLA guarantees. Cost compression in economy tiers is intensifying because GPU embedding inference costs are falling faster than vendor pricing adjustments. Mid-market retailers exhibit the sharpest price sensitivity, whereas enterprise fashion merchants prioritize latency guarantees over subscription fees.
Supply Chain Analysis
Regional distribution centers for vector database hardware cluster in the United States, Taiwan, and South Korea. GPU accelerator supply draws from NVIDIA and AMD foundry partnerships concentrated in Taiwan Semiconductor Manufacturing. Single-source vulnerability in advanced node semiconductor fabrication poses the dominant structural risk. Distribution runs through hyperscaler marketplaces and direct enterprise licensing channels with minimal intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized ML engineering talent scarcity props vendor pricing power, constraining supply expansion faster than demand growth in vector architecture migration cycles.
For Market Incumbents: Deepen vertical integration into proprietary indexing infrastructure to escape hyperscaler compute cost volatility. Consolidate around edge node ownership in the United States and Germany where latency requirements are most stringent. Defend against open-source vector database entrants by embedding compliance tooling for EU AI Act documentation requirements. For New Entrants and Emerging Players: Launch via API-first distribution targeting Indian marketplace integrators seeking ONDC-compliant search layers. White-label visual search modules for mid-market apparel retailers in the United States represent the most penetrable segment. Position against incumbents through pre-built GDPR consent framework implementations that reduce deployment friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid-deployment specialists with German data residency certifications. Long-term viability hinges on vector architecture transition completion rather than legacy inverted-index maintenance. Monitor EU AI Act conformity assessment timelines as the critical inflection signal for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Vector Architecture Migration | Dense embedding models displace keyword indexes, forcing infrastructure rebuilds across vendor tiers. |
| Compliance Tooling Investment | EU AI Act documentation requirements create replacement demand for audited personalization stacks. |
| Edge Computing Expansion | Sub-100ms latency guarantees in the United States and Germany prevent cart abandonment during peak events. |
| B2B Procurement Platform Integration | Punchout catalog and contract pricing modules capture industrial distributor digitization in Germany. |
| Multimodal Embedding Development | Fashion retailers with image-native catalogs drive visual search adoption fastest. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with CTOs, platform engineers, IT procurement officers, and integration specialists at e-commerce vendors and retail enterprises. SEC 10-K disclosures, hyperscaler capex reports, EU AI Act technical documentation, and cloud infrastructure pricing benchmarks supplied quantitative foundations. Bottom-up deployment mode sizing and top-down regional demand aggregation cross-validated segment estimates.
Granularity-level modeling distinguished cloud-based, on-premises, hybrid, and SaaS deployment architectures across organization size tiers and vertical adoption patterns. End-user segmentation captured retailer, B2B platform, marketplace, and service provider demand profiles. Technology layer analysis tracked machine learning, big data, analytics, and visual search implementation density. CAGRs were derived from fitted growth curves against historical adoption trajectories, with elasticity adjustments for regulatory compliance cost shocks.
EU AI Act enforcement timing, TRAI data localization rule changes, and UPI transaction volume trajectories are the dominant revision risks. Forecasts reflect documented assumptions around vector architecture maturation and edge infrastructure buildout rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Austria E-Commerce Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
US Social Commerce Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
E-Commerce Apparel Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
Global Healthcare E-Commerce Market