
 Data Pipeline Market | 2026-2036
Data Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
Data Pipeline Market Analytics
Subscription-based orchestration is decoupling data pipeline software from underlying compute commitments, reshaping vendor economics. Amazon Web Services leverages its managed integration stack to anchor enterprise workloads across multi-tenant environments. Microsoft Corporation extends its position through deep embedding in enterprise productivity suites, while Google LLC specializes in AI-ready streaming infrastructure for analytics-intensive buyers.
A data pipeline is an automated sequence of processes that extracts data from sources, transforms it through validation, cleansing, and enrichment steps, and loads it into destination systems for analysis or operational use, typically orchestrated via directed acyclic graphs with latency targets measured in milliseconds for streaming and hours for batch. Cloud deployment models now dominate new spending as organizations retire on-premises extract-transform-load infrastructure, while stream processing functionality captures the fastest expansion as event-driven architectures replace scheduled batch windows. ETL retains the largest installed base but ELT is displacing it where data lakes and warehouse-native transformation reduce intermediate storage costs.
The EU AI Act, GDPR, and ISO 27001 collectively impose audit trails, data lineage documentation, and cross-border transfer controls that elevate pipeline governance from operational concern to board-level risk management. HIPAA in the United States adds patient data de-identification requirements that shape healthcare pipeline architectures. Stakeholders must weigh sovereign cloud mandates against the cost economics of centralized hyperscaler platforms when designing next-generation data movement infrastructure.
Market Dynamics
The migration from batch-scheduled extraction to event-driven streaming architectures is compressing latency requirements and forcing infrastructure rebuilds across financial services, healthcare, and industrial IoT deployments. This shift elevates real-time orchestration from a performance optimization to a core competitive capability.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions in Germany and France must deploy auditable data lineage systems by fixed deadlines, accelerating replacement of legacy ETL stacks with governed pipeline platforms.
- Algorithmic trading infrastructure:Hedge funds and proprietary trading desks in Chicago and London are demanding sub-100-millisecond data flows, pulling investment into low-latency streaming fabrics.
- Cloud-native architecture migration:Kubernetes-based orchestration is decoupling pipeline logic from compute provisioning, enabling elastic scaling that on-premises hardware cannot match.
Market Restraints
- Specialized engineering talent scarcity:Proficiency in Apache Flink, Kafka Streams, and Spark Structured Streaming commands premium compensation that constrains vendor expansion timelines.
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II rulings complicate pipeline architectures spanning European and North American cloud regions.
- Hyperscaler platform concentration:Dependency on AWS, Azure, and Google Cloud for managed integration services creates vendor lock-in risks and pricing power asymmetries.
Strategic Opportunities
- Healthcare data interoperability:HIPAA-compliant de-identification pipelines for clinical trial matching and real-world evidence generation remain underdeveloped relative to demand from research hospitals.
- Edge-to-cloud streaming:Manufacturing facilities in Japan and South Korea are deploying lightweight pipeline agents on factory floors, converging OT and IT data flows for predictive maintenance.
- ISO 27001 certification as competitive wedge:Vendors achieving certified information security management systems can displace uncertified competitors in regulated procurement cycles.
Industry Challenges
- Legacy mainframe integration complexity:COBOL-based core banking systems in incumbent financial institutions resist standard API connectivity, requiring costly custom connector development.
- Data quality engineering bottlenecks:Schema drift detection, anomaly flagging, and automated remediation demand scarce machine learning operations expertise that outpaces supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Pipeline Market |
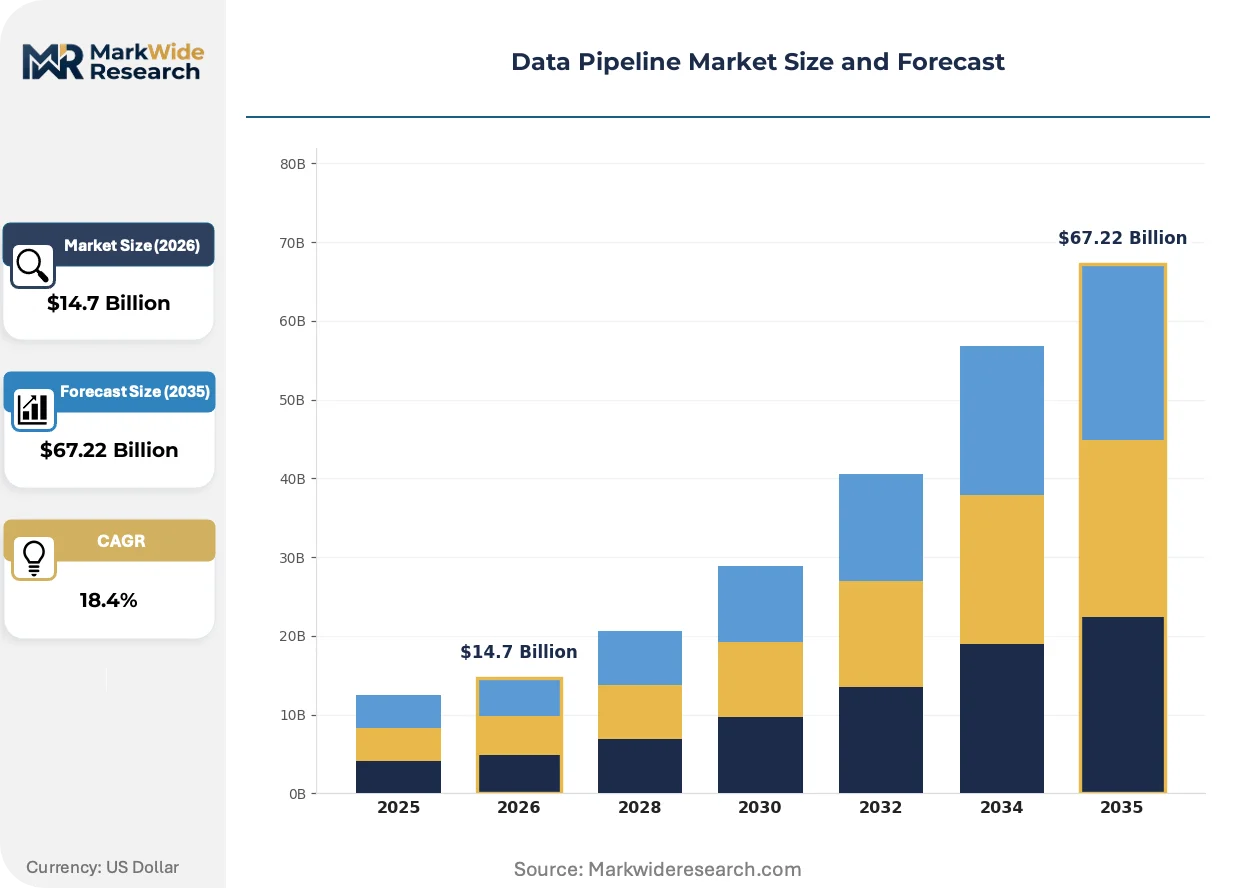
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $67.22 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Multi-Cloud Data Source Type: Structured, Unstructured, Semi-Structured, Real-Time Functionality: Batch Processing, Stream Processing, ETL, ELT End User: IT Services, Healthcare, Retail, Telecommunications |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Google LLC, IBM Corporation, Oracle Corporation, SAP SE, Snowflake, Fivetran, Airbyte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Pipeline Market Evolving Landscape
Pipeline architecture is bifurcating into two competing design philosophies: warehouse-native transformation that pushes compute to destination systems, and stream-native processing that distributes logic across edge, regional, and central tiers. This technical divergence is fragmenting vendor roadmaps and buyer evaluation criteria.
Apache Flink is automating stateful stream processing with exactly-once semantics, enabling financial services firms in Singapore and Switzerland to deploy complex event processing for fraud detection without manual checkpoint management. Capital markets technology teams are adopting it faster than batch-oriented alternatives. The technology is automating operational burdens that previously required dedicated site reliability engineering headcount.
REACH substance registration requirements and the EU AI Act's risk classification framework are forcing industrial manufacturers to document data provenance for supply chain emissions and algorithmic decision systems. Chemical producers must now maintain immutable audit trails from sensor ingestion through regulatory reporting. German automotive suppliers are rebuilding pipelines to capture material composition data at the component level.
Enterprise buyers are consolidating vendor relationships around integrated data platform suites rather than best-of-breed point solutions. Procurement teams in United States healthcare systems now favor vendors offering unified governance, catalog, and pipeline orchestration over specialized streaming-only providers. This preference shift disadvantages pure-play stream processing vendors lacking adjacent data management capabilities.
Data Pipeline Market Segmentation
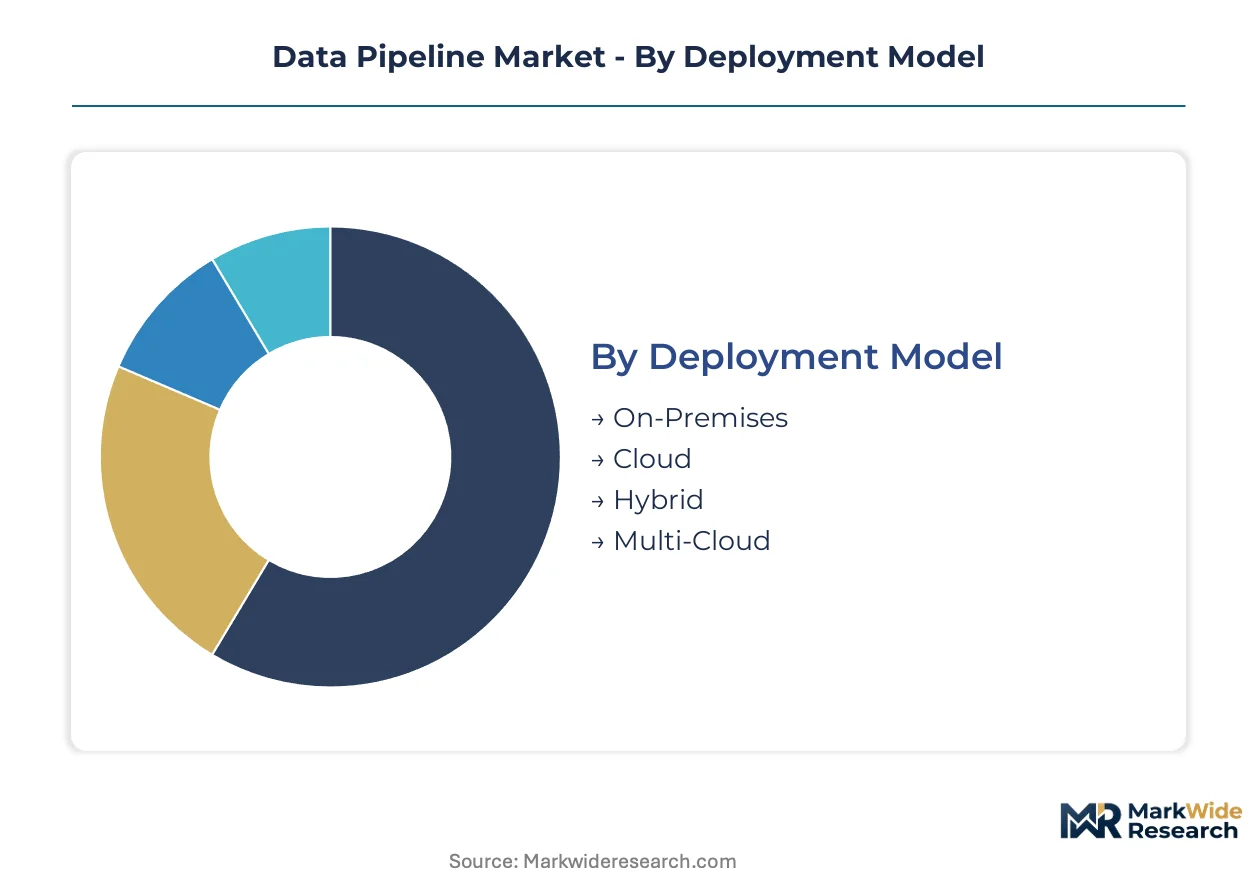
Segmentation in the data pipeline market reveals how architectural choices cascade through cost structures, compliance postures, and talent requirements. Buyers select deployment models and processing paradigms that align with latency tolerances, regulatory jurisdictions, and existing infrastructure investments.
Deployment Model:
Cloud-native orchestration has redefined how organizations provision pipeline infrastructure, shifting capital expenditure to operational models with elastic scaling characteristics.
- Cloud:Fully managed services eliminate hardware procurement cycles and enable automatic scaling based on data volume fluctuations. Financial services firms in Singapore and the United States favor this model for algorithmic trading infrastructure where burst capacity matters.
- Hybrid:Combines on-premises data residency for sensitive workloads with cloud bursting for peak processing demands. German automotive suppliers deploy this architecture to satisfy GDPR data localization requirements while accessing cloud analytics for supply chain optimization.
- On-Premises:Retained where sovereign data mandates or legacy system integration demands physical infrastructure control. Defense contractors and classified government facilities maintain this deployment pattern.
- Multi-Cloud:Distributes pipeline stages across AWS, Azure, and Google Cloud to mitigate vendor lock-in and optimize service-specific capabilities. Hedge funds in London use this approach to arbitrage pricing differences across hyperscaler platforms.
Cloud leads on scale; Multi-Cloud leads on momentum.
Data Source Type:
Source characteristics dictate ingestion architecture, schema enforcement strategies, and preprocessing complexity before data reaches transformation layers.
- Real-Time:Event streams from IoT sensors, trading feeds, and application logs demand sub-second latency with exactly-once processing guarantees. Manufacturing facilities in Japan deploy these pipelines for predictive maintenance on production equipment.
- Structured:Relational database exports and API responses with predefined schemas enable straightforward mapping to warehouse tables. Enterprise resource planning integrations dominate this category.
- Unstructured:Text documents, images, and video files require extraction pipelines with computer vision or natural language processing stages. Healthcare systems in the United States process radiology imaging through these workflows.
- Semi-Structured:JSON logs, XML configurations, and NoSQL exports balance flexibility with partial schema enforcement. E-commerce platforms rely on this category for clickstream and cart abandonment analytics.
Structured leads on scale; Real-Time leads on momentum.
Functionality:
Processing paradigms determine where computation occurs, how latency budgets are allocated, and whether intermediate storage layers add cost and failure modes.
- Stream Processing:Continuous data flow analysis with stateful operators and windowed aggregations enables immediate anomaly detection. Fraud prevention teams at payment processors in Switzerland deploy Apache Flink for transaction scoring.
- ELT:Loads raw data to destination systems before transformation, exploiting warehouse compute for processing. Data lake architectures favor this approach to minimize data movement.
- ETL:Traditional extract-transform-load patterns with intermediate staging databases retain the largest installed base in legacy enterprise environments.
- Batch Processing:Scheduled execution of data movement jobs suits non-time-sensitive reporting and regulatory filings with defined submission deadlines.
ETL leads on scale; Stream Processing leads on momentum.
End User:
Industry verticals impose distinct compliance frameworks, latency requirements, and integration complexity that shape pipeline procurement criteria.
- Healthcare:HIPAA-mandated audit trails and patient de-identification requirements dominate architecture decisions. Research hospitals in the United States build pipelines for clinical trial matching and real-world evidence generation.
- IT Services:Managed service providers aggregate multi-tenant pipeline operations across client environments with standardized monitoring and cost allocation.
- Retail:Omnichannel inventory synchronization and customer 360 profiles drive demand for unified data movement across point-of-sale, e-commerce, and loyalty platforms.
- Telecommunications:Network equipment telemetry and subscriber usage patterns require high-throughput ingestion for capacity planning and churn prediction.
IT Services leads on scale; Healthcare leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing data pipeline investments as firms migrate workloads toward jurisdictions with clearer compliance frameworks and lower cost-of-compliance gaps. The EU AI Act's fixed implementation deadlines have compressed upgrade cycles in Germany and France, while Singapore and Switzerland attract latency-sensitive financial workloads through permissive sandbox regimes. United States hyperscaler investments continue deepening, though cross-border data transfer friction with Europe is forcing architectural fragmentation.
United States
HIPAA-mandated audit trails and de-identification requirements drive healthcare pipeline procurement from research hospitals in Boston and the Mayo Clinic network. The SEC's climate disclosure rules and FDA's real-world evidence guidance create dual compliance pressures for pharmaceutical and financial data flows. Silicon Valley hyperscaler campuses and Chicago trading floors anchor the highest-density deployments of sub-100-millisecond streaming infrastructure for algorithmic trading.
Germany
German automotive suppliers under REACH substance registration mandates are rebuilding pipelines to capture component-level material composition data from sensor ingestion through regulatory reporting. The EU AI Act's risk classification framework forces industrial manufacturers to document data provenance for algorithmic decision systems. Bavaria's manufacturing corridor and Stuttgart's supplier ecosystem concentrate edge-to-cloud streaming deployments for predictive maintenance.
Singapore
Monetary Authority of Singapore sandbox licenses enable hedge funds and proprietary trading desks to deploy sub-100-millisecond data flows with lighter-touch supervision than European equivalents. The city-state's data protection regime offers GDPR adequacy without Schrems II complexity, attracting regional headquarters for multi-national pipeline architectures. Marina Bay financial district houses the densest cluster of Apache Flink deployments for fraud detection in Southeast Asia.
Switzerland
Swissmedic pharmaceutical traceability requirements and FINMA's audit expectations shape pipeline governance for clinical trial data and wealth management platforms. The country's non-EU GDPR adequacy status permits smoother cross-border transfers than neighboring jurisdictions, attracting pharmaceutical data lakes from Basel's Roche and Novartis operations. Zurich's private banking sector drives demand for immutable lineage documentation in multi-generational client data architectures.
Japan
METI's data free flow with trust initiative and industrial IoT subsidies accelerate factory-floor pipeline deployments for predictive maintenance. Manufacturing facilities in Toyota City and Osaka's industrial belt deploy lightweight pipeline agents converging OT and IT data flows. The country's pharmaceutical regulator PMDA drives serialization requirements that mandate end-to-end pipeline traceability for drug distribution networks.
Data Pipeline Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscaler platforms consolidating enterprise workloads while open-source orchestration vendors capture developer-led adoption. The vendor base organizes into three tiers: cloud-native platforms with managed integration stacks, best-of-breed streaming specialists, and legacy ETL incumbents migrating to subscription models. Strategic moves concentrate on M&A to fill governance gaps and capacity expansion in sovereign cloud regions to satisfy data localization mandates.
Within the hyperscaler tier, Microsoft Corporation and Amazon Web Services exemplify divergent anchoring strategies—productivity suite embedding versus managed infrastructure lock-in—while Google LLC occupies a position emphasizing AI-ready streaming for analytics-intensive buyers. Among enterprise software incumbents, IBM Corporation and Oracle Corporation represent the legacy migration archetype, retooling on-premises ETL installed bases for cloud-native orchestration. These five entities collectively anchor procurement patterns across financial services, healthcare, and industrial verticals, with their roadmap decisions cascading through buyer evaluation criteria.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Google LLC |
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Snowflake |
| Fivetran |
| Airbyte |
| Others |
Value Network & Pricing Analysis
Financial services procurement teams at Chicago hedge funds and Singaporean trading desks concentrate buying power around subscription-based orchestration models that decouple software costs from underlying compute commitments. This buyer concentration shapes vendor pricing strategies across the data pipeline market.
Pricing Analysis
Capacity additions in hyperscaler cloud regions are reshaping price floors for managed pipeline services. Three-tier pricing structure across premium, standard, and economy levels dominates, with ISO 27001 certification and sub-100-millisecond latency guarantees driving tier placement. Cost compression in standard tiers is intensifying because open-source alternatives erode differentiation. Healthcare systems show highest price sensitivity due to HIPAA compliance overhead, while algorithmic trading desks prioritize latency over cost.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certifications gate supplier qualification for regulated procurement cycles, filtering vendor participation. Engineering talent concentrates in the United States, Germany, and Singapore. Supply chains draw from Apache Kafka, Apache Flink, and Kubernetes open-source ecosystems. Single-source vulnerability runs through hyperscaler platform concentration at AWS, Azure, and Google Cloud. Distribution runs through direct enterprise sales and cloud marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's fixed implementation deadlines compound regulatory demand, creating sustained procurement pressure for auditable data lineage systems across financial services and industrial manufacturing.
For Market Incumbents: Extend governance capabilities into adjacent data catalog and quality management domains to defend against best-of-breed point solution encroachment. Build ISO 27001 certification moats in healthcare and financial services procurement cycles. Capacity additions in sovereign cloud regions address data localization mandates threatening centralized hyperscaler architectures. For New Entrants and Emerging Players: EU AI Act compliance mandates in Germany and France open a window for specialized audit-trail documentation tools targeting mid-tier automotive suppliers. Healthcare data interoperability for HIPAA-compliant de-identification pipelines remains underdeveloped relative to demand from United States research hospitals. A channel partnership strategy with managed service providers accelerates multi-tenant deployment traction. For Investors and Strategic Acquirers: Hyperscaler platforms are the most active acquirer in this space, consolidating orchestration, catalog, and governance capabilities into unified suites. Long-term viability favors vendors with warehouse-native and stream-native architectural flexibility. Watch Apache Flink adoption velocity in Singaporean fraud detection deployments as an inflection indicator for streaming infrastructure preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies pipeline orchestration with data catalog and governance for healthcare procurement cycles. |
| Geographic Expansion | Establishes sovereign cloud regions in Germany and Switzerland to satisfy GDPR data localization requirements. |
| Acquisition of Specialist Firm | Fills stream processing gaps in legacy ETL installed bases at incumbent financial institutions. |
| Strategic Partnership | Links edge-to-cloud streaming agents with manufacturing execution systems in Japan's automotive sector. |
| Product Launch | Introduces HIPAA-compliant de-identification pipelines for clinical trial matching at United States research hospitals. |
Research Methodology
Multiple input streams — primary interviews with platform engineers, IT procurement officers, and integration specialists; secondary validation through SEC filings, hyperscaler capex disclosures, and open-source project commit analytics — were reconciled through bottom-up and top-down triangulation. Data pipeline architecture decisions at financial services firms in Singapore and healthcare systems in the United States provided demand-side calibration.
Historical spending patterns were cross-referenced against panel input from vendor product managers and enterprise architects. Segmentation dimensions modeled include deployment model, processing paradigm, end-user vertical, and regional regulatory cluster. CAGRs were derived from elasticity analysis across cloud infrastructure investment cycles and compliance-driven upgrade timelines. Apache Flink adoption rates and Kubernetes orchestration penetration served as technology diffusion inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Schrems II rulings disrupting transatlantic data flows. Model outputs reflect assumptions about hyperscaler pricing power and open-source commercialization velocity. A model refresh is warranted upon material change in EU AI Act enforcement timelines or sovereign cloud mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
India ICT Market
Digital Solutions
Inventory Management Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Procure-To-Pay Solutions Market
Digital Solutions
Web Performance Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Business As a Service Market