
 Global Drilling Data Management Systems Market | 2026-2036
Global Drilling Data Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drilling Data Management Systems Market Foresight
Real-time analytics integration with edge computing nodes is tilting the technology stack toward decentralized data processing at the rig site. Schlumberger leverages its subsurface intelligence heritage to anchor deep wellbore analytics capabilities. Pason Systems competes through specialized rig-site hardware that sustains high-fidelity data capture under harsh drilling conditions.
Drilling Data Management Systems comprise software platforms, edge devices, and communication infrastructure that aggregate, validate, and analyze operational parameters from drill bits, downhole sensors, and surface equipment. These systems typically process pressure, temperature, vibration, and rate-of-penetration data at sub-second intervals to enable geosteering decisions and mechanical dysfunction detection. Cloud-Based solutions lead deployment preference among supermajors seeking centralized reservoir modeling, while Edge Computing segments attract interest from remote offshore operations where satellite bandwidth constraints limit backhaul. Predictive Maintenance technology applications are expanding fastest as operators prioritize non-productive time reduction.
API standards alongside BSEE well control regulations in the United States and Norway's PSA framework govern data integrity requirements for safety-critical drilling decisions. The EU AI Act introduces algorithmic transparency obligations for automated drilling recommendations deployed in European waters. Stakeholders must weigh interoperability investments against proprietary platform lock-in as operator consortiums press for open data standards.
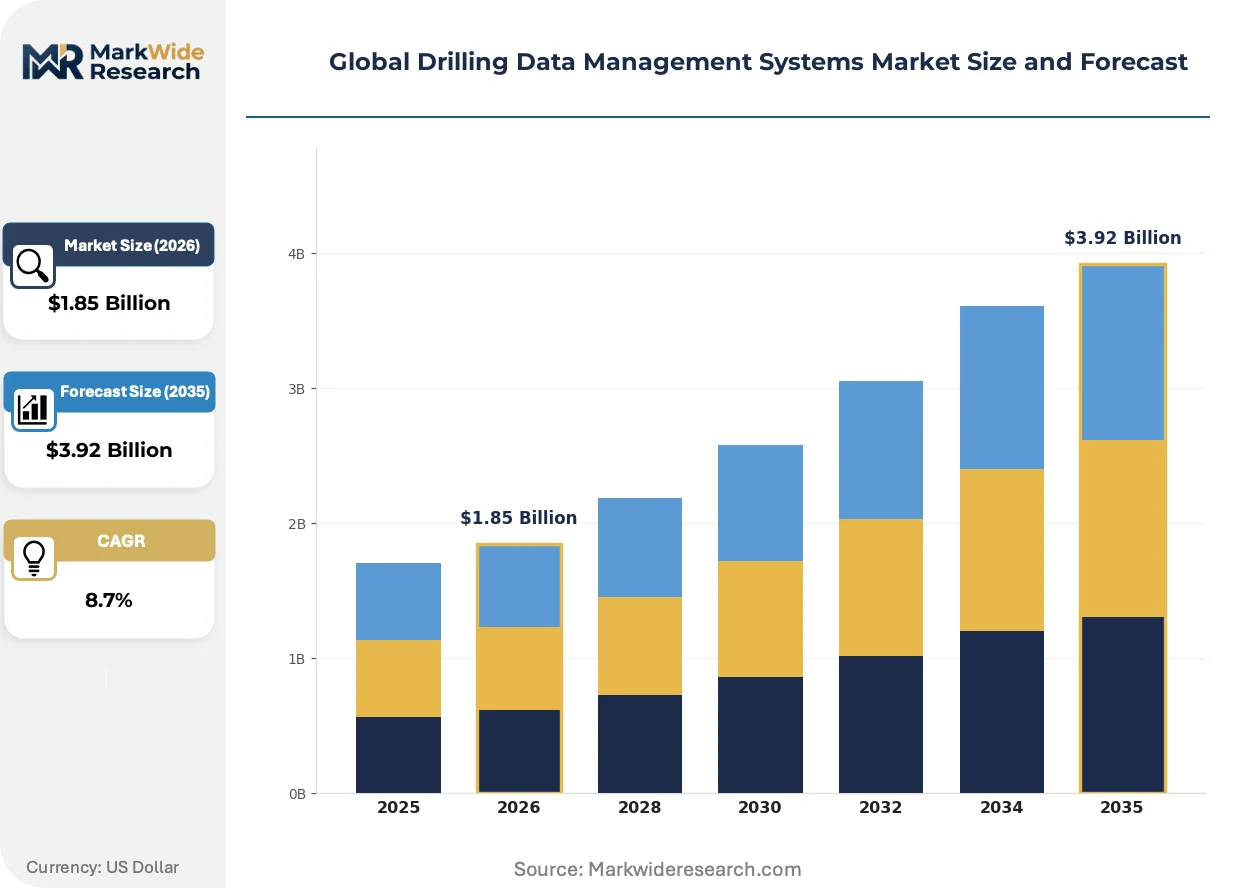
Market Dynamics
Edge computing deployment at the rig site is fragmenting data processing architectures, forcing vendors to rebuild platforms for sub-second latency rather than cloud-centric batch analytics. This decentralization is redrawing competitive boundaries between subsurface software specialists and hardware-integrated service providers.
Growth Catalysts
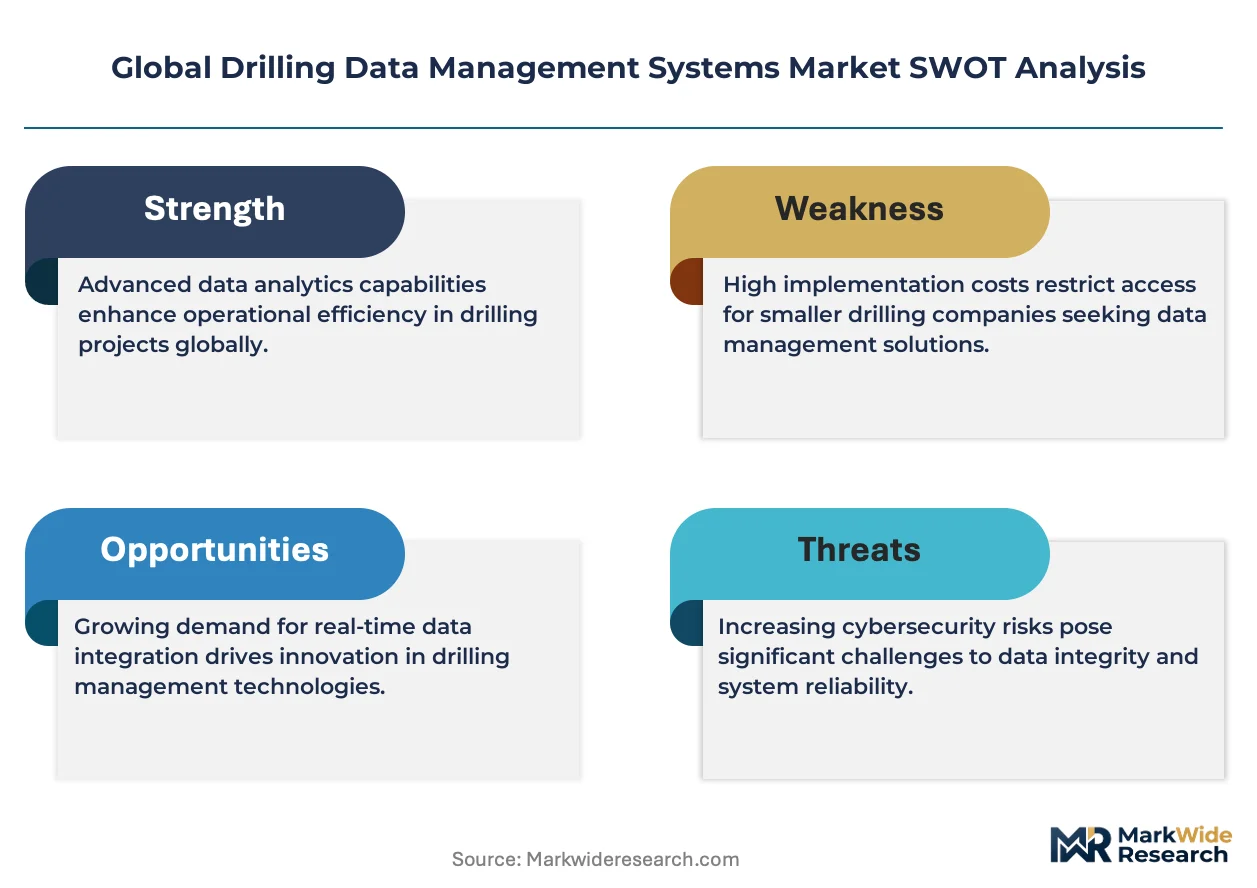
- EU AI Act transparency mandates:Automated drilling recommendation systems in European waters face new algorithmic disclosure requirements, accelerating investment in explainable machine learning frameworks by system developers.
- Sichuan shale basin instrumentation:China's national oil companies are mandating real-time data capture across horizontal laterals exceeding 3,000 meters, creating concentrated demand for high-bandwidth telemetry infrastructure.
- Predictive maintenance modules:Offshore contractors in the North Sea corridor are prioritizing non-productive time reduction through vibration signature analysis and bit-wear forecasting algorithms.
Market Restraints
- Satellite bandwidth economics:Remote offshore installations face prohibitive backhaul costs for full-fidelity data streams, constraining cloud-dependent architectures in West African and Southeast Asian deepwater blocks.
- Sensor supply concentration:High-temperature downhole pressure transducers rely on a limited set of quartz crystal suppliers, creating vulnerability to geopolitical disruptions in semiconductor feedstocks.
- API standard fragmentation:Competing data interoperability specifications between operator consortiums and vendor proprietary formats inflate integration costs for multi-rig fleet deployments.
Strategic Opportunities
- Brazil pre-salt digitalization:Petrobras-led consortiums are retrofitting legacy floating production facilities with integrated data platforms, opening retrofit markets for edge-computing hardware vendors.
- Geothermal drilling crossover:Hard-rock drilling parameters from oil and gas operations are transferring to enhanced geothermal systems, creating application expansion in Nevada and Turkey.
- Norway PSA real-time reporting:The Petroleum Safety Authority's incident notification requirements are mandating automated data validation pipelines, creating regulatory tailwinds for quality-assurance software modules.
Industry Challenges
- Petrophysicist-data engineer hybrid roles:Interpretation of real-time streaming data requires subsurface expertise combined with edge-device troubleshooting skills that existing training pipelines rarely produce.
- Legacy SCADA integration:Decades-old rig control systems use proprietary protocols that resist API-standard connectivity, forcing expensive middleware development for unified dashboards.
- Cybersecurity certification timelines:IEC 62443 compliance for safety-critical drilling networks extends vendor validation cycles by 12-18 months, delaying product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drilling Data Management Systems Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premises, Hybrid, Edge Computing Technology: Real-Time Analytics, Machine Learning, IoT Integration, Data Visualization, Predictive Maintenance Application: Well Planning, Rig Performance Monitoring, Drill Optimization, Safety Compliance End User: Exploration Companies, Drilling Contractors, Petrochemical Firms, Energy Consultants |
| Companies Covered | Weatherford International, Pason Systems, Schlumberger, Honeywell International, Emerson Electric, Halliburton, NOV Inc., ABB, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drilling Data Management Systems Market Shifts & Advancements
Real-time analytics architectures are bifurcating between centralized reservoir modeling platforms and decentralized rig-site intelligence, with vendors forced to support both paradigms simultaneously. This dual-track development is compressing R&D timelines and reshaping partnership strategies across the supply base.
Digital twin technology is migrating from post-drilling forensic analysis to live wellbore simulation. Supermajors operating in the Gulf of Mexico are deploying these virtual replicas during active geosteering operations, compressing decision cycles from hours to minutes. The technology is migrating from desktop reservoir engineering suites to edge-computing nodes physically mounted on drilling packages.
Norway's PSA framework is tightening real-time data integrity requirements for well control decisions, mandating redundant sensor validation and automated anomaly flagging. This regulatory pressure is forcing vendors to rebuild data pipelines with cryptographic provenance tracking. Offshore contractors are responding by consolidating vendor relationships to reduce compliance audit surface area.
Subscription-based software licensing is displacing perpetual ownership models among independent drilling contractors. These capital-constrained operators in the Permian Basin and Alberta oil sands are prioritizing operational expenditure flexibility over upfront platform investments. The shift is most visible among mid-tier contractors with fleets under 20 rigs, where cash flow predictability outweighs long-term total cost of ownership considerations.
Global Drilling Data Management Systems Market Segmentation
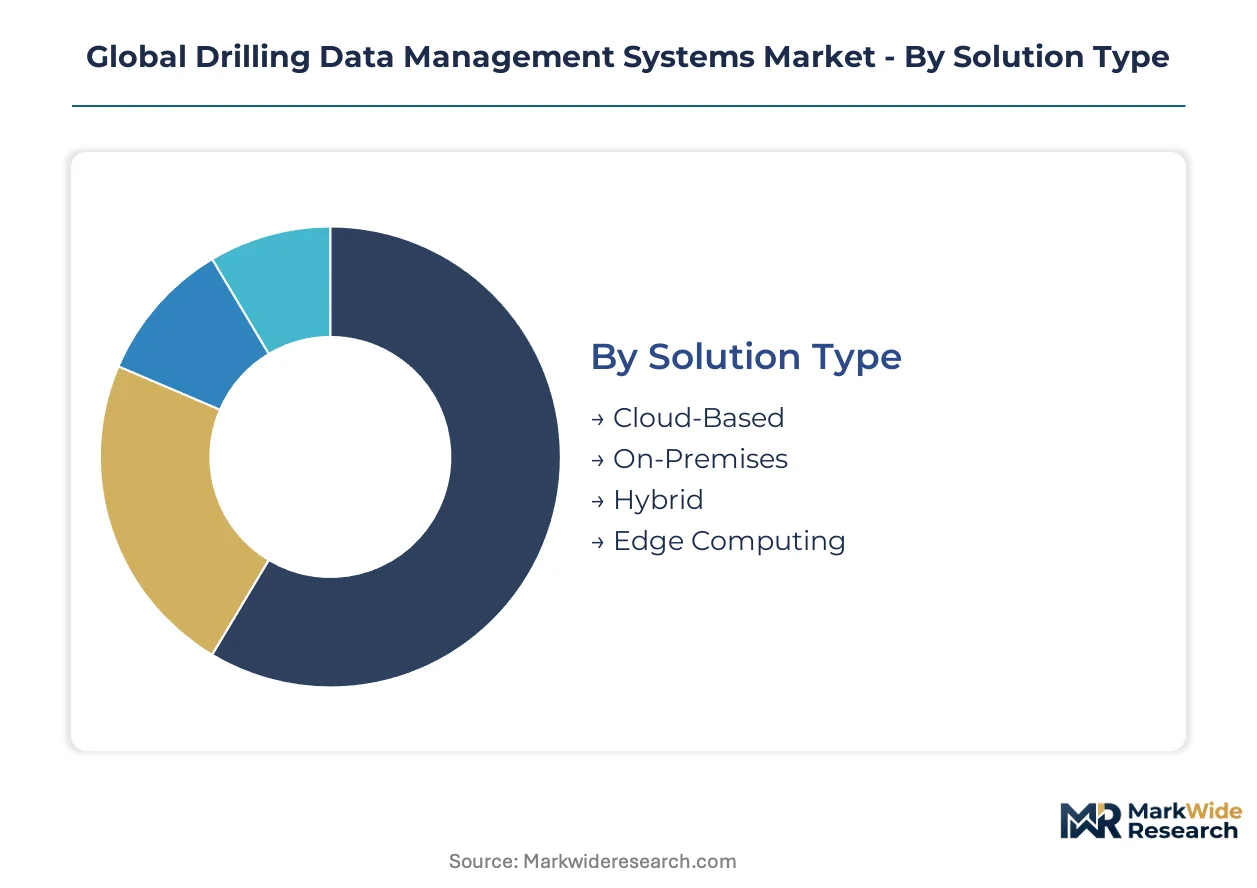
Segmentation in drilling data management systems reflects divergent infrastructure strategies across offshore and onshore operations. Cloud-centric supermajors prioritize centralized reservoir modeling, while remote contractors demand edge-resilient architectures. These splits determine vendor R&D allocation and partnership structures.
Solution Type:
Cost tier differentiation separates capital-intensive upfront deployments from operational expenditure models favored by cash-constrained contractors.
- Cloud-Based:Centralized platforms aggregate multi-rig fleets through satellite or fiber backhaul, enabling unified dashboards for reservoir engineers. Demand concentrates among Gulf of Mexico supermajors seeking cross-asset analytics, though bandwidth economics constrain adoption in West African deepwater.
- Edge Computing:Ruggedized nodes process sub-second telemetry locally, sustaining operations through intermittent connectivity. North Sea contractors facing PSA real-time reporting mandates prioritize these deployments for autonomous anomaly detection without cloud dependency.
- On-Premises:Legacy server installations persist among national oil companies with data sovereignty requirements.
- Hybrid:Split architectures synchronize critical well control data locally while batch-transferring historical logs to cloud reservoirs.
Cloud-Based commands the established base. The steepest expansion runs through Edge Computing.
Technology:
Application maturity varies sharply, with proven diagnostics sitting alongside emerging algorithmic capabilities.
- Predictive Maintenance:Vibration signature analysis and bit-wear forecasting algorithms reduce non-productive time through mechanical dysfunction early warning. Offshore contractors in Norway's North Sea corridor drive adoption as rig dayrates amplify downtime costs.
- Real-Time Analytics:Sub-second processing of pressure, temperature, and rate-of-penetration data enables geosteering decisions during active drilling. China's Sichuan shale basin instrumentation mandates create concentrated demand for high-fidelity telemetry pipelines.
- Machine Learning:Pattern recognition for stuck-pipe prediction and formation pressure estimation.
- IoT Integration:Sensor mesh connectivity spanning drill bits, downhole tools, and surface equipment.
- Data Visualization:3D wellbore rendering and time-series dashboards for remote operations centers.
Real-Time Analytics anchors current investment. Predictive Maintenance is climbing the fastest as contractors prioritize uptime economics.
Application:
Functional scope spans the drilling lifecycle from pre-spud planning through post-incident forensics.
- Drill Optimization:Automated parameter recommendations for weight-on-bit and rotary speed maximize rate-of-penetration while minimizing tool wear. Permian Basin independents deploy these modules to compress drilling curves amid lateral length extension.
- Safety Compliance:Automated data validation pipelines satisfy BSEE well control regulations and Norway PSA incident notification requirements. Cryptographic provenance tracking is becoming mandatory for algorithmic drilling recommendations in EU waters under the AI Act.
- Well Planning:Pre-drill simulation and offset well analysis for trajectory design.
- Rig Performance Monitoring:Equipment utilization tracking and crew efficiency metrics.
Drill Optimization holds the revenue concentration. Safety Compliance is gaining share fastest through regulatory tailwinds.
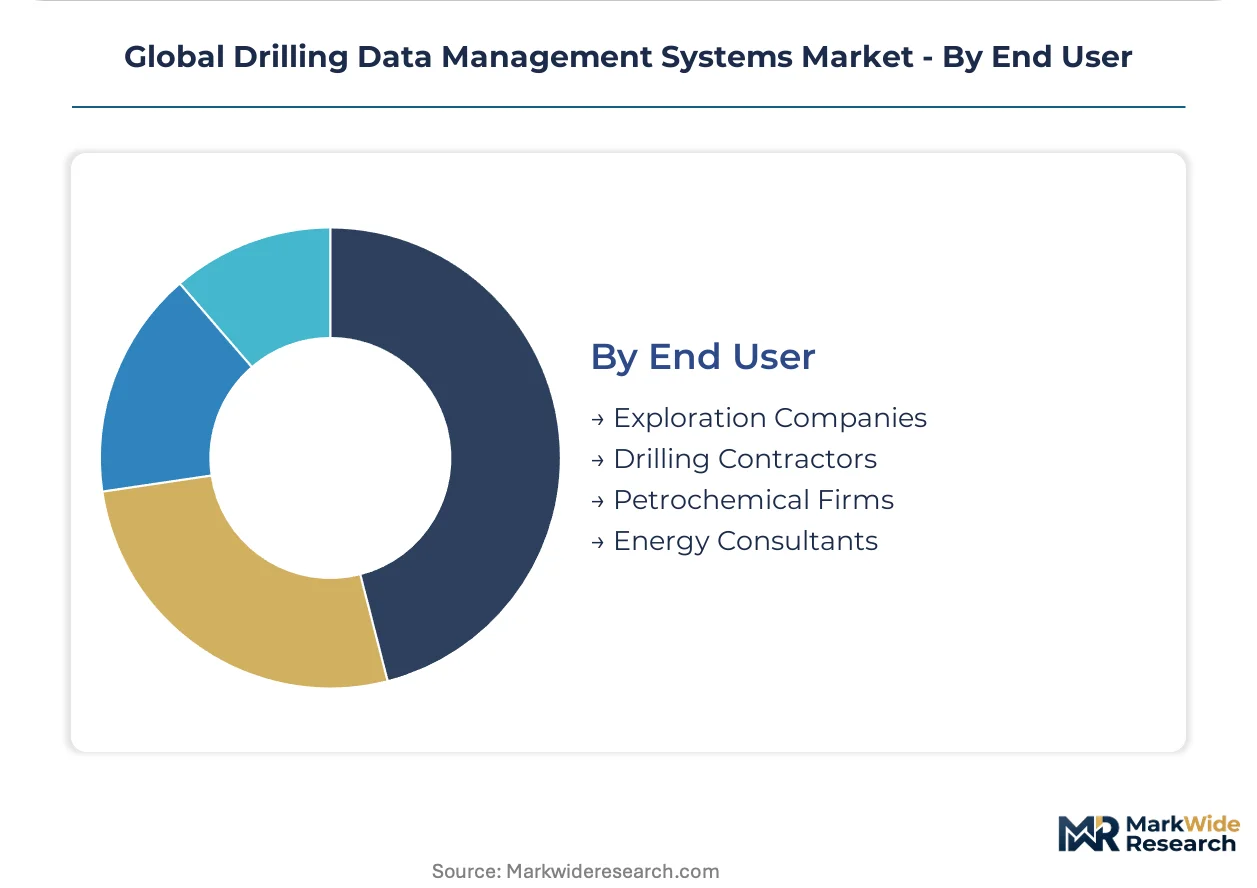
End User:
Customer type determines procurement complexity, from integrated operator consortiums to specialized service providers.
- Drilling Contractors:Fleet-wide standardization across 20+ rig portfolios drives volume procurement of edge hardware and subscription software licenses. These capital-constrained operators in Alberta oil sands prioritize operational expenditure flexibility over upfront platform investments.
- Exploration Companies:Focused deployments supporting single-asset or single-basin development programs.
- Petrochemical Firms:Downstream integration of drilling data with refinery planning systems.
- Energy Consultants:Advisory services bundling data interpretation with reservoir engineering expertise.
Drilling Contractors dominate procurement volume. Exploration Companies show the most rapid technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermajor operators and offshore drilling contractors concentrate procurement in four distinct national markets. Each geography presents divergent infrastructure constraints and regulatory frameworks that shape deployment architecture preferences.
United States
Gulf of Mexico supermajors drive centralized cloud analytics adoption for cross-asset reservoir modeling. BSEE well control regulations mandate automated data validation pipelines for safety-critical drilling decisions. Houston anchors vendor R&D operations and hosts the largest concentration of integrated data platform deployments.
Norway
North Sea contractors prioritize edge computing resilience under intermittent satellite connectivity conditions. The Petroleum Safety Authority's real-time reporting requirements enforce cryptographic provenance tracking for algorithmic drilling recommendations. Stavanger clusters subsurface software specialists serving Equinor-led consortiums.
China
National oil companies mandate high-fidelity telemetry across Sichuan shale basin laterals exceeding 3,000 meters. MIIT cybersecurity standards and data sovereignty requirements favor on-premises server installations over foreign cloud platforms. Chengdu anchors domestic edge-hardware manufacturing for basin-specific instrumentation.
Brazil
Petrobras-led pre-salt digitalization creates retrofit demand for legacy floating production facilities. ANP operational safety regulations govern real-time data integrity for well control systems. Rio de Janeiro hosts the primary vendor engineering centers supporting deepwater edge-computing retrofits.
Global Drilling Data Management Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure. The vendor base fragments between subsurface software heritage firms and hardware-integrated service providers. Three strategic archetypes dominate: full-service energy technology conglomerates, specialized rig-site instrumentation specialists, and industrial automation multinationals. M&A activity concentrates on edge-computing capability acquisition, while strategic partnerships reshape data interoperability consortiums.
Within the full-service archetype, Schlumberger and Halliburton occupy positions anchored by subsurface intelligence heritage and integrated service portfolios. Pason Systems exemplifies the specialized rig-site instrumentation tier with focused hardware-software integration. Among industrial automation multinationals, Honeywell International and Emerson Electric represent scale-driven entries leveraging process control expertise into drilling data architectures.
| Leading Market Players |
|---|
| Weatherford International |
| Pason Systems |
| Schlumberger |
| Honeywell International |
| Emerson Electric |
| Halliburton |
| NOV Inc. |
| ABB |
| Baker Hughes |
| Others |
Supply & Pricing Matrix
Quartz crystal suppliers in Japan and Germany anchor the high-temperature downhole pressure transducer tier, capturing margin pools that resist commoditization despite downstream software price compression. This upstream concentration forces edge-computing hardware vendors to absorb component volatility while subscription-based software providers push operational expenditure models to drilling contractors.
Pricing Analysis
Cost-plus contracts with Brent crude indexation dominate offshore deployment agreements, linking system pricing to hydrocarbon economics. Three-tier pricing structure across premium certified, standard compliant, and economy sensor tiers separates API-standard validated modules from basic telemetry hardware. Pricing pressure stems from satellite bandwidth economics constraining full-fidelity data backhaul in West African deepwater blocks. Independent drilling contractors in the Permian Basin exhibit highest price sensitivity, prioritizing SaaS flexibility over upfront platform investments.
Supply Chain Analysis
Extended payment terms from 90 to 180 days characterize supplier financing arrangements as national oil companies leverage procurement scale. Manufacturing concentrates in China for edge-hardware assembly, Norway for subsurface software development, and the United States for ruggedized rig-site instrumentation. Supply chain risk centers on single-source vulnerability for quartz crystal feedstocks amid semiconductor geopolitical restrictions. Distribution runs through integrated service company channels and direct vendor relationships with supermajor operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where switching costs embedded in legacy SCADA integration and regulatory certification entrench incumbent positions against new entrants.
For Market Incumbents: Insulate market position through backward integration into quartz crystal sensor manufacturing to neutralize supply vulnerability, while accelerating IEC 62443 cybersecurity certification pipelines to extend compliance audit advantages over hardware-integrated challengers. Prioritize API-standard interoperability investments to reduce operator consortium pressure for open data formats. For New Entrants and Emerging Players: Pursue white-space opportunities in Brazil pre-salt retrofit markets where legacy floating production facilities demand edge-computing hardware without incumbent service bundling. Target geothermal drilling crossover applications in Nevada and Turkey where hard-rock parameter transfer from oil and gas operations creates unguarded demand. Lead with subscription-based SaaS pricing to bypass capital-constrained contractor procurement barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rig-site instrumentation specialists holding concentrated North Sea and Gulf of Mexico customer relationships but lacking cloud analytics scale. Five-to-ten year viability hinges on successful edge-to-cloud architecture pivots. Monitor BSEE and Norway PSA regulatory enforcement intensity as inflection indicator for quality-assurance software module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Hardware Acquisition | Consolidates sub-second telemetry capability for PSA-mandated autonomous anomaly detection. |
| API Standard Interoperability Consortium | Reduces integration cost inflation from competing data format specifications across multi-rig fleets. |
| Geothermal Application Expansion | Transfers oil and gas drilling parameters to enhanced geothermal systems in Nevada and Turkey. |
| Cybersecurity Certification Acceleration | Compresses IEC 62443 validation cycles to capture safety-critical drilling network procurement windows. |
| Subscription Licensing Model Transition | Aligns with capital-constrained Permian Basin and Alberta contractor preference for operational expenditure flexibility. |
Research Methodology
A spread of perspectives from drilling contractors, subsurface software engineers, edge-hardware procurement leads, and petroleum safety authority regulators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with fleet operations managers at supermajor operators and technical directors at specialized rig-site instrumentation vendors. Secondary validation drew from BSEE incident databases, Norway PSA audit reports, API standard documentation, and customs records for high-temperature sensor trade flows. Bottom-up rig-count modeling and top-down energy service expenditure triangulation anchored volume estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon, with segmentation modeled by solution type, technology application, and end-user procurement archetype. Deployment architecture preferences bifurcated between cloud-centric supermajors and edge-resilient offshore contractors. CAGRs derived from rig activity trajectories, satellite bandwidth cost curves, and regulatory mandate implementation schedules. Industry-specific inputs included Sichuan shale basin lateral extension targets and Brazil pre-salt floating production facility retrofit pipelines.
Sensitivities concentrate around satellite bandwidth cost volatility, quartz crystal supply disruption scenarios, and EU AI Act algorithmic transparency enforcement timing. Forecasts reflect documented assumptions about edge computing adoption rates and regulatory compliance investment cycles. Macroeconomic hydrocarbon price deviation, geopolitical semiconductor restriction escalation, or accelerated AI Act implementation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
IT Asset Management (ITAM) Software Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Global Competitive Intelligence Tools Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Global Parking Reservation System Market
Digital Solutions
Government Open Data Management Platform Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
API Management Market
Digital Solutions
Global Referral Management Market