
 Global Saas Customer Relationship Management (CRM) Market | 2026-2036
Global Saas Customer Relationship Management (CRM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Saas Customer Relationship Management (CRM) Market Foresight
Enterprise-grade AI integration is rotating SaaS CRM procurement toward platforms with predictive analytics and automated workflow engines. Salesforce leverages its AppExchange ecosystem to sustain developer loyalty across verticals. Microsoft Dynamics anchors mid-market penetration through native Office 365 integration. Oracle differentiates via deep database connectivity for complex enterprise deployments.
Global SaaS Customer Relationship Management (CRM) denotes cloud-hosted software delivering customer data management, sales pipeline orchestration, and marketing automation through multi-tenant architectures with API-first interoperability. These systems process contact records, interaction histories, and revenue forecasts to unify commercial operations across distributed teams. Sales automation within the solution offering dimension commands the largest installed base, while analytics platform deployments are expanding fastest as buyers prioritize outcome-based vendor relationships. Public cloud deployment retains volume leadership, though hybrid cloud configurations are gaining traction among financial services firms with data residency obligations.
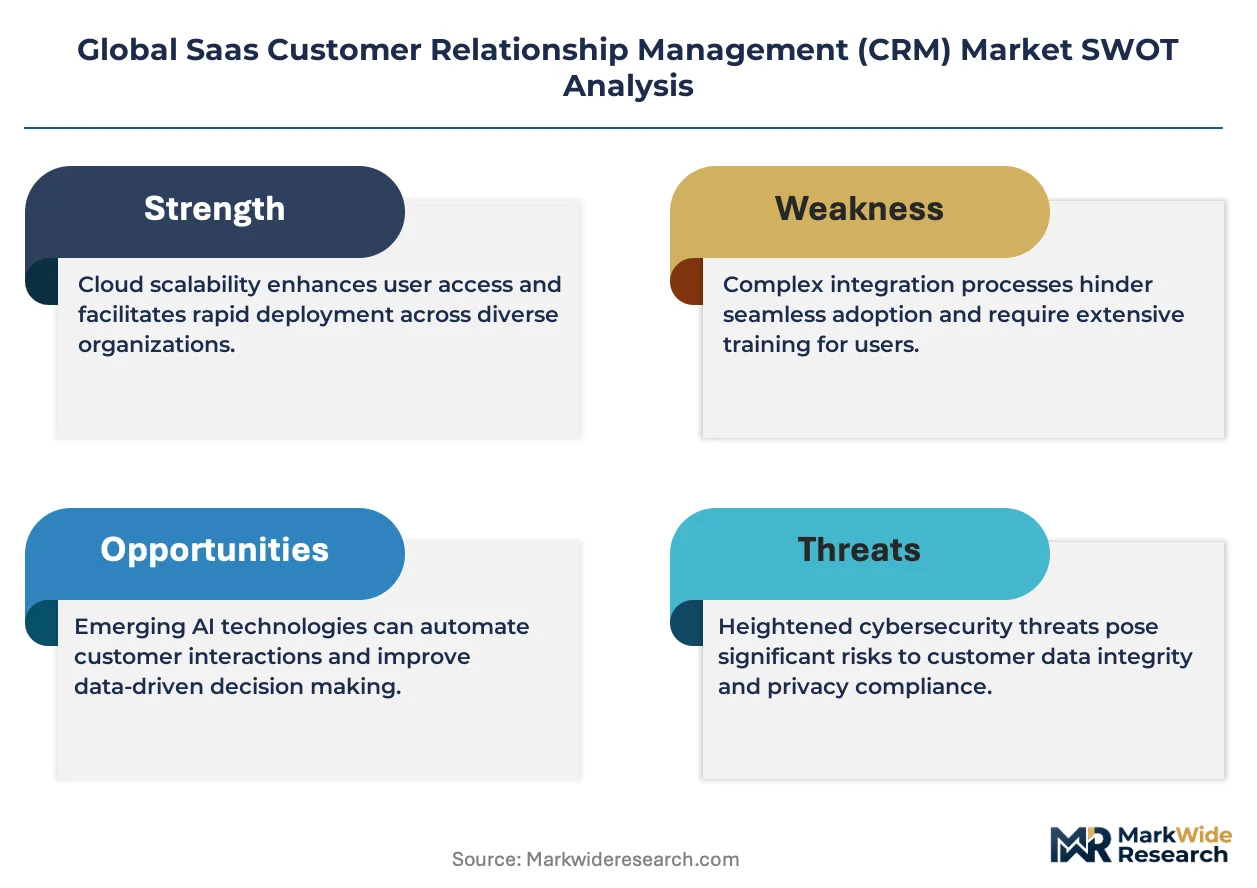
FDA oversight of healthcare CRM data handling, EU GDPR requirements for cross-border customer data transfers, and India's TRAI guidelines on telemarketing consent collectively elevate compliance architecture to a competitive differentiator. The EU AI Act's risk classification framework for automated customer scoring is forcing platform redesigns ahead of enforcement milestones. Stakeholders must evaluate whether their current vendor's regulatory roadmap aligns with jurisdiction-specific certification timelines before committing to multi-year contracts.
Market Dynamics
Enterprise migration toward predictive AI workflows is compressing vendor evaluation cycles and elevating compliance architecture to a primary selection criterion.
Growth Catalysts
- EU AI Act risk classification:Automated customer scoring mandates are forcing platform redesigns, creating replacement demand for certified architectures ahead of enforcement milestones.
- Healthcare patient engagement rules:HIPAA-covered entities and FDA-regulated device manufacturers require audit-ready CRM stacks, expanding vertical-specific procurement.
- India SME digitization:PLI scheme incentives and TRAI-mandated telemarketing consent frameworks accelerate cloud CRM adoption among mid-market distributors.
Market Restraints
- Cross-border data transfer friction:GDPR adequacy decisions and Schrems II litigation create legal uncertainty for US-hosted deployments serving European buyers.
- API dependency concentration:Critical workflow automation relies on three dominant messaging infrastructure providers, creating single-point-of-failure exposure.
- Specialized compliance talent scarcity:Shortage of professionals holding both cloud architecture and healthcare privacy certifications extends implementation timelines.
Strategic Opportunities
- Brazil ANVISA pharmaceutical traceability:Serialization mandates create first-mover advantage for CRM platforms integrating lot-tracking and adverse-event reporting.
- Edge-AI inference convergence:On-device natural language processing enables real-time sentiment analysis without data residency violations.
- Embedded finance distribution:Banking-as-a-Service APIs allow CRM vendors to capture payment flows previously handled by separate treasury systems.
Industry Challenges
- ISO 27001 certification backlog:Audit queue delays at accredited bodies extend enterprise sales cycles by four to eight months.
- Mainframe integration complexity:COBOL-era policy administration systems at incumbent insurers resist standard API protocols, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Saas Customer Relationship Management (CRM) Market |
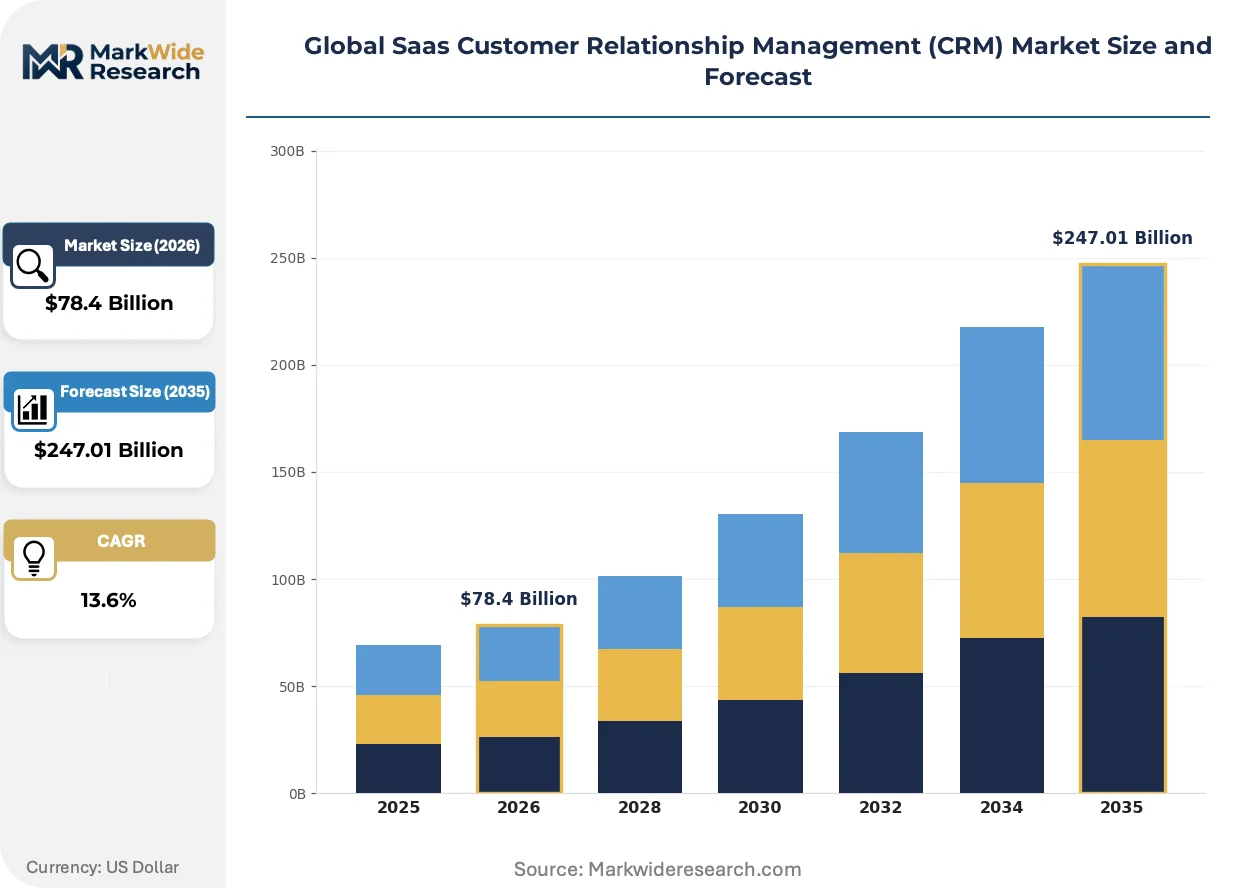
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Sales Automation, Marketing Automation, Customer Support, Analytics Platform, Partner Management Use Case: Lead Management, Contact Management, Pipeline Management, Performance Tracking, Customer Retention End User: Small Business, Mid-Sized Enterprises, Large Corporations, Non-Profit Organizations |
| Companies Covered | Salesforce, Microsoft Dynamics, Oracle, SAP, HubSpot, Zoho, Adobe, Freshworks, International Business Machines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Saas Customer Relationship Management (CRM) Market Shifts & Advancements
Workflow automation architectures are fragmenting into specialized components, with buyers assembling best-of-breed stacks rather than accepting monolithic suites.
Embedded machine learning inference engines are miniaturizing predictive lead scoring into browser-based execution environments. Mid-market sales teams deploy these capabilities without dedicated data science headcount. The technology is miniaturizing enterprise-grade analytics into consumable microservices that bypass traditional IT procurement gates.
EU AI Act enforcement timelines are compressing vendor certification roadmaps for high-risk automated decision systems. Platform providers must document algorithmic transparency and human oversight mechanisms before 2026 deadlines. Financial services CRM deployments across Germany, France, and the Netherlands face the most immediate compliance retrofit obligations.
Subscription bundling patterns are unbundling as procurement teams reject all-in-one pricing for granular consumption metrics. Healthcare providers and professional services firms now negotiate usage-based contracts tied to active contact records rather than seat licenses. This shift is most pronounced in US hospital systems and UK National Health Service trusts migrating from perpetual licenses.
Global Saas Customer Relationship Management (CRM) Market Segmentation
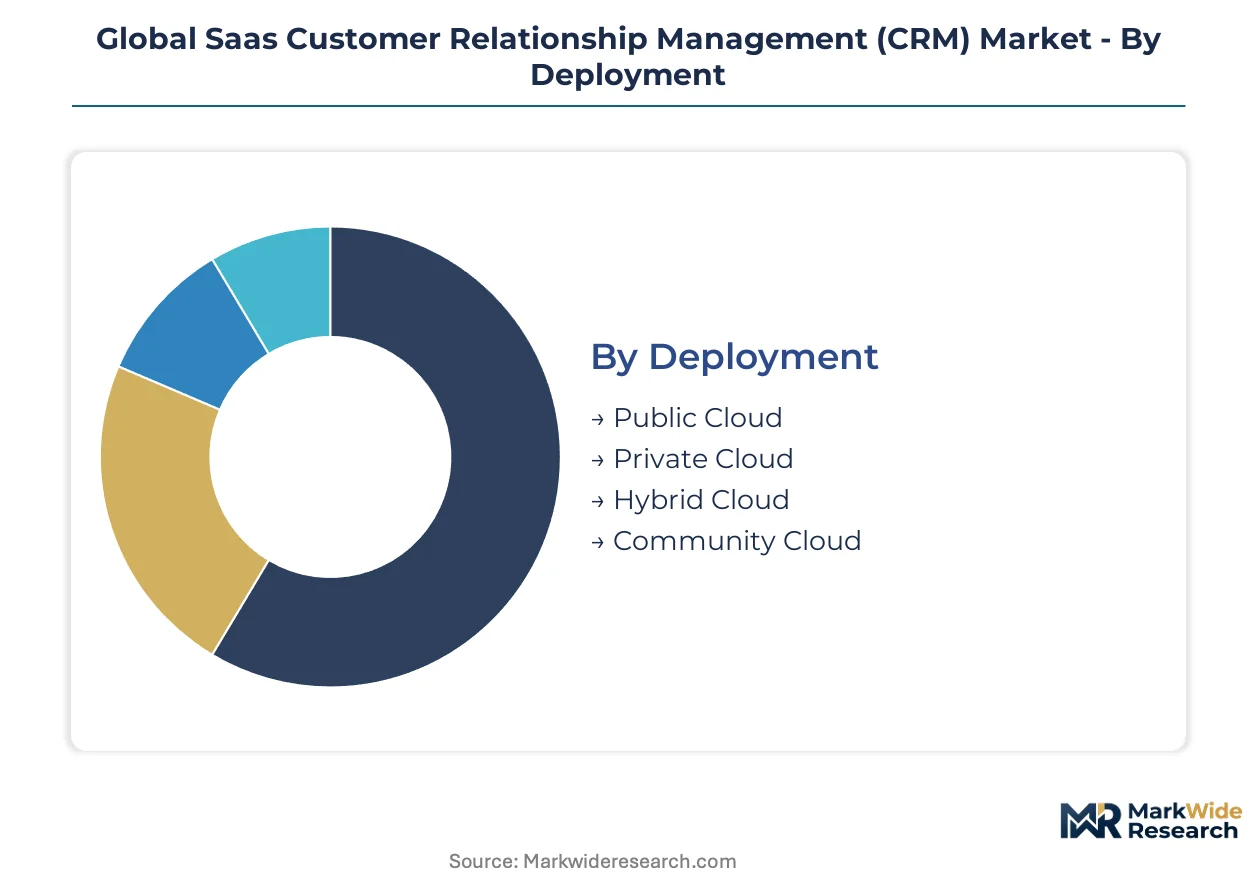
SaaS CRM buyers fragment sharply across deployment architectures and functional requirements, with substitution pressure intensifying where on-premise legacy systems still anchor customer data workflows. Procurement teams evaluate segments against compliance mandates, integration complexity, and per-seat economics rather than feature breadth alone.
Deployment:
Public cloud configurations face mounting substitution pressure from hybrid alternatives as data residency rules harden across regulated industries.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute and storage through shared resource pools with API-first interoperability. Financial services firms in Germany and France are retreating from pure public deployments under GDPR adequacy uncertainty and Schrems II litigation exposure.
- Private Cloud:Single-tenant environments isolate customer data within dedicated virtual networks with customizable encryption protocols. Healthcare providers in the US deploy private instances to satisfy HIPAA audit requirements and FDA data integrity guidelines for device manufacturers.
- Hybrid Cloud:Workload orchestration splits sensitive records across on-premise vaults and cloud analytics layers. India's banking sector accelerates hybrid procurement under RBI data localization mandates for customer transaction histories.
- Community Cloud:Sector-specific infrastructure serves consortia with shared compliance frameworks and mutualized security audits. Pharmaceutical distributors in Brazil leverage community deployments to align with ANVISA serialization traceability requirements.
Public Cloud retains volume leadership; Hybrid Cloud holds the steepest expansion curve as regulatory fragmentation deepens.
Solution Offering:
Cost tier stratification separates enterprise analytics investments from commoditized sales automation seats.
- Sales Automation:Pipeline orchestration modules manage opportunity stages, forecast probabilities, and quota attainment across distributed field teams. Mid-sized distributors in India prioritize sales automation under PLI scheme digitization incentives and TRAI-mandated consent frameworks.
- Marketing Automation:Campaign orchestration engines segment audiences, trigger behavioral workflows, and attribute revenue across touchpoints. EU enterprises demand marketing platforms with EU AI Act-compliant algorithmic transparency documentation for automated scoring.
- Customer Support:Case management systems route inquiries, track resolution SLAs, and unify interaction histories across channels.
- Analytics Platform:Predictive engines surface churn risk, lifetime value projections, and next-best-action recommendations.
- Partner Management:Channel orchestration tools coordinate co-selling motions, deal registration, and margin protection across indirect routes.
Sales Automation retains volume leadership; Analytics Platform climbs the fastest as outcome-based vendor relationships displace seat-license procurement.
Use Case:
Application maturity varies widely, with pipeline management approaching commoditization while performance tracking demands specialized data science integration.
- Lead Management:Prospecting workflows capture inbound inquiries, score engagement signals, and route qualified opportunities to sales queues. US hospital systems deploy lead management to coordinate patient acquisition across service lines under tightening CMS quality metrics.
- Contact Management:Unified profiles consolidate demographic, behavioral, and transactional records across departmental silos. UK National Health Service trusts migrate contact databases to cloud platforms under NHS Digital interoperability mandates.
- Pipeline Management:Stage-gate frameworks track deal progression, identify bottlenecks, and forecast close dates.
- Performance Tracking:Dashboards visualize rep attainment, activity ratios, and conversion metrics against targets.
- Customer Retention:Health-scoring algorithms flag at-risk accounts and trigger proactive engagement protocols.
Contact Management retains volume leadership; Performance Tracking gains share fastest as distributed teams demand real-time visibility without IT intervention.
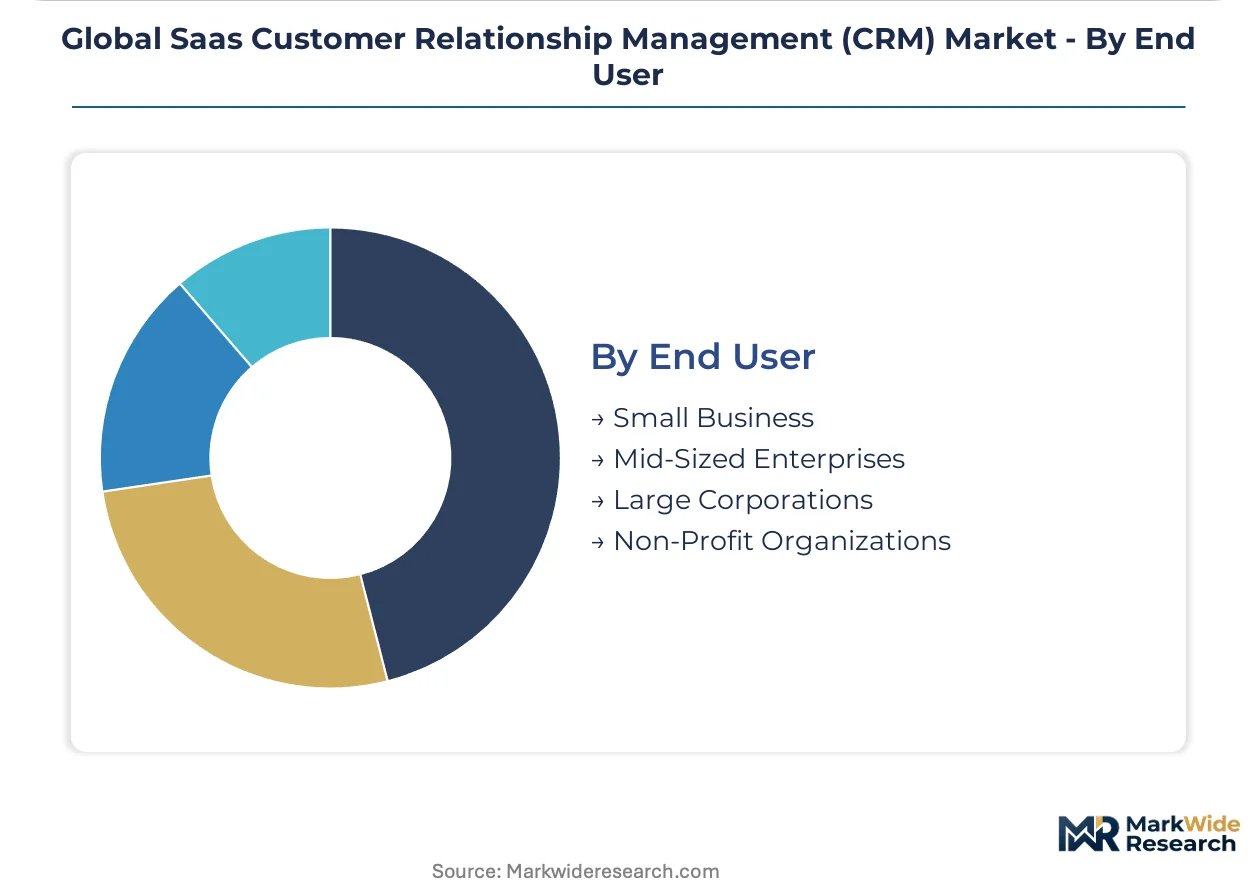
End User:
Customer type concentration tilts toward mid-market enterprises where procurement autonomy meets sufficient scale for platform customization.
- Small Business:Lightweight configurations prioritize rapid deployment, pre-built templates, and per-user pricing without implementation services. India's SME distributor segment accelerates adoption under government digitization schemes and GST compliance automation requirements.
- Mid-Sized Enterprises:Scalable architectures balance standardization across business units with vertical-specific workflow customization. German mid-market manufacturers evaluate CRM platforms against EU AI Act certification timelines for automated customer scoring.
- Large Corporations:Global deployments mandate multi-currency, multi-language, and multi-entity consolidation with enterprise security certifications.
- Non-Profit Organizations:Donor-centric configurations track giving histories, stewardship cycles, and grant compliance with restricted fund accounting.
Mid-Sized Enterprises retain volume leadership; Small Business shows the steepest expansion trajectory as self-service onboarding and usage-based pricing dismantle traditional seat-license barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering resources concentrate disproportionately in the United States, Germany, and India, with regulatory divergence forcing localized compliance architectures rather than global platform homogeneity.
United States
Enterprise healthcare providers and financial institutions drive procurement volume under HIPAA audit requirements and SEC cybersecurity disclosure rules. FDA oversight of medical device customer data handling elevates compliance architecture to a primary selection criterion. Silicon Valley and Seattle clusters anchor platform development, while New York and Chicago financial services firms prioritize hybrid cloud configurations for data residency.
Germany
Industrial mid-market manufacturers and automotive suppliers accelerate replacement cycles ahead of EU AI Act enforcement milestones for automated customer scoring. GDPR adequacy uncertainty and Schrems II litigation exposure push procurement toward certified architectures with documented algorithmic transparency. Bavaria and Baden-Württemberg manufacturing hubs concentrate demand for predictive analytics integration.
India
SME distributors and mid-market enterprises expand procurement under PLI scheme digitization incentives and TRAI-mandated telemarketing consent frameworks. RBI data localization mandates for customer transaction histories accelerate hybrid cloud adoption among banking sector buyers. Mumbai and Bangalore technology corridors concentrate vendor implementation partnerships and localized support infrastructure.
United Kingdom
NHS Digital interoperability mandates and UK GDPR alignment drive public sector migration from perpetual licenses to cloud-native platforms. Professional services firms in London and Southeast England negotiate usage-based contracts tied to active contact records rather than seat licenses. Edinburgh and Manchester financial services clusters prioritize predictive lead scoring capabilities.
Brazil
Pharmaceutical distributors and healthcare providers advance procurement under ANVISA serialization traceability requirements for lot-tracking and adverse-event reporting. Community cloud deployments gain traction among consortia seeking mutualized security audits. São Paulo and Rio de Janeiro industrial corridors concentrate demand for vertical-specific workflow customization.
Global Saas Customer Relationship Management (CRM) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enterprise-grade AI integration separating premium platforms from standardized offerings. The market exhibits tiered consolidation around three strategic clusters: hyperscale cloud-native providers with ecosystem lock-in, legacy enterprise software vendors with database connectivity advantages, and mid-market specialists with rapid deployment capabilities. Dominant competitive moves include vertical-specific compliance certification roadmaps and API-first interoperability investments.
Within the hyperscale tier, Salesforce and Microsoft occupy positions defined by ecosystem breadth and native integration advantages respectively. Oracle exemplifies the legacy database-centric archetype through deep enterprise connectivity. Among mid-market specialists, Zoho and Freshworks represent cost-optimized deployment models targeting SME digitization waves in emerging economies.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Dynamics |
| Oracle |
| SAP |
| HubSpot |
| Zoho |
| Adobe |
| Freshworks |
| International Business Machines |
| Others |
Supply & Pricing Matrix
Hybrid cloud deployment substitution for pure public configurations is simultaneously redistributing vendor engineering capacity toward Germany and India while compressing price premiums for data-residency-certified architectures. This substitution dynamic concentrates supply-side investment in jurisdictions with codified localization mandates, forcing buyers to absorb compliance-layer costs that were previously externalized.
Pricing Analysis
EU AI Act risk classification dictates the pricing tier structure across automated customer scoring modules. Pricing stratifies across certified premium tiers with algorithmic transparency documentation, standard tiers with basic audit trails, and economy tiers lacking high-risk system coverage. Price differentiation hinges on ISO 27001 certification grade and vertical-specific compliance depth for HIPAA-covered entities. Cost compression in the economy tier is intensifying because Indian SME distributors negotiate usage-based contracts tied to active contact records rather than seat licenses. Small business buyers exhibit the highest price sensitivity, while German automotive suppliers prioritize certification premiums over per-seat economics.
Supply Chain Analysis
Implementation lead times for certified deployments have extended four to eight months due to ISO 27001 audit queue delays at accredited bodies. Engineering resources concentrate in the United States, Germany, and India, with localized compliance architectures tethered to jurisdiction-specific certification timelines. Critical workflow automation draws from three dominant messaging infrastructure providers, creating single-point-of-failure exposure. Supply chain risk centers on API dependency concentration where telemarketing consent frameworks and data localization mandates fragment platform interoperability. Distribution runs through hyperscale cloud marketplaces, direct enterprise sales teams, and regional implementation partners serving mid-market distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed compliance services and ongoing certification maintenance represent a service-attach opportunity expanding faster than core platform licensing as regulatory enforcement timelines compress. Recurring revenue from algorithmic transparency documentation and audit-ready architecture support is displacing perpetual license models.
For Market Incumbents: Consolidate around vertical-specific certification roadmaps that preempt EU AI Act enforcement milestones for automated customer scoring. Anchor defensive positioning through deep database connectivity for complex enterprise deployments at incumbent insurers resisting standard API protocols. Prioritize backward integration into edge-AI inference engines that enable real-time sentiment analysis without data residency violations.
For New Entrants and Emerging Players: Differentiate on embedded finance distribution capabilities that capture payment flows previously handled by separate treasury systems. Target Brazil's pharmaceutical distributor segment where ANVISA serialization traceability requirements create first-mover advantage for lot-tracking integration. Pursue community cloud deployments among consortia seeking mutualized security audits as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with pre-certified EU AI Act architectures and established healthcare compliance stacks. Long-term viability over a multi-year window hinges on regulatory roadmap alignment ahead of enforcement milestones. Target acquisition archetypes include mid-market specialists with rapid deployment capabilities in India and vertical-specific workflow engines for FDA-regulated device manufacturers. Watch ISO 27001 certification backlog resolution as the inflection indicator for enterprise sales cycle normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Office 365 connectivity anchors Microsoft Dynamics penetration in German mid-market manufacturing. |
| Acquisition of Specialist Firm | Edge-AI inference capabilities enable real-time sentiment analysis without GDPR data residency violations. |
| Geographic Expansion | PLI scheme incentives accelerate Indian SME distributor procurement under TRAI-mandated consent frameworks. |
| Strategic Partnership | Banking-as-a-Service API alliances capture payment flows previously handled by separate treasury systems. |
| Product Launch | Algorithmic transparency modules address EU AI Act high-risk system documentation requirements ahead of enforcement. |
Research Methodology
Cross-validation between primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists and secondary validation through SEC filings, hyperscaler capex disclosures, and enterprise software vendor financial reports anchors the qualitative findings. Bottom-up and top-down triangulation reconciles deployment model adoption rates with regional regulatory cluster analysis across the analysis window.
Sensitivity analysis across deployment architecture, organization size, vertical industry, and integration complexity dimensions stress-tests volume and value outputs over the projection horizon. CAGRs derive from segmented demand modeling that weights EU AI Act compliance retrofit obligations against India SME digitization incentives. Forecast inputs incorporate ISO 27001 certification pipeline delays and HIPAA audit requirement expansion for FDA-regulated device manufacturers.
Material uncertainties — GDPR adequacy decision reversals, Schrems II litigation outcomes, and central bank data localization mandate expansions — sit outside the modeled envelope. Forecasts reflect assumptions documented in jurisdictional regulatory roadmaps rather than enforcement certainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Thailand CRM Market